
 Gel Column Agglutination Test System Market | 2026-2036
Gel Column Agglutination Test System Market Size, Share, and Industry Trends Forecast 2026-2036
Gel Column Agglutination Test System Market Foresight
CE-marked and FDA-cleared tier certification is bifurcating competitive tiers across the Gel Column Agglutination Test System landscape. Grifols leverages its vertically integrated plasma-derived diagnostics portfolio to sustain European hospital contracts. Bio-Rad Laboratories anchors North American reference laboratory relationships through specialized immunohematology reagent systems. Danaher Corporation competes via operational discipline and diagnostic platform breadth across transfusion medicine workflows.
A gel column agglutination test system employs microtubes containing dextran-acrylamide gel matrices to separate agglutinated from non-agglutinated red blood cells during centrifugation, enabling standardized ABO/Rh typing and antibody detection with objective endpoint interpretation. Automated systems now lead installed base value as blood banks prioritize throughput and error reduction, while semi-automated platforms retain share in mid-volume diagnostic laboratories balancing capital constraints against workflow efficiency. Manual systems occupy declining but persistent niches in resource-limited settings and educational applications where cost minimization dominates procurement criteria.
FDA 510(k) clearance pathways and CE marking under the EU In Vitro Diagnostic Regulation shape product development timelines and commercial launch sequencing for system manufacturers. ISO 15189 accreditation requirements for diagnostic laboratories directly influence instrument validation documentation and quality control module design. Stakeholders must monitor evolving harmonization between FDA digital health guidance and IVDR software classification rules to anticipate compliance costs for next-generation platforms integrating artificial intelligence-assisted pattern recognition.
Market Dynamics
Hospital consolidation across the United States is compressing procurement timelines and favoring integrated diagnostic platforms that bundle gel column testing with broader transfusion medicine workflows. Blood banks now prioritize error-reduction capabilities over standalone instrument specifications.
Growth Catalysts
- Automated Platform Integration:Blood bank laboratories are consolidating onto unified immunohematology workstations that combine gel column processing with sample handling robotics. This reduces manual touchpoints and transfusion error rates.
- FDA 510(k) Pathway Refinement:The FDA's updated guidance on immunohematology device validation is accelerating clearance timelines for manufacturers that submit comprehensive clinical performance data upfront.
- Antibody Detection Volume Surge:Rising complex surgical procedures and oncology transfusion protocols are expanding antibody screening test volumes at tertiary care centers.
Market Restraints
- Acrylamide-Dextran Gel Cost Volatility:Specialized gel matrix raw materials face supply concentration among European chemical suppliers, exposing manufacturers to input price swings.
- CE Marking Transition Burden:The EU In Vitro Diagnostic Regulation's expanded clinical evidence requirements are extending recertification timelines for existing gel column product lines.
- Flow Cytometry Substitution:Advanced flow cytometry platforms for rare antibody identification are capturing high-complexity testing volume from reference laboratories.
Strategic Opportunities
- India Diagnostic Laboratory Expansion:Private hospital chains in Mumbai, Delhi, and Bangalore are investing in automated immunohematology capacity to serve medical tourism and domestic surgical growth.
- Artificial Intelligence Pattern Recognition:Machine learning algorithms for automated gel column endpoint interpretation are converging with cloud-based laboratory information systems.
- ISO 15189 Accreditation Tailwind:Diagnostic laboratories pursuing international quality accreditation are upgrading to gel column platforms with embedded quality control documentation modules.
Industry Challenges
- Immunohematology Specialist Shortage:Blood banks struggle to recruit certified technologists capable of interpreting complex antibody panels and troubleshooting gel column anomalies.
- Legacy System Integration Complexity:Mid-volume laboratories face protracted validation timelines when connecting new gel column instruments to established laboratory information management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gel Column Agglutination Test System Market |
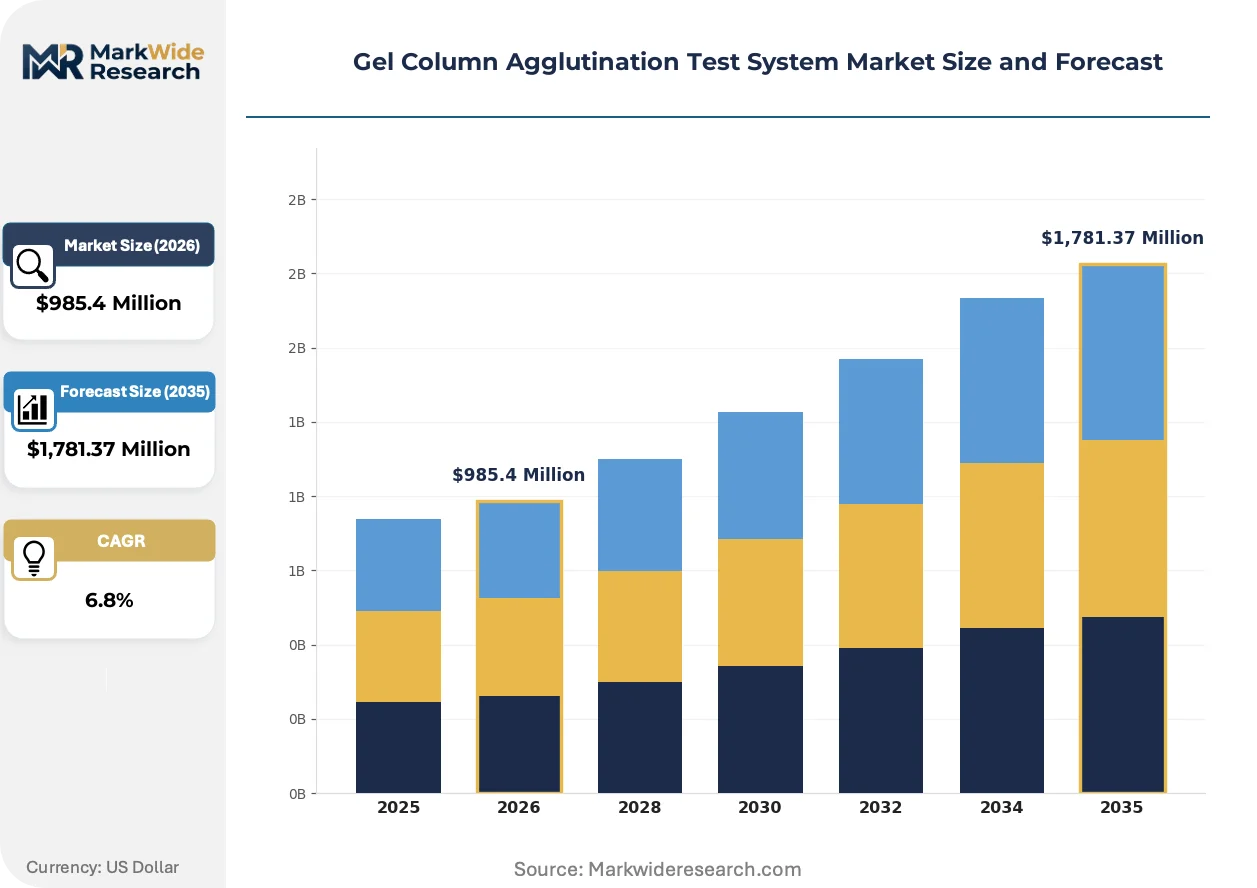
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,781.37 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Semi-Automated Systems, Manual Systems, Hybrid Systems Technology: Immunohematology, Serology, Blood Typing, Antibody Screening, Crossmatching Application: Blood Banks, Diagnostic Laboratories, Transfusion Centers, Research Institutes, Clinical Testing End User: Hospitals, Diagnostic Centers, Blood Donation Agencies, Academic Institutions |
| Companies Covered | Grifols, Tulip Diagnostics, Bio-Rad Laboratories, Danaher Corporation, Immucor, Ortho Clinical Diagnostics, Thermo Fisher Scientific, Diagast, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gel Column Agglutination Test System Market Shifts & Advancements
Digital endpoint capture and algorithmic interpretation are displacing visual gel column reading across high-throughput transfusion medicine operations. These capabilities are reshaping instrument design priorities and service contract structures simultaneously.
Multiplex gel column cartridges capable of simultaneous ABO/Rh typing and antibody screening are decomposing the traditional sequential testing workflow. Regional blood centers in Germany and France are adopting these configurations to compress turnaround times for emergency transfusion protocols. This consolidation is decomposing demand for standalone typing instruments and reshaping manufacturer R&D roadmaps toward integrated assay menus.
The EU In Vitro Diagnostic Regulation's software classification rules are redefining validation requirements for gel column systems with embedded image analysis. Manufacturers must now submit clinical performance studies for algorithm-assisted endpoint determination as part of technical documentation. Systems with AI-assisted reading modules face extended notified body review timelines, favoring early movers that invested in prospective clinical trials.
Hospital procurement committees are consolidating immunohematology spending under centralized laboratory capital budgets rather than blood bank operational accounts. This financial restructuring is elevating total cost-of-ownership analyses over instrument acquisition price in vendor selection. The shift is most pronounced at integrated delivery networks in Texas and Florida, where multi-hospital contracts now span five-year service-inclusive agreements.
Gel Column Agglutination Test System Market Segmentation
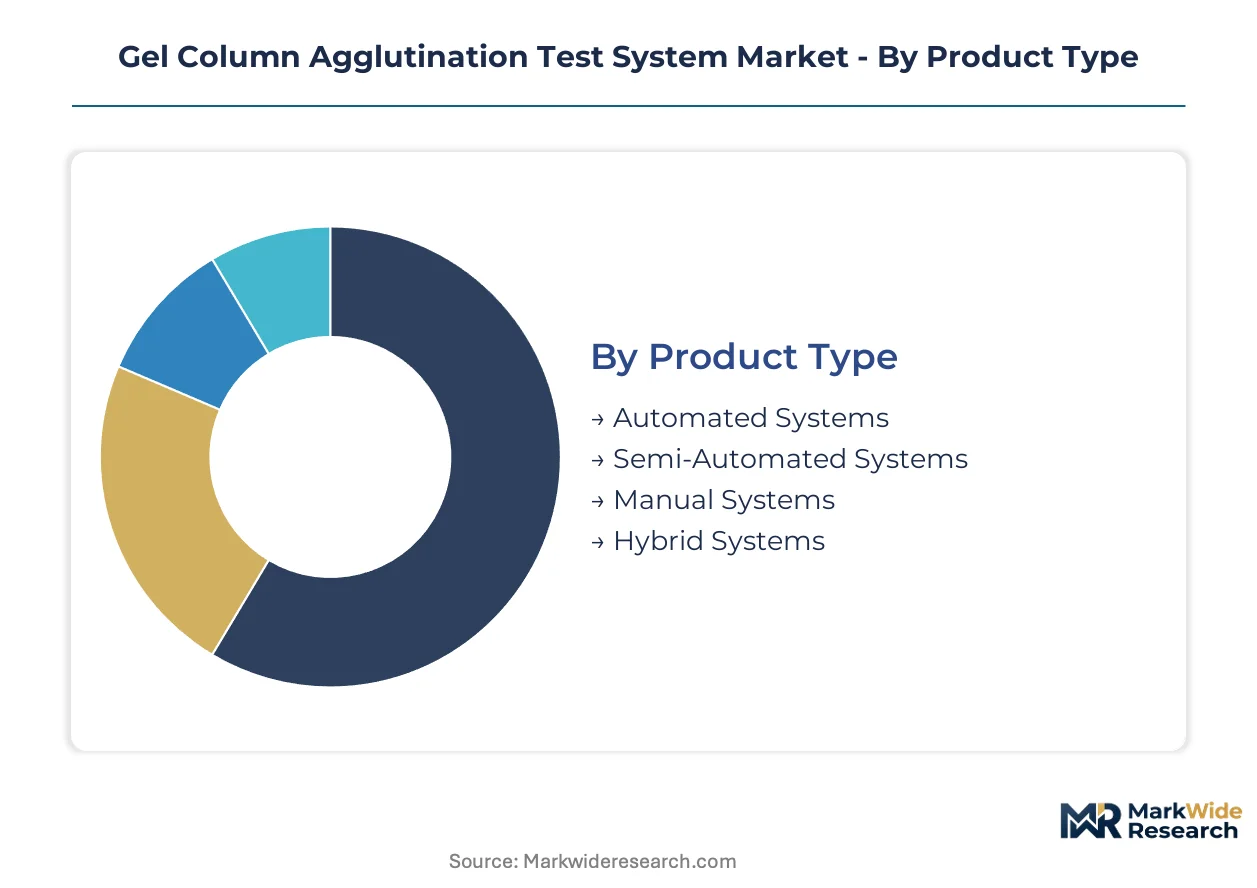
Gel column agglutination test system manufacturers compete across distinct technology tiers and customer workflows. Segmentation reveals where substitution pressures from flow cytometry and molecular diagnostics concentrate, and where instrument-integrated platforms defend incumbent positions.
Product Type:
Flow cytometry substitution pressures automated systems least, while manual platforms face displacement from simplified immunoassay alternatives.
- Automated Systems:Robotic sample handling and centrifugation modules process microtube arrays without technologist intervention. Blood banks in the United States prioritize these configurations to reduce transfusion errors under FDA 510(k) quality system requirements.
- Semi-Automated Systems:Require manual sample loading but automate gel column reading and result documentation. Mid-volume diagnostic laboratories in Texas and Florida deploy these to balance capital constraints against throughput needs during hospital consolidation.
- Manual Systems:Depend entirely on technologist execution of pipetting, centrifugation, and visual endpoint interpretation. Resource-limited settings and educational institutions in India retain procurement interest where cost minimization dominates.
- Hybrid Systems:Combine modular automation with manual override capabilities for complex antibody panels. Regional blood centers in Germany configure these for emergency transfusion flexibility.
Automated systems retain volume leadership; hybrid systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates reference laboratory technologies from routine screening applications, with serology and blood typing commanding premium positioning.
- Immunohematology:Comprehensive ABO/Rh typing, antibody identification, and crossmatching on unified platforms. Tertiary care centers in France and Germany anchor demand for integrated immunohematology workstations under EUDAMED registration requirements.
- Serology:Infectious disease marker detection using gel column separation principles. Blood donation agencies in the United States deploy these for donor screening under FDA biologics guidance.
- Blood Typing:Rapid ABO and Rh phenotype determination for emergency transfusion protocols. Trauma centers in Mumbai and Delhi prioritize throughput speed for medical tourism patients.
- Antibody Screening:Detection of unexpected red cell antibodies in pre-transfusion testing. Oncology transfusion protocols at academic medical centers drive volume expansion.
- Crossmatching:Donor-recipient compatibility verification using gel column agglutination. Hospital blood banks perform these as final safety checks before unit release.
Blood typing commands the highest test frequency; antibody screening is expanding most quickly in oncology settings.
Application:
Customer type concentration shapes procurement patterns, with blood banks and transfusion centers representing integrated demand clusters versus fragmented diagnostic laboratory purchasing.
- Blood Banks:High-volume testing operations requiring standardized ABO/Rh typing and antibody screening. United States hospital consolidation is compressing procurement timelines toward five-year service-inclusive agreements.
- Diagnostic Laboratories:Mid-scale facilities balancing multiple test menus with immunohematology capacity. ISO 15189 accreditation requirements in India and the United States drive quality control module upgrades.
- Transfusion Centers:Specialized facilities managing complex surgical and oncology transfusion protocols. Antibody detection volume surges at these sites as complex procedures expand.
- Research Institutes:Investigational applications in rare antibody characterization and assay development. Funding cycles from the National Institutes of Health shape capital equipment timing.
- Clinical Testing:Point-of-care and near-patient applications for urgent transfusion decisions. Military and trauma settings deploy portable configurations.
Blood banks retain volume leadership; transfusion centers hold the steepest expansion curve.
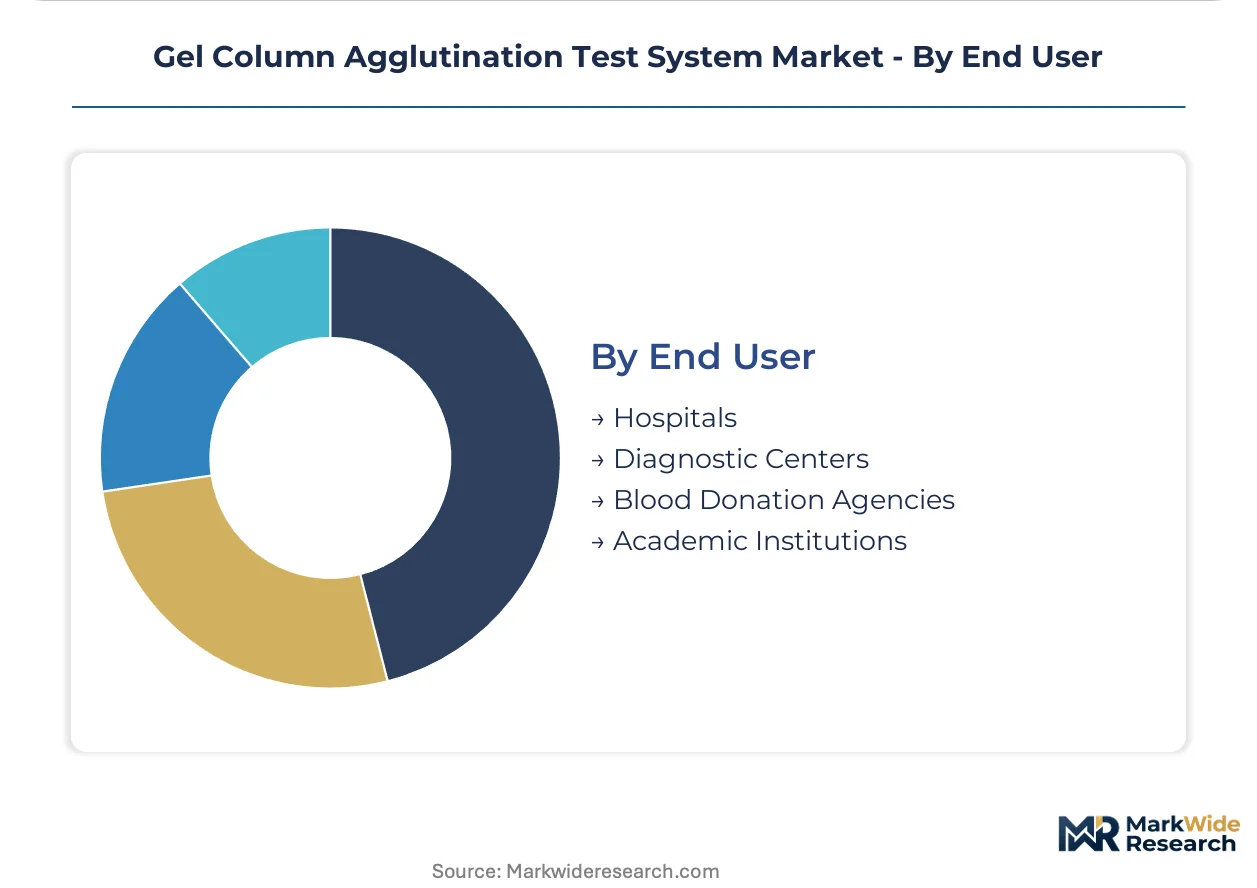
End User:
Supply concentration among European gel matrix producers elevates total cost-of-ownership calculations for hospital procurement committees versus diagnostic center operational budgets.
- Hospitals:Integrated delivery networks in Texas and Florida centralize immunohematology spending under laboratory capital budgets. Five-year service contracts now predominate over instrument acquisition price.
- Diagnostic Centers:Independent facilities serving outpatient surgical and prenatal testing demand. Private chains in Bangalore and Delhi invest in automated capacity for medical tourism growth.
- Blood Donation Agencies:National and regional collection organizations screening donor units for transfusion-transmissible infections. FDA biologics license requirements govern validation protocols.
- Academic Institutions:Teaching hospitals and university laboratories combining patient care with technologist training. Manual systems persist here for educational cost containment.
Hospitals retain volume leadership; diagnostic centers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for gel column agglutination test systems favor established manufacturing bases in Europe and North America over emerging assembly operations. Net importers in South Asia and the Middle East drive aftermarket service revenue for instrument providers.
United States
Hospital consolidation across Texas and Florida compresses procurement timelines toward five-year service-inclusive agreements. FDA 510(k) clearance pathways shape product launch sequencing for manufacturers targeting blood bank automation. The Southeast cluster anchors demand as integrated delivery networks centralize laboratory capital budgets.
Germany
Regional blood centers adopt multiplex gel column cartridges to compress emergency transfusion turnaround times. EUDAMED registration requirements under the EU In Vitro Diagnostic Regulation govern validation protocols for immunohematology workstations. The Rhine-Ruhr industrial corridor concentrates reagent manufacturing and precision centrifugation module assembly.
India
Private hospital chains in Mumbai, Delhi, and Bangalore invest in automated immunohematology capacity for medical tourism and domestic surgical expansion. CDSCO medical device registration timelines influence commercial launch planning for foreign manufacturers. ISO 15189 accreditation requirements accelerate quality control module upgrades across diagnostic laboratory networks.
France
Tertiary care centers anchor demand for integrated immunohematology platforms under ANSM oversight of transfusion medicine safety standards. The EU In Vitro Diagnostic Regulation's expanded clinical evidence requirements extend recertification timelines for existing product lines. The Paris-Saclay cluster concentrates research institute procurement for rare antibody characterization applications.
Japan
Aging demographics expand oncology transfusion protocols and antibody screening volumes at academic medical centers. PMDA consultation pathways for in vitro diagnostics shape algorithm-assisted endpoint determination submissions. The Kansai region around Osaka maintains precision manufacturing capabilities for gel matrix raw material processing.
Gel Column Agglutination Test System Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification depth and geographic coverage breadth. The vendor base consolidates around three tiers: multinational conglomerates with diagnostic platform breadth, mid-cap regional specialists with reagent-chemistry expertise, and niche automation providers focused on blood bank robotics. Archetypes include integrated life science conglomerates, immunohematology pure-plays, and diversified in vitro diagnostic platforms. Dominant competitive moves span strategic partnerships for gel matrix raw material security and portfolio diversification into adjacent transfusion medicine workflows.
Among the integrated conglomerates, Danaher Corporation and Thermo Fisher Scientific exemplify scale-driven operational discipline across diagnostic platform breadth. Grifols and Bio-Rad Laboratories occupy positions within the immunohematology specialist tier, representing reagent-chemistry depth and reference laboratory anchoring respectively. These four names illustrate how competitive positioning stratifies between diversified cash flow stability and focused application expertise.
| Leading Market Players |
|---|
| Grifols |
| Tulip Diagnostics |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Immucor |
| Ortho Clinical Diagnostics |
| Thermo Fisher Scientific |
| Diagast |
| QIAGEN |
| Others |
Supply & Pricing Matrix
Flow cytometry substitution for rare antibody identification is simultaneously reshaping supply geography toward specialized reagent hubs and compressing pricing economics for mid-tier gel column platforms. European gel matrix producers now face margin pressure as blood banks consolidate procurement around automated systems with embedded quality control documentation.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels in the gel column agglutination test system market. Price differentiation hinges on FDA 510(k) clearance tier and five-year service bundling scope, with integrated delivery networks in Texas and Florida showing lowest sensitivity due to centralized capital budgeting. Cost compression in semi-automated tiers is intensifying because mid-volume laboratories delay upgrades during legacy system integration. Academic institutions and resource-limited settings in India represent the most price-sensitive buyer segment, prioritizing manual system acquisition cost over total cost-of-ownership calculations.
Supply Chain Analysis
Just-in-time inventory strategies dominate gel column cartridge replenishment for high-throughput blood banks, while regional stockpiling persists for emergency transfusion protocols in Germany and France. Geographic supply concentration centers on Germany, France, and Japan for precision centrifugation modules and gel matrix raw material processing. Raw material dependencies include dextran-acrylamide gel matrices, specialized microtube polymers, and optical-grade plastics for endpoint detection. Single-source vulnerability from European chemical suppliers for gel matrix components elevates supply chain risk. Distribution runs through diagnostic platform distributors with immunohematology specialization and direct hospital system contracts for integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from five-year maintenance contracts and reagent supply agreements is expanding faster than hardware sales as blood banks prioritize uptime guarantees over capital expenditure minimization.
For Market Incumbents: Shield installed base positions by securing backward integration into dextran-acrylamide gel matrix supply and accelerating FDA 510(k) submissions for AI-assisted endpoint determination modules. Flow cytometry substitution for complex antibody panels threatens reference laboratory revenue streams. Vertical integration into gel matrix production represents the critical defensive lever against European supplier concentration.
For New Entrants and Emerging Players: Anchor in private hospital chains across Mumbai, Delhi, and Bangalore where medical tourism growth outpaces established vendor service capacity. Automated immunohematology workstations for mid-volume diagnostic laboratories represent the most penetrable white space. A software-first go-to-market angle emphasizing cloud-based laboratory information system integration bypasses incumbent hardware lock-in.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors immunohematology pure-plays with reagent-chemistry depth over diversified diagnostic conglomerates. Long-term viability rests on regulatory certification moats and recurring revenue attachment rates. Acquisition targets should demonstrate CE marking under IVDR and FDA 510(k) clearance momentum. The signal to watch is hospital procurement committee shift from instrument acquisition price toward total cost-of-ownership metrics crossing threshold adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercial launch sequencing for manufacturers targeting United States blood bank automation under refined immunohematology device guidance. |
| CE Marking Under IVDR | Extends recertification timelines for existing gel column product lines while elevating clinical evidence requirements for algorithm-assisted systems. |
| Hospital System Partnership | Secures five-year service-inclusive agreements as integrated delivery networks in Texas and Florida centralize laboratory capital budgets. |
| Software Companion Development | Enables machine learning algorithms for automated gel column endpoint interpretation converging with cloud-based laboratory information systems. |
| Reimbursement Strategy | Aligns quality control module design with ISO 15189 accreditation requirements driving diagnostic laboratory upgrade cycles. |
Research Methodology
The analysis maps automated, semi-automated, manual, and hybrid system configurations, each validated through blood bank laboratory directors, diagnostic center procurement managers, immunohematology technologists, and reagent manufacturing executives. Primary interviews combined with secondary validation from FDA 510(k) filings, EUDAMED registration databases, CDSCO medical device approvals, and hospital procurement contract records. Bottom-up instrument shipment modeling and top-down transfusion medicine expenditure analysis provided triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include automation tier, technology application, end-user category, and geographic regulatory cluster. CAGRs derived from weighted average growth rates across segment-specific demand drivers. Industry-specific forecast inputs encompass antibody screening volume expansion at oncology transfusion centers and hospital consolidation patterns in United States integrated delivery networks.
Decision-makers should treat outputs as directional under assumptions of stable FDA 510(k) clearance timelines and continued European gel matrix supply availability; material deviation would warrant model refresh. Revision becomes warranted when CE marking transition burden under IVDR or acrylamide-dextran gel cost volatility crosses thresholds affecting manufacturer pricing power.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Automated Colony Picking Systems Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Laboratory Filtration Devices Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Global Bovine Serum Albumin Market
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Plant Genotyping Equipment Market