
 Edging Tool Market | 2026-2036
Edging Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Edging Tool Market Foresight
Commercial landscaping is broadening its share of the edging tool demand mix as municipalities and golf course operators replace aging fleets. Stanley Black & Decker leverages its battery platform breadth to serve both homeowner and professional channels. Robert Bosch GmbH anchors its position in European markets through precision motor engineering. Husqvarna Group competes across gas-to-battery transition segments with professional-grade durability credentials.
An edging tool is a landscape maintenance implement designed to cut clean boundaries between turf and adjacent surfaces such as pavement, flower beds, or hardscaping, typically employing rotating blades, spooled line, or manual cutting edges with blade depths ranging from two to four inches. Electric edgers are gaining structural share as lithium-ion power density improves and runtime extends to match gas-equivalent performance. Gas-powered edgers retain dominance in heavy-duty commercial applications where continuous operation and raw torque remain critical. Manual edgers occupy a stable niche among residential homeowners seeking low-cost, zero-maintenance solutions for small properties.
EPA emission standards for small spark-ignition engines and California Air Resources Board (CARB) regulations are accelerating product redesign cycles and narrowing the compliant engine supplier base. ISO 5395 safety standards for garden equipment shape blade guarding and operator protection requirements across export markets. Stakeholders must monitor battery supply chain concentration and evolving cordless platform interoperability as electrification capital requirements reshape competitive economics.
Market Dynamics
Battery-electric motor technology is automating the displacement of two-stroke gasoline engines as EPA and CARB emissions frameworks tighten compliance windows and reshape product development roadmaps across the edging tool sector.
Growth Catalysts
- CARB Small Off-Road Engine Standards:California's phased emission reductions are forcing gasoline engine redesigns and accelerating electric platform investment from professional equipment manufacturers.
- Golf Course Fleet Modernization:Municipal and private course operators across the United States, Germany, and China are replacing aging gas-powered maintenance equipment with battery-electric alternatives.
- Lithium-Ion Power Density Gains:Cell chemistry improvements are extending runtime to match gas-equivalent performance without the weight penalties that previously constrained cordless adoption.
Market Restraints
- Compliant Engine Supplier Concentration:EPA Tier 4 and CARB certification requirements have narrowed the small spark-ignition engine supplier base to a handful of specialized manufacturers.
- Raw Material Cost Volatility:Lithium carbonate and cobalt price swings are compressing battery pack margins and complicating long-term equipment pricing strategies.
- Continuous Operation Limitation:Battery thermal management constraints prevent sustained high-torque operation in extreme commercial landscaping conditions where gas engines retain advantage.
Strategic Opportunities
- Platform Interoperability Standards:Cross-manufacturer battery compatibility protocols are creating service ecosystem opportunities for third-party maintenance providers and rental fleets.
- Municipal Electrification Mandates:City-level zero-emission equipment procurement policies in Germany and the Netherlands are opening dedicated bidding channels for battery-electric edging systems.
- Robotics Convergence:Autonomous navigation modules and precision GPS mapping are integrating with electric edging platforms to enable unattended perimeter maintenance in large commercial properties.
Industry Challenges
- Technician Skill Gap:Field service networks lack sufficient training in high-voltage battery diagnostics and power electronics repair, extending equipment downtime for commercial operators.
- ISO 5395 Certification Timelines:Blade guarding and operator protection testing protocols are creating six-to-twelve month product launch delays for redesigned electric platforms.
- Legacy Fleet Integration:Mixed-voltage battery systems and incompatible charging infrastructure are complicating fleet standardization decisions for multi-site landscaping contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edging Tool Market |
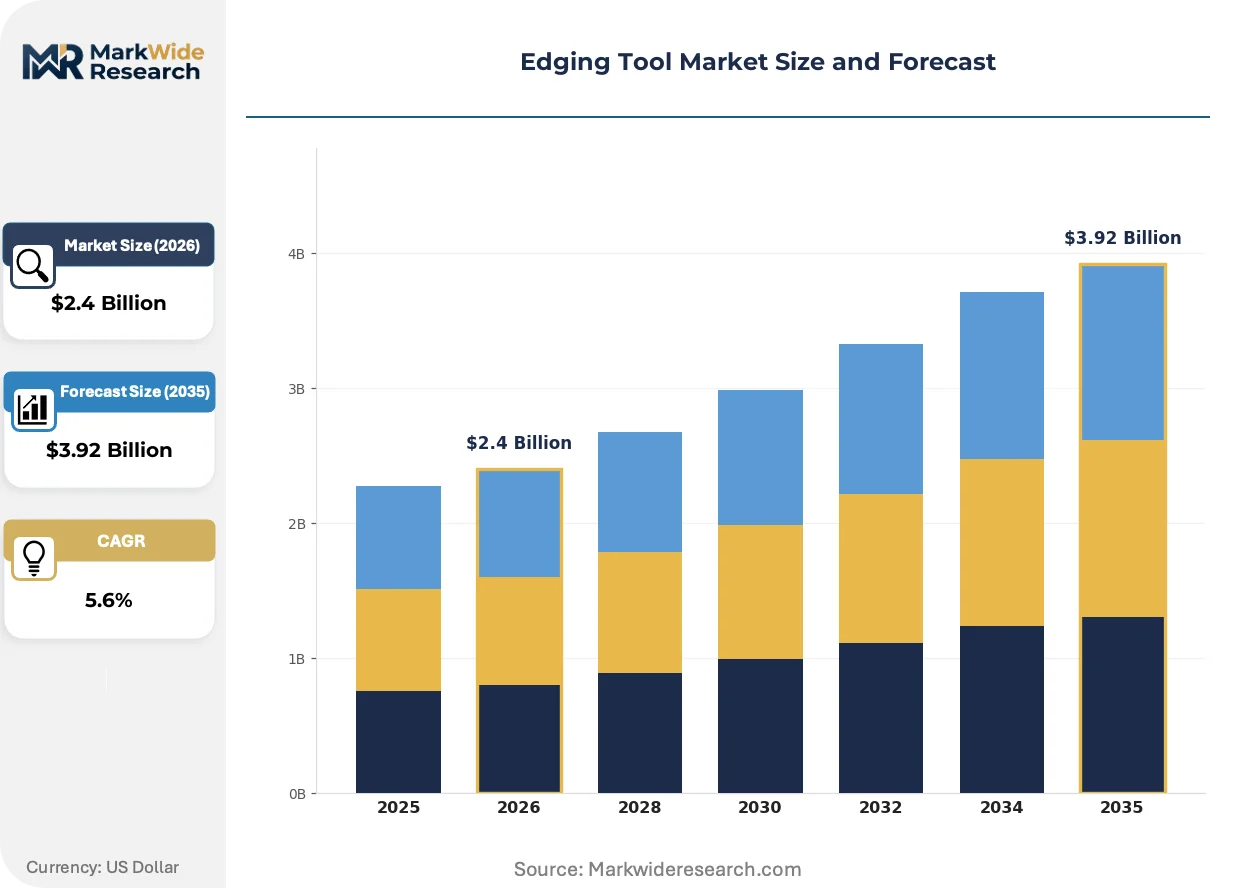
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Edgers, Electric Edgers, Gas-Powered Edgers, Landscape Edgers Application: Residential Landscaping, Commercial Landscaping, Golf Courses, Parks End User: Homeowners, Landscapers, Golf Course Managers, Municipalities Distribution Channel: Online Retail, Home Improvement Stores, Specialty Tool Shops, Distributors |
| Companies Covered | Stanley Black & Decker, Robert Bosch GmbH, Makita Corporation, Husqvarna Group, Fiskars Group, Techtronic Industries, Stihl, Echo Incorporated, Greenworks Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edging Tool Market Shifts & Advancements
Active product development is concentrating on electrification architecture, autonomous operation capabilities, and service model restructuring as manufacturers respond to tightening emissions compliance and shifting buyer expectations.
Brushless DC motor controllers with integrated battery management systems are automating torque optimization across variable grass density and soil conditions. Commercial landscaping fleets in the United States are adopting these platforms fastest, driven by municipal procurement mandates and total cost of ownership calculations. The technology is automating the compression of operator skill requirements while standardizing cut quality across less experienced crews.
EPA emission standards for small spark-ignition engines are narrowing the compliant powertrain supplier base and accelerating product redesign cycles. Equipment manufacturers are responding by accelerating battery platform development and phasing out gasoline-dependent product lines ahead of regulatory deadlines. Professional-grade gas edgers face the steepest compliance cost escalation, shifting investment toward electric motor engineering.
Equipment-as-a-service contracting is replacing outright purchase for municipal and large commercial fleet operators. Third-party fleet management providers are capturing maintenance and upgrade responsibilities, unbundling capital expenditure from operational budgets. This pattern is most visible in Germany and the Netherlands where public procurement regulations favor operational leasing structures over asset ownership.
Edging Tool Market Segmentation
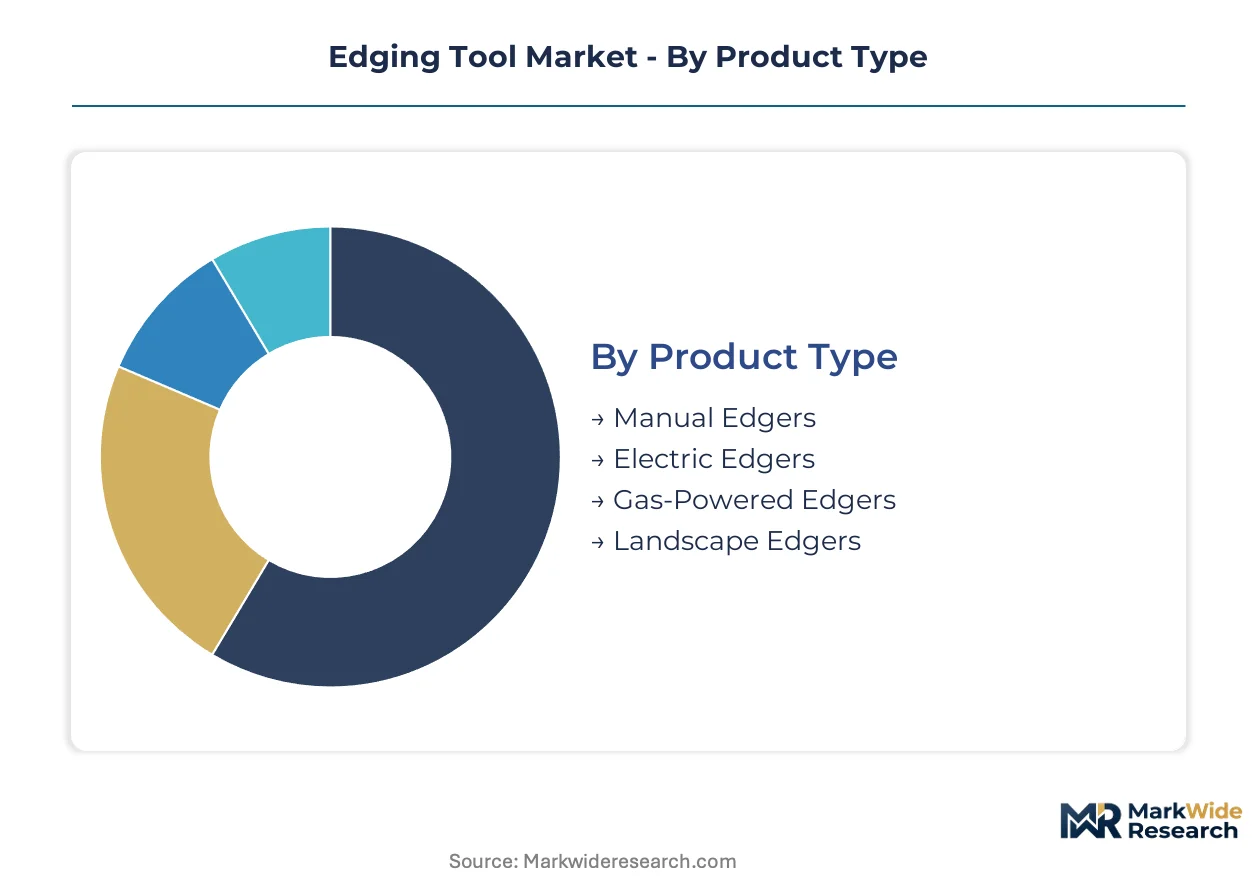
Segmentation in the edging tool market reveals how electrification pressure, professionalization of groundskeeping, and channel consolidation are reshaping procurement patterns. Distinct product architectures, end-use requirements, and buyer sophistication levels create sharply differentiated competitive arenas.
Product Type:
Customization spans from hand-tool simplicity to precision-engineered power systems, with standardization concentrated in mid-market electric platforms.
- Manual Edgers:Hand-operated cutting implements with steel or carbon blades, requiring physical force to sever turf edges. Demand concentrates among homeowners in Germany and the United States seeking zero-maintenance solutions for small residential properties, constrained by labor intensity limiting commercial adoption.
- Electric Edgers:Corded or battery-driven systems employing brushless DC motors with integrated battery management. Municipalities across the Netherlands and California are standardizing procurement around these platforms, driven by zero-emission mandates and total cost of ownership advantages over gasoline equivalents.
- Gas-Powered Edgers:Two-stroke or four-stroke internal combustion engines delivering sustained high torque for continuous commercial operation. Heavy-duty landscaping contractors in Texas and Florida retain preference where runtime demands exceed current battery thermal limits.
- Landscape Edgers:Specialized perimeter maintenance equipment with adjustable blade depths and ergonomic handling systems. Golf course operators in China and the United States specify these for precision turf boundary management alongside fairway maintenance protocols.
Leading the category by volume: Electric Edgers. Growing fastest: Landscape Edgers.
Application:
Cost tier separation distinguishes occasional-use residential installations from capital-intensive commercial fleet deployments.
- Residential Landscaping:Individual property maintenance encompassing lawn borders, driveway edges, and garden bed perimeters. Homeowners in suburban United States markets prioritize storage efficiency and noise reduction, with battery platforms displacing corded electric systems.
- Commercial Landscaping:Professional grounds maintenance services operating across multiple client sites with standardized equipment fleets. Contractors in Germany face municipal procurement rules favoring leased electric equipment over owned gasoline assets.
- Golf Courses:Precision turf management requiring consistent cut quality across extensive perimeter networks. Private and municipal course operators in China are modernizing maintenance equipment as part of facility upgrade investments.
- Parks:Public green space maintenance encompassing varied terrain and high-frequency usage patterns. Municipal park departments in the Netherlands operate under city-level electrification targets affecting equipment replacement cycles.
Highest equipment spend per site: Golf Courses. Expanding most quickly: Commercial Landscaping.
End User:
Customer type determines specification intensity, with professional buyers demanding durability certifications absent from consumer segments.
- Homeowners:Individual property owners performing seasonal or occasional edging tasks without commercial performance requirements. Battery interoperability with existing lawn tool platforms influences purchase decisions in United States retail channels.
- Landscapers:Professional maintenance contractors operating equipment across multiple properties with intensive daily usage. Fleet standardization challenges in California stem from mixed-voltage battery systems complicating multi-site operations.
- Golf Course Managers:Specialized turf professionals requiring precision cutting consistency across tournament-grade playing surfaces. Chinese course developments are importing European equipment standards alongside facility design expertise.
- Municipalities:Government entities managing public grounds with procurement governed by environmental compliance and operational leasing frameworks. German public procurement regulations structurally favor equipment-as-a-service contracting over capital purchase.
Dominant procurement volume: Landscapers. Steepest specification escalation: Municipalities.
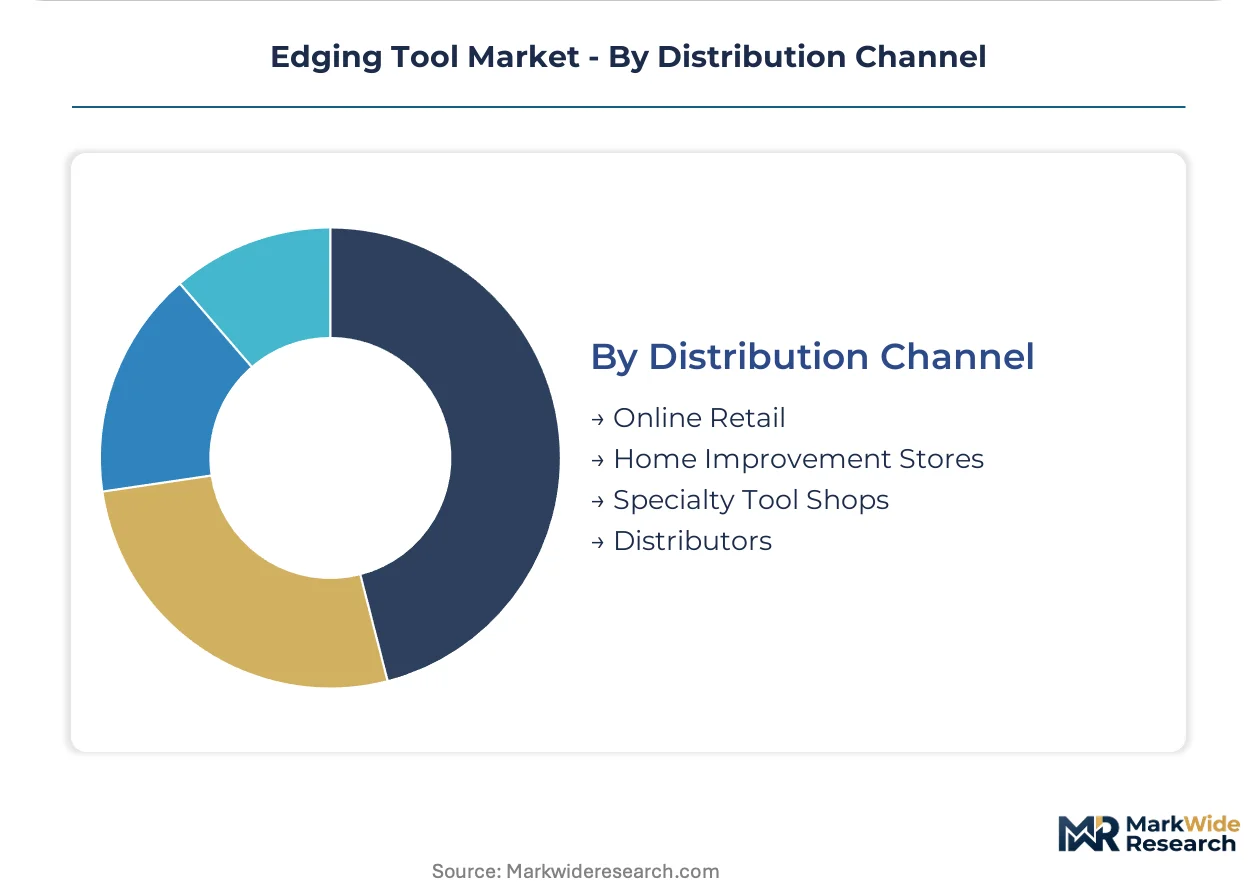
Distribution Channel:
Supply concentration varies from fragmented specialty retail to consolidated e-commerce platforms with distinct service attachment capabilities.
- Online Retail:Digital commerce platforms offering direct-to-consumer fulfillment with limited technical consultation. Battery platform compatibility information and user review systems drive homeowner purchase decisions in United States markets.
- Home Improvement Stores:Big-box retailers combining self-service selection with in-store demonstration and seasonal promotional pricing. Professional contractors in Texas and Florida source replacement units through established commercial account relationships.
- Specialty Tool Shops:Independent dealers providing technical expertise, repair services, and brand-specific parts availability. German landscaping professionals rely on these channels for ISO 5395 compliance documentation and warranty administration.
- Distributors:Wholesale intermediaries serving fleet operators with volume pricing, financing arrangements, and maintenance contract bundling. Municipal procurement in the Netherlands channels through authorized distributors meeting public sector vendor qualification requirements.
Capturing greatest volume share: Home Improvement Stores. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta special economic zone concentrates battery cell manufacturing capacity that feeds electric edging tool production networks across Guangdong province.
United States
Municipal fleet electrification mandates in California and procurement preference programs in Texas drive commercial landscaping equipment turnover. EPA Tier 4 emission standards for small spark-ignition engines compress compliant engine availability and accelerate battery platform adoption. Golf course operators in Florida and Arizona are modernizing perimeter maintenance equipment as part of facility upgrade cycles.
Germany
Public procurement regulations favoring operational leasing over capital purchase reshape municipal equipment acquisition patterns. The EU Green Deal and national climate targets pressure landscaping contractors toward zero-emission fleet composition. Industrial clusters in North Rhine-Westphalia host precision motor engineering facilities serving European professional equipment markets.
China
Golf course development in Hainan and facility upgrades across tier-one cities generate demand for precision turf maintenance equipment. National dual carbon goals and provincial emission control policies restrict gasoline-powered equipment in urban maintenance operations. Manufacturing concentration in Zhejiang province supplies lithium-ion battery packs and brushless motor systems for domestic and export markets.
Netherlands
City-level zero-emission equipment procurement policies in Amsterdam and Rotterdam create dedicated bidding channels for battery-electric systems. The national climate agreement mandates operational emissions reductions across municipal service fleets. Landscaping contractors in the Randstad region standardize on leased electric equipment to meet public sector vendor qualification requirements.
Japan
Precision manufacturing standards and compact equipment preferences shape professional buyer specifications in urban maintenance markets. METI energy efficiency guidelines and local air quality regulations accelerate displacement of two-stroke gasoline engines. Industrial concentration in the Nagoya region supplies precision motor controllers and battery management systems for premium equipment tiers.
Edging Tool Market Competitive Landscape
Top-tier vendors anchor the premium professional segment, while mid-tier specialists and private-label assemblers occupy volume positions in consumer and light-commercial channels. The market structure reflects tiered differentiation across battery platform breadth, motor engineering precision, and professional-grade durability certification. Equipment manufacturers cluster around three strategic archetypes: diversified power tool conglomerates with cross-platform battery ecosystems, specialized outdoor power equipment houses with professional service networks, and emerging electric-native brands with direct-to-consumer distribution. Competitive dynamics center on M&A activity targeting battery technology capabilities and strategic partnerships enabling fleet management service bundling.
Among diversified tool manufacturers, Stanley Black & Decker and Robert Bosch GmbH exemplify archetypes leveraging cross-platform battery interoperability to capture both homeowner and professional channels. Husqvarna Group occupies a position spanning gas-to-battery transition segments with established durability credentials in commercial landscaping. These three anchors represent distinct strategic postures: ecosystem breadth, precision engineering heritage, and professional outdoor equipment specialization respectively.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Makita Corporation |
| Husqvarna Group |
| Fiskars Group |
| Techtronic Industries |
| Stihl |
| Echo Incorporated |
| Greenworks Tools |
| Others |
Supply & Pricing Matrix
Municipal fleet operators in California and the Netherlands anchor procurement volume and impose standardized pricing frameworks through equipment-as-a-service contracting. Their preference for leased electric platforms over capital purchase compresses upfront pricing power while extending revenue capture across multi-year service agreements.
Pricing Analysis
Short lead-time premiums apply to battery pack procurement as lithium carbonate availability fluctuates, while spot inventory discounts emerge for legacy gasoline engine components facing demand contraction. Three-tier pricing structure across premium, standard, and economy levels separates ISO 5395-certified professional units from consumer-grade alternatives. Pricing pressure stems from raw material cost volatility in battery supply chains. Homeowners exhibit highest price sensitivity, whereas golf course operators prioritize performance consistency over unit cost.
Supply Chain Analysis
ISO 5395 certification requirements gate supplier participation, narrowing component sourcing to qualified manufacturers in China, South Korea, and Japan. Brushless DC motor controllers and lithium-ion battery cells draw from concentrated Asian manufacturing hubs. Single-source vulnerability persists for specialized battery management system semiconductors. Distribution runs through authorized dealer networks for professional channels and big-box retail for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The edging tool sector occupies a technology-transition phase as battery-electric platforms displace two-stroke gasoline engines under tightening EPA and CARB frameworks.
For Market Incumbents: Deploy cross-platform battery interoperability as a lock-in mechanism against emerging electric-native competitors. Accelerate backward integration into battery pack assembly to secure supply continuity amid lithium raw material volatility. Strengthen dealer service networks to address the technician skill gap in high-voltage diagnostics that currently extends commercial fleet downtime. For New Entrants and Emerging Players: CARB Small Off-Road Engine Standards in California open a window for pure-electric equipment specialists to capture municipal procurement channels bypassing incumbent gasoline legacy. Target Netherlands municipal electrification mandates through equipment-as-a-service partnerships with established fleet management providers. Pursue direct-to-consumer online retail for residential battery platforms emphasizing noise reduction and storage efficiency. For Investors and Strategic Acquirers: The window for entry favors battery technology specialists with captive motor controller engineering capabilities. Long-term viability hinges on platform standardization across professional landscaping fleets rather than fragmented proprietary ecosystems. Watch for municipal procurement rule changes mandating cross-manufacturer battery compatibility as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Cross-manufacturer interoperability reduces fleet operator switching costs and accelerates electric adoption in California municipal contracts. |
| Backward Integration into Cells | In-house lithium-ion production insulates margins from carbonate price swings affecting Zhejiang and Guangdong supply bases. |
| Autonomous Navigation Partnership | Precision GPS integration enables unattended perimeter maintenance for golf courses in Arizona and Florida seeking labor cost reduction. |
| Equipment-as-a-Service Launch | Operational leasing structures align with German public procurement regulations favoring service contracts over capital expenditure. |
| Technician Certification Program | High-voltage repair training addresses the skill gap extending downtime for commercial landscaping fleets in Texas. |
Research Methodology
Trade association filings, customs import records, and EPA certification databases formed the secondary backbone, supplemented by primary interviews with commercial landscaping fleet managers, municipal procurement officers, golf course maintenance directors, and power equipment dealer principals. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Historical trendline analysis of gasoline-to-electric transition patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, application intensity, end-user professionalization level, and regional regulatory stringency. CAGRs derived from fitted growth curves applied to equipment replacement cycle data and fleet electrification mandate timelines.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions regarding CARB phase-in schedules and lithium supply expansion rates. A model refresh is warranted upon material change in municipal procurement electrification targets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cordless Multi Rotary Tools Market
Tools
Europe Woodworking Power Tools Market
Tools
Machine Bench Vices Market
Tools
Woodworking Sanders Market
Tools
Spray Painting Machine Market
Tools
Gear Cutting Machines Market
Tools
Sand Control Tools Market
Tools
Floor Pads Market
Tools
Portable Grinders Market
Tools
Global Metal Forming Machine Tools Market
Tools
Level Floats Market
Tools
End Milling Machine Market
Tools
Industrial Ladder Market
Tools
Floor Polishing Machine Market
Tools
Mallets and Sledgehammers Market
Tools
Stand Tile Saw Market