
 Rigid Food Packaging Market | 2026-2036
Rigid Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Food Packaging Market Outlook
Subscription-based packaging redesign services are recalibrating how converters monetize long-term customer relationships. Amcor leverages global manufacturing scale to anchor multi-year supply contracts with multinational food brands. Berry Global specializes in multi-layer plastic structures that sustain barrier performance under extended shelf-life requirements. DS Smith competes through fiber-based innovation, positioning molded pulp trays as alternatives to expanded polystyrene in chilled food logistics.
Rigid food packaging comprises inflexible containers manufactured from plastic resins, glass, metal, or wood substrates, engineered to protect contents from mechanical damage, moisture ingress, and oxidative degradation through specified barrier coefficients and closure integrity. These structures serve primary functions of product preservation, portion control, and brand communication in processed food supply chains. Plastic bottles and jars dominate volume throughput in beverage and condiment categories where clarity and lightweighting reduce logistics cost. Metal cans retain structural advantages in retort applications and ambient shelf-stable segments where oxygen exclusion determines shelf life. Glass jars command premium positioning in specialty sauces and organic preserves, though breakage rates and unit weight constrain expansion in e-commerce channels.
The FDA governs food contact substance notifications and migration limits for plastic additives in US markets, while the EPA regulates volatile organic compound emissions from coating and printing operations at converter facilities. EFSA and REACH collectively determine substance authorization thresholds for European rigid packaging imports, creating compliance cost differentials between regional supply bases. Stakeholders must monitor evolving extended producer responsibility frameworks and deposit-return system expansions that will reshape collection infrastructure and recycled content mandates.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing material choice sets across European converter networks, forcing substrate substitutions and capital redeployment toward compliant barrier technologies.
Growth Catalysts
- Sealed Tray Formats:Urban ready-to-eat meal adoption is pulling order volumes for high-barrier sealed trays in chilled food logistics, particularly in German dairy and meat processing corridors.
- REACH Authorization Thresholds:EFSA and REACH substance mandates are accelerating compliant material development cycles among European compounders serving food contact applications.
- Recycled Content Mandates:Extended producer responsibility frameworks across multiple jurisdictions are creating pull-through demand for post-consumer resin integration in rigid containers.
Market Restraints
- Resin Price Volatility:Polypropylene and polyethylene input costs fluctuate with crude oil derivatives, compressing converter margins on long-term supply contracts.
- Barrier Performance Trade-offs:Mono-material structures required by recyclability mandates sacrifice oxygen and moisture barrier coefficients versus multi-layer laminates.
- Retort Metal Can Lock-in:Ambient shelf-stable segments remain structurally dependent on tinplate and aluminum given thermal processing requirements that polymer alternatives cannot yet match.
Strategic Opportunities
- Deposit-Return System Expansion:Scandinavian and German bottle-to-bottle collection infrastructure creates closed-loop feedstock access for food-grade rPET production.
- Molded Pulp Tray Substitution:Fiber-based chilled food logistics formats are capturing share from expanded polystyrene in premium organic and specialty produce channels.
- Digital Print Integration:Direct-to-shape inkjet systems enable short-run customization for regional brand variants without plate changeover costs.
Industry Challenges
- Migration Testing Backlogs:FDA food contact substance notification queues and EFSA scientific opinion timelines delay new additive commercialization by 18-36 months.
- Recyclability Certification Complexity:APR design-for-recycling guidelines and OPRL labeling requirements demand specialized technical staffing that mid-scale converters struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Food Packaging Market |
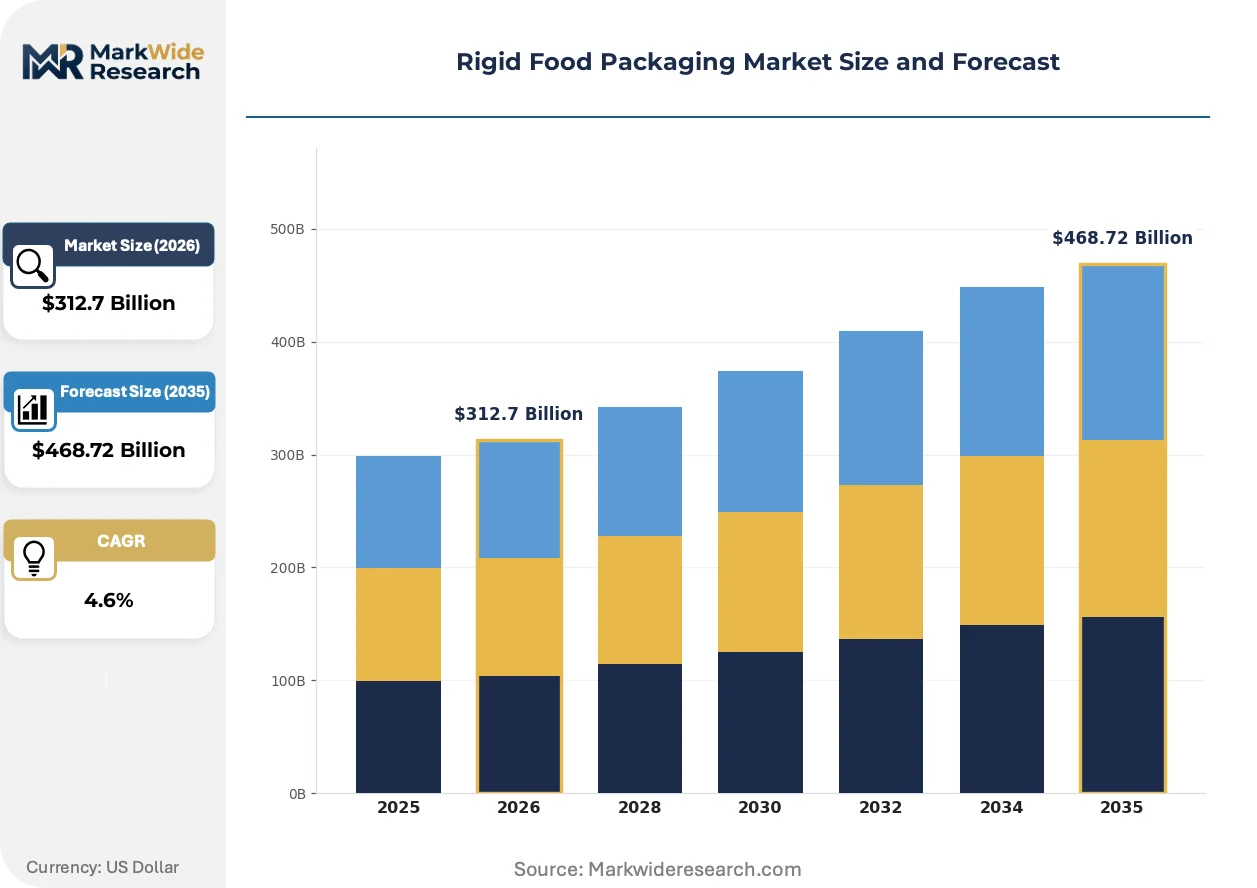
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $468.72 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Metal, Wood Product Form: Bottles, Jars, Tubs, Trays End User: Food Processing, Retail, Foodservice, E-commerce Distribution Channel: Direct Sales, Supermarkets, Online Retail, Convenience Stores |
| Companies Covered | Sonoco, DS Smith, Amcor, Silgan Holdings, Ball Corporation, Berry Global, WestRock, Crown Holdings, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Food Packaging Market Strategic Shifts
Active and intelligent packaging functionalities are migrating from pharmaceutical applications into food preservation systems, reshaping how shelf-life extension and supply chain visibility converge in rigid formats.
High-barrier mono-material polypropylene structures are expanding into retort-ready applications previously reserved for multi-layer laminates or metal substrates. Protein and ready-meal processors in Benelux and Nordic markets are piloting these formats for microwaveable tray applications. The shift is expanding into supply contracts that previously specified aluminum or metallized film barriers, compressing material complexity in sorting streams.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon displacement in foam insulation for cold chain distribution. Converter R&D programs are pivoting toward carbon dioxide and hydrocarbon blowing agents for expanded polystyrene replacements. Chilled dairy logistics across Germany, France, and Poland are experiencing the most acute compliance pressure given temperature excursion sensitivity.
Direct-store-delivery networks are consolidating procurement authority at regional distributor level, compressing converter sales cycles and fragmenting order specifications. Small-format convenience retailers are displacing traditional wholesale club purchasing for ambient and chilled stock-keeping units. This concentration is most visible in US Southeast and Midwest metropolitan corridors where distributor mergers have reduced buyer count by 30-40% since 2020.
Rigid Food Packaging Market Segmentation
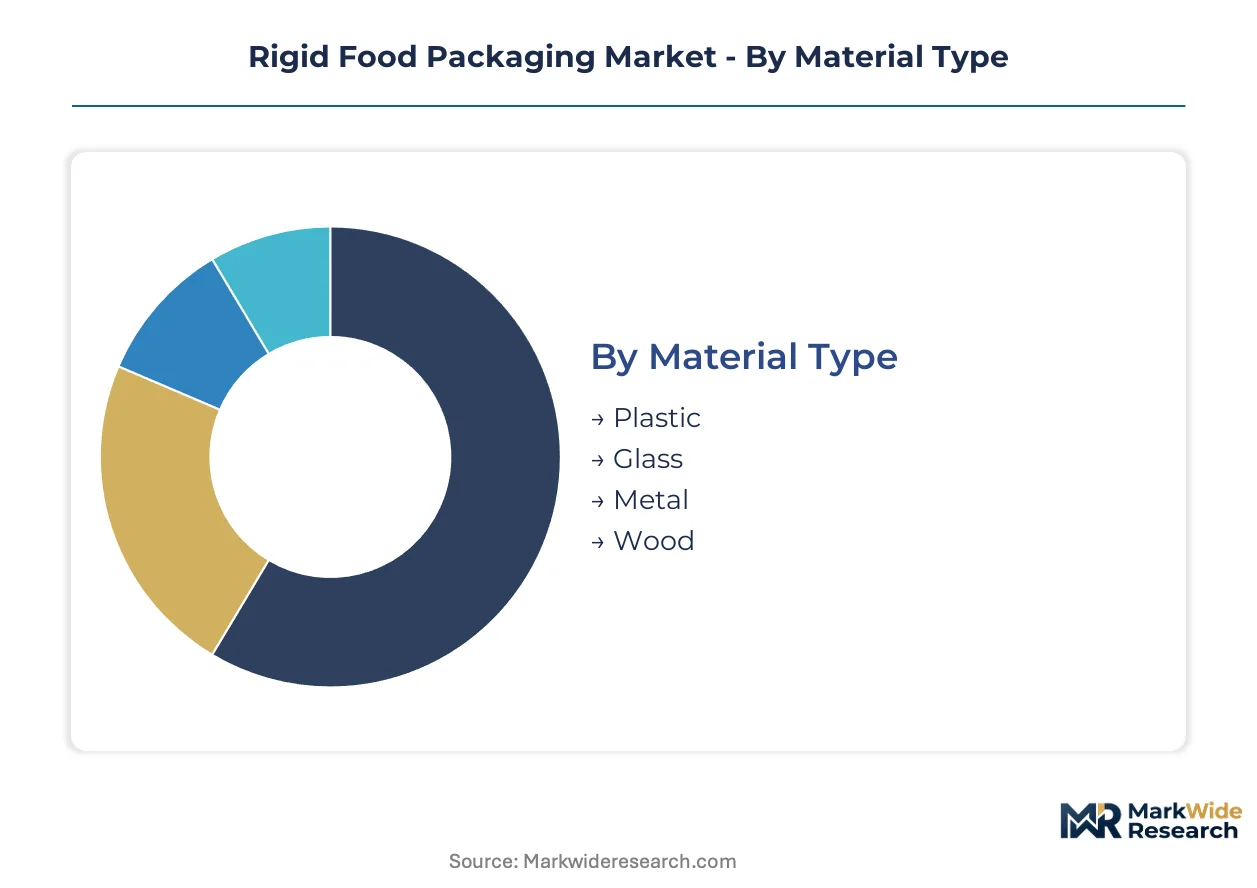
Material selection dictates barrier performance and recyclability pathways across rigid food packaging value chains. Product form determines automation compatibility and shelf presence in retail environments. End-user concentration shapes order specifications and volume commitments.
Material Type:
Converters differentiate procurement strategies based on thermal tolerance requirements and circular economy compliance timelines.
- Plastic:Polypropylene and polyethylene structures dominate beverage and condiment categories where lightweighting reduces freight expenditure. German dairy processors are specifying high-barrier mono-material trays to meet EU Green Deal sorting requirements.
- Metal:Tinplate and aluminum cans sustain retort processing temperatures that polymer alternatives cannot match. Ambient shelf-stable segments in the US Southeast remain structurally dependent on oxygen exclusion properties.
- Glass:Silica-based containers command premium positioning in specialty sauces and organic preserves. Breakage rates and unit weight constrain expansion in direct-to-consumer e-commerce channels.
- Wood:Fiber-based substrates serve niche applications in specialty cheese aging and premium gift packaging. REACH substance thresholds limit preservative treatments for European export compliance.
Volume sits with plastic; growth tilts toward fiber-based alternatives in chilled logistics.
Product Form:
Automation throughput and closure integrity specifications separate high-volume converters from specialty format suppliers.
- Bottles:Blow-molded HDPE and PET structures handle carbonated and still beverages through threaded neck finishes. Deposit-return infrastructure in Germany and Scandinavia drives food-grade rPET feedstock demand.
- Jars:Wide-mouth containers accommodate viscous products and spoon-access consumption. Glass jar specifications persist in organic preserves despite weight penalties in last-mile delivery.
- Tubs:Thermoformed polypropylene vessels serve spreadable dairy and dessert categories. In-mold labeling integration supports brand differentiation in European retail environments.
- Trays:Sealed barrier formats capture ready-to-eal meal adoption in urban corridors. DS Smith and competing converters are positioning molded pulp alternatives to displace expanded polystyrene in premium produce channels.
Trays are climbing the fastest as chilled meal formats expand; bottles retain the largest installed equipment base.
End User:
Order consolidation patterns and specification authority determine converter sales cycle complexity.
- Food Processing:Dairy and meat processors in Germany's industrial corridor drive just-in-time delivery requirements. Multi-year supply contracts with multinational brands anchor converter capacity planning.
- Retail:Supermarket private-label programs demand short-run customization without plate changeover costs. Digital print integration is capturing regional brand variant specifications.
- Foodservice:Institutional catering and restaurant chains prioritize portion control and stackability in back-of-house logistics. Sealed tray formats align with grab-and-go merchandising in convenience retail.
- E-commerce:Direct-to-consumer shipment requirements are forcing breakage-resistant material substitutions. Glass jar suppliers face margin compression from protective packaging add-ons.
Food processing commands volume scale; e-commerce is gaining share fastest as fulfillment networks expand.
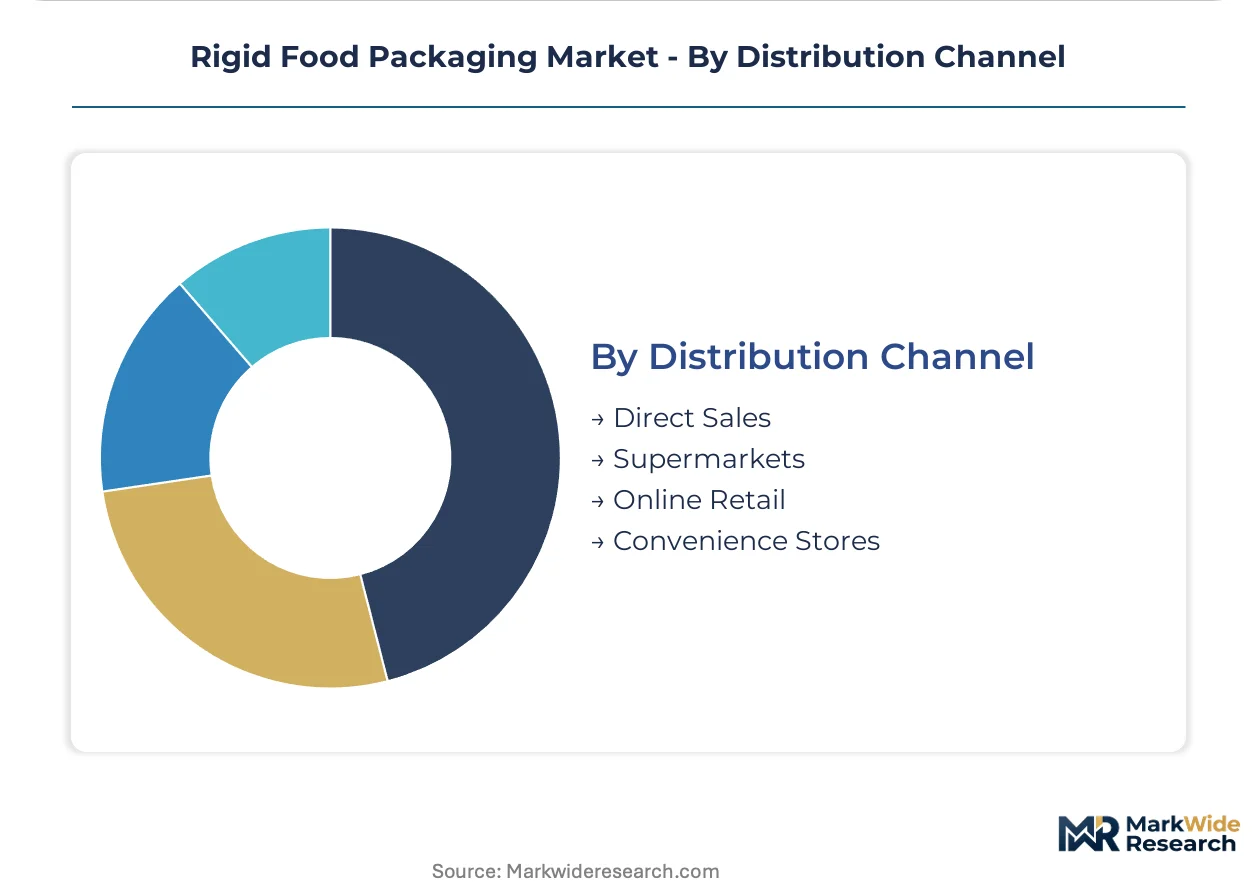
Distribution Channel:
Buyer concentration and procurement authority fragmentation shape pricing leverage and contract structures.
- Direct Sales:Converter relationships with multinational food brands bypass distributor markups through dedicated account management. Amcor leverages global manufacturing scale to anchor multi-year commitments.
- Supermarkets:Private-label consolidation in US Southeast and Midwest metropolitan corridors has reduced buyer count substantially since 2020. Regional distributor mergers compress converter sales cycles.
- Online Retail:Marketplace fulfillment requirements prioritize damage resistance and cube utilization. E-commerce penetration is accelerating specification changes in secondary packaging.
- Convenience Stores:Small-format retailers displace wholesale club purchasing for ambient and chilled stock-keeping units. Single-serve and portion-controlled formats align with immediate consumption occasions.
Direct sales capture margin; convenience stores are expanding most quickly as urban consumption patterns shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces disproportionate volumes of high-barrier trays and bottles for European food processors, while the United States consumes the largest absolute tonnage of rigid containers across beverage and ambient shelf-stable categories. China's converter base supplies cost-optimized formats for domestic dairy and condiment brands, though food-grade resin specifications lag Western compliance thresholds.
Germany
Sealed tray demand from Ruhr Valley meat processors and Bavarian dairy cooperatives drives converter capacity expansion along the industrial corridor. EFSA and REACH substance authorization timelines force compounders to accelerate compliant material development cycles. Converter density in North Rhine-Westphalia supports just-in-time delivery networks for chilled food logistics.
United States
Beverage bottlers in the Southeast and Midwest metropolitan corridors anchor HDPE and PET volume throughput for carbonated and still drinks. FDA food contact substance notification queues delay new additive commercialization by 18-36 months. The Pacific Northwest and California clusters concentrate food-grade rPET production capacity tied to deposit-return infrastructure.
China
Domestic dairy brands in the Yangtze River Delta and Pearl River Delta drive polypropylene tub and bottle specifications for spreadable products. SAMR food contact material standards and GB compliance frameworks create technical barriers for imported resin formulations. Shandong Peninsula converters specialize in cost-optimized condiment jars for regional sauce manufacturers.
France
Specialty sauce and organic preserve brands in Île-de-France sustain glass jar demand despite weight penalties in e-commerce channels. EU Green Deal sorting requirements push converters toward mono-material tray formats for ready-to-eat meal adoption. Auvergne-Rhône-Alpes food processors specify high-barrier structures for extended shelf-life cheese logistics.
India
FSSAI packaging material regulations and state-level plastic waste management rules reshape substrate selection for domestic edible oil and spice brands. Maharashtra and Gujarat converter clusters supply PET bottles and metal caps for processed food exporters. Karnataka dairy cooperatives pilot fiber-based chilled logistics formats for premium organic milk distribution.
Rigid Food Packaging Market Competitive Environment
Capital-heavy integrated producers compete with specialized converters who outsource resin compounding and metallization. The market structures around three tiers: multinational scale players anchoring multi-year supply contracts, regional specialists serving single-category processors, and emerging fiber-based innovators displacing foam insulation. Consolidation pressure intensifies as extended producer responsibility frameworks raise compliance costs that favor balance-sheet depth. Dominant competitive moves include backward integration into recycled resin feedstock and geographic expansion through distributor acquisition.
Among scale-driven multinationals, Amcor exemplifies the integrated converter archetype through global manufacturing footprints that secure beverage and condiment supply contracts. Berry Global occupies a position within the multi-layer barrier specialist tier, while DS Smith represents the fiber-based innovation vector competing for chilled logistics share. These three anchors illustrate how competitive positioning diverges across substrate technology and circular economy compliance capabilities.
| Leading Market Players |
|---|
| Sonoco |
| DS Smith |
| Amcor |
| Silgan Holdings |
| Ball Corporation |
| Berry Global |
| WestRock |
| Crown Holdings |
| Sealed Air |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal compliance timelines gate qualified supply access and premium-tier pricing power, as converters investing in mono-material barrier R&D capture multi-year contracts from German dairy processors while non-compliant competitors face specification lockout.
Pricing Analysis
Margin tightening in standard-grade polypropylene structures reflects crude derivative volatility and long-term contract rigidity. Three-tier pricing structure across premium, standard, and economy levels separates food-grade rPET certified for bottle-to-bottle loops from virgin resin alternatives and non-compliant imports. Price differentiation rests on EFSA substance authorization status and volume scale commitments. Food processing procurement teams exhibit highest price sensitivity; premium organic brands tolerate cost premiums for glass and fiber-based formats.
Supply Chain Analysis
Deposit-return system expansion in Germany and Scandinavia creates reverse-logistics feedstock flows that anchor food-grade rPET production capacity. Raw material procurement draws from Saudi Arabian and US Gulf Coast polyolefin suppliers, German chemical compounders for barrier additives, and Nordic collection infrastructure for post-consumer resin. Single-source vulnerability concentrates in metallized film and specialized oxygen scavenger additives. Distribution runs through direct converter relationships with multinational food brands, bypassing regional distributor markups in high-volume beverage and condiment categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization thresholds and extended producer responsibility frameworks erect compliance moats that favor capitalized incumbents with dedicated regulatory affairs staffing.
For Market Incumbents: Anchor multi-year supply contracts through backward integration into recycled resin feedstock and captive barrier technology R&D. Defend against fiber-based chilled logistics entrants by accelerating high-barrier mono-material polypropylene development cycles. Prioritize certification investment for EFSA and FDA food contact substance approvals to maintain specification authority with multinational dairy and meat processors. For New Entrants and Emerging Players: Digital print direct-to-shape systems offer technology-first wedge into supermarket private-label programs demanding short-run regional brand variants. Target convenience store distributor consolidation in US Southeast metropolitan corridors where buyer count compression creates procurement authority fragmentation. Pursue go-to-market partnerships with molded pulp tray converters serving premium organic produce channels. For Investors and Strategic Acquirers: FDA food contact substance notification queue clearance is the leading indicator that additive compounders have secured 18-36 month competitive lead times. Five-to-ten year viability favors converters with balance-sheet depth for extended producer responsibility compliance and geographic expansion through distributor acquisition. Monitor EFSA scientific opinion publication timelines as inflection signal for compliant material platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Feedstock | Captures closed-loop rPET supply from German and Scandinavian deposit-return infrastructure. |
| High-Barrier Mono-Material R&D Investment | Secures EU Green Deal sorting compliance for retort-ready tray specifications. |
| Digital Print Direct-to-Shape Deployment | Eliminates plate changeover costs for supermarket private-label regional variants. |
| Molded Pulp Tray Manufacturing Scale-Up | Displaces expanded polystyrene in premium organic chilled logistics channels. |
| Regulatory Affairs Capacity Expansion | Accelerates FDA and EFSA food contact substance notification throughput. |
Study Parameters
Document review covered FDA food contact substance notification databases, EFSA scientific opinion registers, EU F-Gas Regulation implementation reports, and trade customs records, complemented by interviews with converter procurement directors, dairy processor supply chain managers, retail category buyers, and barrier technology R&D leads. Secondary validation drew from SEC 10-K filings of publicly traded packaging companies, APR design-for-recycling guidelines, and OPRL labeling requirement updates. Bottom-up volume estimates from individual converter capacity announcements triangulated against top-down market sizing from resin consumption data.
Segment-level outputs across material type, product form, end user, and distribution channel dimensions were generated through driver-based modeling. CAGRs were derived from regression analysis against macroeconomic indicators and regulatory compliance timeline assumptions. Forecast inputs incorporated EU Green Deal implementation schedules, F-Gas Regulation phase-down milestones, and deposit-return system expansion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt resin price spikes or accelerated extended producer responsibility mandate adoption. Practitioners should monitor FDA notification queue lengths and EFSA substance authorization timelines for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
North America Airless Packaging Market