
 Telecom Enterprise Services Market | 2026-2036
Telecom Enterprise Services Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Enterprise Services Market Outlook
Healthcare is expanding its share of enterprise telecom spending as telemedicine, remote diagnostics, and hospital system consolidation drive dedicated connectivity requirements. AT&T leverages its fiber backbone to anchor large health system contracts across multiple states. Verizon Communications competes through specialized network segmentation that isolates patient data flows from general enterprise traffic. Deutsche Telekom sustains its position in European healthcare through GDPR-compliant managed services with strict latency guarantees.
Telecom Enterprise Services encompass dedicated voice, data, and managed network infrastructure delivered to organizational customers under contractual service level agreements specifying uptime percentages, latency thresholds, and security certifications. These services enable mission-critical operations across distributed facilities requiring guaranteed bandwidth and failover redundancy rather than best-effort consumer connectivity. Managed Services commands the largest revenue pool as enterprises outsource network operations complexity, while Cloud Solutions represents the fastest-expanding category as SD-WAN and SASE architectures displace legacy MPLS configurations. Hybrid deployment models attract the strongest margin profiles by combining on-premises control planes with cloud-delivered security functions.
FCC net neutrality rulings and state-level broadband subsidy programs shape infrastructure investment timelines and pricing flexibility for US carriers. EUs GDPR and forthcoming NIS2 Directive tighten security and incident-reporting obligations for cross-border enterprise networks, while Japans METI promotes 5G private networks for manufacturing through spectrum allocation reforms. Stakeholders must monitor how divergent national cybersecurity mandates fragment service architectures and compliance costs across multi-country accounts.
Market Dynamics
SD-WAN and SASE architectures are compressing legacy MPLS timelines as enterprises demand cloud-native security integration over dedicated private circuits. This technology shift is redistributing vendor margins from hardware-centric transport toward software-defined orchestration layers.
Growth Catalysts
- Healthcare Connectivity Mandates:HIPAA and state-level privacy rules tighten data-transport requirements, forcing hospital networks toward managed WAN with guaranteed encryption and audit trails.
- 5G Private Spectrum Allocation:Japan's METI spectrum reforms enable manufacturing campuses to deploy dedicated 5G networks for industrial automation and real-time quality control.
- Cloud Migration Velocity:Enterprise digitization in the United States, Germany, and Japan concentrates demand for low-latency cloud access, pulling spend from premises-based infrastructure.
Market Restraints
- Fiber Build Cost Inflation:Last-mile fiber deployment faces labor shortages and permitting delays that extend payback periods for rural enterprise connectivity.
- Vendor Concentration Risk:Hyperscale cloud providers dominate security stack integration, limiting carrier differentiation in SASE service bundles.
- Regulatory Fragmentation:Divergent national cybersecurity mandates across FCC, GDPR, and NIS2 jurisdictions multiply compliance architecture costs for multi-country accounts.
Strategic Opportunities
- Edge Computing Integration:Convergence of 5G transport with distributed cloud nodes creates new service tiers for latency-sensitive manufacturing and autonomous logistics.
- GDPR-Compliant Managed Services:European data residency requirements generate demand for carrier-hosted infrastructure with strict sovereignty guarantees.
- Underpenetrated Industrial Verticals:Mining, agriculture, and maritime sectors remain underserved by dedicated enterprise connectivity, offering first-mover expansion potential.
Industry Challenges
- Legacy System Integration:Enterprises maintain hybrid environments where SD-WAN overlays must interoperate with aging TDM voice switches and frame-relay remnants.
- Certification Timeline Compression:NIS2 incident-reporting obligations and sector-specific security frameworks accelerate compliance audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Enterprise Services Market |
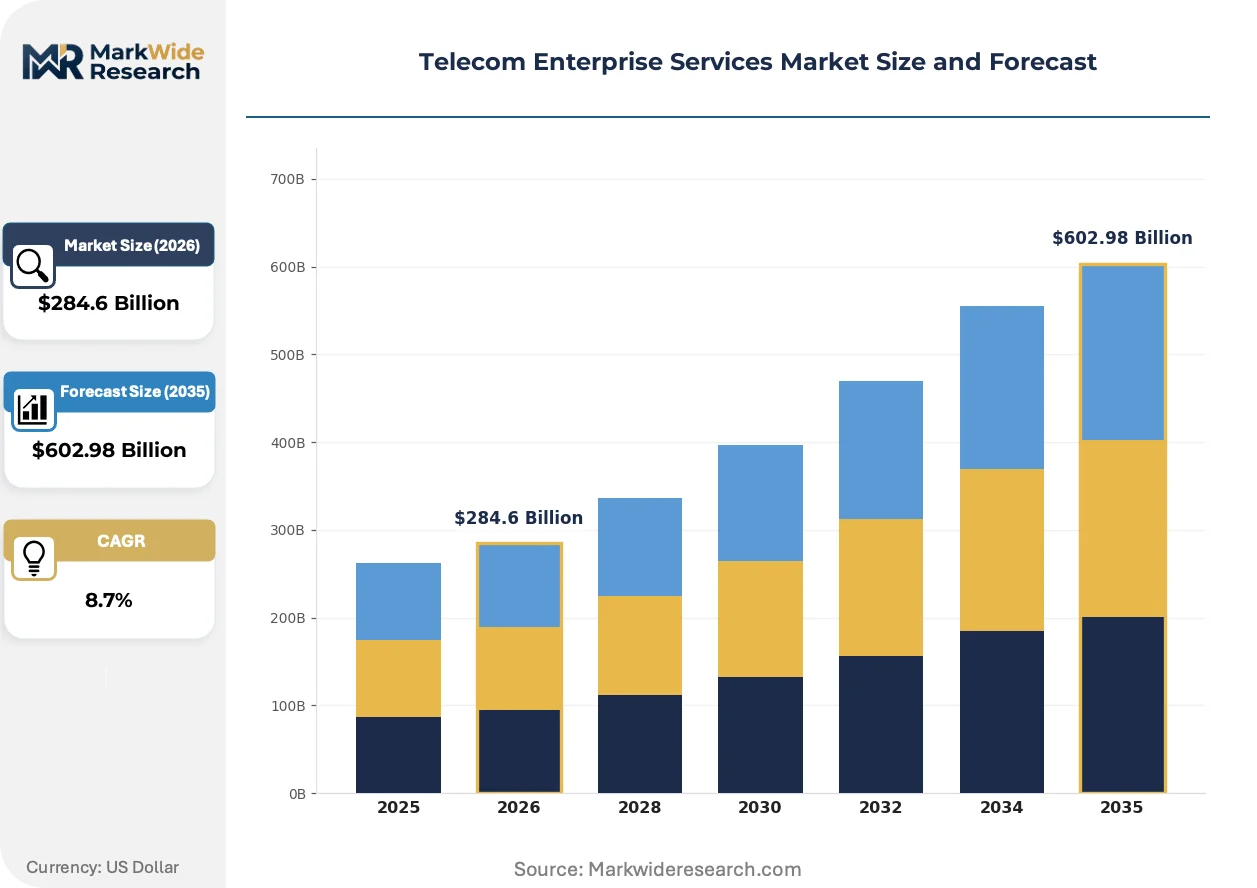
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $602.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Lines, VoIP, Managed Services, Cloud Solutions Industry Vertical: Healthcare, Retail, Manufacturing, Transportation Deployment Model: On-Premises, Cloud-Based, Hybrid, Co-Location Customer Type: SMBs, Enterprises, Public Sector, Non-Profits |
| Companies Covered | AT&T, Verizon Communications, Vodafone Group, Deutsche Telekom, Orange Business Services, BT Group, NTT Communications, China Telecom, Telefónica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Enterprise Services Market Strategic Shifts
Network virtualization is dissolving traditional boundaries between transport, security, and compute layers. Carriers now compete on orchestration sophistication rather than circuit reliability alone.
SD-WAN technology aggregates multiple transport types—broadband, LTE, MPLS—into unified policy-driven fabrics. Financial services and retail chains deploy these overlays to collapse branch connectivity costs. This architecture is converging with cloud security stacks, compressing the distinction between networking and cybersecurity procurement decisions.
The EU's NIS2 Directive mandates stricter incident reporting and supply-chain security audits for critical infrastructure operators. Telecom providers must restructure managed service contracts to assume greater liability for breach detection and response timelines. Healthcare and energy verticals in Germany and France face the steepest compliance recalibration.
Enterprise buyers now unbundle network management from hardware procurement, preferring opex-based service contracts with outcome-defined SLAs. Systems integrators and managed security specialists capture margin that carriers previously retained through equipment financing. This pattern concentrates in the United States and United Kingdom where CFOs prioritize balance-sheet flexibility over asset ownership.
Telecom Enterprise Services Market Segmentation
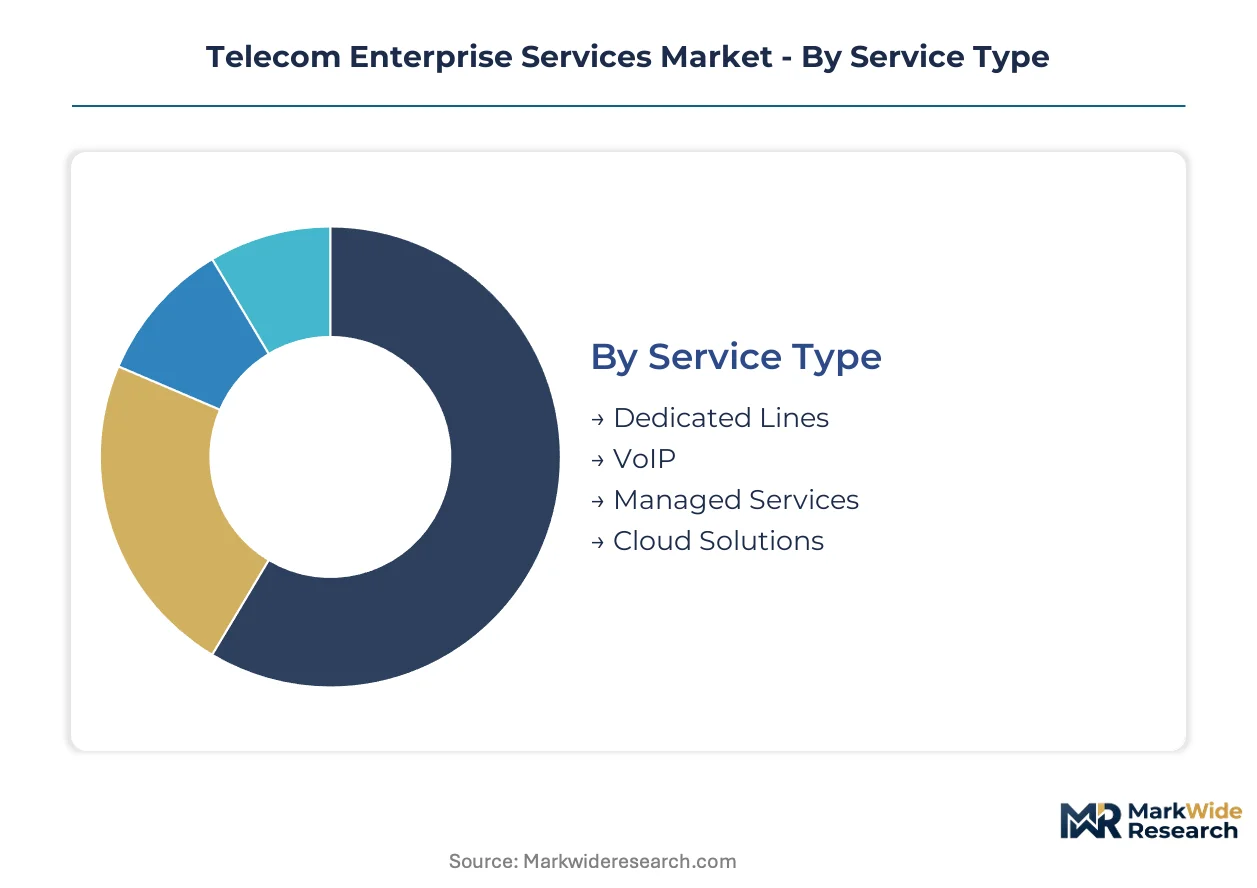
Enterprise telecom procurement decisions fragment across four distinct dimensions: technical service requirements, vertical compliance mandates, infrastructure control preferences, and organizational scale. Each segmentation axis reveals divergent margin structures and competitive dynamics that reshape carrier go-to-market strategies.
Service Type:
Buyers differentiate primarily by their tolerance for operational complexity versus capital efficiency, with outsourcing appetite determining contract value and duration.
- Managed Services:Comprehensive network operations outsourcing encompassing monitoring, maintenance, and security management under fixed-fee arrangements. Healthcare systems in the United States and Germany concentrate demand here as HIPAA and GDPR audit requirements exceed in-house IT capabilities. Carriers capture recurring revenue streams that extend average contract lifecycles substantially.
- Cloud Solutions:SD-WAN and SASE architectures delivered as subscription services with elastic capacity scaling. Manufacturing campuses in Japan leverage these for rapid 5G private network integration without premises-based controller investments. This segment compresses legacy MPLS displacement timelines while redistributing vendor margins toward software orchestration layers.
- Dedicated Lines:Point-to-point private circuits with guaranteed bandwidth and physical isolation. Financial clearinghouses and government facilities maintain demand for uncompromised transport security.
- VoIP:Packetized voice services replacing TDM infrastructure, typically bundled with unified communications platforms. Retail chains deploy these to collapse branch telephony costs.
Managed Services leads volumes today; Cloud Solutions is gaining share fastest.
Industry Vertical:
Regulatory intensity and uptime requirements create tiered pricing power across end-use sectors.
- Healthcare:Telemedicine expansion and hospital system consolidation drive dedicated connectivity with encryption mandates and sub-50ms latency guarantees for diagnostic imaging. State-level privacy rules in the US and GDPR Article 9 requirements in Europe force managed WAN adoption with comprehensive audit trails.
- Manufacturing:Industrial automation and real-time quality control systems demand deterministic latency that 5G private networks address. Japan's METI spectrum reforms accelerate campus network deployments.
- Retail:Distributed point-of-sale systems and inventory management prioritize cost-optimized SD-WAN overlays over premium dedicated circuits.
- Transportation:Fleet telematics and logistics tracking utilize cellular and satellite hybrid connectivity with intermittent availability tolerance.
Healthcare commands premium pricing; Manufacturing shows the steepest expansion trajectory.
Deployment Model:
Control plane location determines security liability allocation and compliance architecture complexity.
- Hybrid:Combines on-premises policy enforcement with cloud-delivered security functions, attracting strongest carrier margins through dual management fees. European enterprises favor this model to satisfy GDPR data residency requirements while accessing scalable threat intelligence feeds.
- Cloud-Based:Fully cloud-native delivery eliminates premises hardware, preferred by United States and United Kingdom CFOs prioritizing opex treatment and balance-sheet flexibility.
- On-Premises:Legacy configurations retaining physical appliances for regulated environments with air-gapped security mandates.
- Co-Location:Carrier-hosted infrastructure at exchange points, serving content delivery networks and financial trading firms requiring microsecond proximity to market data feeds.
Hybrid deployments dominate revenue contribution; Cloud-Based configurations are climbing the fastest.
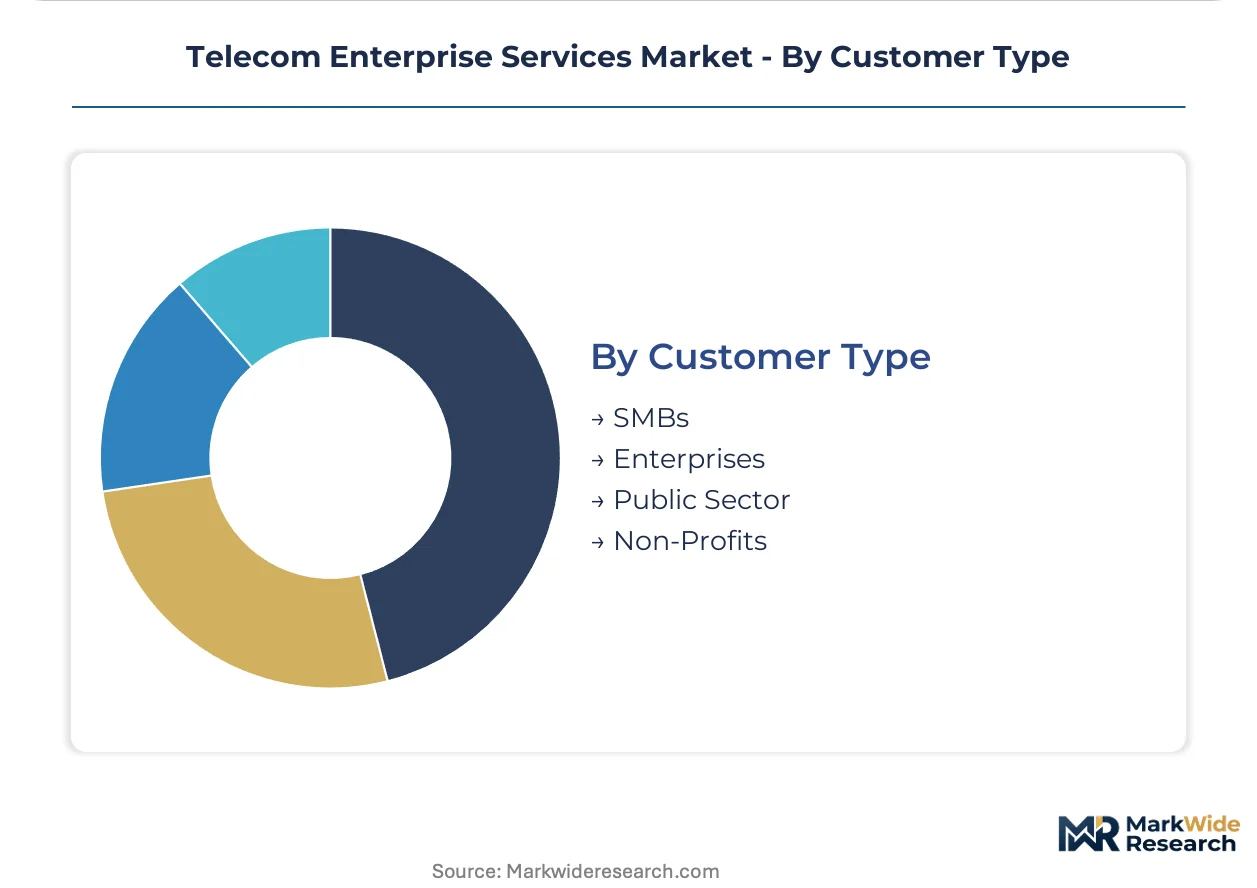
Customer Type:
Procurement sophistication and contract negotiation leverage separate organizational tiers.
- Enterprises:Multi-site organizations with dedicated procurement teams and custom SLA requirements, generating highest absolute contract values. These buyers unbundle network management from hardware financing, pressuring carrier margins while demanding outcome-defined performance guarantees.
- SMBs:Small and medium businesses purchasing standardized service tiers through channel partners, with price sensitivity limiting customization scope.
- Public Sector:Government and education institutions with extended procurement cycles and prevailing wage compliance requirements.
- Non-Profits:Mission-driven organizations qualifying for subsidized connectivity programs with reduced profitability for carriers.
Enterprises anchor revenue concentration; SMBs represent the volume expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage shapes carrier investment flows as compliance cost differentials widen between jurisdictions. Enterprises select service providers based on data residency mandates and incident-reporting obligations rather than transport pricing alone.
United States
Hospital system consolidation and telemedicine expansion drive managed WAN procurement with HIPAA-mandated encryption. FCC net neutrality rulings and state-level broadband subsidy programs reshape infrastructure investment timelines. Texas and California health networks anchor large-scale fiber deployments with sub-50ms latency guarantees for diagnostic imaging.
Germany
Industrial automation demand concentrates in automotive and precision manufacturing clusters. GDPR Article 9 and the forthcoming NIS2 Directive tighten security audit cycles for cross-border enterprise networks. Bavaria and Baden-Württemberg manufacturing campuses deploy 5G private networks through METI-influenced spectrum allocation models.
Japan
Real-time quality control systems in electronics and automotive assembly require deterministic latency that 5G private networks address. METI spectrum reforms enable dedicated campus network deployments without premises-based controller investments. Kanto and Kansai industrial corridors lead manufacturing digitization with cloud-native SD-WAN integration.
United Kingdom
Financial services and retail chains prioritize opex-based service contracts with outcome-defined SLAs. Post-Brexit data sovereignty requirements fragment compliance architectures from EU operations. London and Southeast England financial clearinghouses maintain demand for dedicated lines with microsecond proximity to exchange data feeds.
China
State-owned carriers dominate enterprise connectivity as MIIT promotes 5G private networks for smart manufacturing. Dual carbon goals accelerate edge computing integration in energy-intensive industrial zones. Yangtze River Delta and Pearl River Delta manufacturing hubs concentrate cloud solution deployments with strict data localization mandates.
Telecom Enterprise Services Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with incumbent telecom carriers defending transport revenue while systems integrators capture orchestration margins. The vendor base organizes around three tiers: integrated national carriers with fiber backbone ownership, managed security specialists with SASE software stacks, and regional challengers competing on price-standardized SMB offerings. Market structure rewards scale in infrastructure deployment and regulatory certification depth. Competitive moves concentrate on strategic partnerships between carriers and hyperscale cloud providers, plus portfolio diversification into edge computing nodes.
Among integrated national carriers, AT&T, Deutsche Telekom, and NTT Communications exemplify archetypes spanning North American, European, and Asia-Pacific regulatory jurisdictions. These entities anchor multi-country enterprise accounts through compliance-certified managed services. Their positioning reflects fiber asset depth and security stack integration capabilities rather than software-native agility.
| Leading Market Players |
|---|
| AT&T |
| Verizon Communications |
| Vodafone Group |
| Deutsche Telekom |
| Orange Business Services |
| BT Group |
| NTT Communications |
| China Telecom |
| Telefónica |
| Others |
Value Chain & Pricing Dynamics
EU NIS2 Directive compliance timelines gate both qualified supplier status and premium-tier pricing access for managed security services, as carriers must restructure contracts to assume breach-detection liability before commanding outcome-based SLAs.
Pricing Analysis
Distributor margin compression in SD-WAN orchestration software redistributes value toward direct-to-enterprise SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments by SLA guarantee strength and encryption certification depth. Pricing pressure stems from hyperscaler cloud providers bundling security stacks at scale, eroding carrier differentiation. Healthcare systems show least price sensitivity due to HIPAA audit liability, while retail chains prioritize cost-optimized broadband overlays.
Supply Chain Analysis
Returns and refurbishment flows for legacy MPLS hardware create secondary equipment markets that extend TDM infrastructure lifecycles in regulated environments. Supply concentrates in the United States, Germany, and Japan for fiber backbone infrastructure and 5G private network equipment. Component dependencies include silicon photonics chips, wavelength-division multiplexing gear, and edge computing nodes. Single-source vulnerability in submarine cable landing stations threatens transatlantic enterprise connectivity. Distribution runs through carrier-direct sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between FCC net neutrality jurisdictions and GDPR-NIS2 compliance zones, where divergent cybersecurity mandates multiply contract complexity premiums for multi-country accounts.
For Market Incumbents: Cement fiber asset control in Texas and California health corridors to anchor large-system contracts against hyperscaler encroachment. Deepen backward integration into edge computing node deployment to capture orchestration margins. Prioritize NIS2 certification investment ahead of competitor readiness to lock European manufacturing accounts. For New Entrants and Emerging Players: Enter via maritime and agricultural connectivity white space where dedicated enterprise services remain underpenetrated. Target Japan's Kanto industrial corridor for 5G private network specialization without legacy MPLS baggage. Lead with opex-based SD-WAN subscriptions to bypass capital-intensive fiber build requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional managed security specialists because carrier consolidation is concentrating compliance certification scarcity. Long-term viability hinges on SASE software stack ownership rather than transport infrastructure. Watch hyperscaler partnership announcements as inflection signals for carrier margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Node Deployment | Captures latency-sensitive manufacturing demand through METI-influenced 5G spectrum reforms. |
| SASE Platform Integration | Compresses distinction between networking and cybersecurity procurement decisions for CFOs. |
| GDPR-Compliant Managed Services | Locks European healthcare accounts through Article 9 data residency guarantees. |
| Strategic Partnership with Hyperscalers | Defends carrier relevance as cloud providers dominate security stack integration. |
| Geographic Expansion into Industrial Verticals | Targets mining and agriculture sectors with first-mover connectivity solutions. |
Study Parameters
Direct dialogue with carrier network operations executives, enterprise IT procurement officers, healthcare compliance directors, and systems integrator partners combined with secondary validation from FCC rulings, EU NIS2 directive texts, METI spectrum allocation filings, and carrier 10-K disclosures. Bottom-up and top-down triangulation reconciles contract value analysis with infrastructure deployment tracking.
Bottom-up modeling aggregates individual enterprise contract values across service type, vertical, and deployment model segments; top-down verification cross-checks against national fiber deployment statistics and spectrum auction proceeds. Segmentation dimensions include technical service requirements, compliance intensity by vertical, infrastructure control preferences, and organizational scale tiers. CAGRs derive from elasticity-adjusted demand curves incorporating cloud migration velocity and 5G private network adoption rates.
The model holds under stable regulatory enforcement timelines; deviation in FCC net neutrality reversals or NIS2 implementation delays would shift carrier investment priorities. Forecasts reflect assumptions about enterprise digitization pacing and hyperscaler competitive positioning. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
North America Managed Services Market
Enterprise Services
Shared Services Center Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Field Service Management Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market