
 North America IT Device Market | 2026-2036
North America IT Device Market Size, Share, and Industry Trends Forecast 2026-2036
North America IT Device Market Analytics
The US EPA ENERGY STAR certification program is expanding procurement mandates across federal agencies and large enterprises, compelling OEMs to redesign power architectures. Microsoft Corporation leverages its Azure-integrated Surface portfolio to anchor hybrid-work contracts across Fortune 500 accounts. Dell Technologies sustains manufacturing scale through its Austin, Texas operations, while Apple Inc. differentiates via vertical silicon control from design to foundry placement.
North America IT devices encompass computing hardware including microprocessors, memory modules, storage subsystems, and display assemblies engineered for data processing, connectivity, and human interface. These systems operate across thermal envelopes from 15W ultraportable processors to 350W server-grade silicon, serving transactional, analytical, and immersive workloads. Laptops and servers command the largest revenue pools, with cloud computing and AI-enabled configurations representing the fastest-expanding technology layer. Tablets face margin compression as enterprise buyers consolidate around convertible laptop form factors, while direct sales channels capture premium pricing in government and healthcare verticals.
The Federal Communications Commission governs electromagnetic emissions and spectrum allocation for wireless-enabled devices, while the US Food and Drug Administration regulates IT hardware deployed in diagnostic and patient-monitoring contexts under 21 CFR Part 820 quality-system requirements. State legislatures in California, Minnesota, and New York are advancing right-to-repair statutes that mandate parts availability and diagnostic tool access, forcing OEMs to restructure service revenue models. Stakeholders must monitor how NIST cybersecurity framework revisions and emerging FDA software-as-medical-device guidance reshape hardware authentication requirements and product liability exposure.
Market Dynamics
Enterprise refresh cycles are compressing from five-year to three-year intervals as hybrid-work mandates and AI-ready hardware requirements force simultaneous fleet upgrades across Fortune 500 accounts.
Growth Catalysts
- EPA ENERGY STAR procurement mandates:Federal agencies and state governments now require certified devices, redirecting R&D budgets toward power-efficient architectures and creating guaranteed demand pools for compliant OEMs.
- Right-to-repair legislation:Minnesota and New York statutes mandating parts availability and diagnostic tool access are extending hardware lifecycles and opening secondary service markets previously captured by manufacturers.
- Cloud computing infrastructure buildouts:Hyperscale data center expansions across Texas, Virginia, and Oregon are pulling server-grade silicon, memory modules, and storage subsystems through direct procurement channels at enterprise scale.
Market Restraints
- Advanced node foundry concentration:Taiwan-based TSMC controls production of sub-5nm processors, exposing North American OEMs to geopolitical disruption risk and allocation constraints during demand spikes.
- DDR5 memory cost volatility:Complex multi-layer packaging and yield challenges at Samsung and SK Hynix facilities are inflating bill-of-materials for high-performance laptops and servers.
- FCC electromagnetic compliance timelines:Extended certification queues for Wi-Fi 7 and 6GHz devices are delaying product launches and compressing selling seasons for back-to-school and holiday cycles.
Strategic Opportunities
- Canadian federal digital modernization:Ottawa's cloud-first procurement directives and AI adoption frameworks are creating underserved demand for secure, domestically compliant enterprise devices outside US saturation zones.
- ARM-based architecture convergence:The intersection of power-efficient mobile processors with desktop-class performance is enabling fanless designs and extended battery life in enterprise convertible form factors.
- Healthcare IT hardware certification:FDA 21 CFR Part 820 quality-system requirements for diagnostic device integration are creating premium pricing tiers for hardened, validated systems in hospital networks.
Industry Challenges
- Semiconductor packaging engineer scarcity:The specialized skill set for chiplet integration and 3D stacking is concentrated at a handful of universities and incumbent fabs, constraining design team scaling.
- NIST cybersecurity framework compliance:Hardware authentication and supply chain attestation requirements are extending product development cycles and requiring pre-market security certification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America IT Device Market |
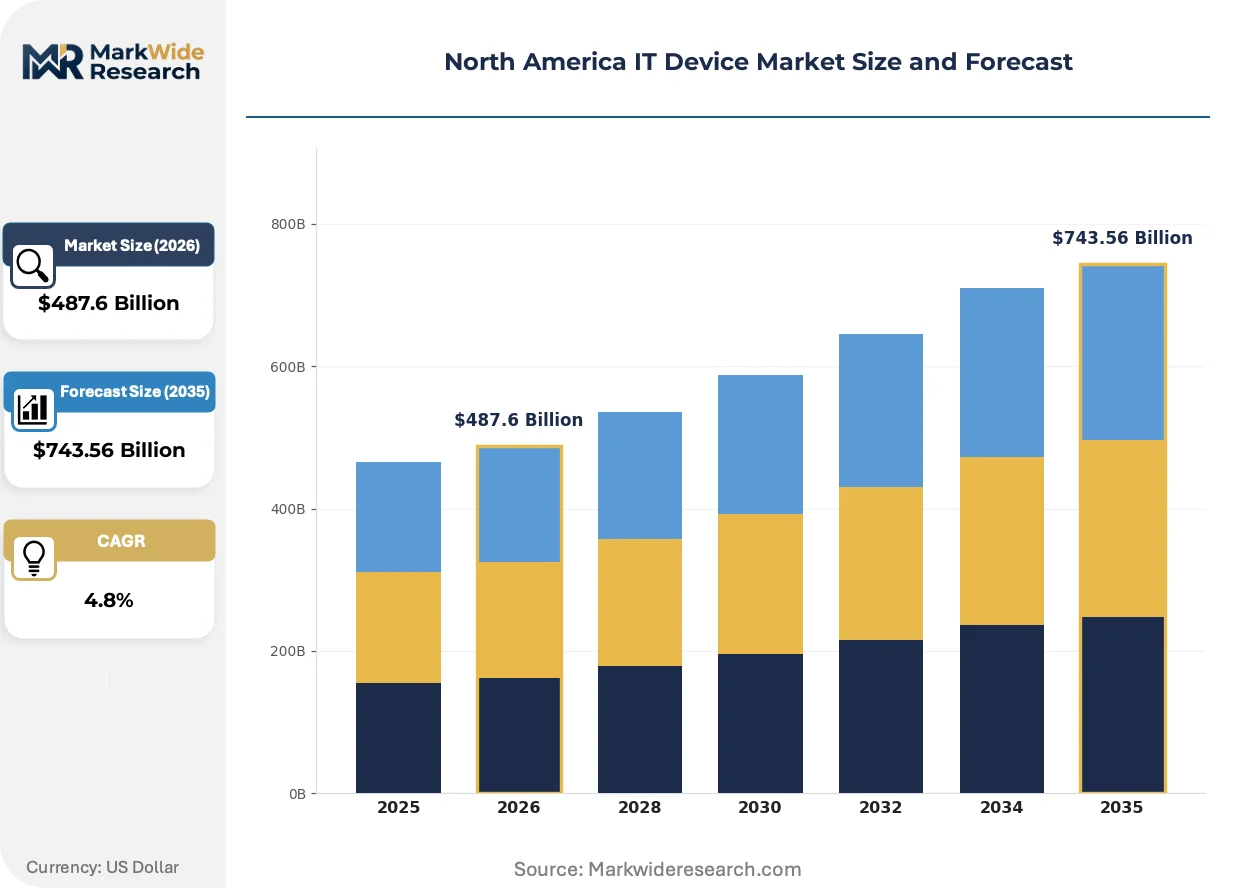
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laptops, Desktops, Tablets, Servers End User: Corporate, Education, Government, Healthcare Technology: Cloud Computing, AI, IoT, Virtual Reality Distribution Channel: Online Retail, Direct Sales, Resellers, Retail Stores |
| Companies Covered | Microsoft Corporation, Apple Inc., Lenovo Group Limited, Dell Technologies, Intel Corporation, IBM Corporation, Samsung Electronics Co., Ltd., Hewlett Packard Enterprise, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America IT Device Market Evolving Landscape
AI inference workloads are restructuring silicon priorities across the device stack, forcing thermal design power envelopes upward and memory bandwidth requirements to outpace traditional CPU-centric specifications.
Neural processing units are absorbing matrix multiplication and transformer-model execution from general-purpose CPUs in enterprise laptops. Fortune 500 IT departments are specifying NPU TOPS thresholds in RFPs for 2024-2025 fleet renewals. This shift is absorbing margin from discrete GPU add-in cards in standard business configurations while concentrating value capture at the SoC level.
California's right-to-repair statute and pending federal analogues are mandating schematic disclosure and serialized parts availability for seven-year windows. OEMs are restructuring service revenue from replacement sales to extended warranty and parts distribution. Enterprise buyers in healthcare and government verticals are rewriting procurement specifications to prioritize repairability scores alongside performance benchmarks.
Device-as-a-service contracts are displacing capital expenditure ownership in mid-market enterprise segments. Dell, HP, and Lenovo direct sales organizations are competing with CDW and SHI International for multi-year managed endpoint agreements. This transition is most visible in Texas and California metropolitan corridors where private equity-backed portfolio companies are standardizing on operational expenditure models for tax efficiency.
North America IT Device Market Segmentation
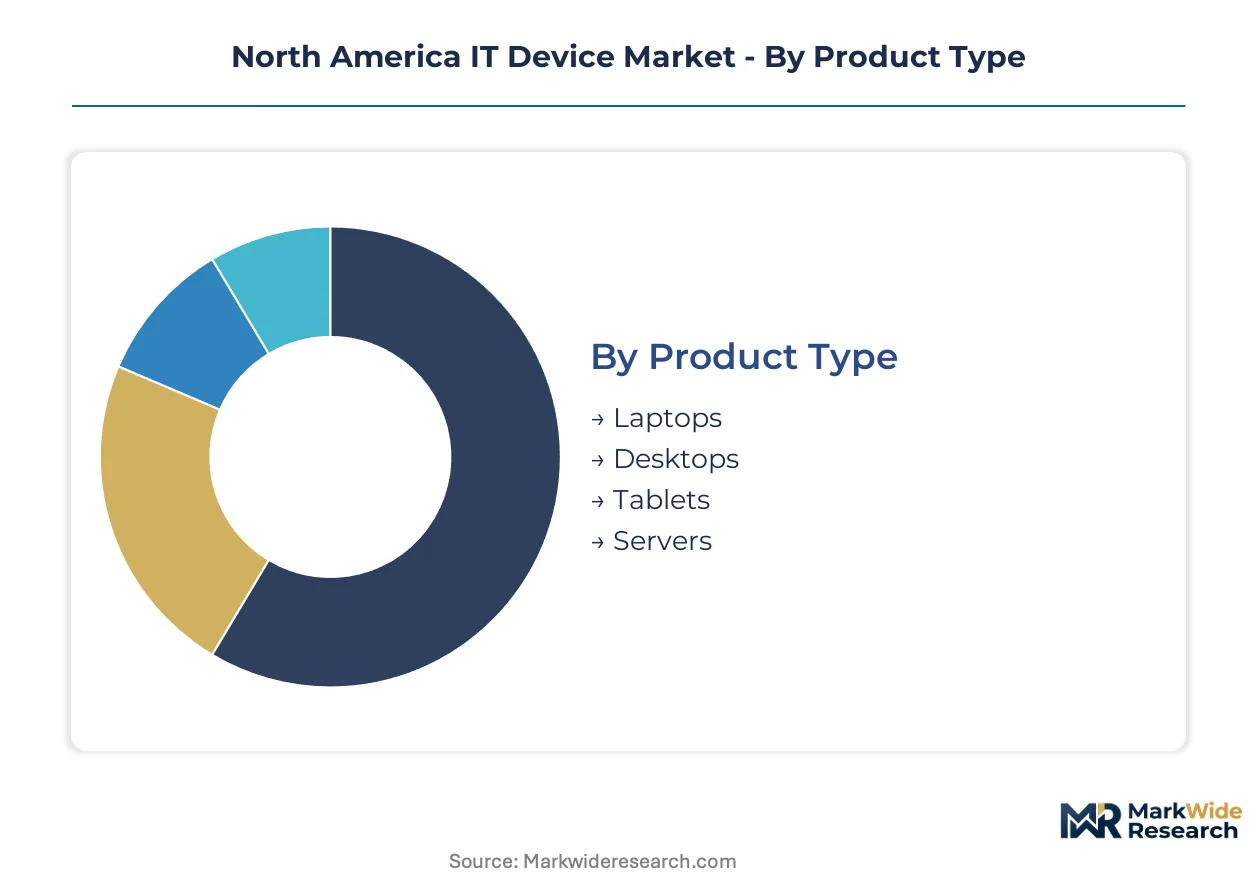
IT device procurement across North America diverges sharply between standardized volume contracts and customized enterprise configurations. Segmentation reveals how thermal design power, regulatory compliance tiers, and service-attach requirements reshape vendor economics across each category boundary.
Product Type:
Customization intensity spans from commodity desktop towers to thermally constrained mobile workstations, with standardization concentrated in price-sensitive institutional segments.
- Laptops:Convertible form factors with 15W to 45W TDP envelopes dominate Fortune 500 refresh cycles. Texas and California metropolitan corridors absorb the dominant share as hybrid-work mandates force simultaneous fleet upgrades across enterprise accounts.
- Servers:Rack-mounted systems with 350W server-grade silicon serve hyperscale data center expansions across Virginia and Oregon. Direct procurement channels at enterprise scale pull memory modules and storage subsystems through cloud computing infrastructure buildouts.
- Desktops:Tower and small-form-factor units persist in cost-sensitive education and government verticals where capital expenditure constraints outweigh mobility requirements.
- Tablets:Enterprise buyers consolidate around convertible laptop alternatives, compressing margins as form factor boundaries blur in corporate procurement specifications.
Leading the category by volume: Laptops. Growing fastest: Servers.
End User:
Procurement sophistication escalates from volume-driven education tenders to compliance-intensive healthcare integrations, with margin capture inversely correlated to standardization.
- Corporate:Enterprise refresh cycles compress to three-year intervals as AI-ready hardware requirements and hybrid-work mandates force simultaneous upgrades. Device-as-a-service contracts displace capital expenditure ownership in mid-market segments across Texas and California corridors.
- Healthcare:FDA 21 CFR Part 820 quality-system requirements for diagnostic device integration create premium pricing tiers. Hardened, validated systems command procurement priority in hospital networks where liability exposure drives specification stringency.
- Government:Federal agencies require EPA ENERGY STAR certified devices, redirecting vendor R&D toward power-efficient architectures and creating guaranteed demand pools for compliant OEMs.
- Education:K-12 and higher education institutions prioritize capital expenditure efficiency over performance thresholds, concentrating volume in standardized desktop and entry-level laptop configurations.
Corporate procurement generates the largest revenue pool. Healthcare specifications command the highest margin premiums.
Technology:
Architecture maturity separates deployed infrastructure from emerging workload categories, with integration complexity determining vendor service-attach rates.
- Cloud Computing:Hyperscale data center expansions across Texas, Virginia, and Oregon pull server-grade silicon through direct procurement channels. Infrastructure-as-a-service models concentrate purchasing authority at cloud provider procurement organizations.
- AI:Neural processing units absorb matrix multiplication workloads from general-purpose CPUs in enterprise laptops. Fortune 500 IT departments specify NPU TOPS thresholds in fleet renewal RFPs, restructuring silicon priorities across the device stack.
- IoT:Edge computing deployments in manufacturing and logistics verticals demand hardened connectivity modules with extended thermal operating ranges.
- Virtual Reality:Enterprise training and design visualization applications remain concentrated in specialized aerospace and automotive manufacturing accounts with dedicated IT support infrastructure.
Cloud Computing anchors current infrastructure investment. AI-enabled configurations are climbing the fastest.
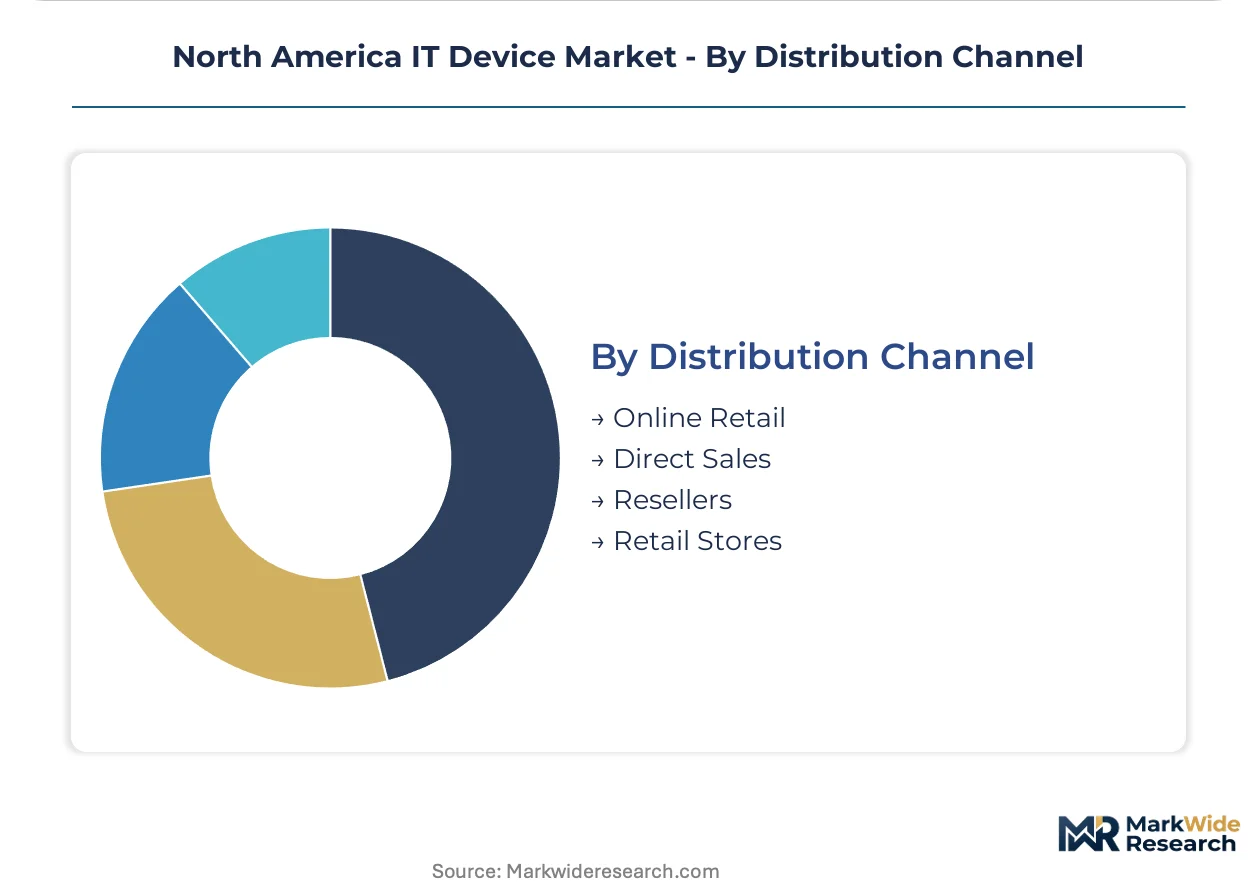
Distribution Channel:
Channel selection reflects procurement scale and compliance complexity, with direct engagement dominating regulated verticals and self-service capturing price-sensitive volume.
- Direct Sales:Dell, HP, and Lenovo direct sales organizations compete for multi-year managed endpoint agreements. Premium pricing persists in government and healthcare verticals where procurement specifications require pre-market security certification and hardware authentication.
- Resellers:CDW and SHI International intermediate enterprise volume with configuration services and logistics integration for distributed workforce deployments.
- Online Retail:Self-service procurement dominates small and medium business segments where standard configurations satisfy technical requirements without consultation overhead.
- Retail Stores:Consumer and prosumer segments sustain foot traffic in metropolitan corridors, though enterprise procurement bypasses this channel entirely.
Direct Sales captures the highest margin transactions. Online Retail is expanding most quickly in the mid-market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austin, Texas anchors North American IT device manufacturing with Dell Technologies sustaining server and laptop assembly operations that feed enterprise procurement corridors across the southern United States.
United States
Federal agencies mandate EPA ENERGY STAR certified devices, redirecting vendor R&D toward power-efficient architectures. The FCC governs electromagnetic emissions and spectrum allocation for wireless-enabled hardware. Texas, California, and New York metropolitan corridors absorb dominant procurement volumes as Fortune 500 accounts execute simultaneous fleet upgrades.
Canada
Ottawa's cloud-first procurement directives and AI adoption frameworks create underserved demand for secure, domestically compliant enterprise devices. Health Canada and PMRA regulate hardware deployed in diagnostic contexts through quality-system requirements. Toronto and Vancouver technology clusters concentrate federal and provincial government IT modernization contracts.
Mexico
Nearshoring incentives pull electronics assembly and component manufacturing across the northern border states. Mexico's national standards body, NOM, enforces electromagnetic compatibility and energy efficiency labeling for imported devices. Guadalajara and Tijuana industrial corridors house contract manufacturing operations serving US enterprise demand.
North America IT Device Market Competitive Landscape
Premium-margin players sit above commodity-margin players across silicon integration and service-attach capabilities. The vendor base separates into three tiers: integrated OEMs controlling chip-to-system design, contract assemblers competing on logistics scale, and component specialists capturing value at the memory and storage layers. Strategic archetypes include ARM-based architecture convergers, repairability-compliant service restructurers, and DaaS contract aggregators. Dominant competitive moves encompass M&A for NPU IP and capacity expansion across Texas and Mexico border zones.
Within the integrated OEM tier, Microsoft Corporation and Apple Inc. occupy positions exemplifying divergent control strategies over silicon and software stacks. Dell Technologies anchors the enterprise direct-sales archetype with manufacturing presence in Austin. These three entities represent the spectrum from cloud-integrated endpoint ecosystems to vertical silicon control.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Apple Inc. |
| Lenovo Group Limited |
| Dell Technologies |
| Intel Corporation |
| IBM Corporation |
| Samsung Electronics Co., Ltd. |
| Hewlett Packard Enterprise |
| Oracle Corporation |
| Others |
Value Network & Pricing Analysis
DDR5 memory module costs cascade from Samsung and SK Hynix fabrication facilities through server-grade configurations to enterprise laptop bill-of-materials, with yield challenges at advanced nodes compressing margins across premium tiers before reaching volume education contracts.
Pricing Analysis
Outcome-based pricing tied to fleet uptime guarantees anchors enterprise device-as-a-service contracts across Fortune 500 accounts. Pricing stratifies across ENERGY STAR-certified premium tiers, FDA-validated healthcare configurations, and standardized education volumes. Cost compression in mid-market laptops intensifies because convertible form factor consolidation forces vendor competition on identical specifications. Education procurement exhibits highest price sensitivity; healthcare hardened systems command lowest buyer elasticity.
Supply Chain Analysis
Reverse-logistics flows for right-to-repair compliance extend hardware lifecycles through refurbishment corridors in Guadalajara and Tijuana, feeding secondary service markets with serialized components. Taiwan, South Korea, and the United States concentrate sub-5nm foundry capacity and advanced packaging operations. The supply chain draws from cobalt-dense cathodes, high-bandwidth memory stacks, and rare-earth magnet assemblies. Single-source vulnerability at TSMC for leading-edge silicon creates allocation risk during demand spikes. Distribution runs through direct sales organizations for regulated verticals and reseller intermediaries for distributed enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America IT Device Market functions as a cost-of-compliance arena where EPA ENERGY STAR mandates and emerging right-to-repair statutes erect regulatory moats favoring incumbents with pre-certified product portfolios and established service infrastructure.
For Market Incumbents: Hedge against ARM-based architecture convergence by securing NPU IP through targeted acquisitions and accelerating Austin-based capacity for AI-ready server silicon. TSMC allocation constraints threaten production continuity; backward integration into domestic advanced packaging at Intel and Samsung Austin facilities reduces single-source exposure. Certification maintenance for FDA and FCC compliance preserves premium pricing in healthcare and government verticals.
For New Entrants and Emerging Players: Capture underserved Canadian federal procurement outside US saturation zones by aligning with Ottawa's cloud-first directives and domestic security requirements. The repairability-compliant service tier offers penetrable white space as OEMs restructure from replacement revenue to parts distribution. A channel partnership strategy with CDW or SHI International bypasses direct sales infrastructure requirements.
For Investors and Strategic Acquirers: Minnesota and New York right-to-repair enactment is the leading indicator that service revenue restructuring will separate repairable-design specialists from replacement-dependent vendors across the analysis window. Target acquisition archetypes include NPU IP specialists and domestic advanced packaging operations. Monitor FCC certification queue lengths as inflection signal for product launch velocity and selling season capture.
| Strategic Initiative | Industry Significance |
|---|---|
| NPU IP Acquisition | Neural processing unit integration secures Fortune 500 fleet renewal specifications ahead of CPU-centric competitors. |
| Domestic Packaging Expansion | Advanced node packaging at Intel and Samsung Austin reduces Taiwan concentration risk for hyperscale server demand. |
| Right-to-Repair Service Restructuring | Seven-year parts availability mandates in California and Minnesota transform replacement revenue to warranty and distribution models. |
| Canadian Federal Channel Development | Ottawa's cloud-first procurement creates underserved demand for domestically compliant enterprise device vendors. |
| Healthcare FDA 21 CFR Part 820 Certification | Diagnostic device integration requirements command premium pricing tiers in hospital network procurement. |
Research Methodology
Document review covered SEC 10-K filings from Dell Technologies and HP Inc., hyperscaler capex disclosures from Microsoft Azure and Amazon Web Services, FCC equipment authorization databases, and EPA ENERGY STAR certified product listings, complemented by interviews with enterprise IT procurement officers, biomedical engineers at hospital systems, OEM platform architects, and channel sales directors at CDW and SHI International. Secondary validation drew from customs import records for semiconductor components, NIST cybersecurity framework revisions, and state legislative tracking for right-to-repair statutes. Bottom-up unit shipment estimates triangulated against top-down enterprise IT spending surveys.
Segmentation outputs across product type, end user, technology layer, and distribution channel were projected across the modeling period using elasticity-adjusted replacement cycle compression and AI-enabled configuration penetration curves. CAGRs derived from weighted average of historical shipment volatility, enterprise fleet refresh acceleration, and cloud infrastructure buildout pull-through. Forecast inputs incorporated TSMC capacity allocation patterns, DDR5 yield improvement trajectories, and ENERGY STAR procurement mandate expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical disruption at Taiwan foundries, federal right-to-repair legislation passage, and NIST cybersecurity framework hardware authentication revisions. Material deviation in TSMC allocation priority, Minnesota-style repairability statute adoption velocity, or hyperscaler data center construction cadence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Learning Analytics Market
Others
Spend Analytics Market
Others
Flexographic Printing Plate Market
Others
Content Experience Platforms Market
Others
AI in Home Automation Market
Others
AI In Government And Public Services Market
Others
Chip Card Scanners Market
Others
ISO Cylinder Market
Others
High Frequency Vibrator Market
Others
Security Bottles Market
Others
Dried Fruit Extracts Market
Others
Africa Cotton Market
Others
AI in Precision Medicine Market
Others
Smart Home Solutions Market
Others
North America Halal Food and Beverage Market
Others
Fresh Durian Market