
 North America Healthcare Flexible Packaging Market | 2026-2036
North America Healthcare Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Healthcare Flexible Packaging Market Intelligence
Home care medication delivery is realigning demand toward child-resistant, senior-friendly pouch formats. Amcor plc leverages its pharmaceutical-certified film laminating network across the Midwest to serve this shift. Sealed Air Corporation sustains leadership in sterile barrier systems for implantable devices through advanced cleanroom extrusion capabilities. ProAmpac LLC differentiates via specialized high-barrier structures for moisture-sensitive oncology APIs.
Healthcare flexible packaging denotes multilayer polymer or paper-polymer laminates engineered to provide microbial barrier, chemical stability, and tamper evidence for regulated medical and pharmaceutical contents, typically incorporating heat-sealable coextruded films with oxygen transmission rates below 0.1 cc per square meter per day. Its primary purpose is preserving sterility and potency from manufacture through patient administration. Stand-up pouches and roll stock dominate volume throughput, with roll stock commanding tighter margins due to commodity polyethylene input cost exposure while stand-up pouches capture premium positioning through value-added dispensing features. Bags for diagnostic specimen collection represent a mature, replacement-driven segment, whereas wraps for sterile device kits are gaining share as outpatient surgical volumes rise.
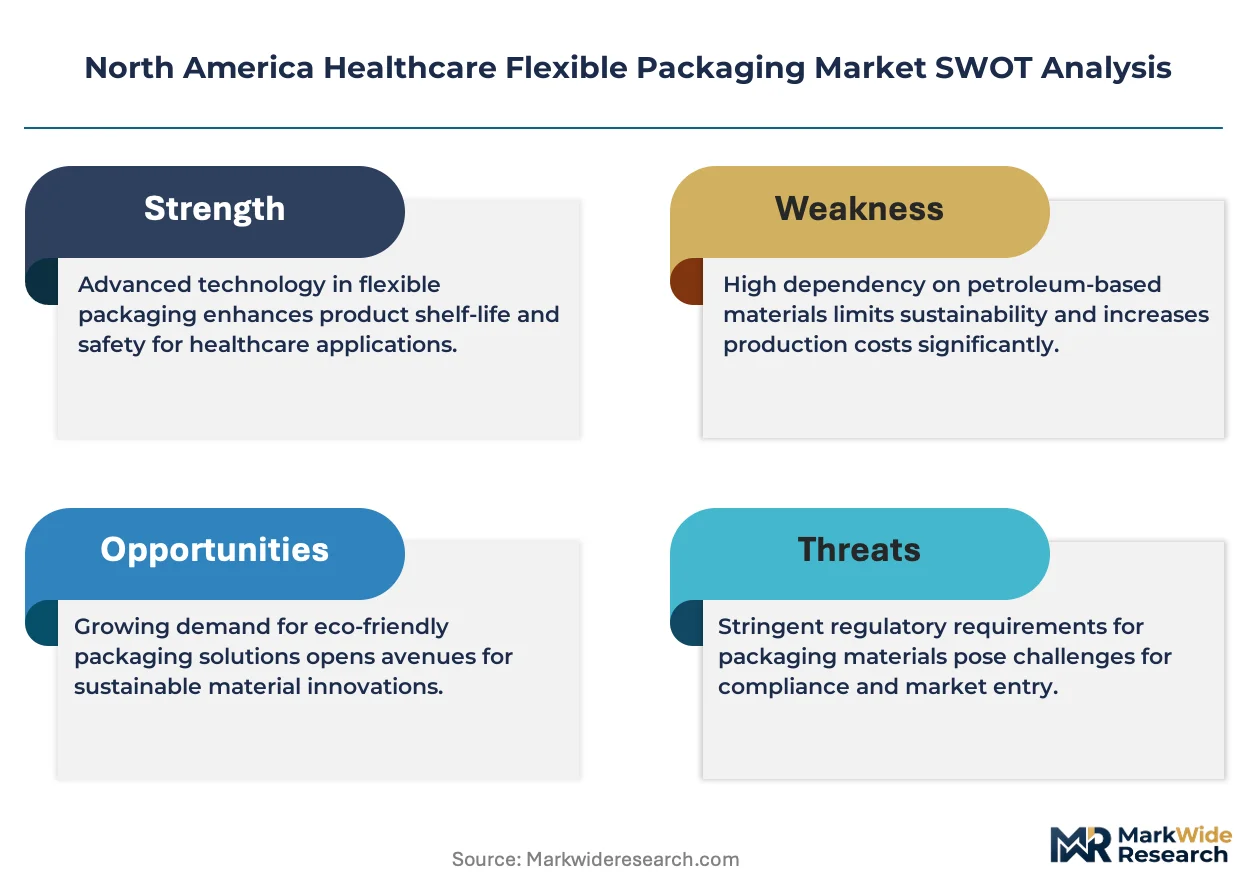
FDA Title 21 CFR Part 211 and USP <661> packaging standards govern material biocompatibility and extractables testing, compelling converters to maintain validated supply chains and documentation systems. Health Canada's Medical Device Regulations and ISO 11607 sterilization validation requirements further shape cross-border product qualification protocols. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions, as fluorochemical barrier coatings face prospective phase-out timelines that could force rapid material transitions across sterile packaging portfolios.
Market Dynamics
Serialization mandates from FDA and Health Canada are compressing qualification timelines for pharmaceutical contract packagers, forcing converters to revalidate multilayer film structures ahead of 2027 compliance deadlines. This regulatory velocity is restructuring supplier-buyer relationships across the Great Lakes manufacturing corridor.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Track-and-trace requirements for prescription drugs are expanding demand for integrated smart packaging with embedded authentication features across Wisconsin and Illinois production facilities.
- Outpatient surgical migration:Ambulatory surgery centers in Michigan and Ohio are scaling sterile barrier pouch consumption for implantable device kits, outpacing hospital-based procurement growth.
- High-barrier coextrusion:Oxygen transmission rates below 0.1 cc per square meter per day are becoming standard specification for oncology API protection, pulling investment into Midwest cleanroom extrusion capacity.
Market Restraints
- Polyethylene input cost exposure:Roll stock margins compress when resin prices spike, disproportionately affecting commodity converters lacking long-term supply agreements with Gulf Coast petrochemical suppliers.
- Fluorochemical barrier dependency:EPA per- and polyfluoroalkyl substance restrictions threaten sterile packaging portfolios that rely on fluorinated coatings for moisture and chemical resistance.
- Cleanroom capacity concentration:Sterile barrier system production clusters in southeastern Wisconsin and northern Illinois, creating geographic vulnerability to regional labor disruptions or weather events.
Strategic Opportunities
- Home infusion therapy expansion:Senior-friendly pouch formats for self-administered biologics present white space in Texas and Florida markets where aging demographics concentrate.
- EU MDR-aligned export qualification:Canadian converters achieving ISO 11607 sterilization validation can access European medical device packaging demand without redundant certification.
- Recyclable mono-material structures:How2Recycle labeling acceptance for polyethylene-based sterile barriers opens channel access through hospital sustainability procurement committees.
Industry Challenges
- Extractables testing expertise shortage:USP 661.1 chemical characterization requirements demand analytical chemists with specialized polymer leachable profiling capabilities that Midwest packaging hubs struggle to recruit.
- Cross-border documentation harmonization:Health Canada Medical Device Regulations and FDA Title 21 CFR Part 211 maintain divergent batch record requirements, complicating integrated US-Canada supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Healthcare Flexible Packaging Market |
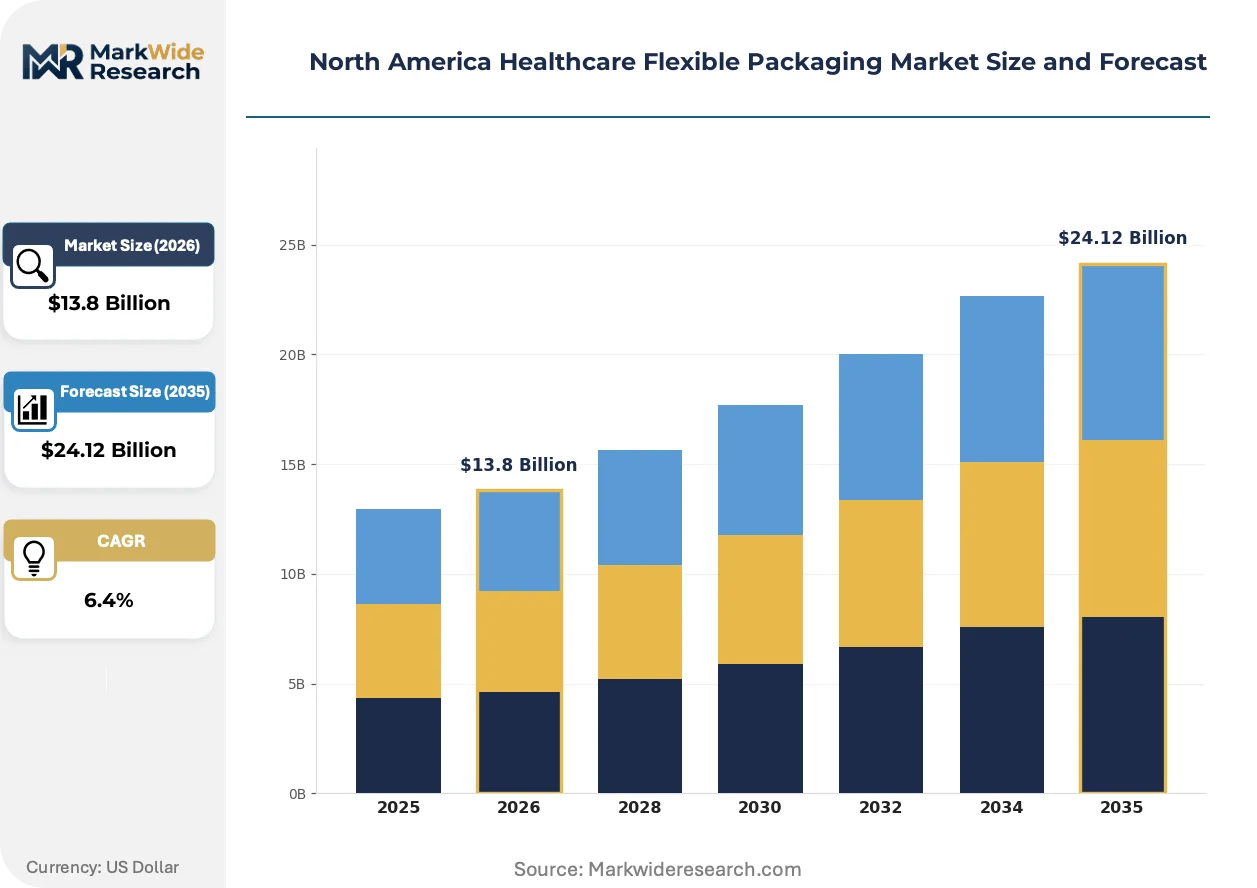
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Roll Stock, Bags, Wraps Material: Polyethylene, Polypropylene, Nylon, Paper Application: Pharmaceuticals, Medical Devices, Dietary Supplements, Diagnostics End User: Hospitals, Clinics, Labs, Home Care |
| Companies Covered | Constantia Flexibles, Transcontinental Inc., Amcor plc, ProAmpac LLC, American Packaging Corporation, Sealed Air Corporation, Sonoco Products Company, CCL Industries, Mondi plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Healthcare Flexible Packaging Market Strategic Shifts & Innovations
Material science advances and regulatory compliance automation are converging to redefine sterile barrier performance standards. Converters are racing to embed traceability and sustainability credentials without compromising microbial protection.
Ethylene vinyl alcohol copolymer is overtaking metallized polyethylene terephthalate as the preferred oxygen barrier layer in pharmaceutical pouches. Oncology API packagers in Illinois are specifying EVOH-rich coextrusions at triple the rate of 2022 baselines. This transition is overtaking legacy metallized structures in premium moisture-sensitive applications while reducing aluminum content for recyclability scoring.
Health Canada's Medical Device Regulations now mandate sterilization validation documentation that aligns with ISO 11607-1:2019 shelf-life testing protocols. Canadian contract manufacturers serving US parent companies face dual jurisdiction audits, compressing product launch timelines by four to six months. Sterile device kit wrappers destined for cross-border distribution absorb the heaviest compliance burden, with Ontario-based converters investing in redundant testing capacity.
Hospital procurement committees are consolidating supplier rosters around vendors offering integrated serialization and sustainability certification. Group purchasing organizations in the US Midwest now require How2Recycle labeling and recycled content disclosures as threshold qualifications for pouch contract awards. This concentration is most visible in Michigan's Detroit-Ann Arbor corridor, where health system mergers have reduced active flexible packaging suppliers from twelve to four across major oncology and implantable device categories.
North America Healthcare Flexible Packaging Market Segmentation
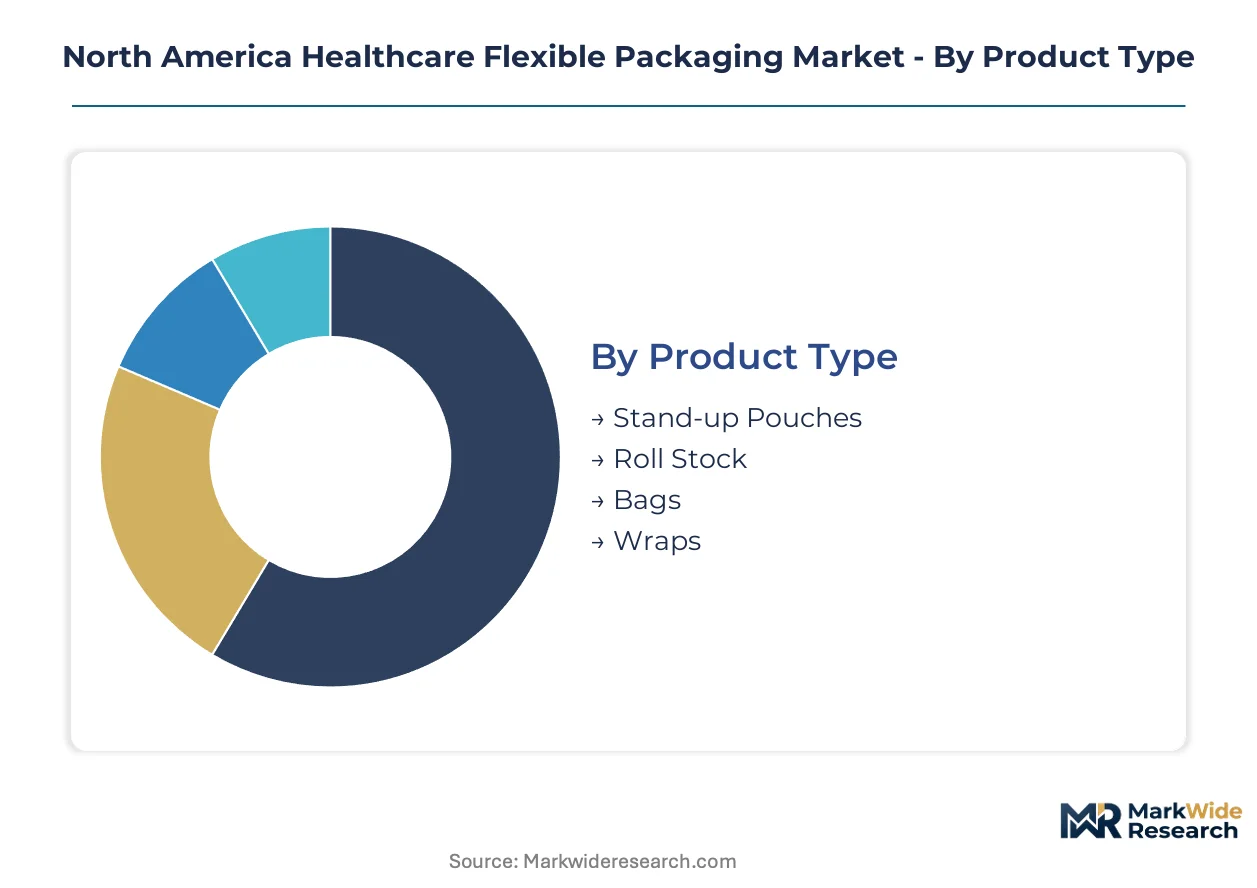
Healthcare flexible packaging segmentation reflects divergent certification burdens across pharmaceutical and medical device channels. FDA Title 21 CFR Part 211, USP 661, and ISO 11607 validation requirements create tiered compliance costs that reshape competitive positioning within each category.
Product Type:
FDA Drug Supply Chain Security Act track-and-trace mandates impose distinct serialization requirements across pouch formats, with sterile barrier systems facing the heaviest documentation loads.
- Stand-up Pouches:Multilayer coextruded structures with child-resistant closures and senior-friendly dispensing features dominate home care biologics delivery. Michigan and Ohio ambulatory surgery centers are specifying these for implantable device kits as outpatient volumes rise.
- Roll Stock:Unformed film webs supplied to contract packagers for pharmaceutical blister and pouch conversion carry commodity polyethylene cost exposure. Wisconsin converters serving high-volume oral solid dose lines maintain long-term Gulf Coast resin agreements to defend margin position.
- Bags:Diagnostic specimen collection pouches with integrated absorbent materials face mature replacement demand cycles.
- Wraps:Sterile barrier systems for surgical instrument kits require ISO 11607-1 shelf-life validation and accelerated aging protocols.
Roll stock sits at the top of the volume ranking, with stand-up pouches climbing the fastest.
Material:
Material selection hinges on oxygen transmission specifications and recyclability scoring under How2Recycle labeling protocols now required by Midwest hospital group purchasing organizations.
- Polyethylene:Linear low-density and high-density grades form the base layer in most sterile barrier laminates. Cleanroom extrusion capacity in southeastern Wisconsin concentrates production of medical-grade PE with extractables profiles meeting USP 661.1.
- Polypropylene:Cast and oriented PP films provide clarity and moisture barrier for diagnostic device windows. Illinois converters are expanding biaxially oriented PP capacity for high-visibility pharmaceutical labeling applications.
- Nylon:Polyamide layers deliver puncture resistance and thermoformability for surgical tray packaging.
- Paper:Medical-grade kraft and Tyvek substrates enable steam and ethylene oxide sterilization permeability for device wraps.
Polyethylene commands the highest tonnage, though polypropylene is expanding most quickly as clarity requirements intensify.
Application:
Application segments separate by sterilization method and potency protection requirements, with oncology APIs demanding the tightest oxygen barrier specifications.
- Pharmaceuticals:Oral solid dose, injectable, and biologic packaging requires USP 661 chemical characterization and stability studies. EVOH-rich coextrusions with sub-0.1 cc oxygen transmission rates are becoming standard specification for moisture-sensitive oncology APIs in Illinois production facilities.
- Medical Devices:Sterile barrier systems for implantable and surgical instruments face ISO 11607 validation and Health Canada MDR-aligned documentation. Ontario-based converters serving cross-border distribution are absorbing redundant testing capacity investments.
- Dietary Supplements:Nutraceutical pouches with tamper-evident features follow less stringent USP 2091 guidelines.
- Diagnostics:Specimen transport bags and test kit packaging prioritize puncture resistance and temperature stability.
Medical devices lead absolute volume, while pharmaceuticals are gaining share fastest as serialization mandates expand.
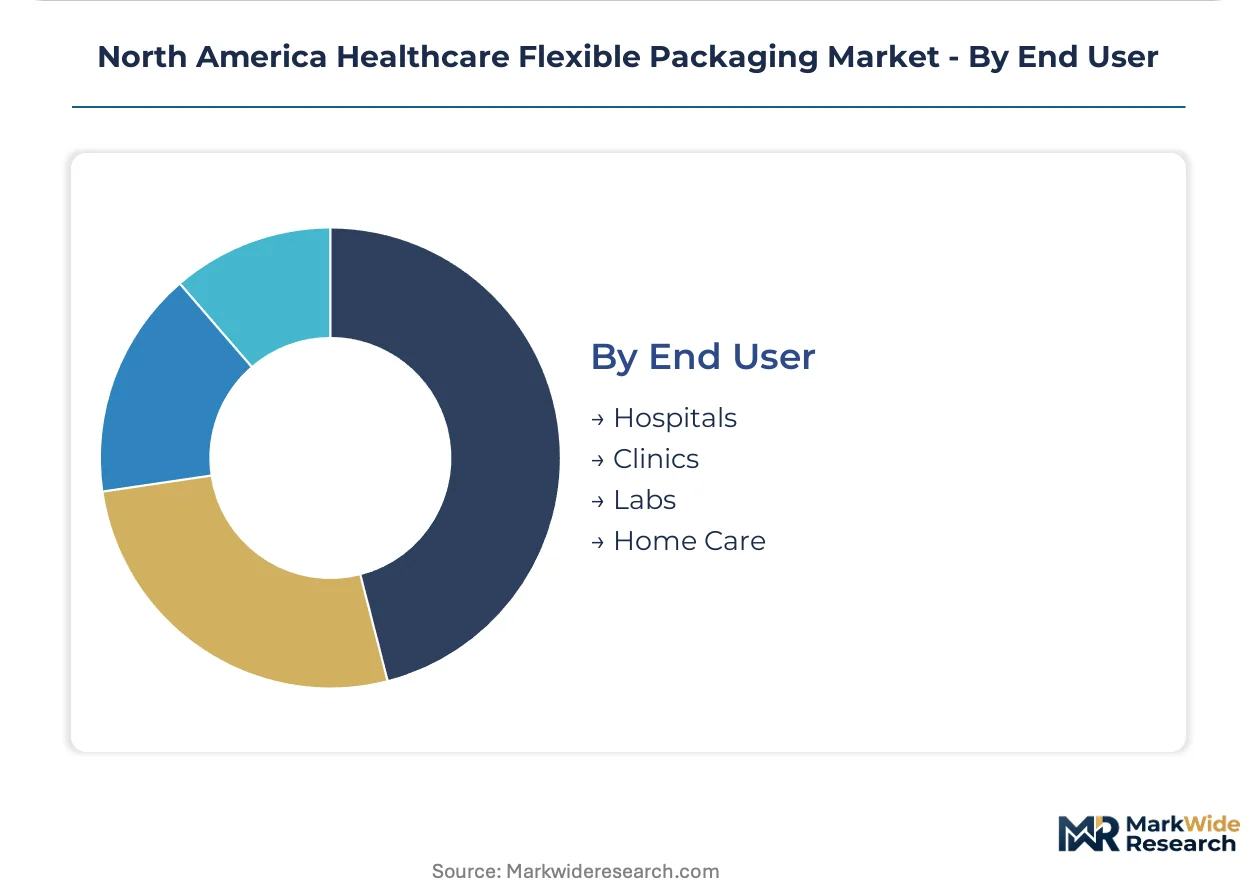
End User:
End user procurement patterns diverge sharply between institutional consolidated purchasing and fragmented home care channels.
- Hospitals:Integrated delivery networks in Michigan's Detroit-Ann Arbor corridor have consolidated active flexible packaging suppliers from twelve to four across major categories. Group purchasing organizations now mandate How2Recycle labeling and recycled content disclosures as threshold qualifications.
- Home Care:Self-administered biologics and infusion therapy are creating white space demand for senior-friendly pouch formats. Texas and Florida markets with concentrated aging demographics are pulling Midwest converter capacity into regional distribution.
- Clinics:Physician office laboratories and urgent care centers source lower-volume, standardized pouch configurations.
- Labs:Reference and clinical laboratories maintain steady demand for diagnostic specimen bags with absorbent and biohazard features.
Hospitals retain the dominant procurement volume, with home care showing the steepest expansion trajectory as medication delivery migrates beyond institutional settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as converters migrate capacity toward jurisdictions with streamlined FDA and Health Canada alignment protocols. Cost-of-compliance gaps between serialization-ready facilities and legacy operations are accelerating this geographic sorting.
United States
FDA Drug Supply Chain Security Act mandates and outpatient surgical volume expansion drive demand across the Great Lakes corridor. Title 21 CFR Part 211 validation requirements concentrate investment in Wisconsin and Illinois cleanroom extrusion facilities. Michigan's Detroit-Ann Arbor corridor hosts intensifying sterile barrier pouch production for ambulatory surgery centers.
Canada
Health Canada Medical Device Regulations and EU MDR-aligned export qualification protocols attract cross-border contract packaging investment. ISO 11607 sterilization validation requirements pull Ontario-based converters toward redundant testing capacity. Toronto-area facilities absorb compliance burdens for sterile device kit wrappers destined for US-European distribution.
Mexico
Nearshoring advantages and proximity to Texas medical device clusters expand maquiladora flexible packaging output. COFEPRIS regulatory convergence efforts with FDA standards reduce dual-qualification friction. Baja California and Chihuahua production zones supply diagnostic specimen bag volumes to southwestern US laboratory networks.
North America Healthcare Flexible Packaging Market Key Industry Players
Capacity expansion dominates the current landscape as converters race to install cleanroom extrusion lines ahead of 2027 serialization deadlines. The supplier base concentrates around three tiers: multinational film laminators with pharmaceutical-certified networks, regional contract packagers with sterilization validation expertise, and commodity roll stock producers exposed to resin price volatility. Strategic archetypes include barrier-enhancement specialists, integrated serialization providers, and sustainability-focused mono-material innovators. M&A activity and geographic diversification represent the dominant competitive vectors as players defend margin position against polyethylene input cost swings.
Among diversified packaging conglomerates, Amcor plc and Sealed Air Corporation exemplify scale-driven archetypes with Midwest pharmaceutical-certified infrastructure. ProAmpac LLC occupies a specialist position within high-barrier oncology API protection. These three entities anchor the competitive structure through differentiated cleanroom capabilities and regulatory qualification depth rather than commodity volume positioning.
| Leading Market Players |
|---|
| Constantia Flexibles |
| Transcontinental Inc. |
| Amcor plc |
| ProAmpac LLC |
| American Packaging Corporation |
| Sealed Air Corporation |
| Sonoco Products Company |
| CCL Industries |
| Mondi plc |
| Others |
Cost & Logistics Intelligence
Captive cleanroom extrusion capacity in southeastern Wisconsin and northern Illinois anchors both supply security and pricing power for sterile barrier systems. Converters with in-house pharmaceutical-certified film laminating networks command premium positioning against commodity roll stock producers exposed to Gulf Coast polyethylene spot markets.
Pricing Analysis
Distributor margins for sterile barrier pouches compress when group purchasing organizations consolidate supplier rosters, while direct-to-hospital contracts reward serialization-ready converters with pricing premiums. Three-tier pricing structure across pharmaceutical-certified, medical-grade standard, and commodity roll stock levels separates converters by FDA Title 21 CFR Part 211 validation depth. Cost compression in commodity polyethylene-based roll stock is intensifying because resin price spikes transmit directly to margin pressure. Ambulatory surgery centers show highest price sensitivity as procurement shifts from hospital-based integrated delivery networks to fragmented outpatient channels.
Supply Chain Analysis
Freight costs from Wisconsin and Illinois cleanroom clusters to Texas and Florida home care markets are reshaping regional distribution economics as aging demographics pull capacity southward. Raw material supply draws from Gulf Coast petrochemical complexes for polyethylene resin, Ontario-based EVOH barrier film production, and domestic medical-grade paper substrates. Single-source vulnerability concentrates in fluorochemical barrier coatings facing EPA per- and polyfluoroalkyl substance phase-out timelines. Distribution runs through hospital group purchasing organizations and direct contracts with ambulatory surgery center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory compliance burdens into sustainable competitive moats, with FDA Drug Supply Chain Security Act serialization mandates through 2027 creating irreversible qualification barriers for late entrants.
For Market Incumbents: To counter polyethylene input cost volatility, secure long-term Gulf Coast resin offtake agreements and expand captive cleanroom extrusion capacity in Michigan's Detroit-Ann Arbor corridor. Backward integration into EVOH-rich coextrusion technology defends margin position against metallized film substitutes. For New Entrants and Emerging Players: Direct-to-ambulatory-surgery-center digital procurement platforms offer the most penetrable route around entrenched hospital GPO relationships. Target senior-friendly pouch formats for Texas and Florida home infusion therapy markets where Midwest converter distribution remains underdeveloped. Lead with How2Recycle-certified mono-material structures to satisfy sustainability procurement committees. For Investors and Strategic Acquirers: Roll-up economics work for regional contract packagers with ISO 11607 sterilization validation expertise because Health Canada and FDA dual-qualification requirements create irreplicable regulatory assets. Five-to-ten year viability hinges on consolidation of Ontario-based redundant testing capacity serving cross-border distribution. Watch for EPA fluorochemical restriction acceleration as inflection signal forcing rapid material transition capex.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Extrusion Capacity Expansion | Pharmaceutical-certified film laminating networks in Wisconsin defend against commodity resin price volatility. |
| EVOH Barrier Technology Transition | Sub-0.1 cc oxygen transmission specifications displace legacy metallized structures for oncology API protection. |
| Dual FDA-Health Canada Qualification | ISO 11607 sterilization validation unlocks cross-border sterile device kit wrapper contracts without redundant certification. |
| How2Recycle Mono-Material Development | Polyethylene-based sterile barrier acceptance opens hospital sustainability procurement committee channel access. |
| Home Care Pouch Format Innovation | Senior-friendly dispensing features capture self-administered biologics demand in Texas and Florida aging demographics. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical packaging procurement managers, cleanroom extrusion plant engineers, FDA regulatory affairs consultants, and hospital group purchasing organization contract directors with secondary validation against FDA Drug Supply Chain Security Act guidance documents, Health Canada Medical Device Regulations, USP 661 extractables testing protocols, ISO 11607 sterilization validation standards, and SEC 10-K filings from diversified packaging conglomerates. Bottom-up capacity and demand modeling triangulated against top-down market sizing.
Segment-weighting across product type, material composition, application, and end user channels structured the analytical framework over the projection horizon. CAGRs derived from trend extrapolation of cleanroom extrusion capacity installation rates, outpatient surgical volume migration patterns, and EVOH barrier film adoption curves. Forecast inputs incorporated FDA serialization mandate compliance timelines and EPA per- and polyfluoroalkyl substance restriction evolution scenarios.
The model assumes a particular technology adoption path; alternative pathways for fluorochemical-free barrier coatings would alter the outlook if material science breakthroughs accelerate beyond current EVOH transition baselines. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and resin price volatility persistence. A model refresh is warranted upon material change in EPA fluorochemical phase-out scheduling or Health Canada-EU MDR alignment protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Transparent Plastics Market
Others
Lychee Market
Others
Traditional PC Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Storage Dewars Market
Others
Europe Military 4D Printing Market
Others
Smart Home and Office Market
Others
Africa Cotton Market
Others
Global Snow Sports Apparel Market
Others
Latin America Contract Packaging Market
Others
AC Switchgear Market
Others
Architectural Fabrics Market
Others
North America Thermoformed Plastics Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Europe Refrigerated Display Cases Market
Others
Qatar Smartphone Market