
 Automotive Digital Mapping Market | 2026-2036
Automotive Digital Mapping Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Mapping Market Outlook
Fleet operators is bifurcating from traditional OEM-centric procurement as logistics companies demand real-time route optimization layers. HERE Technologies dominates European HD map coverage through its Open Location Platform. NVIDIA Corporation leverages GPU-accelerated mapping pipelines to anchor autonomous driving development. TomTom International specializes in cloud-based navigation services for embedded automotive systems.
Automotive digital mapping comprises geospatial data acquisition, processing, and visualization systems that render road geometry, lane-level detail, and dynamic traffic conditions with centimeter-scale accuracy for machine-readable navigation. These systems fuse LiDAR point clouds, computer vision outputs, and AI-based mapping algorithms to enable safe path planning in autonomous vehicles. HD Maps command premium positioning due to their sensor-fusion complexity and safety-critical validation requirements, while Cloud-Based Mapping grows fastest as over-the-air update cycles compress from quarterly to weekly intervals. GPS Navigation retains volume leadership in aftermarket and entry-vehicle segments where hardware cost constraints persist.
FCC spectrum allocations for C-V2X communication shape how US-based providers structure real-time data exchange protocols. EASA and NHTSA calibration standards for automated driving systems enforce rigorous geospatial accuracy thresholds that filter market access. China's SAMR and MIIT jointly administer map data security reviews, creating compliance barriers for foreign cloud-based mapping services. Stakeholders must weigh sovereign data requirements against cross-border platform economics when selecting regional deployment architectures.
Market Dynamics
Over-the-air update cycles compressing from quarterly to weekly intervals are forcing HD map providers to rearchitect cloud infrastructure and validation pipelines around real-time sensor fusion workflows.
Growth Catalysts
- Autonomous driving programs:OEM procurement of centimeter-accurate lane geometry accelerates as Level 3 systems approach commercial deployment in Germany and California.
- MIIT data localization mandate:China's connected-vehicle regulations require domestic cloud storage, accelerating investment in sovereign mapping infrastructure.
- LiDAR cost curves:Solid-state sensor prices falling below automotive-grade thresholds enable fleet-scale HD map data collection by logistics operators.
Market Restraints
- Geospatial accuracy validation:EASA and NHTSA calibration standards for automated driving enforce multi-million-kilometer verification regimes that extend development timelines.
- Input cost concentration:High-precision GPS correction services and satellite imagery licensing concentrate pricing power with a handful of aerospace data providers.
- Substitution by vision-only systems:Tesla and Comma.ai demonstrate end-to-end neural navigation reducing reliance on pre-mapped road geometry in certain operating domains.
Strategic Opportunities
- Indian logistics corridors:Underpenetrated commercial fleet telematics create whitespace for real-time route optimization layers on national highway networks.
- EU AI Act compliance tooling:Automated driving system traceability requirements open markets for map data provenance and algorithmic auditing services.
- Edge-cloud convergence:5G-V2X roadside units enabling distributed map tile processing at intersection-level granularity reduce backhaul bandwidth requirements.
Industry Challenges
- Sensor fusion engineering talent:Scarcity of specialists combining point cloud processing, SLAM algorithms, and safety-critical software validation constrains team scaling.
- Cross-border data governance:SAMR security review timelines for foreign cloud-based mapping services create deployment uncertainty for multi-national platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Mapping Market |
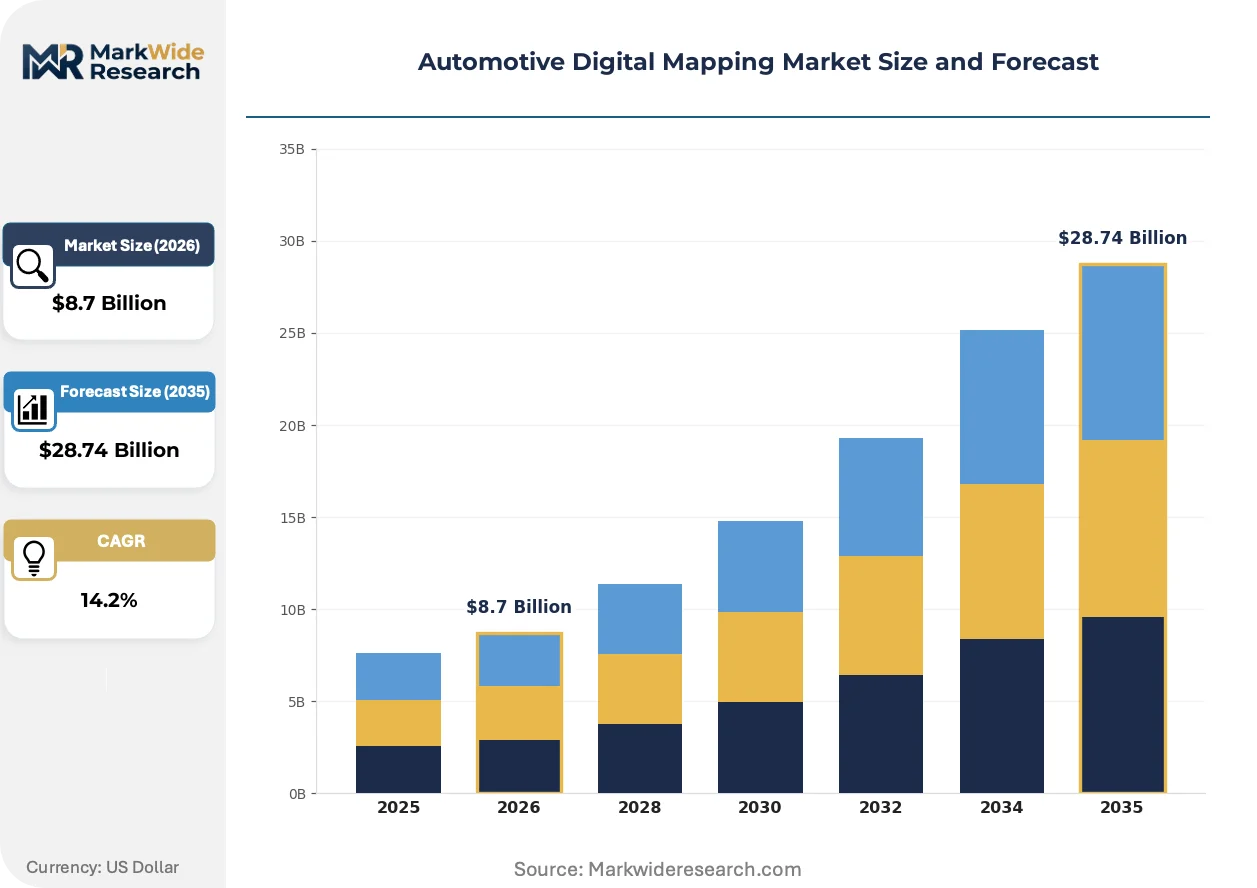
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Maps, GPS Navigation, HD Maps, Cloud-Based Mapping Technology: LiDAR, Computer Vision, AI-Based Mapping, Geospatial Data End User: OEMs, Fleet Operators, Telematics Providers, Logistics Companies Application: Autonomous Driving, Vehicle Navigation, Traffic Management, Route Optimization |
| Companies Covered | TomTom International, Baidu Inc., Google LLC, Denso Corporation, Continental AG, Apple Inc., Mapbox Inc., NVIDIA Corporation, HERE Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Mapping Market Strategic Shifts
Sensor fusion architectures and sovereign data frameworks are actively restructuring how geospatial intelligence moves from collection vehicles to embedded automotive systems. Three developments dominate competitive positioning.
HD map production is bifurcating between centralized cloud pipelines and distributed edge-processing nodes. Tier 1 suppliers adopt hybrid architectures where raw LiDAR point clouds undergo initial feature extraction onboard collection vehicles before transmission. This compression reduces cellular data costs by an order of magnitude while preserving centimeter-level lane boundary fidelity. The structural consequence is displacing pure-play cloud mapping vendors in favor of hardware-software integrated platforms.
REACH and F-Gas Regulation compliance requirements are extending to automotive sensor manufacturing, affecting LiDAR emitter materials and thermal management components. European map data providers now audit supplier chemical declarations upstream of hardware procurement. German KBA type-approval processes incorporate environmental material passports, lengthening qualification cycles for non-EU component sources.
Fleet operators now contract directly with mapping API providers, bypassing traditional OEM bundled navigation systems. Logistics companies in the US and Germany negotiate standalone real-time traffic and road condition subscriptions. This channel disintermediation compresses pricing power for embedded system integrators while expanding addressable market for cloud-native location platforms.
Automotive Digital Mapping Market Segmentation
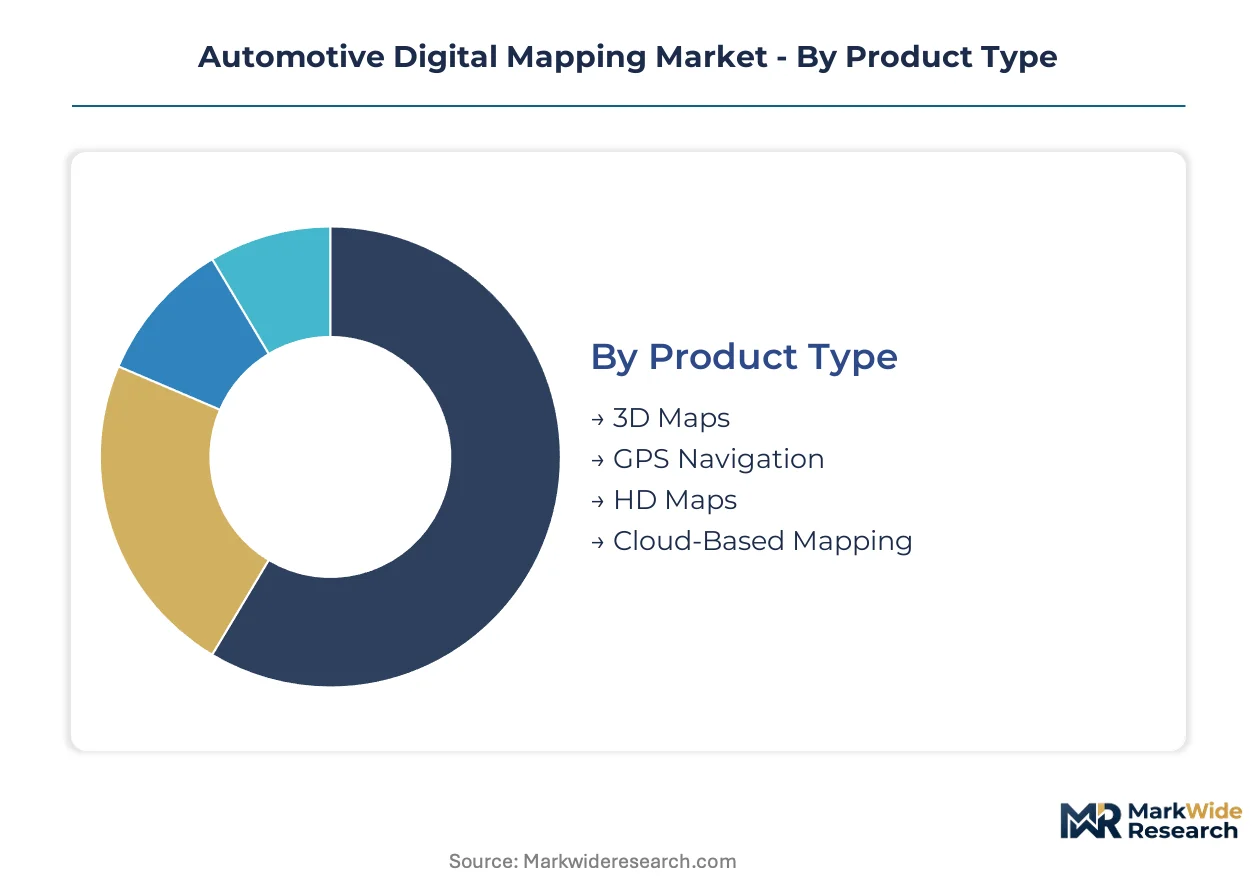
Segmentation in automotive digital mapping reflects divergent technical requirements across safety-critical autonomous systems and cost-sensitive aftermarket navigation. Regulatory frameworks from NHTSA, EASA, and China's MIIT impose distinct validation thresholds that reshape how providers prioritize product development and geographic deployment.
Product Type:
EASA and NHTSA calibration standards for automated driving systems enforce divergent accuracy thresholds that filter which product types gain type-approval in each jurisdiction.
- HD Maps:Centimeter-scale lane geometry fused from LiDAR point clouds and computer vision outputs. German KBA type-approval requirements for Level 3 systems concentrate procurement with precision geospatial suppliers capable of multi-million-kilometer validation regimes.
- Cloud-Based Mapping:Dynamic map tiles delivered via over-the-air protocols with update cycles compressing toward weekly intervals. China's MIIT data localization mandate accelerates domestic infrastructure investment while creating compliance barriers for foreign platform architectures.
- 3D Maps:Elevation-aware road geometry supporting advanced driver assistance visualization layers.
- GPS Navigation:Volume positioning in aftermarket and entry-vehicle segments where hardware cost constraints persist.
Established volume favors GPS Navigation; emerging adoption favors Cloud-Based Mapping.
Technology:
Cost tier differentiation separates premium sensor-fusion stacks from software-only positioning alternatives.
- LiDAR:Solid-state emitter arrays generating dense point clouds for lane-level feature extraction. Solid-state sensor prices falling below automotive-grade thresholds enable fleet-scale HD map data collection by logistics operators in Germany and California.
- AI-Based Mapping:Neural architectures processing raw sensor streams into machine-readable road topology. Tesla and Comma.ai demonstrate end-to-end navigation reducing reliance on pre-mapped geometry in certain operating domains.
- Computer Vision:Camera-derived feature detection for lane marking and traffic sign classification.
- Geospatial Data:Satellite imagery and GPS correction services licensed from aerospace data providers.
Input cost concentration sits with Geospatial Data; capability scarcity constrains AI-Based Mapping deployment timelines.
End User:
Procurement patterns bifurcate between bundled OEM supply agreements and direct fleet operator contracting.
- Fleet Operators:Logistics companies negotiating standalone real-time traffic and road condition subscriptions. US and German freight carriers now bypass traditional OEM navigation bundles to contract directly with mapping API providers.
- OEMs:Integrated cockpit system procurement spanning embedded hardware and software validation. Level 3 autonomous driving programs in Germany and California accelerate centimeter-accurate lane geometry procurement.
- Telematics Providers:White-label location services for insurance and usage-based pricing applications.
- Logistics Companies:Route optimization layer demand concentrated on Indian national highway corridors with underpenetrated commercial fleet telematics.
Channel disintermediation compresses OEM pricing power; direct contracting expands addressable market for cloud-native platforms.
Application:
Safety-critical validation requirements stratify applications by functional safety integrity level.
- Autonomous Driving:Path planning systems requiring ISO 26262 ASIL-D compliance and EASA/NHTSA geospatial accuracy verification. Multi-million-kilometer validation regimes extend development timelines while filtering market access.
- Route Optimization:Real-time traffic integration for commercial freight efficiency. 5G-V2X roadside units enabling distributed map tile processing at intersection-level granularity reduce backhaul bandwidth requirements.
- Vehicle Navigation:Turn-by-turn guidance systems with quarterly update cycles in embedded architectures.
- Traffic Management:Municipal and highway authority systems for congestion monitoring and signal optimization.
Regulatory stringency peaks at Autonomous Driving; update frequency demands climb fastest in Route Optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision geospatial validation services to California's autonomous driving test corridors, creating a transatlantic trade flow in HD map certification expertise. This bilateral exchange shapes procurement patterns for Level 3 system deployments.
United States
NHTSA calibration standards for automated driving systems filter market access through multi-million-kilometer validation requirements. FCC spectrum allocations for C-V2X communication structure real-time data exchange protocols for domestic providers. California's Bay Area concentrates autonomous vehicle testing fleets demanding centimeter-accurate lane geometry updates.
Germany
KBA type-approval requirements for Level 3 automated driving systems concentrate procurement with precision geospatial suppliers. REACH and F-Gas Regulation compliance extends to automotive sensor manufacturing, affecting LiDAR component qualification. Stuttgart and Munich anchor OEM engineering centers expanding HD map procurement for production vehicle programs.
China
MIIT mandates connected-vehicle data localization, accelerating domestic cloud-based mapping infrastructure investment. SAMR and MIIT jointly administer map data security reviews, creating compliance barriers for foreign platform architectures. Beijing and Shanghai host sovereign mapping data centers serving domestic autonomous driving programs.
Japan
METI programs support high-definition mapping for automated highway systems and urban mobility corridors. JIS standards govern geospatial data interoperability for automotive embedded systems. Nagoya's automotive manufacturing cluster integrates precision mapping into production vehicle navigation systems.
India
Underpenetrated commercial fleet telematics on national highway networks create whitespace for real-time route optimization layers. BIS standards for automotive electronics provide regulatory scaffolding for navigation system certification. Maharashtra and Gujarat logistics corridors attract direct contracting between freight operators and mapping API providers.
Automotive Digital Mapping Market Competitive Environment
Listed leaders compete with private specialists across cloud infrastructure and sensor-fusion capabilities, creating a tiered market structure. Consolidation concentrates around integrated hardware-software platforms capable of real-time validation pipelines. Three archetypes dominate: sovereign cloud providers with data localization compliance, GPU-accelerated platform vendors, and open-location platform operators with European coverage density. Competitive moves center on strategic partnerships for C-V2X protocol integration and backward integration into solid-state LiDAR component sourcing.
Within the sovereign cloud tier, Baidu Inc. exemplifies compliance-driven architecture for China's MIIT localization mandates. Among GPU-accelerated platform vendors, NVIDIA Corporation occupies a position anchoring autonomous driving development pipelines. On the open-location vector, HERE Technologies represents European HD map coverage density through platform-based licensing models. These three entities illustrate how geographic regulatory requirements reshape competitive positioning across cloud-native and embedded system domains.
| Leading Market Players |
|---|
| TomTom International |
| Baidu Inc. |
| Google LLC |
| Denso Corporation |
| Continental AG |
| Apple Inc. |
| Mapbox Inc. |
| NVIDIA Corporation |
| HERE Technologies |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with aerospace imagery providers lock in both supply access and price visibility for HD map producers, compressing margin flexibility while securing multi-year satellite correction service availability against spot-market volatility in Germany and California.
Pricing Analysis
Current-generation solid-state LiDAR pricing sits at a 40-60% premium over prior-generation mechanical units, while next-generation chip-scale photonic sensors promise further cost compression. Three-tier pricing structure across premium HD maps, standard cloud-based tiles, and economy GPS navigation bundles dominates procurement. Price differentiation rests on EASA/NHTSA certification grade and update frequency commitments. Cost compression in the standard tier is intensifying because logistics operators now negotiate direct API subscriptions bypassing OEM markups. Fleet operators exhibit highest price sensitivity; autonomous driving program procurement teams prioritize validation rigor over unit cost.
Supply Chain Analysis
High-precision GPS correction service licensing concentrates supply power with a handful of aerospace data providers, creating a chokepoint that Tier 1 map vendors cannot easily circumvent. Component sourcing draws from Germany for LiDAR emitter assemblies, Taiwan for photonic chip fabrication, and the United States for satellite imagery licensing. Raw material dependencies span indium phosphide wafers, automotive-grade thermal management substrates, and rare-earth magnet components for solid-state beam steering. Single-source vulnerability in photonic integrated circuit foundry capacity exposes providers to allocation risk during demand surges. Distribution runs through OEM embedded system integrators, direct fleet API licensing, and aftermarket navigation hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous driving commercialization represents a high-growth disruption as Level 3 systems approach regulatory approval in Germany and California, compressing development timelines and validating centimeter-accuracy procurement at scale.
For Market Incumbents: Secure validation pipeline capacity ahead of KBA and NHTSA type-approval waves by expanding multi-million-kilometer test fleets in Stuttgart and Munich engineering corridors. Deepen backward integration into solid-state LiDAR component sourcing to displace pure-play cloud vendors. Channel control through exclusive OEM bundled navigation agreements faces erosion from direct fleet contracting; incumbents must capture logistics operator API relationships before cloud-native platforms consolidate this whitespace. For New Entrants and Emerging Players: Differentiate on sovereign data compliance architectures for China's MIIT localization mandates, where foreign platform barriers create protected domestic market access. Indian national highway corridors offer the most penetrable geography for real-time route optimization layers given underpenetrated commercial fleet telematics. A go-to-market angle through 5G-V2X roadside unit partnerships enables distributed edge-processing capabilities that reduce cellular backhaul costs for price-sensitive freight operators. For Investors and Strategic Acquirers: Capital is best deployed toward GPU-accelerated platform vendors with autonomous driving development anchor relationships, as these entities capture recurring pipeline revenue across OEM program cycles. Long-term viability across the projection horizon hinges on validation infrastructure ownership rather than pure software licensing. The signal to watch is SAMR security review timeline compression for foreign cloud architectures, which would signal either opening or hardening of China's sovereign mapping market.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Buildout | MIIT data localization mandates in Beijing and Shanghai require domestic data center capacity for market access. |
| LiDAR Component Backward Integration | Solid-state sensor cost curves enable fleet-scale HD map collection by logistics operators in Germany. |
| 5G-V2X Roadside Unit Partnership | FCC spectrum allocations structure real-time data exchange protocols for distributed edge processing. |
| Autonomous Driving Validation Pipeline Expansion | EASA and NHTSA calibration standards enforce multi-million-kilometer verification regimes filtering market access. |
| Direct Fleet API Licensing Platform | Logistics operators in the US and Germany now bypass OEM bundles to contract mapping services directly. |
Study Parameters
The analysis maps HD map production pipelines, cloud-based mapping service architectures, and embedded navigation system supply chains, each validated through primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers, and autonomous driving program directors. Secondary sources include vehicle production databases, IHS Markit registration data, FCC spectrum allocation filings, and EASA/NHTSA regulatory guidance documents. Bottom-up segment sizing triangulates against top-down market aggregation across technology and end-use dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. The analytical framework models segmentation by map product type, sensor technology tier, end-user procurement pattern, and application safety-criticality, with regional production cluster overlays. CAGRs derive from installed base growth curves, content-per-vehicle trajectories, and update frequency compression trends. Industry-specific forecast inputs span LiDAR cost curve trajectories and C-V2X deployment timelines.
The analysis sits within stated boundaries; outcomes outside current regulatory approval trajectories for Level 3 systems would require recalibration. Forecasts reflect documented assumptions regarding autonomous driving commercialization pace and sovereign data framework evolution. Practitioners should keep alternative scenarios live as EASA/NHTSA calibration standard revisions and SAMR security review timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Shared Mobility Market