
 China Data Center Physical Security Market | 2026-2036
China Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Physical Security Market Insights
The capability gap between integrated platform providers and component specialists is redrawing competitive boundaries in China's data center security sector. Honeywell International Inc. leverages its building-automation heritage to bundle environmental and physical security for hyperscale campuses. Hangzhou Hikvision Digital Technology Co., Ltd. anchors its position through deep domestic manufacturing scale and AI-enhanced video analytics tuned for local deployment conditions. Bosch Sicherheitssysteme GmbH competes on European-engineered reliability credentials that appeal to multinational tenants operating within China.
China data center physical security encompasses the integrated hardware, software, and procedural systems that restrict unauthorized physical access to server halls, cooling plants, and power infrastructure, typically operating across perimeter-to-rack protection layers with response thresholds measured in sub-second detection latency. The primary purpose is safeguarding compute continuity and data sovereignty compliance for facilities governed by China's Cybersecurity Law and classified protection requirements. Access control systems and surveillance cameras together occupy the dominant share of product-type revenue, reflecting their status as baseline procurement items in every new facility build. Video analytics within the technology dimension is expanding fastest, driven by facial recognition integration and behavior-analysis algorithms that reduce guard-count requirements. Cloud-based security architectures are gaining traction among colocation operators seeking centralized oversight across dispersed regional sites.
MIIT enforces energy-efficiency and facility-grade standards that indirectly mandate physical security tiering, while GB 50174 specifies access-control zoning and surveillance coverage for A-grade data centers. SAMR oversees product certification and quality compliance for security equipment sold into critical infrastructure. Stakeholders must monitor how China's evolving data-localization rules and dual carbon goals will reshape capital allocation between new construction and retrofit security upgrades across provincial hub clusters.
Market Dynamics
Hyperscale cloud operators in eastern China are consolidating procurement power, forcing security vendors to bundle environmental monitoring with physical access systems under unified platform contracts rather than selling discrete components.
Growth Catalysts
- MIIT energy-efficiency mandates:Facility-grade classifications now require tiered physical security zoning, compelling A-grade data centers to upgrade perimeter-to-rack protection layers.
- Facial recognition integration:AI-enhanced video analytics reduce guard-count requirements while accelerating incident response latency for hyperscale campuses.
- Yangtze River Delta cluster expansion:Concentrated facility construction across Shanghai, Jiangsu, and Zhejiang generates synchronized procurement waves for integrated security platforms.
Market Restraints
- Domestic component concentration:Reliance on local manufacturing for surveillance cameras and access controllers creates supply vulnerability during regional logistics disruptions.
- GB 50174 compliance costs:Stringent access-control zoning specifications inflate engineering and installation expenses for retrofit projects.
- Silicon input volatility:Semiconductor price fluctuations directly impact video analytics server and edge device production economics.
Strategic Opportunities
- Western provincial hub development:Chengdu-Chongqing and Guizhou data center clusters remain underpenetrated for cloud-based security architectures.
- Dual carbon policy alignment:SAMR certification pathways for low-power surveillance equipment open preferential procurement channels for energy-efficient vendors.
- Colocation operator consolidation:Centralized oversight platforms enable multi-site security management across dispersed regional facilities.
Industry Challenges
- AI model training expertise:Shortage of computer vision engineers delays deployment of behavior-analysis algorithms for threat detection.
- Legacy analog integration:Hybrid environments complicate retrofit timelines as facilities bridge coaxial camera networks with IP-based analytics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Physical Security Market |
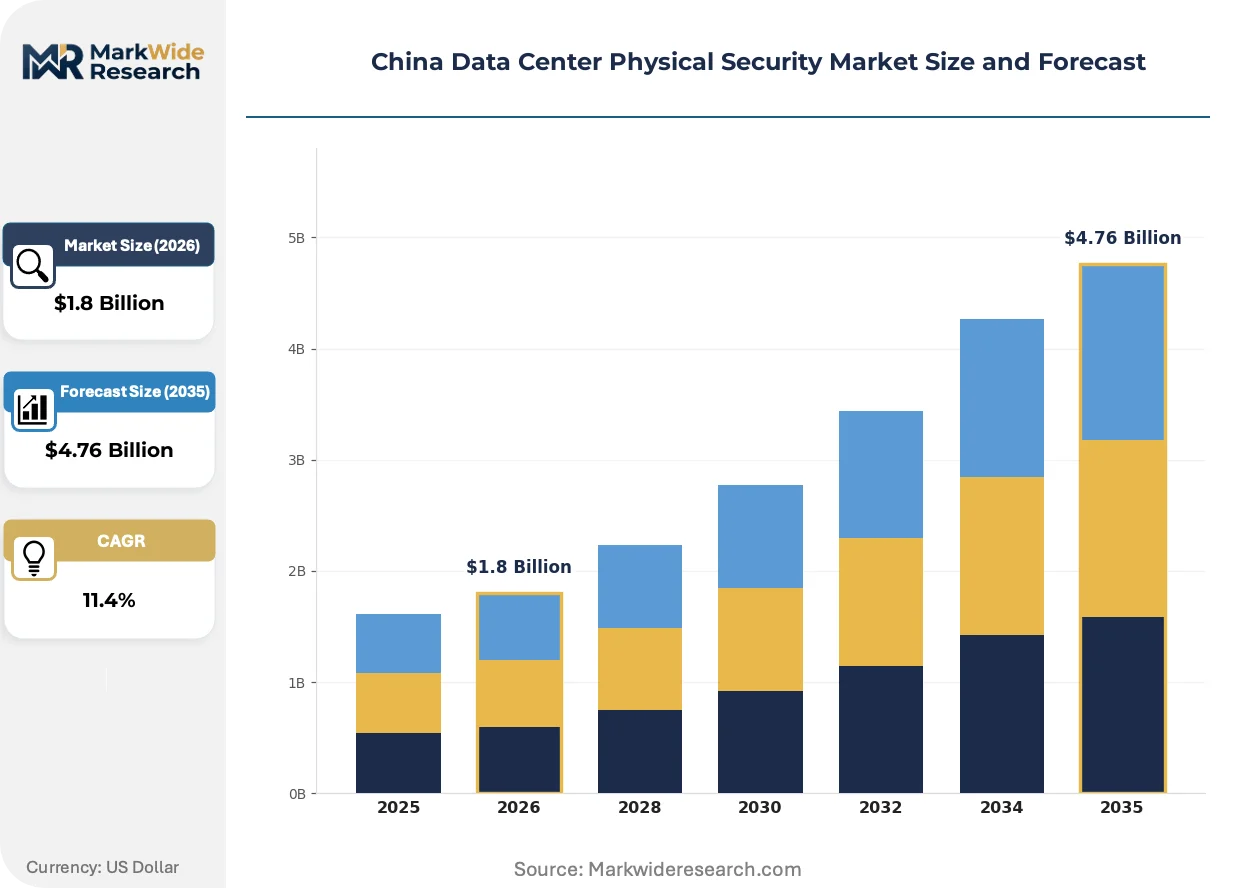
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control Systems, Surveillance Cameras, Intrusion Detection Systems, Perimeter Security Technology: Biometric Authentication, Video Analytics, RFID Systems, Cloud-Based Security End User: Telecommunications, BFSI, Government, Healthcare Installation: On-Premises, Managed Services, Hybrid Solutions, Remote Monitoring |
| Companies Covered | Honeywell International Inc., Bosch Sicherheitssysteme GmbH, Hangzhou Hikvision Digital Technology Co., Ltd., Schneider Electric SE, ABB Ltd, Zhejiang Dahua Technology Co., Ltd., Johnson Controls, Siemens AG, Axis Communications AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Physical Security Market Trends and Innovations
Edge-based video processing is compressing detection-to-response latency while reshaping how security architectures balance centralized cloud oversight with localized decision autonomy.
Biometric multi-factor authentication systems are supplanting card-based access control in hyperscale facilities. Cloud operators in Jiangsu and Zhejiang have mandated palm-vein and facial recognition for server hall entry. This technology is supplanting traditional credential management by eliminating card cloning risks and reducing tailgating incidents through liveness detection.
GB 50174-2017 amendments are tightening surveillance coverage density requirements for A-grade facilities. The industrial consequence is expanded procurement of 4K-resolution cameras with low-light performance specifications. Colocation operators in Shanghai are responding by pre-wiring higher cable conduit capacity to accommodate future sensor density upgrades.
Security-as-a-service contracting is displacing capital-intensive equipment purchases among mid-tier colocation providers. Subscription models bundle hardware refresh cycles with remote monitoring labor, transferring obsolescence risk to vendors. This pattern concentrates in Zhejiang province where facility operators prioritize operational expenditure predictability over asset ownership.
China Data Center Physical Security Market Segmentation
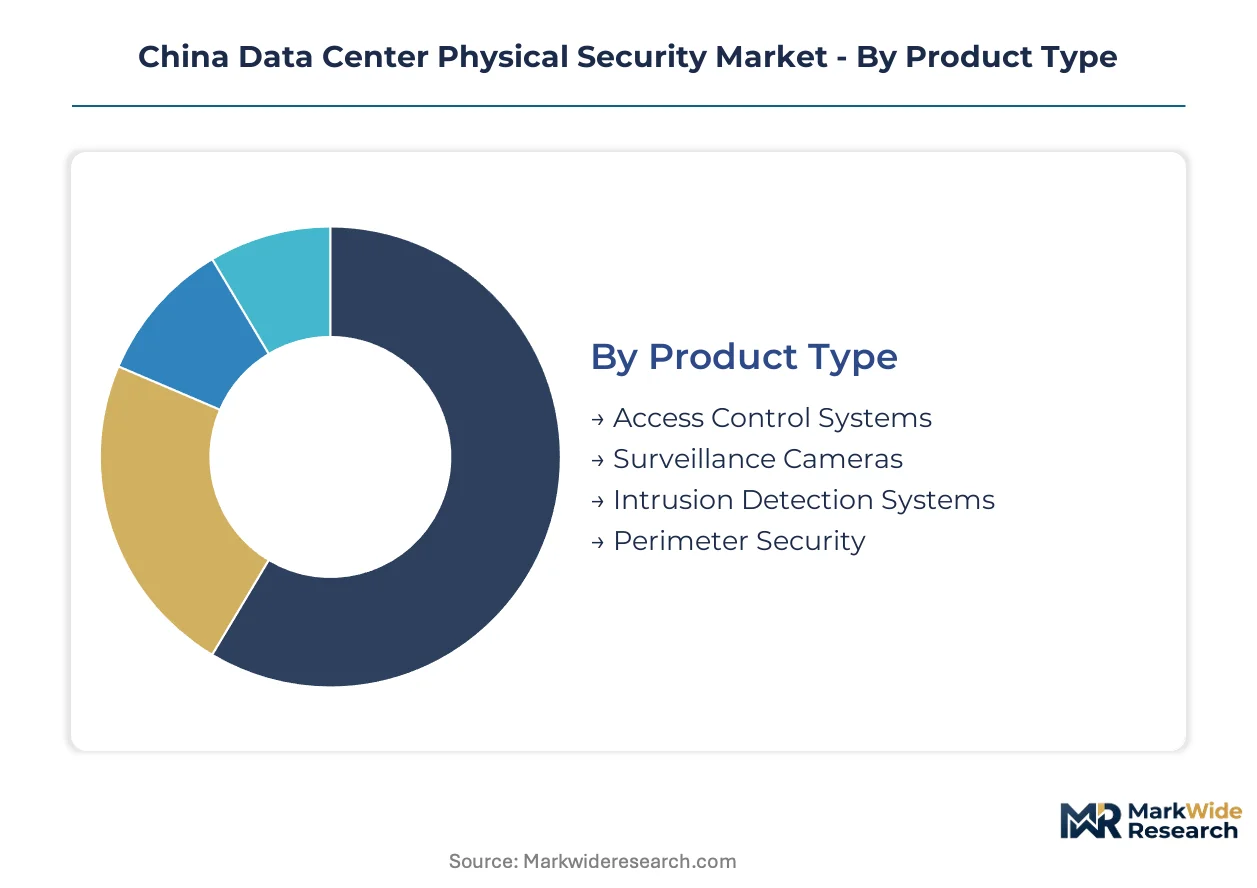
China data center physical security procurement follows tiered compliance pathways where GB 50174 facility grades dictate minimum product specifications. Segmentation reveals how MIIT mandates concentrate demand in integrated platforms while cost pressures sustain component-level markets.
Product Type:
MIIT facility-grade classifications mandate tiered security zoning that directly shapes procurement volume across hardware categories.
- Access Control Systems:Electromechanical credential readers, biometric terminals, and server rack-level locks form the perimeter-to-rack protection backbone. Hyperscale campuses in Jiangsu province mandate palm-vein authentication for server hall entry, eliminating card cloning vulnerabilities while reducing guard deployment.
- Surveillance Cameras:Fixed and PTZ camera networks with 4K resolution and low-light specifications satisfy GB 50174-2017 coverage density requirements. Shanghai colocation operators pre-wire elevated conduit capacity to accommodate future sensor density upgrades mandated for A-grade recertification.
- Intrusion Detection Systems:Volumetric and beam sensors monitor unmanned zones between perimeter fences and facility envelopes.
- Perimeter Security:Bollards, fencing, and crash-rated barriers protect against vehicle-borne threats at hyperscale campus boundaries.
Established volume favors Surveillance Cameras; emerging adoption favors Access Control Systems.
Technology:
Cost tier differentiation separates capital-intensive biometric deployments from subscription-based cloud architectures.
- Biometric Authentication:Palm-vein, facial recognition, and iris scanning systems eliminate credential transfer risks. Zhejiang cloud operators mandate multi-factor biometric entry for all personnel accessing critical infrastructure zones.
- Video Analytics:AI-enhanced behavior detection algorithms reduce false alarm rates while compressing incident response latency. Yangtze River Delta facilities deploy edge-based processing to balance centralized oversight with localized decision autonomy.
- RFID Systems:Legacy contactless credentialing persists in retrofit environments bridging analog and IP infrastructure.
- Cloud-Based Security:Subscription architectures transfer obsolescence risk to vendors while enabling multi-site oversight.
Capital deployment concentrates in Biometric Authentication; operational expenditure migration favors Cloud-Based Security.
End User:
Customer type determines compliance stringency and procurement scale across vertical applications.
- Telecommunications:State-owned carriers operate hyperscale facilities requiring perimeter-to-rack protection with sovereign data compliance. Jiangsu and Zhejiang carrier campuses drive synchronized procurement waves for integrated security platforms.
- BFSI:Financial institutions mandate transaction-grade audit trails and dual-custody access protocols for core banking infrastructure. Shanghai banking clusters prioritize biometric multi-factor systems with immutable logging capabilities.
- Government:Classified protection requirements under China's Cybersecurity Law dictate air-gapped access control with domestic component sourcing.
- Healthcare:Medical data sovereignty rules impose patient-record isolation with role-based physical access restrictions.
Volume concentration sits with Telecommunications; compliance complexity peaks in Government.
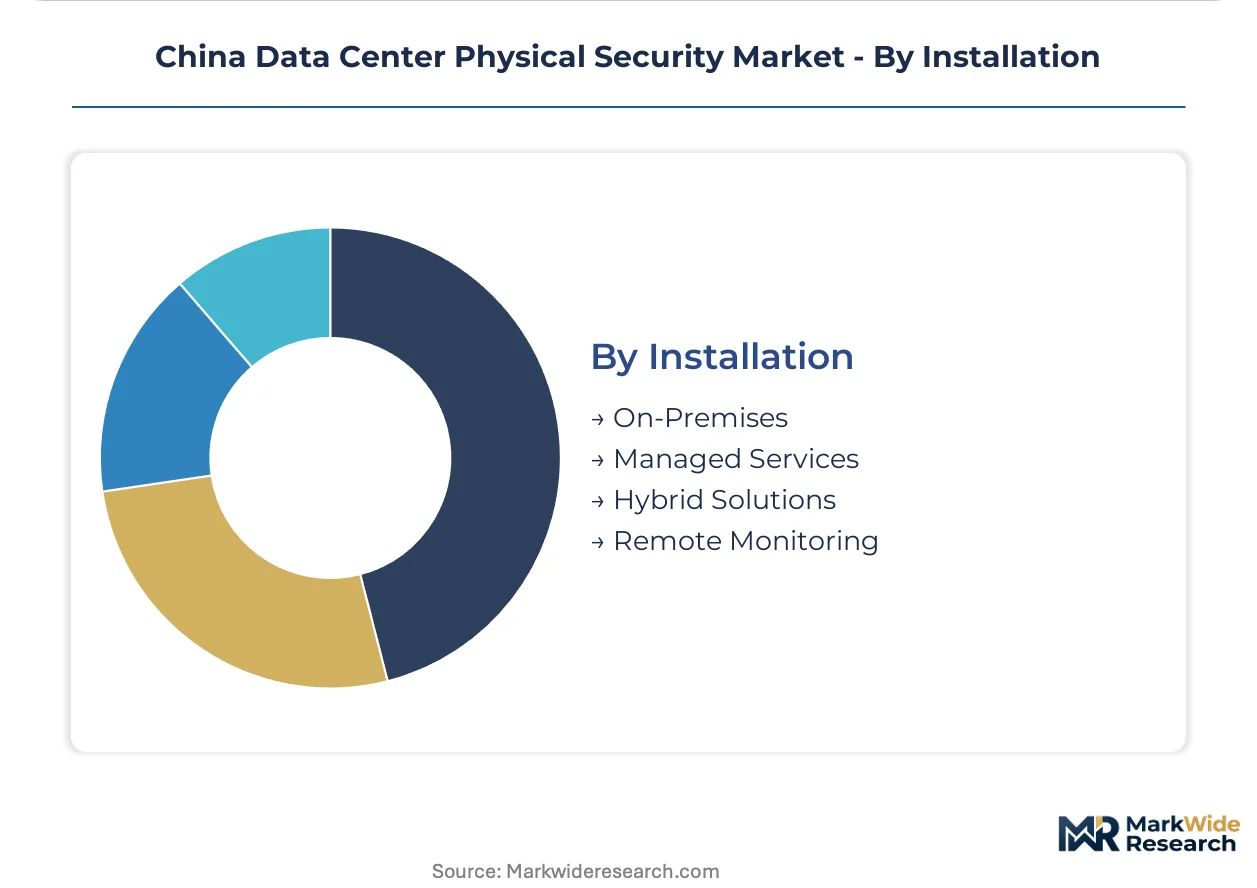
Installation:
Margin structure separates asset-heavy on-premises deployment from recurring-revenue service models.
- On-Premises:Capital-intensive equipment ownership with internal maintenance staffing dominates state-owned carrier procurement. Eastern province hyperscale operators retain direct control over security architecture to satisfy data sovereignty audit requirements.
- Managed Services:Vendor-operated monitoring and response centers reduce internal security staffing for mid-tier colocation providers. Zhejiang facilities increasingly outsource tier-one alarm verification to specialized security operations centers.
- Hybrid Solutions:Mixed ownership models combine on-site hardware with cloud-based management platforms.
- Remote Monitoring:Centralized oversight of dispersed regional sites enables multi-facility security coordination.
Asset ownership dominates On-Premises; service migration accelerates in Managed Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastern coastal provinces command pricing premiums for integrated security platforms while western inland markets absorb cost-sensitive component procurement. This asymmetry reflects divergent facility-grade requirements and hyperscale operator concentration patterns across China's data center geography.
Yangtze River Delta
Hyperscale cloud operators drive synchronized procurement waves for unified security platforms across Shanghai, Jiangsu, and Zhejiang. MIIT energy-efficiency mandates compel A-grade facility recertification with tiered physical access zoning. Shanghai colocation operators pre-wire elevated conduit capacity to accommodate future sensor density upgrades.
Pearl River Delta
Shenzhen and Guangzhou financial services clusters demand biometric multi-factor systems with immutable audit logging for core banking infrastructure. GB 50174-2017 amendments tighten surveillance coverage density specifications for A-grade recertification. Guangdong province hosts manufacturing scale for low-light 4K camera modules serving regional retrofit projects.
Beijing-Tianjin-Hebei
Government and state-owned carrier facilities concentrate procurement for air-gapped access control with domestic component sourcing mandates. China's Cybersecurity Law classified protection requirements dictate sovereign data compliance architecture. Beijing municipal clusters prioritize palm-vein authentication for personnel accessing critical infrastructure zones.
Sichuan-Chongqing
Chengdu-Chongqing data center clusters remain underpenetrated for cloud-based security architectures relative to eastern benchmarks. Western provincial hub development incentives attract colocation operators seeking centralized oversight platforms across dispersed regional sites. Chongqing facilities increasingly outsource tier-one alarm verification to specialized security operations centers.
Guizhou
Big data pilot zone designation concentrates government and telecom carrier procurement for perimeter-to-rack protection systems. Dual carbon policy alignment creates preferential procurement channels for SAMR-certified low-power surveillance equipment. Guiyang-Anshun corridor generates demand for subscription-based security-as-a-service models among mid-tier facility operators.
China Data Center Physical Security Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across China's data center physical security sector. The vendor base separates into integrated platform providers bundling environmental and access systems versus component specialists dominating discrete hardware procurement. Three archetypes define competitive positioning: multinational building-automation conglomerates, domestic AI-video manufacturers, and European-engineered reliability specialists. Consolidation pressure intensifies as hyperscale operators mandate unified platform contracts over discrete component sales, while strategic partnerships between cloud operators and security vendors reshape procurement channel structures.
Within the multinational tier, Honeywell International Inc. and Bosch Sicherheitssysteme GmbH represent building-automation heritage positioning for bundled campus-wide deployments. Among domestic manufacturers, Hangzhou Hikvision Digital Technology Co., Ltd. anchors manufacturing scale advantages for AI-enhanced video analytics tuned to local deployment conditions. These three exemplify how competitive boundaries redraw around integrated platform capabilities versus component cost efficiency.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Bosch Sicherheitssysteme GmbH |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Schneider Electric SE |
| ABB Ltd |
| Zhejiang Dahua Technology Co., Ltd. |
| Johnson Controls |
| Siemens AG |
| Axis Communications AB |
| Others |
Pricing and Supply Chain Analysis
Hyperscale procurement consolidation in Jiangsu and Zhejiang compresses margin structures for discrete component vendors while elevating platform-level pricing power for integrated providers. Scale economies in domestic camera manufacturing anchor price floors for surveillance hardware, whereas biometric authentication systems command customization premiums due to limited engineering capacity for palm-vein algorithm tuning.
Pricing Analysis
Configured-to-order biometric platforms carry 40-60 percent premiums over standard access control catalogs. Project-based contracting dominates hyperscale campus deployments, with pricing stratifying across A-grade certification tiers, volume scale, and after-sales service bundling. Cost compression in mid-tier colocation segments intensifies as subscription-based security-as-a-service models displace capital purchases. State-owned telecommunications carriers exhibit lowest price sensitivity due to sovereign compliance mandates; mid-tier Zhejiang colocation operators demonstrate highest sensitivity, prioritizing operational expenditure predictability.
Supply Chain Analysis
China anchors global production of surveillance cameras and access control hardware, while Taiwan and South Korea supply critical image sensors and edge processing chipsets. Domestic manufacturing draws from CMOS sensor wafers, precision electromechanical components, and AI training compute clusters. Single-source vulnerability concentrates in advanced semiconductor inputs subject to export control friction. Distribution runs through direct hyperscale procurement channels and regional systems integrators serving colocation retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering scarcity for computer vision specialists and edge-AI deployment expertise constrains vendor capacity to meet synchronized procurement waves from Yangtze River Delta hyperscale operators.
For Market Incumbents: Consolidate platform capabilities by acquiring niche biometric algorithm developers and expanding Jiangsu-based technical service teams. Defend against domestic AI-video manufacturers by deepening backward integration into edge hardware design. Prioritize SAMR certification investment for low-power surveillance equipment to capture dual carbon policy procurement preferences. For New Entrants and Emerging Players: Cloud-native security operations center services represent the most penetrable white-space where incumbents under-serve mid-tier colocation operators. Target Sichuan-Chongqing clusters with subscription-based remote monitoring offerings. Establish go-to-market partnerships with regional systems integrators possessing existing facility maintenance relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated platform providers over component specialists across the analysis window. Long-term viability hinges on AI model training infrastructure and sovereign compliance architecture. Acquisition target archetype: domestic engineering teams with GB 50174 certification expertise and hyperscale deployment track records. Monitor MIIT facility-grade recertification timelines as demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified environmental and physical security bundles satisfy hyperscale procurement consolidation in Jiangsu province. |
| Biometric Algorithm Acquisition | Palm-vein and facial recognition capabilities eliminate card-cloning vulnerabilities for A-grade facilities. |
| SAMR Certification Investment | Low-power surveillance credentials unlock preferential procurement channels under dual carbon policy alignment. |
| Western Hub Geographic Expansion | Chengdu-Chongqing cluster development captures underpenetrated demand for cloud-based security architectures. |
| Security-as-a-Service Launch | Subscription models transfer obsolescence risk to vendors while serving Zhejiang colocation operational expenditure preferences. |
Research Methodology
A spread of perspectives from hyperscale facility engineering directors, security systems integrators, MIIT policy researchers, and colocation operator procurement managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against GB standard documentation, SAMR certification registries, and provincial data center development filings. Bottom-up equipment procurement estimates triangulated against top-down facility construction pipeline assessments.
Segmentation dimensions modeled include product type hierarchy, technology deployment tier, end-user compliance stringency, and installation service model across the projection horizon. CAGRs derived from facility-grade classification trajectories and hyperscale operator capex disclosure patterns. Industry-specific forecast inputs encompass MIIT energy-efficiency mandate enforcement timelines and GB 50174 amendment adoption curves.
Forecasts assume regulatory continuity in MIIT facility-grade standards and SAMR certification pathways; material policy shifts would require re-modeling. Semiconductor input availability and logistics disruption scenarios represent specific revision triggers. Recalibration cycles align with material shifts in hyperscale procurement consolidation patterns and provincial hub development incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
US Data Center Construction Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
Connected Distribution Center Market