
 GCC Cigarette Market | 2026-2036
GCC Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Cigarette Market Intelligence
Duty-free retail channels across Gulf airports is tilting toward premium and luxury brand portfolios as passenger volumes recover and transit hubs expand commercial space. Philip Morris International leverages heat-not-burn technology leadership to diversify beyond combustibles in Saudi Arabia and the UAE. British American Tobacco sustains its regional manufacturing footprint through localized production facilities that supply multiple GCC markets. Japan Tobacco Inc. competes on menthol and capsule variants tailored to Gulf consumer preferences.
A cigarette is a cylindrical roll of cured and cut tobacco leaf encased in paper, typically containing additives for flavor, burn rate control, and moisture retention, with a standard length of 70 to 100 millimeters and tar yields regulated under national health standards. Its primary commercial purpose is recreational nicotine delivery through combustion inhalation. Filter cigarettes anchor the largest revenue pool across the GCC given their established production infrastructure and consumer familiarity, while menthol cigarettes capture disproportionate margin in younger demographics despite tightening flavor restrictions. Brand positioning stratifies sharply: premium and luxury tiers concentrate in duty-free and high-end retail in Dubai and Riyadh, whereas budget brands dominate volume through convenience store channels in secondary Saudi cities.
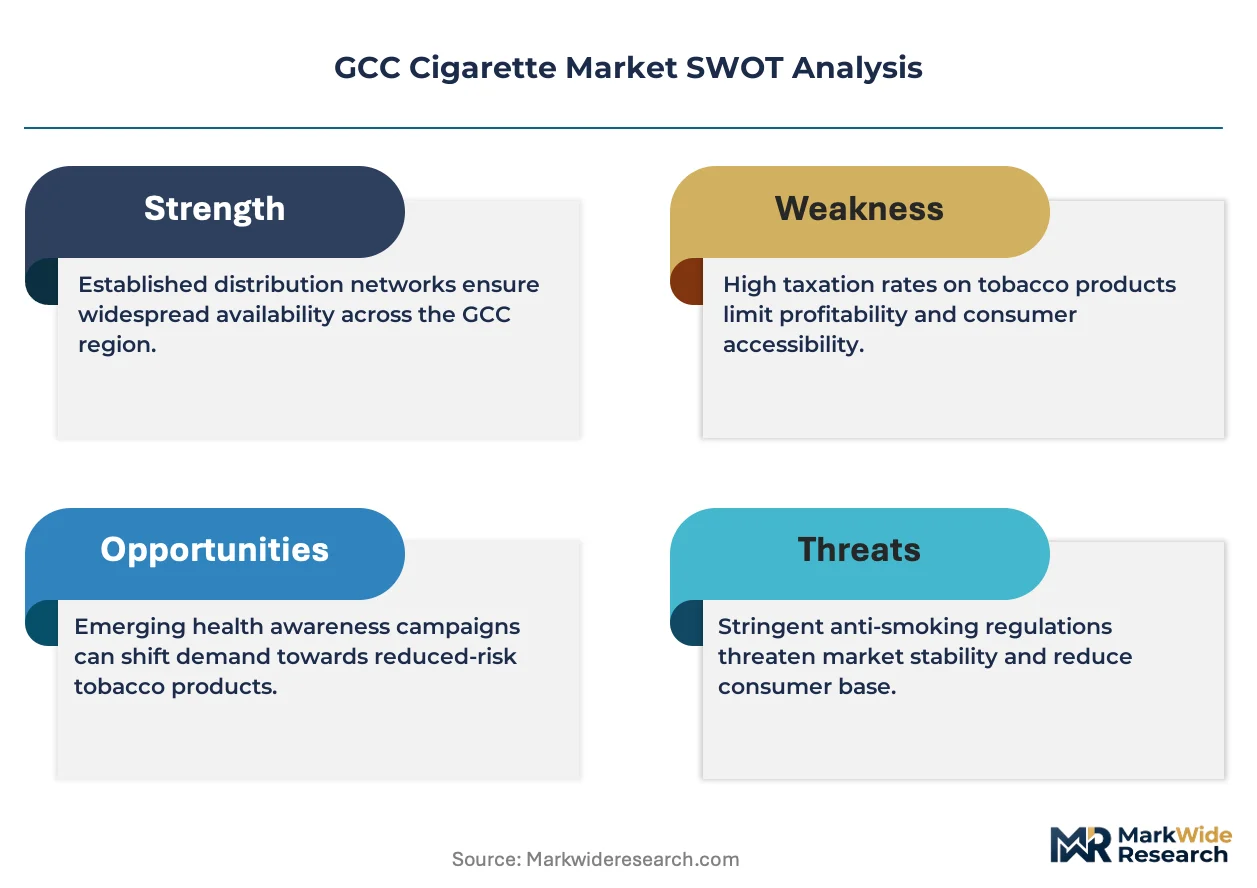
Saudi Arabia's General Authority for Food and Drug Administration and the UAE's Ministry of Health and Prevention enforce tobacco packaging standards, excise tax tiers, and advertising prohibitions that compress marketing flexibility and elevate compliance costs. The Gulf Standardization Organization coordinates technical specifications across member states, creating partial harmonization but leaving national discretion on taxation and public consumption bans. Stakeholders must monitor excise escalation trajectories and emerging heat-not-burn regulatory classifications to calibrate portfolio transitions and manufacturing investments.
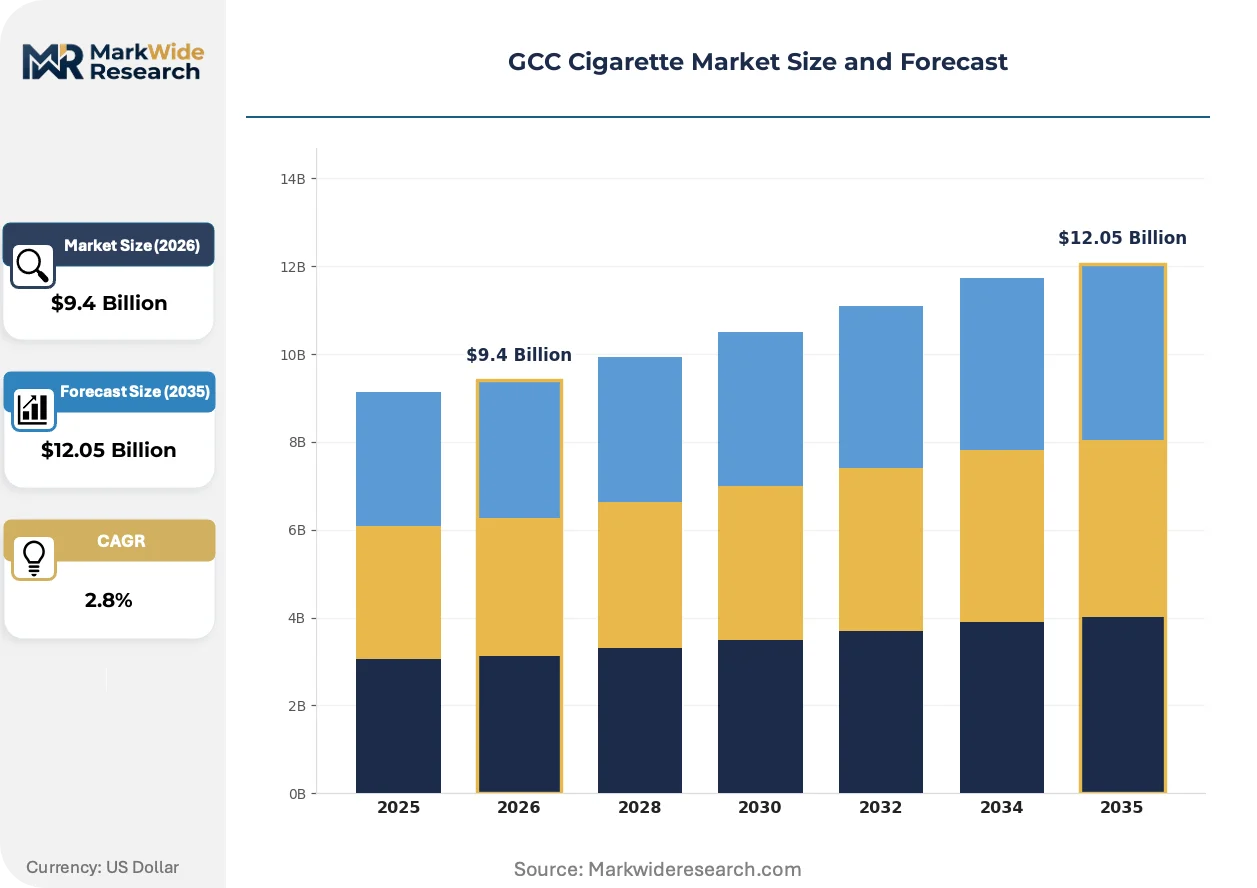
Market Dynamics
Heat-not-burn technology adoption in Saudi Arabia and the UAE is fragmenting traditional combustible demand while regulatory compression on flavor additives and packaging visibility forces portfolio restructuring across Gulf markets.
Growth Catalysts
- SFDA packaging mandates:Saudi Arabia's standardized plain-packaging requirements accelerate brand consolidation toward established multinational portfolios with compliance infrastructure.
- Young adult consumption patterns:Demographic expansion in Riyadh and Jeddah sustains volume flows for menthol and capsule variants despite flavor restrictions tightening elsewhere.
- Heat-not-burn infrastructure:Device ecosystem investments across Dubai and Abu Dhabi duty-free channels create alternative revenue streams beyond traditional cigarette combustion.
Market Restraints
- Excise tax escalation:The UAE's tiered tobacco excise framework compresses margin structures and elevates working capital requirements for inventory holding.
- Raw material concentration:Filter tow and acetate supply dependence on Asian chemical producers exposes GCC manufacturers to freight cost volatility and currency fluctuation.
- Substitution acceleration:Nicotine pouches and oral tobacco products capture switching consumers in Bahrain and Qatar where enforcement gaps persist.
Strategic Opportunities
- Underpenetrated Oman:Lower excise burdens and limited heat-not-burn distribution create white space for premium combustible brand establishment.
- Regulatory tailwind from MOHAP:The UAE's emerging classification framework for reduced-risk products may permit differentiated marketing claims for heat-not-burn relative to combustibles.
- Duty-free channel expansion:Passenger volume recovery at Dubai International and King Abdulaziz International creates commercial space for luxury portfolio positioning.
Industry Challenges
- Compliance talent scarcity:Gulf Standardization Organization technical specification expertise remains concentrated in Riyadh and Dubai, constraining rapid market entry elsewhere.
- Legacy system integration:Track-and-trace serialization requirements for Saudi and Emirati markets force expensive ERP reconfiguration for distributors serving multiple GCC territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Cigarette Market |
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $12.05 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filter Cigarettes, Roll-Your-Own, Cigarillos, Menthol Cigarettes Customer Type: Men, Women, Young Adults, Seniors Brand Positioning: Premium Brands, Mid-Range Brands, Budget Brands, Luxury Brands Distribution Channel: Convenience Stores, Supermarkets, Online Retail, Duty-Free Shops |
| Companies Covered | Imperial Brands, China National Tobacco Corporation, Philip Morris International, ITC Limited, Altria Group, British American Tobacco, KT and G Corporation, Scandinavian Tobacco Group, Japan Tobacco Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Cigarette Market Strategic Shifts & Innovations
Product architecture and distribution mechanics across Gulf markets are diverging as reduced-risk alternatives mature and regulatory granularity tightens on traditional combustibles.
Heat-not-burn devices are hybridizing combustible ritual with electronic temperature control, preserving nicotine delivery while eliminating combustion byproducts. Young adult adopters in Dubai and Riyadh are transitioning at pace from premium filter cigarettes toward device-based systems. This technology convergence is compressing traditional volume growth projections while elevating hardware and consumable bundling requirements.
MOHAP's evolving reduced-risk product classification framework in the UAE is creating regulatory segmentation between heat-not-burn and traditional cigarettes. Industrial consequence includes differentiated shelf positioning and marketing latitude for devices relative to combustibles. Premium retail channels in Abu Dhabi and Dubai are responding by reallocating floor space toward device demonstration zones.
Younger demographics are fragmenting brand loyalty toward capsule and menthol variants despite SFDA flavor additive restrictions tightening in Saudi Arabia. Convenience store channels in secondary Saudi cities are losing share to airport retail and e-commerce platforms where enforcement gaps permit variant availability. This channel rotation is most visible in Jeddah and Dammam where transit hub commercial expansion accelerates.
GCC Cigarette Market Segmentation
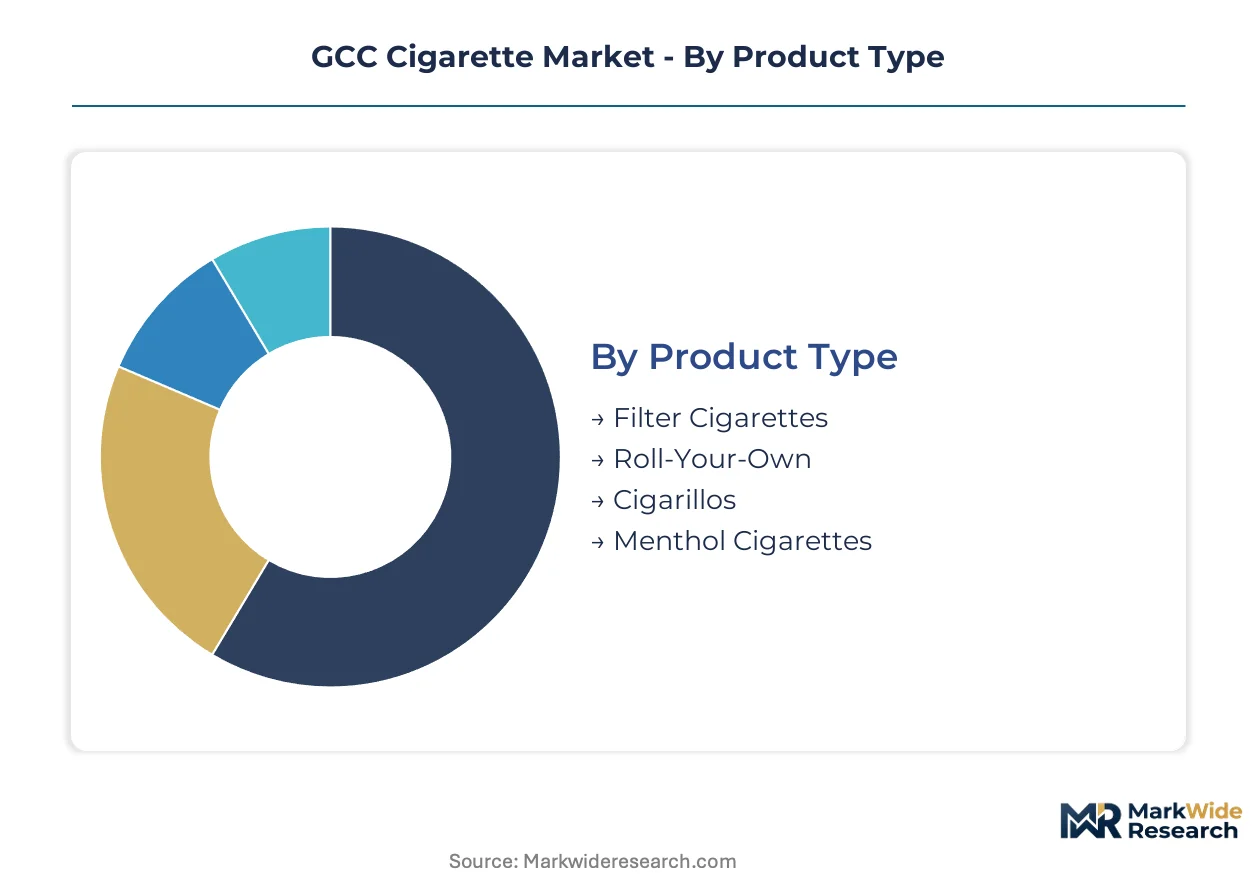
Segmentation reveals how regulatory compression and channel fragmentation are reshaping portfolio allocation across GCC markets. Understanding these divisions exposes where margin pools concentrate and where compliance burdens diverge.
Product Type:
After-sales service intensity varies sharply by product format, with device-dependent categories requiring technical support infrastructure absent from traditional combustibles.
- Filter Cigarettes:Standard cellulose acetate filters dominate manufacturing scale across Saudi and Emirati production facilities. Volume concentrates in Riyadh and Jeddah where established distribution networks serve mass-market demand despite excise escalation compressing per-unit margins.
- Roll-Your-Own:Loose tobacco with separate rolling papers appeals to price-sensitive consumers in Bahrain and Oman where excise differentials against manufactured cigarettes remain narrower. Demand is climbing fastest among budget-conscious segments in secondary GCC cities.
- Cigarillos:Small-format cigars with tobacco leaf wrappers occupy niche positioning in Abu Dhabi and Dubai duty-free channels.
- Menthol Cigarettes:Flavor-capsule variants face tightening SFDA additive restrictions yet sustain loyalty among young adult consumers in Jeddah enforcement gaps.
Filter cigarettes hold the largest share; momentum sits with roll-your-own as excise differentials widen.
Customer Type:
Cost tier stratification drives divergent channel access, with premium spenders concentrating in airport retail while budget buyers populate convenience store networks.
- Men:Traditional core demographic sustaining volume across all GCC territories with established brand loyalty patterns.
- Women:Emerging segment with preference for slimmer formats and lower-tar variants in UAE urban centers.
- Young Adults:Consumers aged 18-30 in Riyadh and Dubai are shifting fastest toward heat-not-burn devices and capsule variants. This cohort commands disproportionate attention from portfolio strategists despite regulatory restrictions on flavor marketing.
- Seniors:Established filter cigarette consumers in Saudi Arabia's secondary cities maintain stable consumption patterns with limited product switching.
Men retain volume dominance; young adults are gaining share fastest as device adoption accelerates.
Brand Positioning:
Margin structure separates sharply across tiers, with luxury and premium categories capturing duty-free price premiums unavailable to budget portfolios.
- Premium Brands:Mid-to-high price positioning with established multinational manufacturing presence. Revenue concentrates in Dubai and Riyadh airport retail where passenger recovery expands commercial space.
- Mid-Range Brands:Volume workhorses serving mainstream demand across Saudi convenience store networks.
- Budget Brands:Price-focused positioning dominates secondary city channels in Oman and Bahrain where excise burdens remain lighter.
- Luxury Brands:Ultra-premium positioning with limited edition releases and heritage marketing. Demand clusters in Abu Dhabi and Dubai duty-free zones where high-net-worth transit passengers sustain price inelasticity.
Premium brands anchor revenue; luxury brands are expanding most quickly as airport retail recovers.
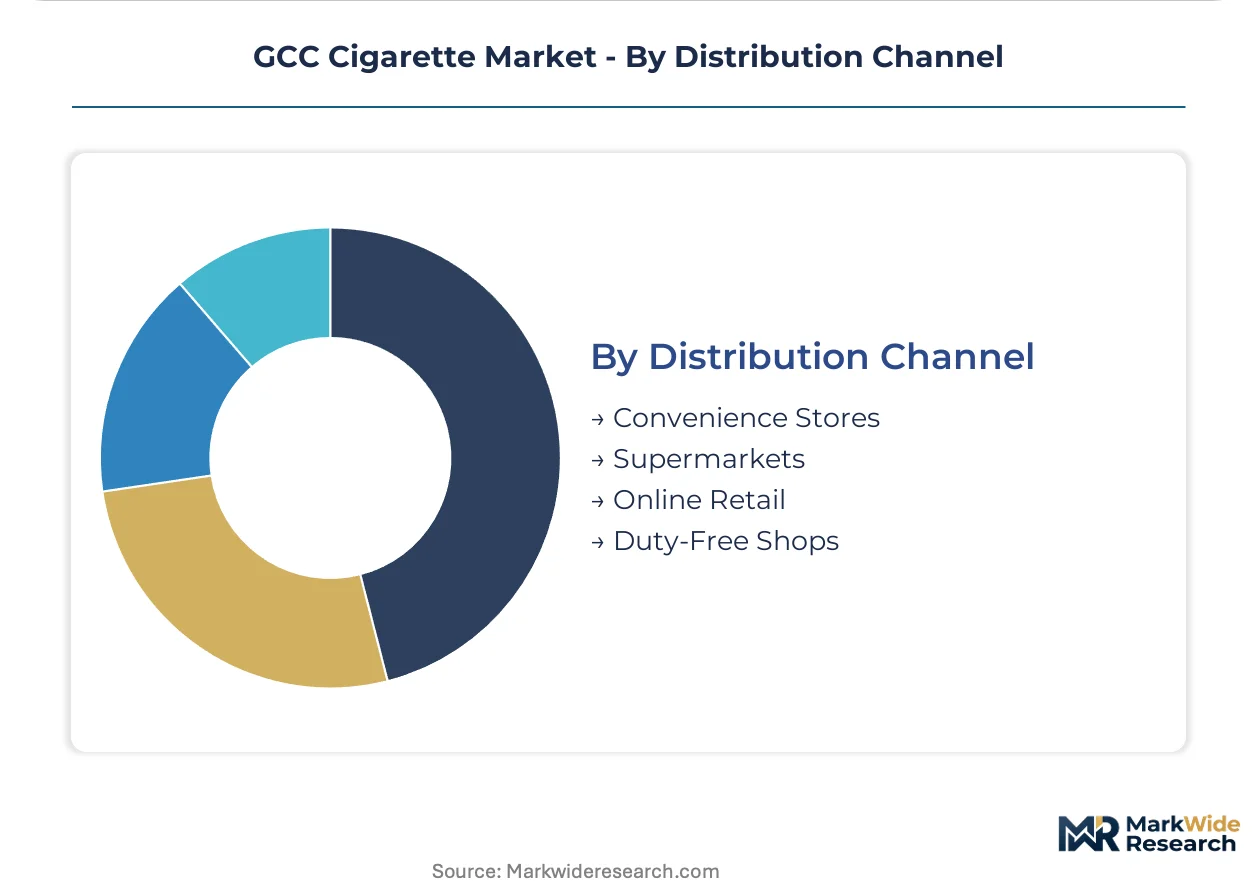
Distribution Channel:
Supply concentration determines competitive access, with duty-free and online channels requiring specialized licensing infrastructure absent from conventional retail.
- Convenience Stores:High-frequency neighborhood outlets dominate volume flows in Saudi Arabia's secondary cities. These channels face margin compression from excise tax accumulation and inventory serialization requirements.
- Supermarkets:Organized retail with standardized shelving and plain-packaging compliance infrastructure. Share is climbing fastest in UAE urban centers as modern trade formats expand.
- Online Retail:E-commerce platforms with age-verification and delivery restrictions. Enforcement gaps permit variant availability unavailable in physical channels.
- Duty-Free Shops:Airport and border retail with tax-advantaged pricing. King Abdulaziz International and Dubai International are reallocating floor space toward premium portfolio demonstration zones.
Convenience stores hold the largest share; duty-free shops are gaining share fastest as passenger volumes recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdulaziz International Airport's commercial expansion anchors Saudi Arabia's position as the Gulf's dominant cigarette distribution hub, connecting Riyadh and Jeddah manufacturing clusters to transit retail networks across the peninsula.
Saudi Arabia
Riyadh and Jeddah sustain the region's largest combustible volume flows as young adult consumers drive menthol and capsule variant demand. SFDA packaging mandates enforce standardized plain-packaging requirements that compress marketing flexibility and elevate compliance costs for distributors. The Eastern Province's Dammam corridor hosts manufacturing facilities supplying multiple GCC territories with filter cigarette production.
United Arab Emirates
Dubai International Airport's duty-free channel recovery reallocates floor space toward premium portfolio demonstration zones as passenger volumes expand. MOHAP's emerging reduced-risk product classification framework creates regulatory segmentation between heat-not-burn devices and traditional cigarettes. Abu Dhabi's retail modernization concentrates organized supermarket expansion with standardized shelving infrastructure.
Oman
Muscat and secondary urban centers present white space for premium combustible brand establishment given lower excise burdens and limited heat-not-burn distribution penetration. The country's national food and drug administration maintains lighter flavor additive enforcement compared to Saudi and Emirati standards. Salalah's port infrastructure supports import-dependent supply chains serving budget-conscious segments.
Qatar
Doha's Hamad International Airport transit hub expansion elevates luxury brand positioning opportunities among high-net-worth passenger flows. The Ministry of Public Health's tobacco control unit enforces advertising prohibitions that constrain traditional marketing channels. Nicotine pouches and oral tobacco products capture switching consumers through enforcement gaps in retail distribution.
Bahrain
Manama's compact retail landscape concentrates convenience store networks serving price-sensitive demand segments with roll-your-own tobacco growth. The National Health Regulatory Authority coordinates with Gulf Standardization Organization technical specifications while retaining national discretion on taxation tiers. Budget brand dominance persists across secondary city channels where excise differentials against manufactured cigarettes remain narrower.
GCC Cigarette Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying filter tow, acetate, and flavor additive inputs. The vendor base stratifies sharply between multinational manufacturers with Gulf production footprints and regional distributors navigating serialization compliance. Three archetypes dominate: heat-not-burn technology leaders diversifying beyond combustibles, established combustible specialists defending volume through localized manufacturing, and reduced-risk product entrants exploiting regulatory classification gaps. Competitive moves concentrate on portfolio diversification toward device ecosystems and strategic partnerships securing duty-free channel access.
Among multinational tobacco conglomerates, Philip Morris International, British American Tobacco, and Japan Tobacco Inc. occupy positions reflecting divergent strategic postures. Philip Morris International exemplifies the heat-not-burn transition archetype through device ecosystem investments across Dubai and Abu Dhabi duty-free channels. British American Tobacco anchors the localized manufacturing archetype with regional production facilities supplying multiple GCC markets from centralized Gulf hubs. Japan Tobacco Inc. represents the variant specialization archetype, competing on menthol and capsule formulations tailored to Gulf consumer preferences despite tightening SFDA additive restrictions.
| Leading Market Players |
|---|
| Imperial Brands |
| China National Tobacco Corporation |
| Philip Morris International |
| ITC Limited |
| Altria Group |
| British American Tobacco |
| KT and G Corporation |
| Scandinavian Tobacco Group |
| Japan Tobacco Inc. |
| Others |
Cost & Logistics Intelligence
Riyadh's manufacturing corridor anchors GCC cigarette production capacity, with scale concentration in Saudi and Emirati facilities translating directly into downstream pricing leverage for multinational portfolios. Filter tow and acetate input costs from Asian chemical producers ripple through finished goods pricing, while excise tax tiering compresses margin structures at the budget end of the spectrum.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates GCC cigarette markets, with brand heritage and duty-free channel access driving differentiation between tiers. Volume-scale discounts favor established multinational portfolios with compliance infrastructure, while young adult consumers in Dubai and Riyadh demonstrate lowest price sensitivity toward heat-not-burn devices. Pricing pressure stems from UAE excise escalation and SFDA packaging mandate compliance costs, which squeeze per-unit margins most severely in convenience store channels serving secondary Saudi cities.
Supply Chain Analysis
Upstream feedstock dependence on Chinese and South Korean acetate and filter tow producers exposes GCC manufacturers to freight cost volatility and currency fluctuation against Gulf currencies. Raw material flows hinge on cellulose acetate, flavor additives, and specialized packaging substrates from concentrated Asian supply bases. Single-source vulnerability in filter component supply creates structural risk, with distribution running through Riyadh and Jeddah manufacturing clusters serving pan-GCC territories via organized retail and duty-free channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC cigarette market fragmentation creates multiple entry niches as heat-not-burn technology adoption splits traditional combustible demand and regulatory classification gaps open differentiated positioning opportunities.
For Market Incumbents: Entrench device ecosystem leadership through Dubai and Abu Dhabi duty-free demonstration zones, while consolidating combustible volume defense via Riyadh manufacturing scale and SFDA compliance infrastructure. Heat-not-burn substitution acceleration and nicotine pouch encroachment in Bahrain and Qatar demand portfolio diversification toward reduced-risk product categories with regulatory tailwind potential. For New Entrants and Emerging Players: Establish a beachhead in Oman's underpenetrated premium combustible segment, where lighter excise burdens and limited heat-not-burn distribution create white space for brand establishment. Target Muscat and secondary urban centers with heritage-positioned portfolios, leveraging Salalah port infrastructure for import-dependent supply chain efficiency and the national food and drug administration's relatively lighter flavor additive enforcement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reduced-risk product specialists with MOHAP classification framework clarity and device ecosystem bundling capabilities over pure combustible volume plays. Long-term viability over the coming decade rests on regulatory navigation capacity and heat-not-burn infrastructure deployment velocity, with the signal to watch being SFDA's stance on reduced-risk product marketing claims relative to combustibles.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-not-Burn Device Ecosystem Expansion | Philip Morris International's Dubai duty-free investments create alternative revenue streams beyond traditional combustion. |
| Localized Manufacturing Footprint Consolidation | British American Tobacco's Riyadh and Jeddah facilities supply multiple GCC markets with filter cigarette production scale. |
| Reduced-Risk Product Classification Navigation | MOHAP's emerging framework permits differentiated shelf positioning and marketing latitude for heat-not-burn relative to combustibles. |
| Premium Portfolio Duty-Free Channel Expansion | Dubai International and King Abdulaziz International passenger recovery reallocates floor space toward luxury brand demonstration zones. |
| Flavor Variant Compliance Infrastructure Investment | Japan Tobacco Inc.'s menthol and capsule specialization requires adaptation to SFDA additive restrictions tightening across Saudi Arabia. |
Research Approach
The analysis maps combustible cigarettes, heat-not-burn devices, roll-your-own tobacco, and nicotine pouches, each validated through manufacturing executives, regulatory affairs specialists, duty-free channel managers, and retail distribution heads. Primary interviews with SFDA compliance officers and MOHAP classification framework administrators combined with secondary validation from Gulf Standardization Organization technical specifications, customs and excise records, and airport retail audit data. Bottom-up volume triangulation across product formats and top-down macroeconomic anchoring ensured convergence.
Assumptions regarding excise tax trajectory stability, heat-not-burn regulatory classification timelines, and passenger volume recovery patterns were held fixed across modeling scenarios while device adoption elasticity and flavor restriction enforcement intensity were varied. Segmentation dimensions included product format, customer demographic cohort, brand positioning tier, and distribution channel type. CAGRs were derived from historical volume trend extrapolation adjusted for structural substitution effects and policy intervention impacts, with filter cigarette volume baselines and heat-not-burn device penetration curves as core forecast inputs.
Stress conditions across excise escalation velocity, raw material freight cost volatility, and reduced-risk product regulatory classification timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding policy continuity and technology adoption S-curve parameters, with specific risk factors including SFDA packaging mandate expansion, MOHAP framework revision, and Asian acetate supply disruption capable of material revision. Cross-checking against Gulf Standardization Organization technical specification updates and national excise policy announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Home Controller Market
Others
South Korea Smart Home Market
Others
Pin Mills Market
Others
Shisha Tobacco Market
Others
Enterprise Video Content Management Market
Others
Global Geotechnical Instrumentation and Monitoring Market
Others
Japan Indoor LBS Market
Others
Latin America Video Conferencing Hardware Market
Others
Europe Transportation Management Systems Market
Others
Rotary Dial Machine Market
Others
Advanced Fiber-Based Gasket Market
Others
LED Packaging Market
Others
North America IT Device Market
Others
United States Smart Homes Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Turbo Mills Market