
 LED Packaging Market | 2026-2036
LED Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
LED Packaging Market Intelligence
The EU Green Deal is expanding efficiency requirements for solid-state lighting across member states, pushing OEMs toward higher-performance package architectures. Nichia Corporation leverages its phosphor expertise to sustain premium positioning in high-CRI segments. ams-OSRAM AG anchors European supply chains through captive epitaxy capacity and automotive qualification pathways. Seoul Semiconductor Co. Ltd. competes on patent-protected WICOP technology, differentiating against conventional flip-chip designs in display backlighting.
LED packaging encloses semiconductor dies in thermally conductive housings with optical elements, typically operating at junction temperatures below 150°C to preserve lumen maintenance and color stability. The process integrates die attach, wire bonding or flip-chip interconnection, phosphor deposition, and lens molding to extract and shape light for end-use applications. Surface Mount Device formats dominate general illumination volumes due to compatibility with automated PCB assembly and retrofit lamp form factors. Chip-on-Board architectures capture margin pools in high-lumen-density applications such as stadium lighting and horticultural fixtures where thermal management determines product lifespan. Quantum Dot LED technology is gaining traction in display technology segments where color gamut specifications exceed conventional phosphor capabilities.
REACH restrictions on hazardous substances and RoHS substance limits constrain solder alloys and phosphor chemistries available to European manufacturers. Ecodesign requirements under EU regulations mandate minimum efficacy thresholds and product disassembly provisions that reshape package material selection. The US EPA ENERGY STAR program and California Title 20 standards create bifurcated compliance obligations for suppliers serving transatlantic demand. Stakeholders must monitor regulatory convergence between EU and Asian efficiency benchmarks to anticipate harmonization costs or certification fragmentation.
Market Dynamics
Automotive electrification is compressing LED packaging qualification timelines as OEMs demand AEC-Q101-compliant modules for headlamp arrays and cabin illumination systems. Thermal interface materials and ceramic substrates face renewed specification pressure from Tier 1 suppliers racing to secure 2027-2028 vehicle platform slots.
Growth Catalysts
- China dual carbon goals:GB standards for energy efficiency are tightening lumen-per-watt thresholds, forcing domestic packaging houses to upgrade phosphor deposition and thermal management capabilities.
- EV interior lighting:Cabin ambient systems require multi-zone addressable LED arrays, expanding die-count-per-vehicle and driving demand for compact multi-chip packages.
- Chip-on-Board thermal density:Horticultural and stadium applications above 500W equivalent lumen output favor direct-mount architectures that bypass conventional SMT limitations.
Market Restraints
- Epitaxial wafer concentration:Sapphire and silicon carbide substrate supply clusters in East Asian foundries, exposing packaging houses to single-source disruption risk during substrate allocation cycles.
- Phosphor rare earth dependency:Cerium-doped yttrium aluminum garnet and nitride red phosphors rely on Chinese rare earth processing, creating input cost volatility beyond packaging house control.
- RoHS substance limits:REACH restrictions constrain high-lead solder alloys and certain phosphor activators, forcing reformulation of established package chemistries with unproven field reliability data.
Strategic Opportunities
- Quantum Dot color conversion:Display manufacturers in South Korea and Taiwan are qualifying Cd-free QDEF films for premium monitor and television backlighting, opening phosphor-independent margin pools.
- Micro-LED transfer integration:Packaging houses with precision pick-and-place and laser lift-off capabilities can capture value from display panel makers struggling with mass transfer yield rates.
- EU Ecodesign disassembly mandates:Modular package designs with separable optical and thermal subassemblies align with circular economy requirements and command premium positioning in European retrofit channels.
Industry Challenges
- Thermal simulation talent scarcity:Junction temperature modeling for multi-die arrays requires combined expertise in computational fluid dynamics and optoelectronic device physics that packaging houses struggle to recruit.
- AEC-Q101 certification timelines:Automotive qualification cycles spanning 18-24 months misalign with EV platform development acceleration, forcing packaging houses to pre-validate designs before firm volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Packaging Market |
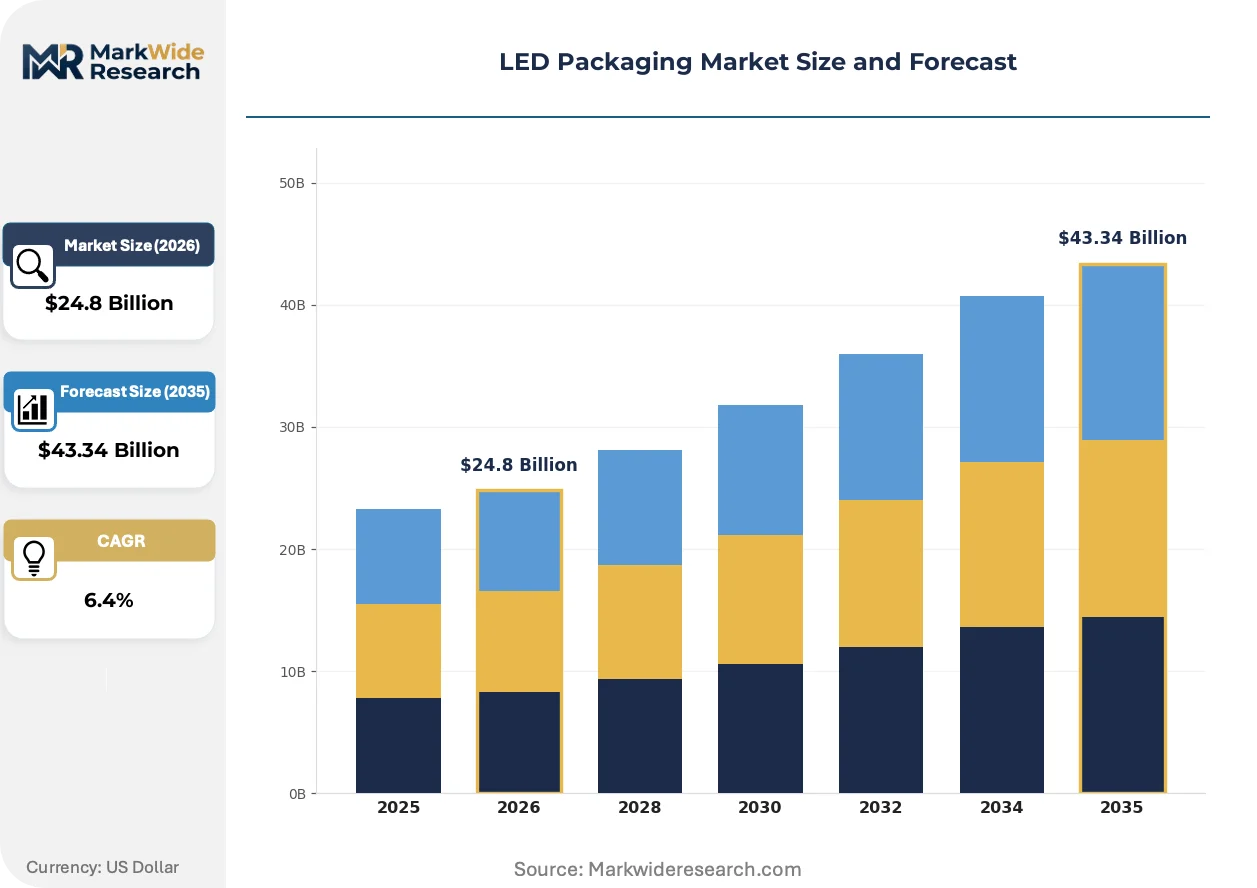
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chip-on-Board, Surface Mount Device, Dual In-line Package, Ceramic Package Technology: Organic LED, Quantum Dot LED, MicroLED, Hybrid LED Application: Display Technology, Automotive Lighting, General Illumination, Signage End User: Consumer Electronics, Automotive, Retail, Industrial |
| Companies Covered | Nichia Corporation, ams-OSRAM AG, Lumileds Holding B.V., Seoul Semiconductor Co. Ltd., Samsung Electronics Co. Ltd, LG INNOTEK, Everlight Electronics Co. Ltd., Citizen Electronics Co. Ltd., MLS Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Packaging Market Strategic Shifts & Innovations
Materials science and thermal engineering are converging to redefine package performance ceilings. Three developments are compressing traditional design trade-offs between lumen density, color stability, and operating lifespan.
Flip-chip on ceramic substrates is electrifying high-power general illumination by eliminating wire bond thermal resistance and enabling double-sided thermal extraction. Commercial builders and industrial facility managers in Germany and Japan are specifying these modules for 100,000-hour maintenance-free installations. The technology is compressing market share for conventional plastic leaded chip carrier formats in outdoor and high-bay applications.
The EU Green Deal's expanding efficiency requirements are mandating minimum efficacy thresholds and product disassembly provisions that reshape material selection across member states. Packaging houses serving European OEMs must now document phosphor chemistry and solder alloy composition for circular economy compliance. High-CRI segments for museum and retail lighting face the steepest reformulation burden as warm-white phosphor blends fall under renewed substance scrutiny.
Automotive procurement departments are consolidating supplier lists and demanding integrated optical-electrical-thermal subassemblies rather than discrete packaged LEDs. Tier 1 lighting module manufacturers in Michigan and Bavaria are selecting packaging partners based on simulation collaboration capabilities and concurrent engineering support. This consolidation is most visible in adaptive driving beam programs where pixel count and thermal response time determine platform awards.
LED Packaging Market Segmentation
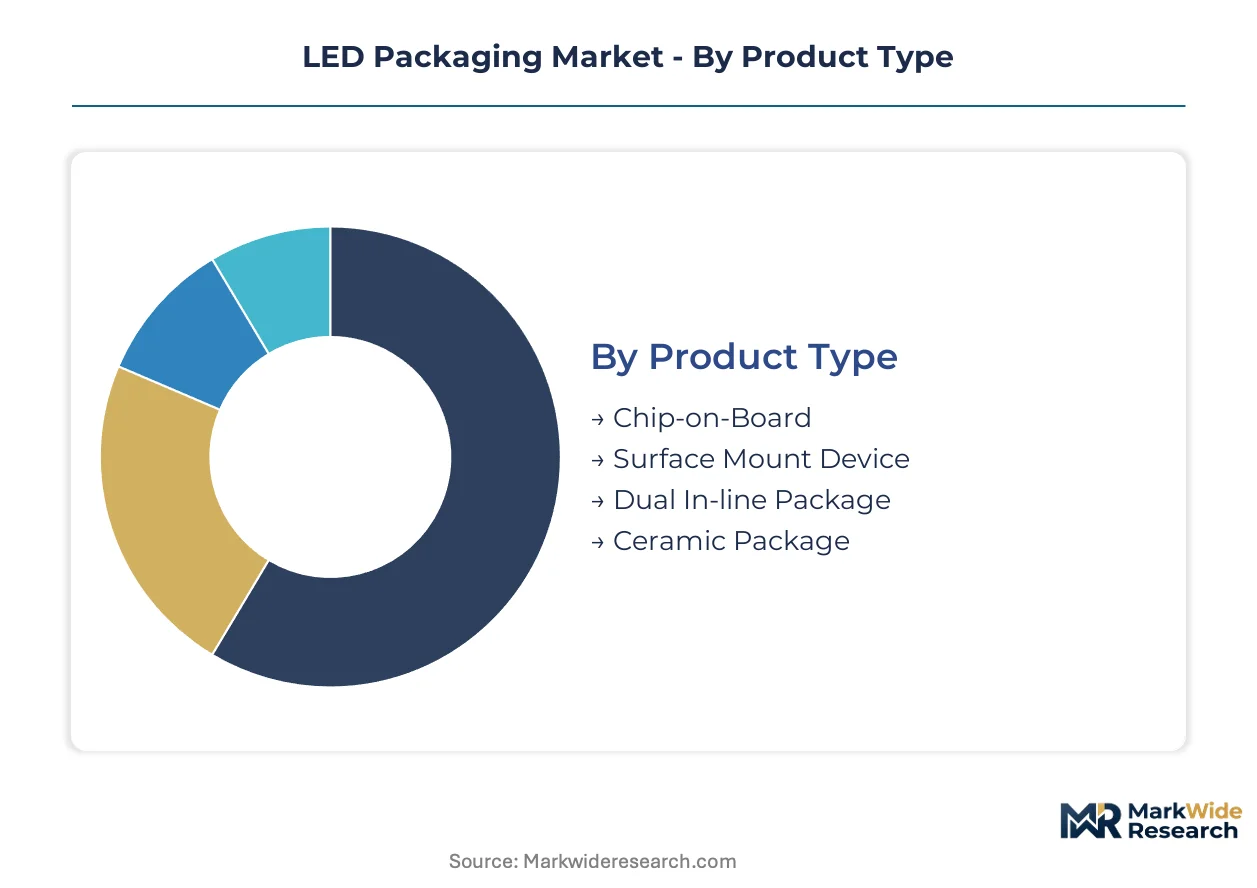
LED packaging architectures diverge sharply across thermal density, optical precision, and qualification burden requirements. Each segment carries distinct certification pathways that determine supplier eligibility and margin capture potential.
Product Type:
Certification intensity varies from self-declared CE marking for standard SMT formats to full AEC-Q101 automotive validation for ceramic substrates in headlamp modules.
- Chip-on-Board:Direct die attachment to metal-core PCBs eliminates wire bond thermal resistance, enabling lumen densities above 500W equivalent. Demand concentrates in German industrial horticulture facilities and Japanese stadium retrofits where maintenance-free 100,000-hour lifespans justify premium positioning. AEC-Q101 compliance remains rare, limiting automotive penetration.
- Surface Mount Device:Plastic leaded chip carrier formats dominate retrofit lamp volumes through compatibility with automated PCB assembly. Chinese GB standard efficiency thresholds are forcing domestic packaging houses to upgrade phosphor deposition precision for lumen-per-watt compliance. CE marking and UL listing satisfy most general illumination channels without tiered automotive burden.
- Dual In-line Package:Legacy through-hole formats persist in signage and indicator applications with minimal thermal management requirements.
- Ceramic Package:Alumina and aluminum nitride substrates enable junction temperatures below 150°C in compact footprints, commanding automotive headlamp slots.
Leading the category by volume: Surface Mount Device. Growing fastest: Chip-on-Board.
Technology:
Cost tiers separate mature phosphor-converted formats from emerging quantum dot and microLED platforms requiring capital-intensive deposition equipment.
- Organic LED:Thin-film encapsulation on flexible substrates enables curved automotive interior panels and wearable displays. South Korean panel makers are qualifying multi-layer barrier films to meet 85°C/85%RH lifetime specifications for automotive cabin integration. Premium pricing reflects yield losses from pinhole defects in thin-film encapsulation.
- Quantum Dot LED:Cadmium-free quantum dot enhancement films exceed NTSC color gamut thresholds for premium monitor and television backlighting. Taiwanese and South Korean display manufacturers are scaling QDEF integration for high-refresh-rate gaming panels where color volume specifications outpace conventional phosphor capabilities. RoHS substance scrutiny on cadmium and indium phosphide alternatives complicates chemistry selection.
- MicroLED:Chip-scale packaging with precision mass transfer enables pixel densities beyond OLED limitations for augmented reality headsets.
- Hybrid LED:Combines quantum dot color conversion with conventional blue pump architectures in cost-optimized display backlighting.
Volume leadership: Organic LED. Steepest expansion trajectory: Quantum Dot LED.
Application:
Customer type determines specification intensity, with automotive OEMs imposing concurrent engineering requirements absent in retail and signage channels.
- Display Technology:Color uniformity specifications below 3 MacAdam ellipses demand phosphor deposition control at micron-scale tolerances. Backlighting for premium monitors and televisions in Taiwan and South Korea drives demand for quantum dot and miniLED array formats where local dimming zones exceed 1,000 segments.
- Automotive Lighting:Adaptive driving beam arrays require pixel-level addressability with thermal response times below 10 milliseconds. Tier 1 suppliers in Michigan and Bavaria are consolidating supplier lists around packaging houses with simulation collaboration capabilities and AEC-Q101 pre-validation.
- General Illumination:Commercial and industrial retrofit volumes concentrate on efficacy-maximizing SMT formats with ENERGY STAR and EU Ecodesign compliance.
- Signage:Channel letter and billboard applications prioritize lumen-per-dollar over color stability, accepting wider binning tolerances.
Fastest-growing application: Automotive Lighting. Largest volume base: General Illumination.
End User:
Supply concentration differs across customer types, with automotive procurement consolidating to captive-tier relationships while consumer electronics maintains fragmented vendor pools.
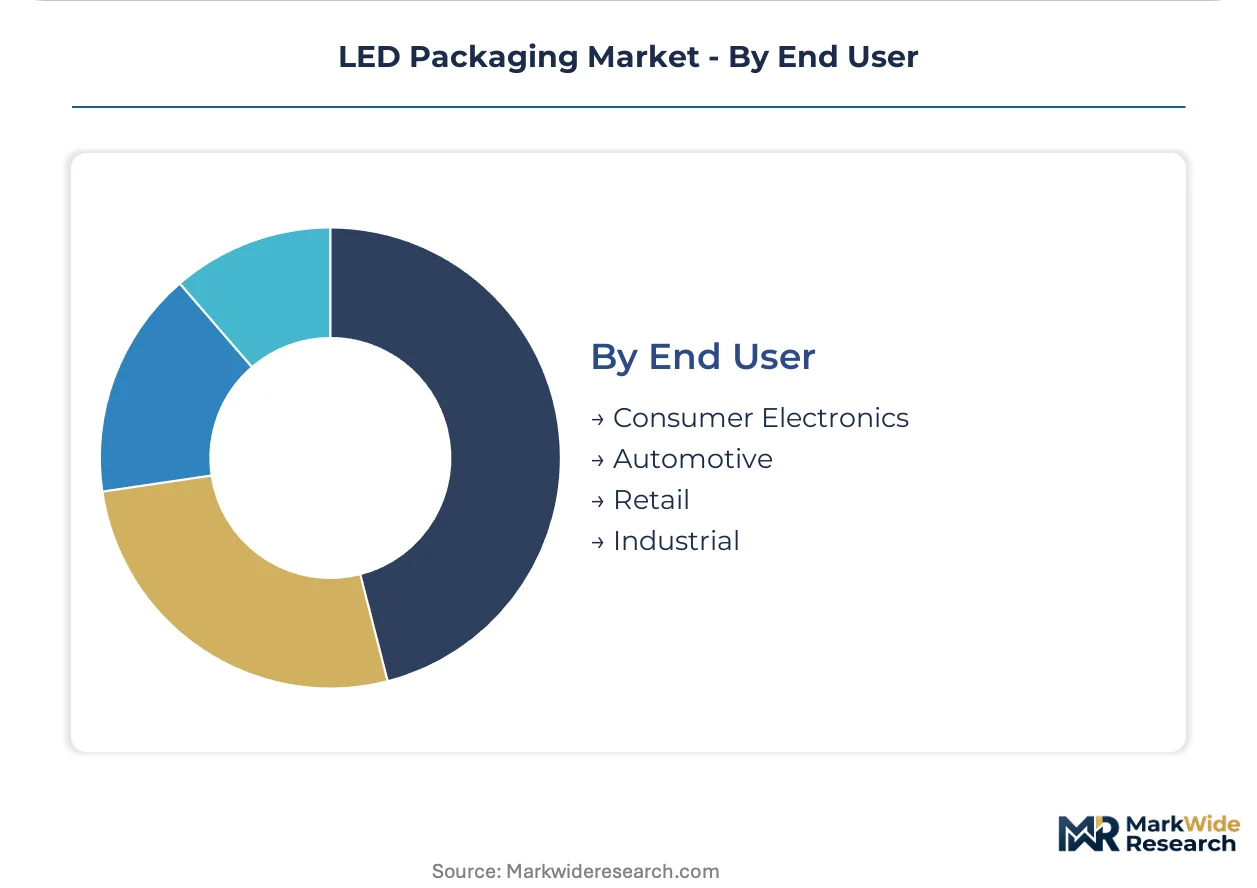
- Consumer Electronics:Smartphone and tablet backlighting demands ultra-compact 0.3mm-thin packages with color consistency across millions of units. Chinese display panel integration is concentrating demand around domestic packaging houses with GB standard compliance and proximity to Shenzhen assembly clusters.
- Automotive:Electrification is compressing LED packaging qualification timelines as OEMs demand AEC-Q101-compliant modules for 2027-2028 vehicle platform slots. Interior ambient systems require multi-zone addressable arrays, expanding die-count-per-vehicle.
- Retail:Museum and high-end commercial lighting specifications emphasize CRI above 90 with warm-white phosphor blends facing EU substance scrutiny.
- Industrial:Hazardous location fixtures and high-bay warehouse lighting prioritize thermal management and ingress protection over color rendering precision.
Volume concentration: Consumer Electronics. Fastest expansion: Automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the LED packaging demand concentration through its integration with display panel assembly clusters and EV manufacturing corridors. The Pearl River Delta's supplier density compresses procurement timelines for consumer electronics and automotive Tier 1s. Regulatory divergence across major economies is fragmenting certification pathways and reshaping regional competitive positioning.
China
Domestic display panel and EV production scaling concentrates demand around Shenzhen and Dongguan packaging houses. GB standards for energy efficiency under dual carbon goals tighten lumen-per-watt thresholds, forcing phosphor deposition upgrades. Suzhou and Hangzhou clusters specialize in high-CRI packages for museum and retail lighting exports.
Germany
Automotive headlamp and industrial horticulture applications drive specification intensity from Bavarian Tier 1 suppliers. EU Ecodesign requirements under the EU Green Deal mandate minimum efficacy thresholds and product disassembly provisions. Munich and Stuttgart engineering centers collaborate with packaging houses on thermal simulation for adaptive driving beam arrays.
United States
Automotive procurement consolidation in Michigan demands AEC-Q101 pre-validation and concurrent engineering capabilities. EPA ENERGY STAR program and California Title 20 standards create bifurcated compliance obligations. Detroit-area module manufacturers specify integrated optical-electrical-thermal subassemblies for 2027-2028 EV platform slots.
South Korea
Premium monitor and television backlighting demand concentrates around Seoul and Suwon display manufacturers qualifying quantum dot enhancement films. RoHS substance scrutiny on cadmium and indium phosphide alternatives complicates chemistry selection. Busan packaging houses supply multi-zone addressable arrays for automotive cabin ambient systems.
Japan
Stadium retrofit and high-bay industrial applications in Tokyo and Osaka favor chip-on-board architectures with 100,000-hour maintenance-free specifications. METI efficiency benchmarks align with EU Ecodesign thresholds, reducing certification duplication. Nagoya automotive suppliers integrate ceramic substrate packages for compact headlamp footprints.
LED Packaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across thermal management capability and automotive qualification status. The vendor base stratifies between captive-integrated display makers, independent packaging specialists, and automotive-focused ceramic substrate suppliers. Three archetypes dominate: phosphor-conversion specialists with rare earth supply relationships, flip-chip technology licensors with patent-protected architectures, and automotive-qualified houses with AEC-Q101 validation infrastructure. Competitive moves concentrate on backward integration into epitaxial capacity and strategic partnerships for micro-LED mass transfer yield improvement.
Within the phosphor-conversion tier, Nichia Corporation and Seoul Semiconductor Co. Ltd. exemplify divergent technology positioning. Nichia's Japanese corporate structure anchors premium CRI segment representation through established phosphor expertise. Seoul Semiconductor's Korean headquarters sit within the patent-protected WICOP technology archetype, differentiating against conventional flip-chip designs. ams-OSRAM AG's Austrian-German corporate form occupies the European automotive qualification pathway, supplying ceramic substrate packages to Bavarian Tier 1 lighting module manufacturers.
| Leading Market Players |
|---|
| Nichia Corporation |
| ams-OSRAM AG |
| Lumileds Holding B.V. |
| Seoul Semiconductor Co. Ltd. |
| Samsung Electronics Co. Ltd |
| LG INNOTEK |
| Everlight Electronics Co. Ltd. |
| Citizen Electronics Co. Ltd. |
| MLS Co. Ltd |
| Others |
Cost & Logistics Intelligence
Automotive procurement consolidation around AEC-Q101 pre-validation requirements is compressing supplier margins and forcing packaging houses to absorb upfront qualification costs before securing volume commitments. Tier 1 lighting module manufacturers in Michigan and Bavaria now demand integrated optical-electrical-thermal subassemblies rather than discrete packaged LEDs, reshaping how suppliers structure pricing and configure production assets.
Pricing Analysis
Yield-guaranteed throughput anchors value-based pricing for quantum dot and micro-LED formats where display manufacturers pay premiums for mass transfer reliability. Pricing stratifies across AEC-Q101 automotive tiers, high-CRI museum specifications, and commodity SMT retrofit volumes. Cost compression in standard SMT segments intensifies as Chinese domestic packaging houses upgrade phosphor deposition capabilities for GB standard compliance. Consumer electronics backlighting shows highest price sensitivity due to million-unit scale procurement and proximity to Shenzhen assembly clusters.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand while distributor networks serve fragmented general illumination and signage customers. Sapphire and silicon carbide substrate supply clusters in China, Taiwan, and South Korea expose packaging houses to single-source disruption during allocation cycles. Rare earth processing for cerium-doped yttrium aluminum garnet and nitride red phosphors draws from Chinese refineries, creating input cost volatility. REACH restrictions on hazardous substances constrain solder alloy and phosphor chemistry options for European manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over epitaxial wafer supply and precision mass transfer equipment determines margin capture. Players are pursuing backward integration into captive epitaxy capacity to secure substrate allocation priority.
For Market Incumbents: Deepen AEC-Q101 validation infrastructure to defend automotive slots against emerging ceramic substrate specialists from Japan and South Korea. Secure long-term rare earth supply agreements with Chinese processors before phosphor cost volatility accelerates. Prioritize concurrent engineering partnerships with Bavarian and Michigan Tier 1s to embed specifications early in 2027-2028 EV platform development. For New Entrants and Emerging Players: Capture quantum dot color conversion opportunities in Taiwanese and South Korean display backlighting where Cd-free QDEF qualification creates phosphor-independent margin pools. Target modular package designs with separable optical and thermal subassemblies for EU Ecodesign compliance premiums. Lead with thermal simulation collaboration capabilities to differentiate against established houses facing talent scarcity. For Investors and Strategic Acquirers: The window for entry favors packaging houses with precision pick-and-place and laser lift-off capabilities that can capture micro-LED mass transfer value from struggling display panel makers. Long-term viability hinges on automotive qualification status and rare earth supply relationships rather than commodity SMT scale. Watch for inflection when AEC-Q101 pre-validation timelines compress below 18 months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxy | Captive wafer supply secures substrate allocation priority during shortage cycles. |
| AEC-Q101 Pre-Validation Investment | Early qualification locks 2027-2028 EV platform slots before competitor submission. |
| Quantum Dot Enhancement Film Partnership | Cd-free QDEF integration opens premium monitor and television backlighting margins. |
| Modular Package Design Development | Separable subassemblies command EU Ecodesign premiums in retrofit channels. |
| Micro-LED Mass Transfer Capability Buildout | Precision pick-and-place addresses display panel maker yield struggles. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with packaging house operations directors, Tier 1 automotive procurement managers, display panel integration engineers, and phosphor chemistry suppliers combined with bottom-up and top-down triangulation. Secondary sources included EPA ENERGY STAR certification databases, EU Ecodesign implementing measures, China GB standard publications, and SEC filings from listed LED component manufacturers.
Segment-level modeling tracked product type, technology platform, application intensity, and end-user concentration across the analysis window. Volume and value outputs reflected disaggregated forecasting by packaging architecture and qualification tier. CAGRs derived from regression analysis against automotive production schedules, display panel shipment forecasts, and commercial building retrofit cycles. Industry-specific inputs incorporated rare earth price indices, AEC-Q101 certification pipeline data, and thermal interface material specification trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to substrate allocation disruptions, REACH substance restriction expansions, and EV platform timeline accelerations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Social Networks Market
Others
ISO Cylinder Market
Others
Global Recruitment and Staffing Market
Others
Global Extruded Plastics Market
Others
Global Smart Home Installation Service Market
Others
5G Edge Computing Market
Others
Thailand Travel Retail Market
Others
Trusted Platform Module (TPM) Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Telecom Transformers Market
Others
Solar Panel Testers Market
Others
Global OTA Testing Market
Others
Africa 3D Printing Construction Market
Others
Automotive Smart Lighting Market
Others
Fluorite Market
Others
Global Electronic Filters Market