
 Global Geotechnical Instrumentation and Monitoring Market | 2026-2036
Global Geotechnical Instrumentation and Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Geotechnical Instrumentation and Monitoring Market Intelligence
Specialized manufacturing capacity for high-precision fiber optic sensors is hardening around established technology clusters in Canada and Switzerland. RST Instruments Ltd. leverages its expertise in custom sensor design for complex mining applications. Fugro differentiates through its integrated data acquisition and analysis services for offshore structures. Keller Group extends its foundation engineering services to include comprehensive monitoring solutions.
Geotechnical instrumentation and monitoring involves the use of sensors to measure physical parameters within soil, rock, and man-made structures. These systems, often requiring measurement accuracy to the microstrain level, provide critical data for assessing stability and performance. While Piezometers and Inclinometers form a mature base of the market, demand for Fiber Optic Sensors is accelerating due to their durability and immunity to electromagnetic interference. Tunnel Safety and Dam and Reservoir Surveillance applications represent high-margin opportunities for suppliers.
Safety mandates from bodies like the US Army Corps of Engineers and China's Ministry of Emergency Management compel the use of monitoring on critical infrastructure. Conformance with ISO standards for sensor calibration and data management is a key prerequisite for project tenders in Europe and the Middle East. Vendor selection increasingly depends on the ability to provide integrated, end-to-end data platforms rather than just discrete hardware components.
Market Dynamics
The central force shaping the market is the client-side demand for integrated, end-to-end data platforms. This shift is displacing the traditional model of procuring discrete hardware components and performing separate in-house analysis, favoring vendors who offer a unified service.
Growth Catalysts
- Infrastructure Investment:Government-backed spending on large-scale urban development, new tunnels, and dam projects in countries like India and Brazil directly stimulates demand for comprehensive geotechnical monitoring to ensure structural integrity and public safety.
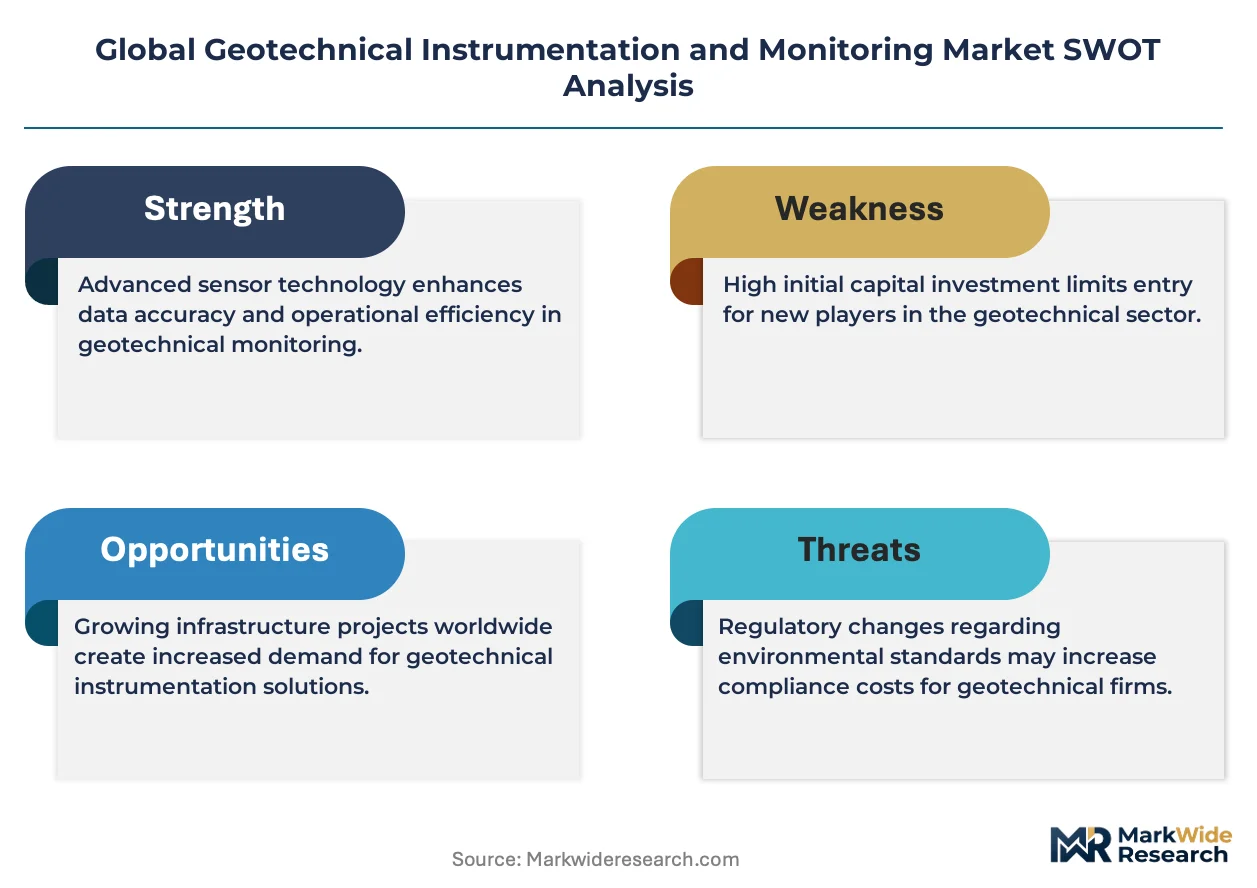
- Regulatory Mandates:Safety requirements from bodies such as the US Army Corps of Engineers and China's Ministry of Emergency Management compel the use of continuous monitoring on critical infrastructure, making instrumentation a non-discretionary project expense.
- Fiber Optic Sensor Adoption:The superior durability, EMI immunity, and high precision of fiber optic sensors are driving their adoption in harsh environments like mines and tunnels, where traditional electronic sensors face limitations.
Market Restraints
- High Initial Cost:The significant upfront capital investment required for advanced systems, particularly those incorporating fiber optic sensors and automated data acquisition units, can be a barrier for projects with constrained budgets.
- Standardization Gaps:A lack of universally accepted standards for sensor calibration and data formatting across different regions complicates system integration and creates compliance hurdles for suppliers bidding on international tenders.
- Technical Limitations of Legacy Systems:Existing portfolios of older, less accurate sensors installed on aging infrastructure present technical challenges for upgrade and integration, limiting the immediate addressable market for the latest technologies.
Strategic Opportunities
- Predictive Analytics Platforms:Developing software platforms that use machine learning to analyze sensor data for predictive maintenance and failure forecasting offers a high-margin service opportunity beyond hardware sales.
- Renewable Energy Infrastructure:The construction of offshore wind farms and geothermal plants creates new applications for monitoring foundation stability, soil interaction, and structural health in novel operating environments.
- Service Expansion in Emerging Markets:Providing integrated monitoring and data analysis services in fast-developing regions in the Middle East and Southeast Asia, where local expertise is scarce, presents a significant growth vector.
Industry Challenges
- Specialized Talent Shortage:A scarcity of technicians and engineers who possess the dual expertise in geotechnical principles and modern data science creates a bottleneck for deploying and managing advanced monitoring systems.
- Data Integration Complexity:Integrating real-time data streams from new wireless or fiber optic sensors with clients' legacy IT infrastructure and disparate older monitoring systems poses a significant technical and operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Geotechnical Instrumentation and Monitoring Market |
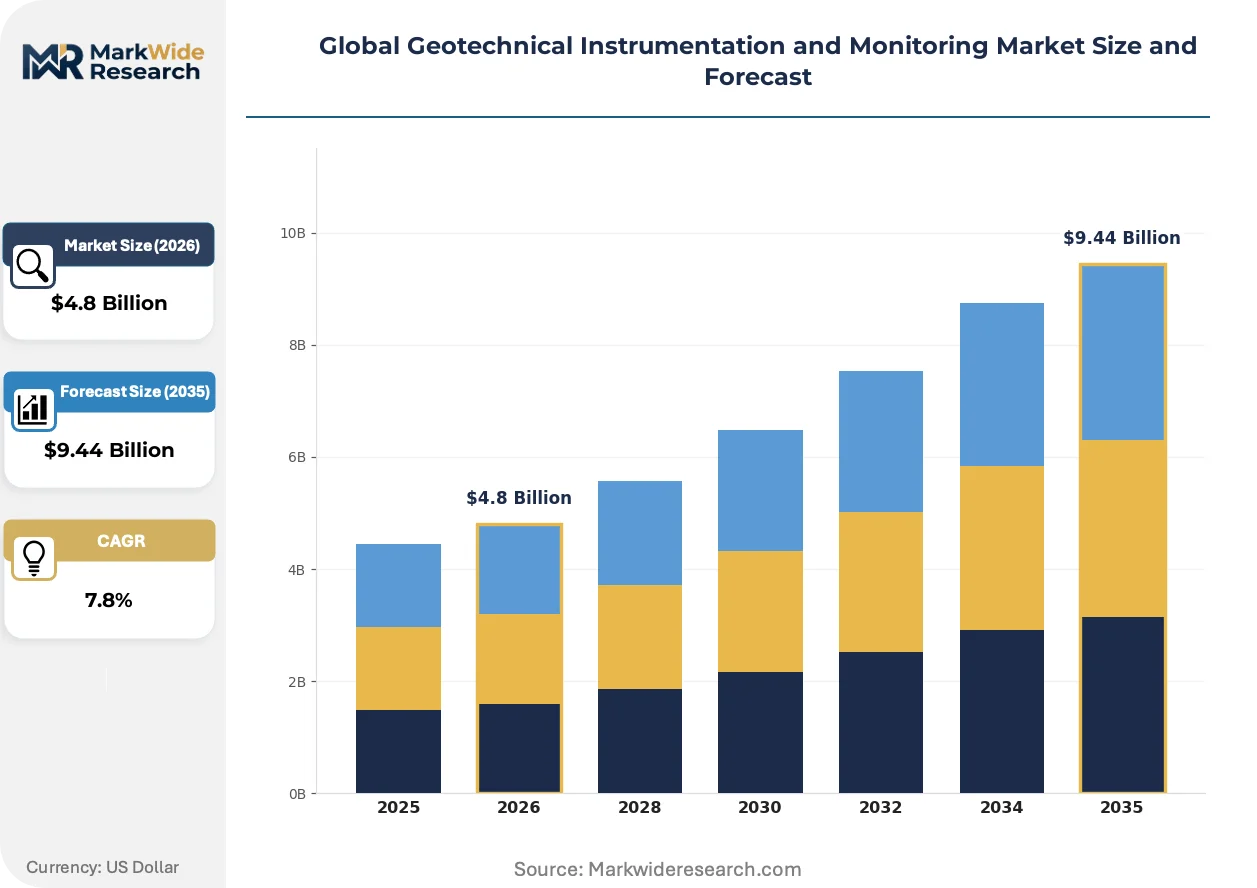
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.44 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inclinometers, Piezometers, Load Cells, Extensometers, Tiltmeters, Strain Gauges Technology: Fiber Optic Sensors, Wireless Monitoring, Embedded Systems, Remote Sensing, Digital Data Acquisition, Acoustic Emission Application: Mining Site Stability, Tunnel Safety, Dam and Reservoir Surveillance, Construction Site Monitoring, Slope Stability, Bridge Structural Assessment End User: Engineering Consultants, Government Agencies, Construction Firms, Infrastructure Developers, Research Institutes, Environmental Agencies |
| Companies Covered | Geokon, RST Instruments Ltd., Fugro, Deep Excavation LLC, Sisgeo S.r.l., Keller Group, Geocomp Corporation, James Fisher & Sons plc, Nova Metrix LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Geotechnical Instrumentation and Monitoring Market Strategic Shifts & Innovations
A fundamental shift from reactive monitoring to predictive asset management defines the market's trajectory. This evolution prioritizes forecasting potential failures over simply recording current conditions, altering the value proposition of instrumentation services and the software platforms that deliver them.
Wireless sensor networks (WSNs) provide automated, real-time data collection without the need for extensive physical cabling. Construction and mining operations are adopting WSNs to improve site safety and operational efficiency. This technology is modularizing monitoring system architecture, allowing for flexible, scalable deployments that can be easily reconfigured or expanded as project needs change.
European Union directives focused on the resilience of critical infrastructure are compelling asset owners to enhance their monitoring capabilities. These regulations mandate more rigorous and frequent assessments of structures like dams, bridges, and transportation networks. The dam safety and tunnel surveillance segments are most affected, driving investment in continuous, automated monitoring systems to meet new compliance thresholds.
Client purchasing behavior is moving away from discrete hardware procurement toward performance-based service contracts that bundle instrumentation, data acquisition, and analytics. This model disrupts traditional component distributors and favors system integrators capable of delivering actionable insights. The trend is most pronounced in large-scale offshore energy and complex civil infrastructure projects in North America and Europe.
Global Geotechnical Instrumentation and Monitoring Market Segmentation
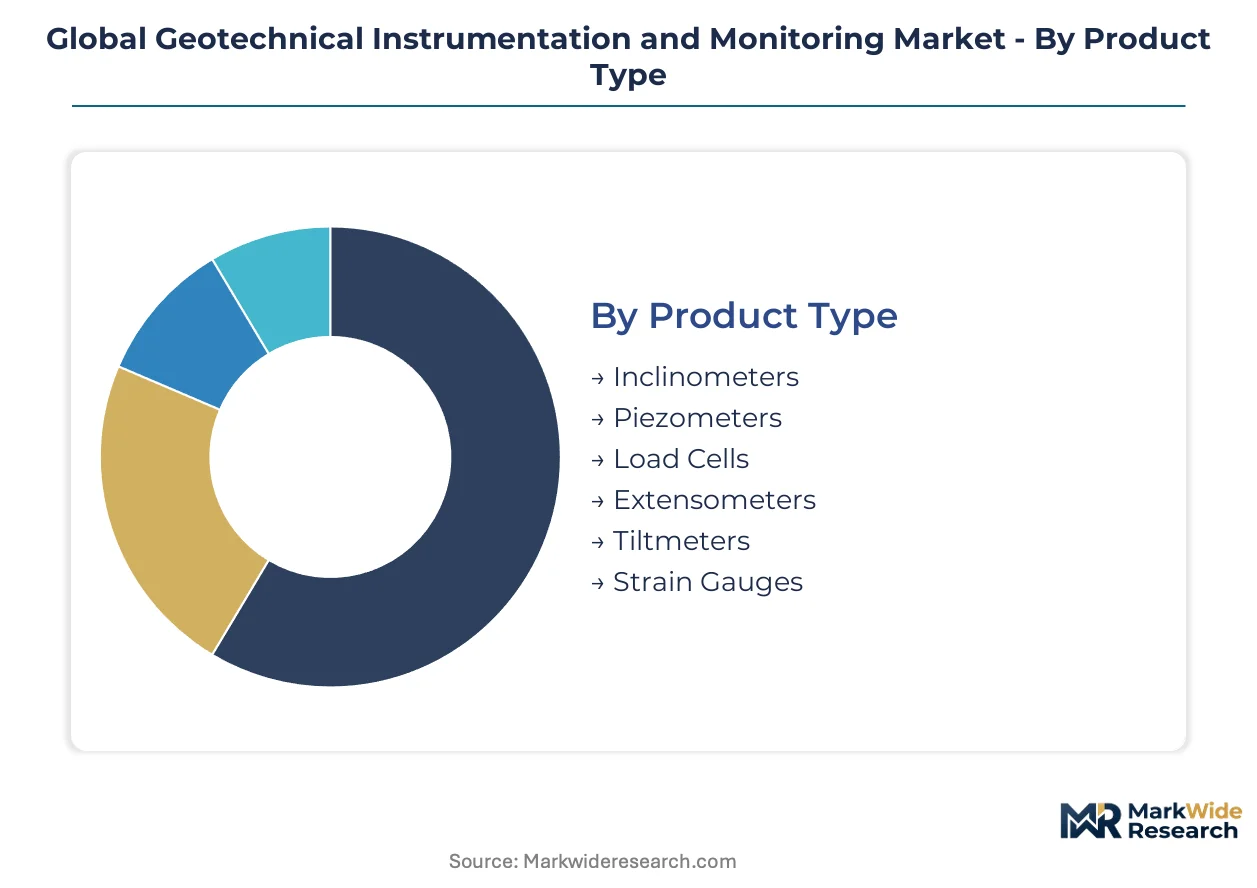
The Global Geotechnical Instrumentation and Monitoring Market segments to reveal distinct demand patterns and technological preferences across various project types. Understanding these segments helps providers align their offerings with specific client needs for structural integrity and public safety. Each category reflects unique operational requirements and regulatory drivers.
Product Type:
Buyers prioritize specific product types based on the required measurement precision and environmental resilience for their geotechnical projects.
- Inclinometers:These instruments measure lateral ground movement and deformation within boreholes, providing critical data for slope stability and retaining wall performance. Demand concentrates in large-scale infrastructure projects across India and Brazil, where ground stability is a constant concern.
- Piezometers:Devices designed to measure pore water pressure within soil and rock masses, essential for analyzing groundwater conditions and embankment stability. Construction firms utilize piezometers extensively in dam projects and tunneling operations to manage hydrostatic forces.
- Load Cells:These sensors quantify axial loads and forces in structural elements like rock bolts, anchors, and piles, ensuring the integrity of support systems.
- Extensometers:Instruments used to measure displacement and deformation over time, crucial for monitoring tunnels, mines, and landslides.
- Tiltmeters:These devices monitor minute changes in the inclination or tilt of structures, providing early warnings for potential structural failures.
- Strain Gauges:Sensors that measure deformation or strain in structural components, offering high-precision data for critical stress analysis in bridges and buildings.
Volume sits with Inclinometers; growth tilts toward Strain Gauges.
Technology:
Technology choices often reflect the balance between initial deployment costs and long-term operational efficiency for monitoring systems.
- Fiber Optic Sensors:These sensors utilize light for measurement, offering immunity to electromagnetic interference and exceptional durability in harsh environments. Investment in new tunnel projects in Switzerland drives demand for these high-precision solutions.
- Wireless Monitoring:Wireless sensor networks provide automated, real-time data collection without extensive cabling, improving deployment flexibility and site safety. Mining operations in Canada adopt wireless systems for continuous subsurface monitoring.
- Embedded Systems:Integrated hardware and software solutions designed for dedicated control and data acquisition tasks within monitoring systems.
- Remote Sensing:Techniques using satellite or aerial platforms to collect data over large areas, providing macro-level insights into ground movement and structural changes.
- Digital Data Acquisition:Systems that convert analog sensor signals into digital data for processing, storage, and analysis, enabling integrated data platforms.
- Acoustic Emission:Technology detecting stress waves generated by material deformation and fracture, used for early detection of structural damage in concrete and rock.
Digital Data Acquisition solutions are expanding most quickly.
Application:
Specific applications dictate the type and density of geotechnical instrumentation, directly influencing project safety and compliance.
- Tunnel Safety:This segment involves comprehensive monitoring of tunnel excavation, lining stability, and ground convergence to prevent collapses and ensure worker safety. Safety mandates from China's Ministry of Emergency Management compel extensive monitoring in new tunnel constructions.
- Dam and Reservoir Surveillance:Critical applications include monitoring pore pressure, seepage, and structural deformation in dams to ensure long-term stability and prevent catastrophic failures. The US Army Corps of Engineers mandates continuous surveillance on critical water infrastructure.
- Mining Site Stability:Monitoring ground movement, rockfall, and slope stability in open-pit and underground mines to enhance operational safety.
- Construction Site Monitoring:Geotechnical instrumentation deployed during construction phases to manage risks associated with excavations, foundations, and temporary structures.
- Slope Stability:Assessment and continuous monitoring of natural and engineered slopes to predict and mitigate landslides and rockfalls.
- Bridge Structural Assessment:Instrumentation used to evaluate the health and performance of bridge components under various load conditions and environmental stresses.
Dam and Reservoir Surveillance applications are climbing the fastest.
End User:
Different end-user segments require tailored monitoring solutions, ranging from raw data provision to full-service analytical platforms.
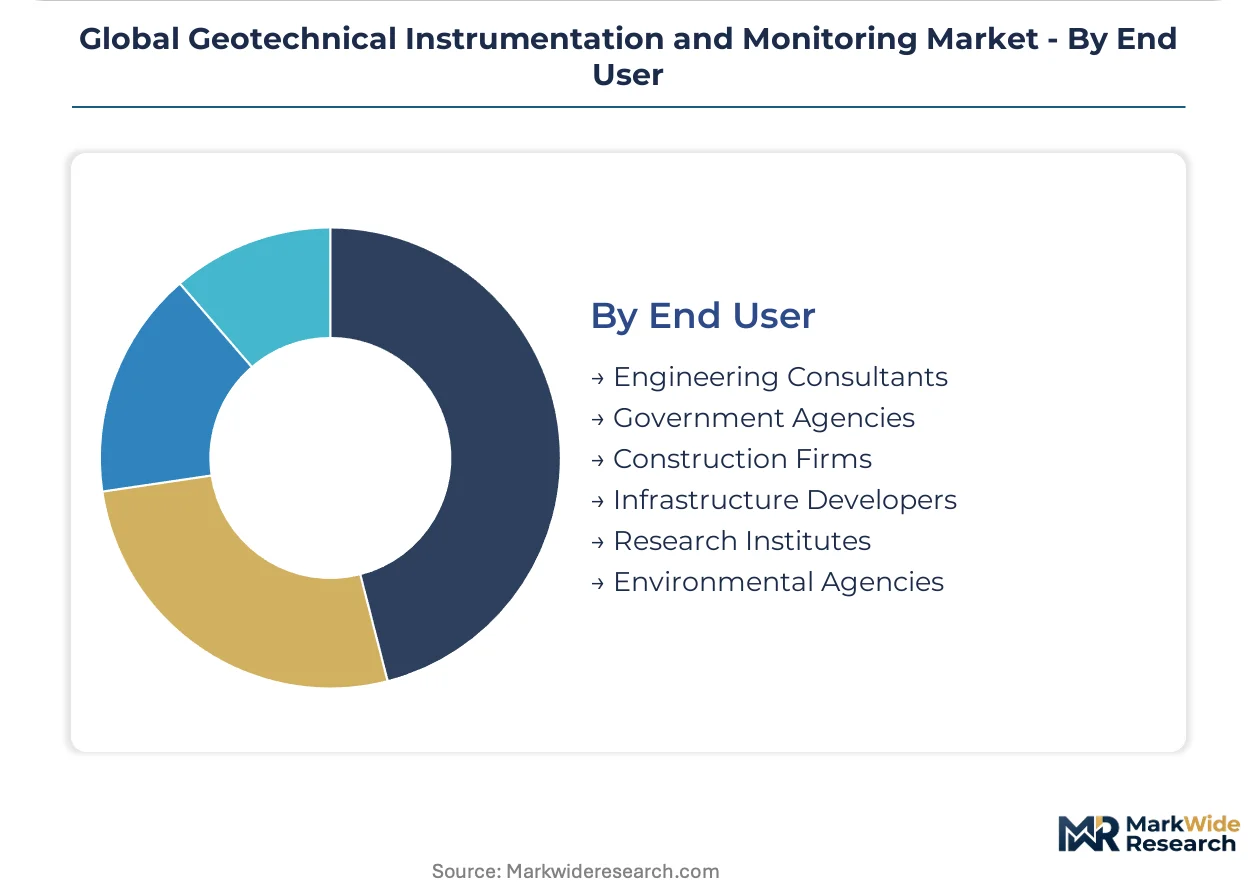
- Construction Firms:These entities utilize monitoring solutions for real-time site assessment, ensuring project safety, compliance, and efficient resource allocation. Large-scale urban infrastructure projects drive significant demand from these firms.
- Government Agencies:Public bodies responsible for infrastructure development and safety mandates require monitoring for regulatory compliance and long-term asset management. Agencies like the US Army Corps of Engineers are key drivers for continuous monitoring.
- Engineering Consultants:Firms providing specialized geotechnical analysis and design services, often integrating monitoring data into their recommendations.
- Infrastructure Developers:Organizations funding and managing large-scale infrastructure projects, requiring comprehensive monitoring from planning through operation.
- Research Institutes:Academic and scientific bodies conducting studies on soil mechanics and structural behavior, using advanced instrumentation for data collection.
- Environmental Agencies:Bodies monitoring environmental impacts of construction or natural hazards, utilizing geotechnical data for risk assessment.
Infrastructure Developers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Significant infrastructure development in emerging economies anchors demand for geotechnical instrumentation. These large-scale projects necessitate precise monitoring solutions for structural integrity and public safety. Investment in new tunnels and dam projects concentrates demand globally.
India
India's extensive government-backed spending on large-scale urban infrastructure drives significant demand. National infrastructure programs compel advanced instrumentation use for structural integrity. Major urban centers like Mumbai and Delhi-NCR see concentrated deployment for metro and highway construction.
Brazil
Brazil's ongoing investment in new dam projects and complex urban infrastructure fuels the need for comprehensive geotechnical instrumentation. National safety standards for critical infrastructure compel continuous surveillance, especially in hydroelectric power. The São Paulo region experiences concentrated demand for monitoring solutions within its expanding transportation networks.
Canada
Wireless monitoring technologies are increasingly adopted for complex mining applications across Canada, enhancing operational safety. Provincial mining safety regulations mandate continuous subsurface monitoring to prevent rockfalls. Technology clusters in Ontario specialize in developing high-precision fiber optic sensors for harsh underground environments.
Switzerland
Switzerland's focus on new tunnel projects and high-precision engineering drives demand for advanced fiber optic sensors. Stringent Swiss engineering standards necessitate microstrain-level accuracy for critical infrastructure. Established technology clusters around Zurich and Lausanne harden specialized manufacturing capacity for these precise instruments.
China
China's extensive new tunnel constructions and critical infrastructure projects generate substantial demand for geotechnical monitoring. The Ministry of Emergency Management compels comprehensive monitoring to ensure tunnel safety. The Yangtze River Delta region sees widespread deployment of monitoring systems for its expanding urban and transportation networks.
Global Geotechnical Instrumentation and Monitoring Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated data platforms and predictive analytics. The market exhibits a tiered structure, with specialized hardware manufacturers coexisting alongside full-service solution providers. Strategic archetypes include high-precision sensor specialists, integrated data acquisition firms, and foundation engineering companies extending into monitoring. Portfolio diversification into end-to-end data platforms and strategic partnerships to combine hardware with analytics are common competitive moves.
Specialists in integrated data acquisition and analysis, such as Fugro, exemplify the shift towards comprehensive service offerings, particularly for complex offshore structures. Keller Group represents a major foundation engineering firm that has successfully extended its core services to include full geotechnical monitoring solutions, catering to large-scale infrastructure projects. RST Instruments Ltd., a Canadian entity, anchors the high-precision sensor archetype, leveraging its deep expertise in custom sensor design specifically for demanding mining applications. These firms collectively demonstrate the market's evolution from discrete hardware sales to integrated, value-added services.
| Leading Market Players |
|---|
| Geokon |
| RST Instruments Ltd. |
| Fugro |
| Deep Excavation LLC |
| Sisgeo S.r.l. |
| Keller Group |
| Geocomp Corporation |
| James Fisher & Sons plc |
| Nova Metrix LLC |
| Others |
Cost & Logistics Intelligence
The integration of wireless monitoring technologies and fiber optic sensors reshapes cost economics by reducing installation complexity, concentrating specialized manufacturing in technology clusters. This shift impacts pricing strategies and supply chain resilience for geotechnical instrumentation.
Pricing Analysis
Performance-based service contracts bundle instrumentation, data acquisition, and analytics, moving away from discrete hardware procurement. The dominant pricing model favors project-based solutions, differentiating on high-precision sensor calibration and end-to-end data platform integration. Pricing pressure stems from client-side demand for unified services, impacting traditional component suppliers. Construction firms exhibit high price sensitivity for basic hardware, whereas government agencies prioritize value and compliance for critical infrastructure monitoring.
Supply Chain Analysis
Dual-sourcing requirements for critical components are emerging, particularly for high-precision fiber optic sensors. The supply of specialized manufacturing capacity concentrates in Switzerland and Canada, with broader electronic component sourcing from China. Raw material dependencies include specialized optical fibers and sensor-grade silicon, creating single-source vulnerability for advanced systems. Distribution runs through direct sales channels to large infrastructure developers and via specialized engineering consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The geotechnical instrumentation market is fundamentally a cost-of-compliance story. Safety mandates from bodies like the US Army Corps of Engineers create a significant barrier to entry for non-compliant solutions, while ISO standards for sensor calibration establish a competitive moat.
For Market Incumbents:Deepen vertical integration into end-to-end data platforms to counter emerging entrants offering integrated solutions. Strategic partnerships with AI/ML specialists can enhance predictive analytics capabilities, transforming raw data into actionable insights. Investing in advanced sensor calibration facilities secures a competitive advantage against less precise offerings. This strategy defends market share against new players focused solely on software and analytics.
For New Entrants and Emerging Players:Small-to-mid-sized construction projects represent an underserved buyer archetype for cost-effective, easily deployable monitoring solutions. Target remote site monitoring applications in developing regions like Southeast Asia, where local expertise is scarce. A subscription-based, wireless monitoring-as-a-service model can lower upfront costs. Focus on modular, scalable systems that simplify deployment and maintenance for these segments.
For Investors and Strategic Acquirers:Re-rating potential sits with integrated data platform providers, given the regulatory push for predictive asset management on critical infrastructure. This market offers long-term viability due to continuous demand for structural integrity and public safety. Target specialized software firms possessing advanced AI/ML capabilities for sensor data analysis. Adoption rates of predictive analytics platforms will signal market maturation and consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Predictive Analytics | Transforms reactive monitoring into proactive asset management for infrastructure developers. |
| Expand Fiber Optic Sensor Manufacturing | Addresses demand for durable, EMI-immune sensors in harsh environments like mines. |
| Offer Integrated Monitoring-as-a-Service | Aligns with client demand for end-to-end solutions, reducing upfront capital expenditure. |
| Secure ISO Certification for Data Management | Ensures compliance with European and Middle Eastern project tender prerequisites. |
| Establish Local Service Hubs in Emerging Markets | Captures growth in fast-developing regions with limited local geotechnical expertise. |
Research Approach
Multi-period observation of infrastructure investment trends and regulatory mandates anchored the trend analysis, supplemented by interviews with geotechnical engineers and project managers. Regulatory compliance officers and sensor R&D specialists provided primary insights. Secondary validation drew from government infrastructure spending reports, engineering society publications, and company financial statements. This approach utilized bottom-up market sizing and top-down validation.
Segment-weighting across product type, technology, application, end-user, and regional regulatory frameworks informed the forecast framework. The analytical framework projected demand over the analysis window, integrating planned infrastructure project pipelines and regulatory compliance rates. Compound Annual Growth Rates derived through regression analysis of historical data ensured granular understanding of future market trajectory.
Revisions become necessary when unforeseen shifts in government infrastructure funding or new safety regulations materialize. Forecasts reflect current assumptions regarding technological adoption rates and project development timelines. Deviation in global economic stability or critical infrastructure policy shifts the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bio-Imaging Technologies Market
Others
North America Halal Food and Beverage Market
Others
Fiberglass Storage Tanks Market
Others
Mini Personal Computer Market
Others
Global Platform Trolley Market
Others
Billet Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
Japan Indoor LBS Market
Others
Global Compact Wheel Loaders Market
Others
Defense Optronics Market
Others
Latin America Automotive HVAC Market
Others
Europe Air Separation Unit Market
Others
Binoculars Market
Others
Fenoxanil Market
Others
Retail Media Platform Market
Others
Eye Balm Market