
 Splash Shield Market | 2026-2036
Splash Shield Market Size, Share, and Industry Trends Forecast 2026-2036
Splash Shield Market Outlook
Software-defined aerodynamic tuning is decoupling splash shield procurement from static part catalogs, enabling OEMs to update underbody airflow profiles through over-the-air calibration rather than physical redesign. Magna International Inc. leverages its chassis systems integration to bundle active airflow management with shield assemblies. Toyota Boshoku Corporation anchors Japanese OEM relationships through thermal-acoustic composite expertise. Hyundai Mobis Co. Ltd. competes on Korean domestic volume and EV platform standardization.
A splash shield is a protective barrier, typically molded from polypropylene or glass-reinforced nylon composites, designed to deflect road debris, water spray, and corrosive agents from vehicle underbodies, powertrain components, and brake systems; manufacturers employ injection molding or thermoforming with thicknesses ranging from 2 mm to 5 mm depending on impact zone requirements. Polycarbonate face shields dominate healthcare personal protection due to optical clarity and repeated sterilization tolerance, while polyethylene industrial safety applications sustain margin pools through high-volume construction sector contracts. Full face masks represent the fastest-growing configuration in laboratory use as chemical handling protocols tighten.
The EPA enforces material recyclability thresholds under automotive efficiency mandates, while NHTSA crashworthiness standards govern underbody component retention during impact events; the EU REACH regulation restricts certain phthalate plasticizers in polymer formulations, forcing reformulation across export-bound production lines. Stakeholders must monitor evolving battery enclosure sealing requirements as EV architectures integrate splash protection with thermal management boundaries.
Market Dynamics
Software-defined aerodynamic tuning is decoupling splash shield procurement from static part catalogs, forcing suppliers to reengineer around over-the-air calibration capabilities rather than fixed hardware specifications.
Growth Catalysts
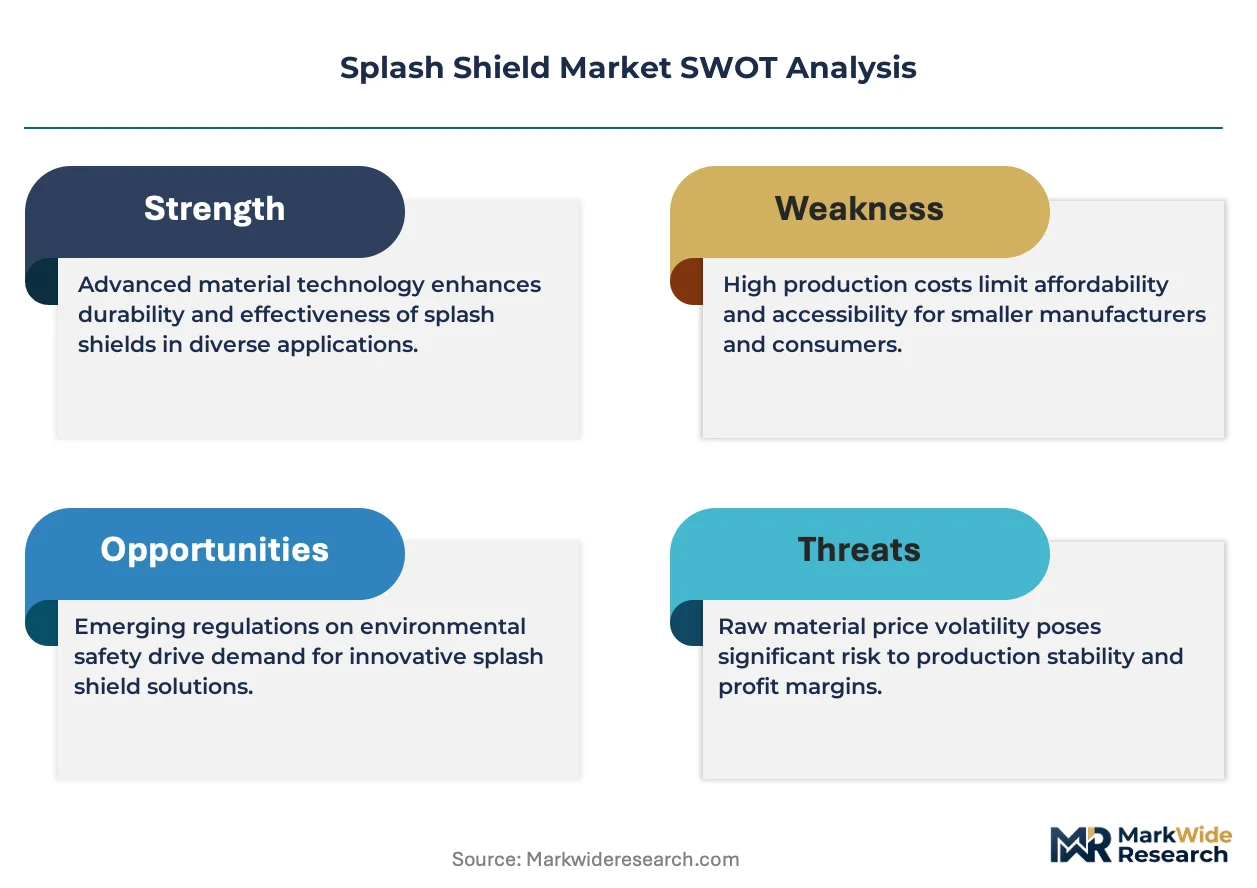
- EPA vehicle efficiency standards:Mandates for improved fuel economy and reduced emissions are compelling OEMs to adopt aerodynamic undertray systems that integrate splash protection with airflow optimization.
- EV platform proliferation:Battery electric vehicle architectures require thermal-acoustic composite shields that simultaneously protect battery enclosures and manage underbody airflow profiles.
- NHTSA safety regulations:Crashworthiness standards governing underbody component retention during impact events are tightening material performance specifications across North American supply chains.
Market Restraints
- Polypropylene feedstock volatility:Crude oil price fluctuations directly compress margins for injection-molded shield producers locked into long-term OEM supply agreements.
- German supplier concentration:BMW and Volkswagen procurement relationships anchor in Plastic Omnium SE and Magna International Inc., creating barriers for new entrants seeking platform access.
- REACH phthalate restrictions:EU ECHA regulations on plasticizer formulations force costly reformulation across export-bound production lines serving European markets.
Strategic Opportunities
- India automotive manufacturing:BIS standards alignment and PLI scheme incentives for EV component localization create entry points for shield suppliers establishing domestic molding capacity.
- Active airflow convergence:Integration of motorized aerodynamic elements with passive shield structures enables tier-one suppliers to capture chassis systems bundling value.
- Recyclability mandates:EPA automotive efficiency thresholds for material recyclability reward suppliers with closed-loop polypropylene recovery capabilities.
Industry Challenges
- CAE simulation talent scarcity:Computational fluid dynamics expertise for underbody airflow modeling commands premium compensation, constraining mid-tier suppliers.
- Dual-cavity tooling capex:Multi-material injection molds for thermal-acoustic composites require capital commitments that strain supplier balance sheets.
- Platform certification timelines:OEM validation cycles for new EV architectures extend 18-24 months, delaying revenue recognition for qualified shield designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Splash Shield Market |
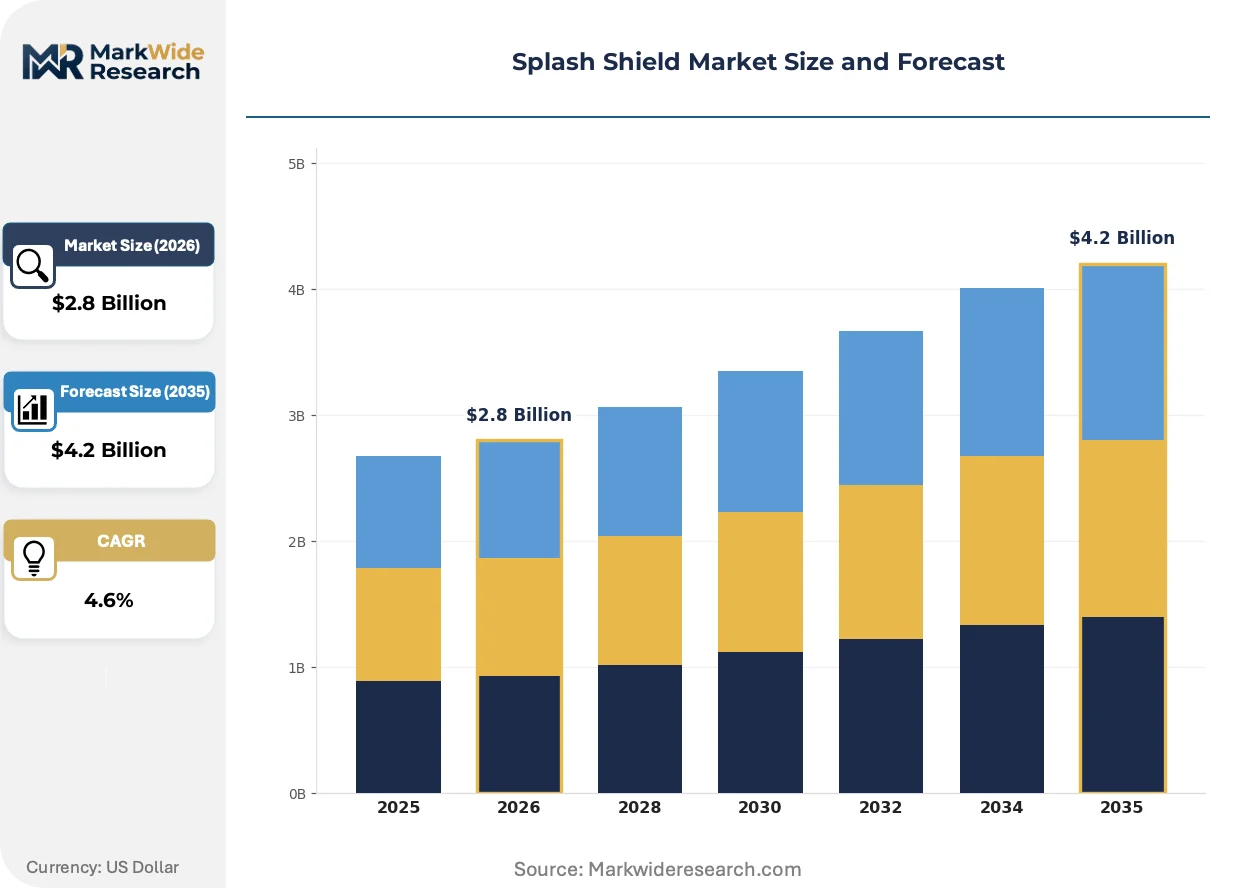
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Face Shield, Safety Goggles, Full Face Mask, Protective Visor Material: Polycarbonate, Acrylic, PVC, Polyethylene End User: Healthcare, Food Service, Manufacturing, Construction Application: Personal Protection, Laboratory Use, Industrial Safety, Medical Procedures |
| Companies Covered | Toyota Boshoku Corporation, SRG Global Inc., Magna International Inc., Hyundai Mobis Co. Ltd., Yanfeng Automotive Interiors, Plastic Omnium SE, FLEX-N-GATE Corporation, Aisin Corporation, FORVIA (Faurecia), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Splash Shield Market Strategic Shifts
Over-the-air calibration capabilities are transforming splash shields from static hardware into software-configurable aerodynamic elements, compressing traditional redesign cycles and redefining supplier value propositions.
Glass-reinforced nylon composites are rewriting material selection criteria for high-impact zones. Toyota Boshoku Corporation specifications now specify these polymers for thermal-acoustic underbody applications. The shift is compressing commodity polypropylene volumes while elevating compounder technical service requirements.
REACH regulation amendments on phthalate plasticizers are forcing polymer reformulation across European export production. ECHA enforcement is tightening testing documentation for automotive interior and underbody components. Suppliers serving Germany, France, and Italy are accelerating bio-based plasticizer qualification programs to maintain market access.
Fleet procurement consolidation among rental and mobility operators is compressing supplier negotiation leverage. Enterprise buyers now demand standardized EV platform shield configurations across multi-brand vehicle pools. This concentration is most visible in North American and Western European fleet management contracts, where volume aggregation overrides brand-specific engineering preferences.
Splash Shield Market Segmentation
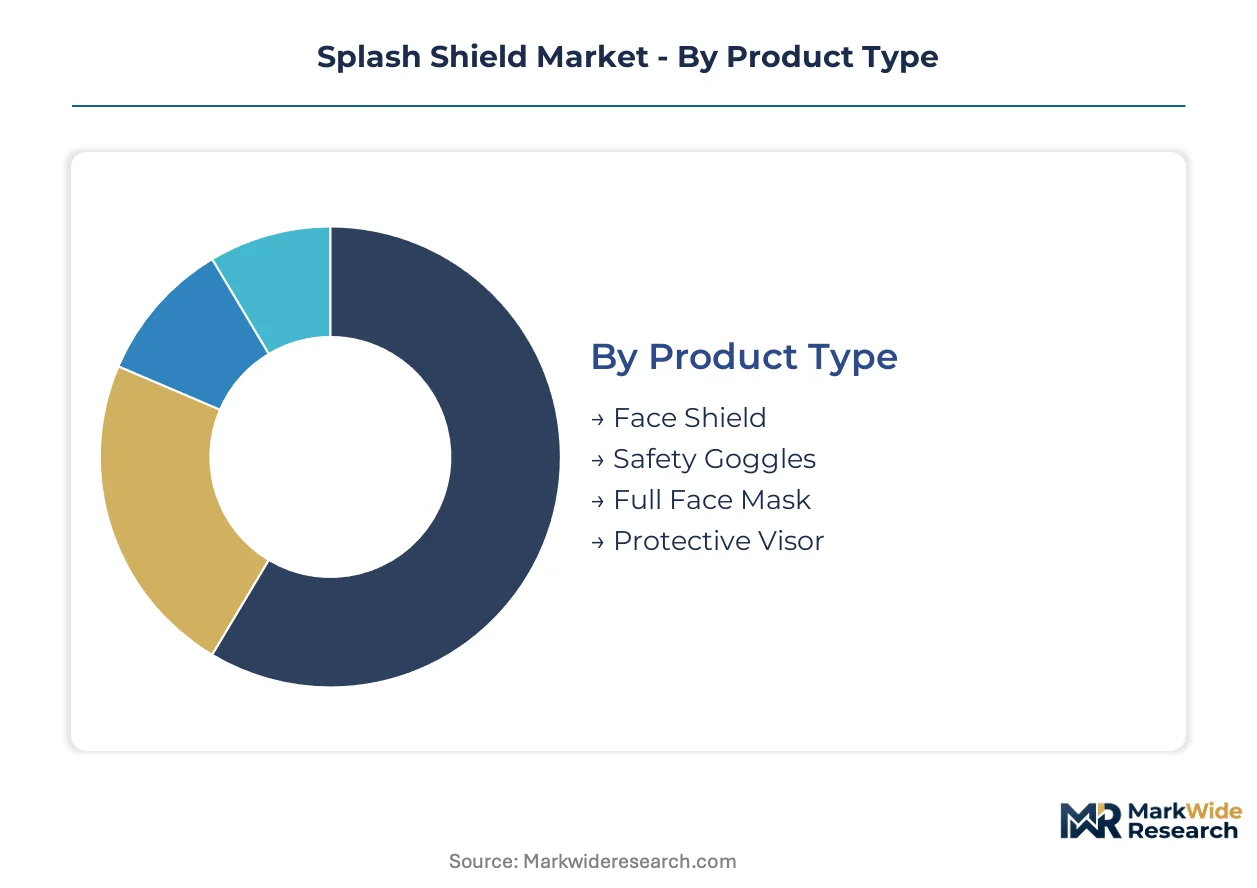
Splash shield procurement patterns diverge sharply between automotive underbody applications and personal protective equipment, with material specifications and regulatory compliance requirements driving entirely separate sourcing logics. Understanding these segment boundaries clarifies where supplier capabilities transfer across end-use categories and where specialization dominates.
Product Type:
Standalone face protection dominates high-frequency replacement cycles, while integrated full-face systems embed deeper into enterprise safety protocols with longer attachment horizons.
- Face Shield:Polycarbonate face shields deliver optical clarity and repeated sterilization tolerance for healthcare environments. Demand concentrates in North American hospital systems facing OSHA bloodborne pathogen compliance deadlines.
- Full Face Mask:These configurations seal respiratory and ocular protection into unified systems using elastomeric interfaces and cartridge filtration. Laboratory chemical handling protocols in Germany and France are accelerating specification upgrades beyond basic splash protection.
- Safety Goggles:Indirect-vented designs dominate manufacturing floor deployments where chemical splash hazards intersect with fine particulate exposure.
- Protective Visor:Flip-up visor mechanisms serve food service and light industrial applications requiring rapid transition between protection modes and unimpeded communication.
Volume placements concentrate in Face Shield; the faster expansion belongs to Full Face Mask.
Material:
Cost tiers separate commodity thermoplastics from engineered polymers with certified impact resistance and optical grades.
- Polycarbonate:This amorphous thermoplastic delivers the highest impact resistance among transparent shield materials, with ANSI Z87.1 certification mandatory for industrial safety applications. German automotive suppliers specify polycarbonate for EV underbody shields requiring thermal stability alongside debris protection.
- Polyethylene:Low-density formulations dominate disposable face shield production for healthcare mass consumption, with India PLI scheme incentives accelerating domestic blown-film capacity expansion.
- Acrylic:PMMA offers superior optical clarity at lower cost than polycarbonate, though brittleness limits deployment to low-impact laboratory and food service environments.
- PVC:Plasticized formulations serve flexible curtain and drape applications in medical isolation protocols, with REACH phthalate restrictions forcing reformulation across European export production.
Polyethylene captures the highest unit volumes; polycarbonate commands the steepest expansion trajectory as automotive and industrial safety specifications converge.
End User:
Customer type determines whether procurement flows through centralized safety departments or decentralized clinical supply chains.
- Healthcare:Hospital systems and outpatient clinics drive face shield consumption through infection control committees responding to CDC and WHO guidance updates. US health system consolidation is compressing supplier counts toward national distribution agreements.
- Construction:High-volume polyethylene industrial safety applications sustain margin pools through multi-year project contracts with tier-one general contractors.
- Manufacturing:Chemical processing and electronics fabrication facilities specify full-face respiratory integration for combined vapor and splash hazards.
- Food Service:Quick-service restaurant chains and institutional cafeterias prioritize low-cost disposable visors with anti-fog coatings for high-temperature kitchen environments.
Healthcare absorbs the largest procurement spend; construction delivers the most stable volume commitments through project-based contracting.
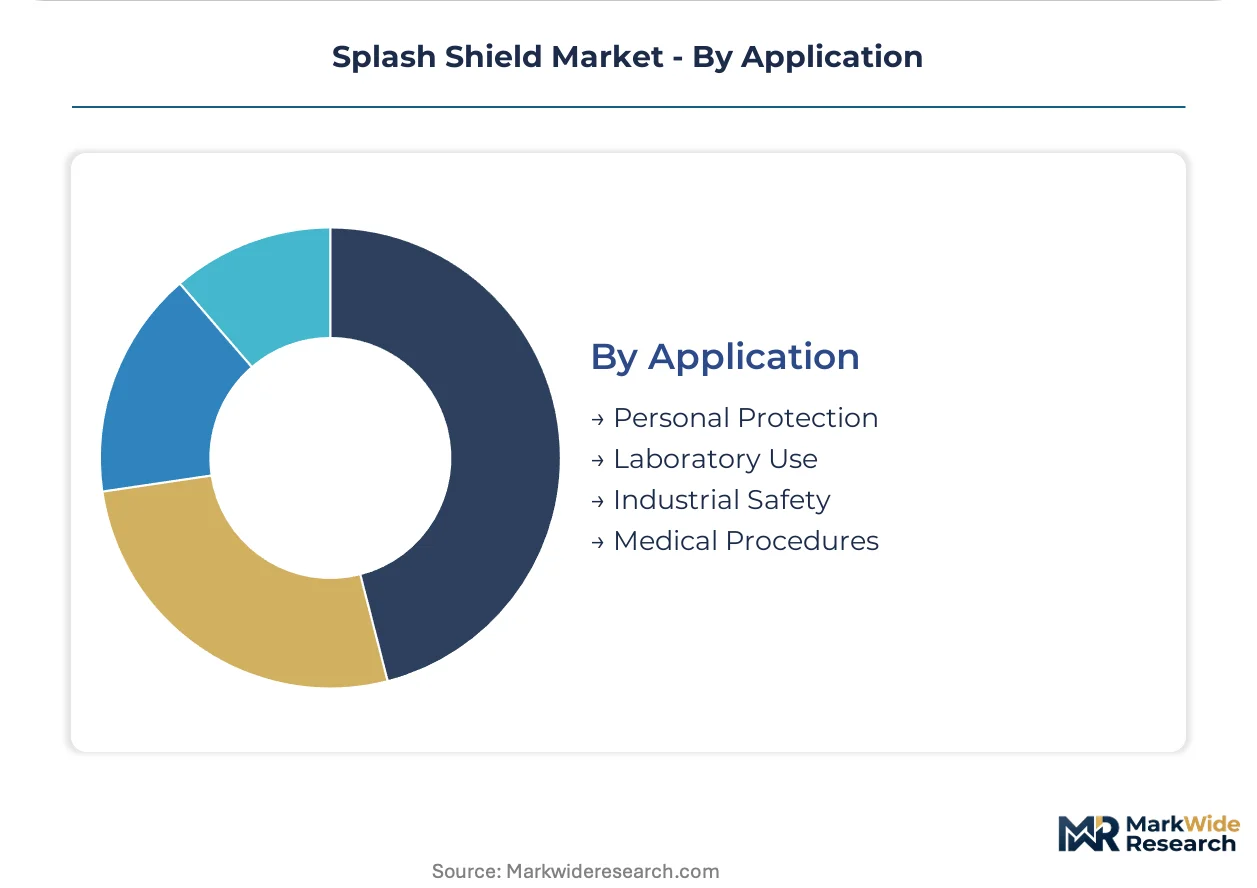
Application:
Use-case maturity separates established personal protection protocols from emerging laboratory and medical procedure specifications.
- Personal Protection:General industrial and public safety deployments represent the most standardized specification environment, with ANSI and EN 166 certification sufficient for most procurement decisions. US manufacturing reshoring initiatives are expanding domestic shield production capacity.
- Medical Procedures:Surgical and interventional applications demand sterile packaging, biocompatibility testing, and FDA 510(k) clearance pathways that extend qualification timelines. Japanese PMDA alignment with ISO 10993 standards is harmonizing Asia-Pacific regulatory entry.
- Laboratory Use:Research and diagnostic facilities specify chemical resistance ratings against specific reagent families, with academic procurement fragmented across institutional safety offices.
- Industrial Safety:Heavy manufacturing and energy sector deployments integrate splash shields into broader PPE ensembles with coordinated fit testing and training protocols.
Personal Protection anchors current volume; Medical Procedures is climbing the fastest as minimally invasive surgical techniques proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany, the United States, Japan, and South Korea, while consumption expands across these same automotive hubs as EV platform rollouts accelerate. The United States and Germany anchor OEM procurement relationships, whereas Japan and South Korea concentrate supplier engineering and domestic volume production.
United States
EPA vehicle efficiency standards and NHTSA crashworthiness regulations are tightening material specifications for underbody shields across Detroit Three supply chains. OEMs in Michigan and Ohio are qualifying thermal-acoustic composite assemblies that integrate splash protection with battery enclosure sealing. The Southeast automotive corridor spanning Tennessee, South Carolina, and Georgia is attracting injection molding capacity as EV assembly plants localize.
Germany
BMW and Volkswagen procurement contracts anchor supplier relationships with tier-one integrators in Bavaria and Lower Saxony. REACH phthalate restrictions enforced by ECHA are forcing polymer reformulation across export-bound production lines serving France and Italy. The Stuttgart and Munich engineering clusters concentrate CAE simulation talent for underbody airflow optimization.
Japan
Toyota and Honda platform standardization drives thermal-acoustic composite demand through supplier keiretsu networks anchored in Aichi Prefecture. METI carbon neutrality roadmaps are accelerating recyclability mandates that reward closed-loop polypropylene recovery capabilities. The Nagoya industrial belt houses concentrated molding expertise for glass-reinforced nylon applications.
South Korea
Hyundai and Kia EV platform proliferation is standardizing undertray specifications across domestic and export production. MFDS alignment with ISO 10993 standards supports medical-grade face shield exports, though automotive underbody applications dominate local polymer consumption. The Busan-Ulsan manufacturing corridor concentrates high-volume injection capacity for both automotive and industrial safety segments.
India
BIS standards alignment and PLI scheme incentives for EV component localization are creating entry points for shield suppliers establishing domestic molding capacity. Maruti Suzuki and Tata Motors procurement is shifting toward localized underbody assemblies as import substitution policies tighten. The Chennai and Pune automotive clusters are attracting tier-one suppliers seeking platform access to domestic OEMs.
Splash Shield Market Competitive Environment
Top-tier vendors anchor chassis systems integration, while mid-tier compounders compete on material formulation and regional molding capacity. The vendor base stratifies across three tiers: global tier-one integrators bundling active airflow management, regional injection molders serving domestic OEM platforms, and specialized compounders supplying glass-reinforced nylon formulations. Consolidation pressure is intensifying as OEMs reduce supplier counts and extend platform certification timelines.
Within the tier-one integrator tier, Magna International Inc. and Plastic Omnium SE exemplify the chassis systems bundling archetype, while Toyota Boshoku Corporation occupies a position representing thermal-acoustic composite specialization for Japanese OEM relationships. Hyundai Mobis Co. Ltd. anchors the Korean domestic volume vector. These named entities sit within competitive positions defined by geographic proximity to major OEM engineering centers and platform access depth rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| SRG Global Inc. |
| Magna International Inc. |
| Hyundai Mobis Co. Ltd. |
| Yanfeng Automotive Interiors |
| Plastic Omnium SE |
| FLEX-N-GATE Corporation |
| Aisin Corporation |
| FORVIA (Faurecia) |
| Others |
Value Chain & Pricing Dynamics
Tier-one OEM procurement consolidation across Detroit Three and German premium platforms anchors contract-based long-term offtake pricing with volume-tiered discounts. This buyer concentration compresses margin pools for injection molders locked into fixed-price agreements while rewarding compounders with active airflow bundling capabilities.
Pricing Analysis
Margin tightening in commodity polypropylene shield tiers reflects crude oil feedstock volatility and long-term OEM contract rigidity. Three-tier pricing structure across active-integrated, thermal-acoustic composite, and standard polypropylene levels separates chassis systems bundlers from regional molders. Cost-down pressure on standalone shield suppliers accelerates because EV platform standardization eliminates brand-specific engineering premiums. Fleet procurement aggregators exhibit highest price sensitivity; tier-one integrators with chassis bundling capabilities demonstrate lowest.
Supply Chain Analysis
Platform certification timelines and REACH phthalate compliance documentation gate supplier access to BMW, Volkswagen, and Detroit Three engineering centers. Manufacturing gravity centers on Germany, the United States, and Japan for tier-one integrators; South Korea and India feed regional domestic volume. Polypropylene resin and glass-reinforced nylon compounds constitute primary material inputs, with bio-based plasticizer alternatives gaining traction. Single-source vulnerability concentrates in CAE simulation talent pools for underbody airflow modeling. Distribution runs through OEM tier-one supplier portals and fleet management national agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as platform certification timelines and dual-cavity tooling capex requirements force mid-tier molders toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from software-defined aerodynamic tuning decoupling hardware from value capture. Deepen chassis systems bundling through active airflow integration to defend against standalone shield commoditization. Prioritize closed-loop polypropylene recovery capabilities ahead of EPA recyclability mandate enforcement. For New Entrants and Emerging Players: Launch via PLI scheme partnerships with Maruti Suzuki and Tata Motors in India automotive manufacturing corridors. Target domestic molding capacity in Chennai and Pune clusters where import substitution policies create white-space entry. Pursue thermal-acoustic composite specialization for EV battery enclosure sealing applications. For Investors and Strategic Acquirers: The window for entry favors compounders with glass-reinforced nylon formulation expertise and active airflow R&D pipelines. Mid-tier molders with OEM platform access but strained balance sheets represent prime acquisition targets. Watch for battery enclosure sealing requirement harmonization across EPA and EU regulatory frameworks as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Active Airflow Integration | Magna International and Plastic Omnium capture chassis systems bundling value through motorized aerodynamic elements. |
| Closed-Loop Polypropylene Recovery | Suppliers with in-house recycling capabilities align with EPA automotive efficiency recyclability thresholds. |
| Glass-Reinforced Nylon Qualification | Toyota Boshoku specifications for thermal-acoustic composites displace commodity polypropylene in high-impact zones. |
| India Domestic Molding Capacity | BIS standards alignment and PLI incentives enable platform access to Maruti Suzuki and Tata Motors procurement. |
| Bio-Based Plasticizer Reformulation | ECHA REACH enforcement on phthalate restrictions forces polymer reformulation for European market access retention. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and CAE simulation specialists. EPA vehicle efficiency standard documents, NHTSA crashworthiness test reports, ECHA REACH amendment filings, and BIS automotive component standards formed the regulatory backbone. Bottom-up production capacity modeling triangulated against top-down OEM procurement spend estimates.
Segment-level volume and value outputs reconciled vehicle production databases, IHS Markit registration data, and tier-one supplier revenue disclosures across the projection horizon. Modeling dimensions spanned propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from compound annual trajectory fitting to qualified supplier revenue recognition timelines and platform rollout schedules. EV battery enclosure sealing integration trends and software-defined aerodynamic tuning adoption curves informed scenario weighting.
Polypropylene feedstock price volatility, REACH regulatory amendment timing, and EV platform certification delays are the dominant revision risks to forecast assumptions. A model refresh is warranted upon material change in EPA automotive efficiency standard enforcement stringency or battery enclosure thermal management boundary specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Face Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respirator Filter Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market