
 North America Explosion-Proof Equipment Market | 2026-2036
North America Explosion-Proof Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Explosion-Proof Equipment Market Analytics
Canada is reshaping regional supply dynamics through expanded manufacturing capacity for hazardous location electrical equipment serving Alberta oil sands and Saskatchewan potash operations. Eaton Corporation leverages its integrated electrical portfolio to anchor large-scale petrochemical project bids across the Gulf Coast. Honeywell International Inc. sustains technology leadership through advanced gas detection systems bundled with explosion-proof control architectures. MSA Safety Incorporated dominates self-contained breathing apparatus and fixed gas monitoring integration in underground mining applications.
Explosion-proof equipment denotes electrical and mechanical apparatus engineered to contain internal ignition of flammable gases, vapors, or combustible dusts without transmitting combustion to the surrounding hazardous atmosphere, typically certified under NEC/CEC Class I Division 1 or Zone 0/1/2 designations with temperature codes limiting surface thermal energy. Flameproof enclosures represent the largest installed base across North American refineries due to proven reliability in hydrogen-rich process streams, while intrinsic safety technology captures the fastest growth trajectory in pharmaceutical cleanrooms and battery manufacturing facilities where low-energy signaling limits ignition risk. Permanent installation systems command the dominant revenue share given capital-intensive infrastructure commitments, though portable explosion-proof lighting experiences accelerated replacement cycles in turnaround maintenance contexts.
OSHA Process Safety Management standards and NFPA 70 National Electrical Code classifications govern hazardous location equipment specification across United States industrial facilities, while Canadian Electrical Code Section 18 and provincial jurisdictional authorities enforce parallel certification requirements through CSA Group standards. The EPA's methane emissions reduction framework and emerging state-level hydrogen hub investments are redirecting procurement specifications toward equipment rated for hydrogen service and extended temperature ranges. Stakeholders must monitor evolving IECEx-ATEX alignment pressures and hydrogen-specific ignition energy thresholds as fuel transition strategies reshape certification demand across North American energy infrastructure.
Market Dynamics
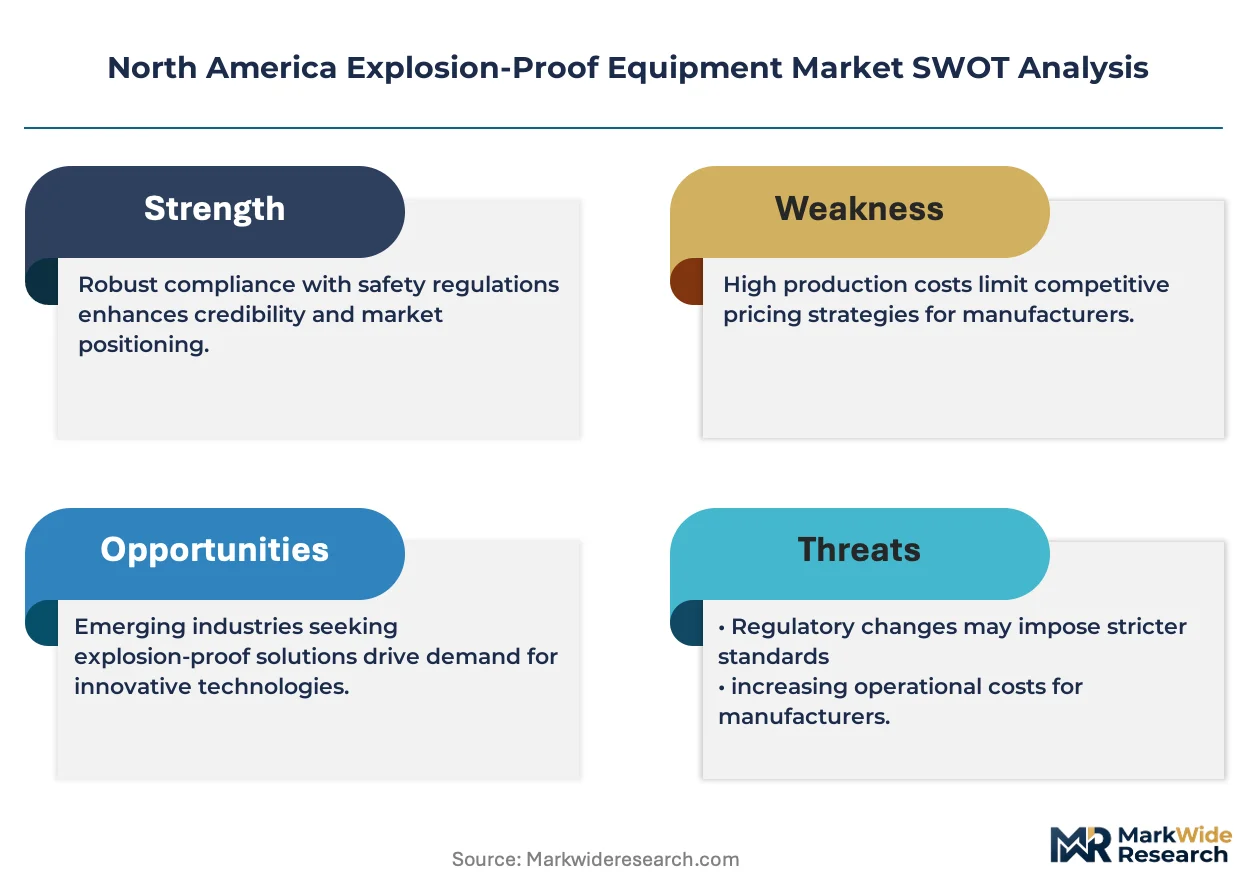
OSHA enforcement of combustible dust standards and EPA methane reduction rules are tightening certification requirements for hazardous location equipment, forcing upstream oil and gas operators to accelerate replacement cycles for legacy explosion-proof infrastructure.
Growth Catalysts
- EPA Methane Emissions Framework:The agency's methane reduction rules are redirecting procurement specifications toward equipment rated for hydrogen service and extended temperature ranges across Permian Basin operations.
- Texas and Louisiana Petrochemical Clusters:Expansion of LNG export terminal construction and downstream chemical processing capacity is driving demand for flameproof enclosures and intrinsically safe lighting systems.
- Intrinsic Safety Technology:Low-energy signaling protocols are capturing accelerated adoption in pharmaceutical cleanrooms and battery manufacturing facilities where ignition risk minimization is paramount.
Market Restraints
- Copper and Aluminum Input Volatility:Raw material price swings for enclosure-grade metals compress margin predictability for electrical housing manufacturers serving hazardous location markets.
- Certification Body Concentration:CSA Group and UL Solutions dominate third-party testing for NEC/CEC compliance, creating bottlenecks for new product introductions requiring dual certification.
- Extended Lead Times for Zone 0 Equipment:Specialized manufacturing capacity for highest-protection-category apparatus remains geographically concentrated, limiting supply elasticity during demand surges.
Strategic Opportunities
- Alberta Oil Sands Electrification:Canadian operators are expanding procurement of hazardous location electrical equipment as steam-assisted gravity drainage facilities modernize power distribution infrastructure.
- Hydrogen Hub Infrastructure:State-level hydrogen investments are creating demand for explosion-proof equipment rated to hydrogen-specific ignition energy thresholds not covered by legacy natural gas certifications.
- IIoT Sensor Integration:Convergence of wireless gas detection networks with explosion-proof control architectures enables predictive maintenance models in refinery process units.
Industry Challenges
- IECEx-ATEX Alignment Complexity:Equipment manufacturers face dual-track engineering requirements as North American certification standards diverge from European harmonization pressures.
- Legacy System Integration:Brownfield installations in Gulf Coast refineries require specialized interface engineering between new intrinsically safe systems and existing Class I Division 1 infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Explosion-Proof Equipment Market |
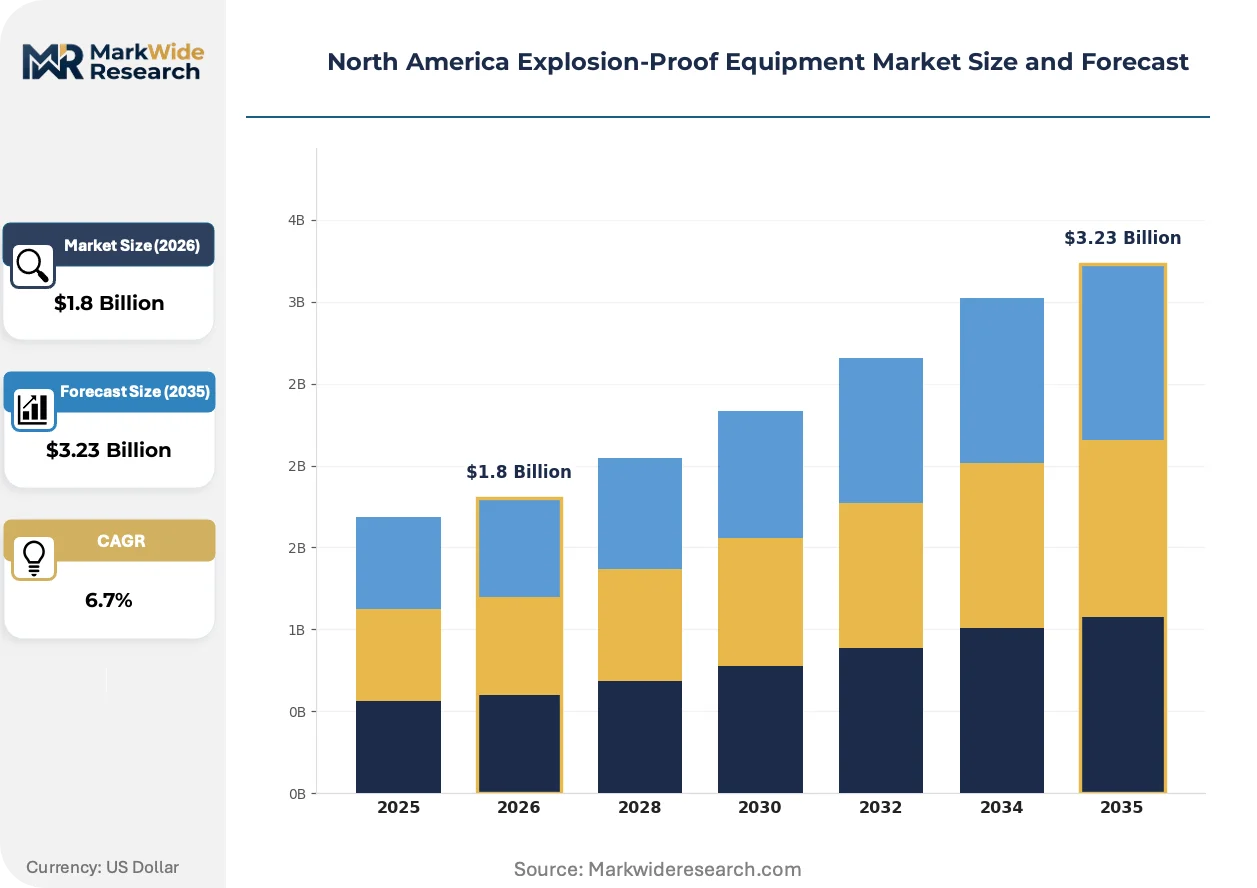
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting, Enclosures, Junction Boxes, Switches Technology: Intrinsic Safety, Flameproof, Increased Safety, Pressurized End User: Oil & Gas, Chemical, Mining, Pharmaceuticals Installation: Permanent, Portable, Temporary, Fixed |
| Companies Covered | R. STAHL Inc., Honeywell International Inc., Adalet Inc., EX Industries, Larson Electronics LLC, MSA Safety Incorporated, Eaton Corporation, Rockwell Automation Inc., Intertek Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Explosion-Proof Equipment Market Evolving Landscape
Wireless gas detection networks and solid-state lighting architectures are compressing maintenance cycles and enabling predictive safety models across hazardous location installations.
LED-based explosion-proof lighting systems are replacing legacy high-pressure sodium and metal halide fixtures in refinery process units. Downstream operators in Texas and Louisiana are specifying solid-state luminaires for turnaround maintenance contexts where portable lighting replacement cycles have accelerated. This transition is rendering obsolete the established aftermarket revenue streams tied to lamp replacement and ballast servicing.
OSHA Process Safety Management standards are mandating more granular documentation of hazardous location equipment specifications. Industrial facilities must now maintain detailed records of temperature codes and protection methods for every installed apparatus. Refinery operators in the Gulf Coast region are responding by consolidating vendor relationships to simplify compliance auditing and certification traceability.
Integrated service contracts are displacing transactional equipment sales in large-scale petrochemical project bids. Engineering procurement and construction firms are bundling explosion-proof electrical systems with multi-year maintenance agreements. This pattern concentrates in greenfield LNG export terminal developments where operational continuity guarantees override upfront capital cost minimization.
North America Explosion-Proof Equipment Market Segmentation
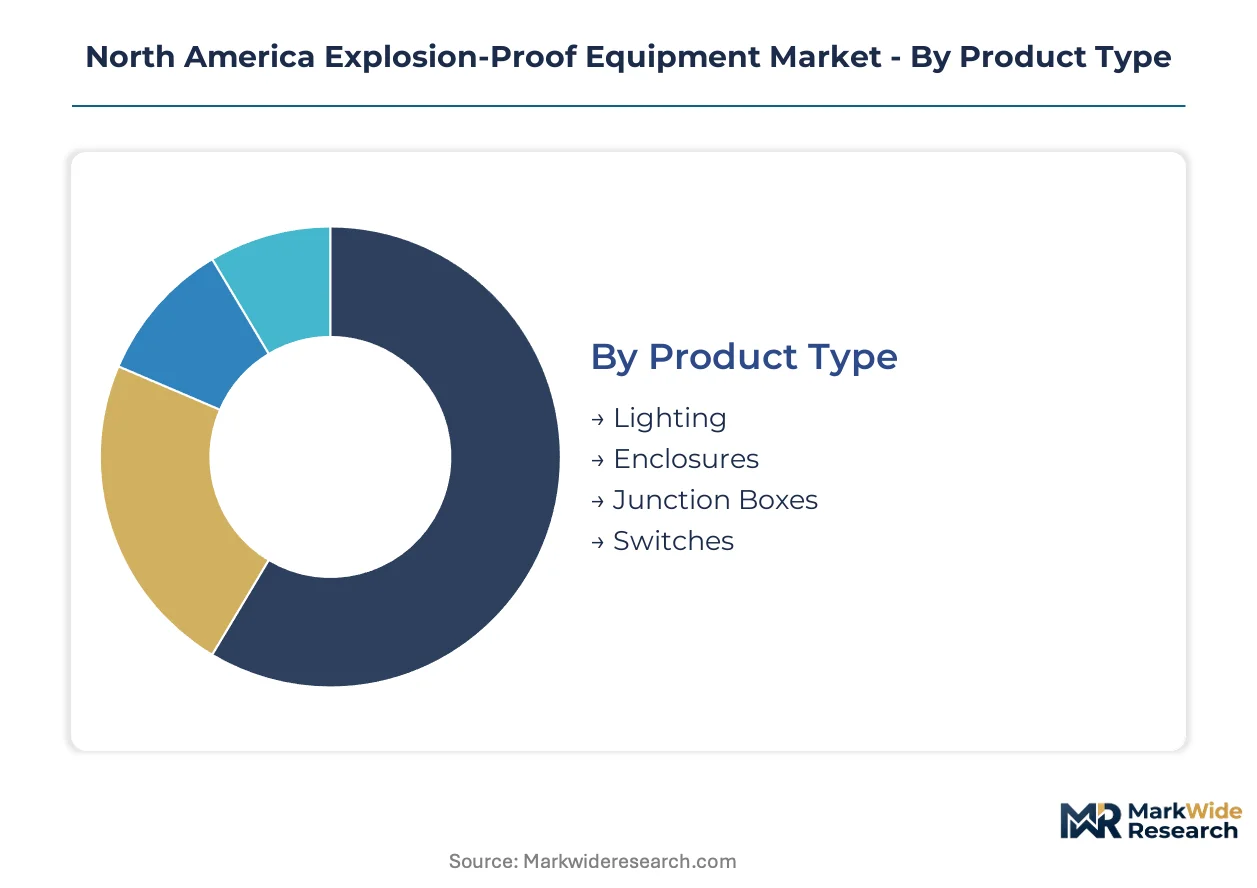
Explosion-proof equipment procurement in North America follows distinct technical hierarchies shaped by hazardous location classifications, ignition energy thresholds, and regional regulatory enforcement. Segmentation reveals where capital concentrates versus where specification standards are tightening fastest.
Product Type:
Mature enclosure architectures dominate installed base value, while solid-state lighting platforms capture specification momentum in greenfield developments.
- Lighting:LED-based explosion-proof luminaires are displacing high-pressure sodium fixtures across Gulf Coast refinery turnarounds. Texas and Louisiana operators specify solid-state architectures for maintenance cycle compression in process unit retrofits.
- Enclosures:Flameproof housings contain internal ignition of hydrogen-rich atmospheres without transmitting combustion to surrounding areas. Permian Basin upstream operators are expanding procurement of cast aluminum and stainless steel variants rated for Class I Division 1 service.
- Junction Boxes:Terminal enclosures for hazardous location cable management serve petrochemical cluster expansion across Alberta oil sands electrification projects.
- Switches:Heavy-duty disconnect and control stations rated for Zone 1/2 environments support mining automation in Saskatchewan potash operations.
Enclosures handle the majority of throughput; lighting is the fastest mover on share.
Technology:
Cost tier differentiation separates capital-intensive flameproof systems from lower-installed-cost intrinsic safety approaches in cleanroom and battery manufacturing contexts.
- Intrinsic Safety:Low-energy signaling protocols limit ignition risk through voltage and current restriction rather than containment. Pharmaceutical cleanrooms in New Jersey and North Carolina battery gigafactories specify these systems for personnel safety in hydrogen-adjacent processes.
- Flameproof:Robust enclosure designs withstand internal explosions and prevent flame transmission to external atmospheres. Gulf Coast refineries specify these for hydrogen service as EPA methane rules redirect procurement toward extended temperature range ratings.
- Increased Safety:Enhanced construction techniques prevent arcs and sparks in normal operation. Canadian oil sands operators deploy these for motor terminal boxes and heating systems in steam-assisted gravity drainage facilities.
- Pressurized:Purged and pressurized enclosures maintain positive internal pressure to exclude hazardous atmospheres. Analytical instrumentation shelters in Louisiana chemical plants use these for continuous gas monitoring systems.
Flameproof technology anchors capital deployment; intrinsic safety is expanding most quickly in pharmaceutical and advanced manufacturing specifications.
End User:
Application severity drives specification divergence between continuous-process hydrocarbon infrastructure and batch-oriented chemical synthesis operations.
- Oil & Gas:Upstream, midstream, and downstream hydrocarbon operations require equipment rated for hydrogen sulfide exposure and wide ambient temperature ranges. Permian Basin drilling contractors and Texas LNG export terminal developers anchor regional demand concentration.
- Chemical:Petrochemical crackers, ammonia synthesis, and specialty chemical producers specify equipment for corrosive atmospheres and cyclic thermal loading. Louisiana chemical corridor expansion sustains replacement cycles for legacy infrastructure.
- Mining:Underground coal and hard rock operations require MSHA-compliant apparatus for methane and combustible dust environments. Saskatchewan potash and Appalachian coal basins drive procurement of portable lighting and fixed gas monitoring integration.
- Pharmaceuticals:Solvent handling and hydrogenation processes in active pharmaceutical ingredient manufacturing demand intrinsically safe instrumentation. New Jersey and Pennsylvania manufacturing clusters specify these for OSHA Process Safety Management compliance.
Oil and gas commands the largest equipment throughput; pharmaceutical applications are climbing the fastest on specification intensity.
Installation:
Customer type splits between capital-intensive permanent infrastructure and maintenance-driven portable replacement cycles.
- Permanent:Hardwired systems integrated into facility power distribution and process control architectures. Greenfield LNG terminals and refinery expansion projects specify these with multi-year service contracts bundled into engineering procurement.
- Portable:Battery-powered and cord-connected equipment for turnaround maintenance and confined space entry. Gulf Coast refinery contractors accelerate replacement cycles for LED work lights and ventilation equipment.
- Temporary:Rental and short-duration installations for construction phases and emergency response. Alberta oil sands project developers specify these during facility commissioning before permanent systems activate.
- Fixed:Stationary apparatus mounted on structures or equipment skids with dedicated power feeds. Chemical plant process units deploy these for continuous gas detection and alarm annunciation systems.
Permanent installation dominates capital allocation; portable equipment is gaining share fastest in maintenance and turnaround service markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA anchors hazardous location equipment demand across the United States, where the Permian Basin and Gulf Coast petrochemical corridor generate the dominant procurement volumes for flameproof enclosures and intrinsically safe systems.
United States
Texas and Louisiana concentrate equipment demand through LNG export terminal construction and refinery expansion projects. EPA methane reduction rules redirect procurement toward hydrogen-rated apparatus with extended temperature certifications. Houston and Lake Charles anchor the Gulf Coast petrochemical cluster where integrated service contracts bundle explosion-proof electrical systems with multi-year maintenance agreements.
Canada
Alberta oil sands electrification and Saskatchewan potash mining drive procurement of hazardous location electrical equipment for steam-assisted gravity drainage facilities. Canadian Electrical Code Section 18 and CSA Group standards enforce parallel certification requirements to NEC classifications. Edmonton and Fort McMurray host expanding manufacturing capacity for enclosure-grade metals serving western Canadian energy infrastructure.
Mexico
Pemex refinery modernization and private-sector petrochemical joint ventures in Tamaulipas and Veracruz create demand for Zone-rated apparatus. The country's national petroleum regulator and energy ministry coordinate hazardous location standards alignment with North American trade frameworks. Altamira and Coatzacoalcos industrial corridors attract cross-border equipment suppliers from Texas-based distributors.
California
Battery manufacturing gigafactories and pharmaceutical cleanrooms in the San Francisco Bay Area and Los Angeles Basin specify intrinsically safe instrumentation for hydrogen-adjacent processes. Cal/OSHA Process Safety Management enforcement mirrors federal standards with additional state-level chemical facility safety requirements. Fremont and San Diego clusters drive specification intensity for low-energy signaling protocols in advanced manufacturing contexts.
North America Explosion-Proof Equipment Market Competitive Landscape
Integrated electrical conglomerates and specialized hazardous location fabricators split the market across distinct capability tiers. The vendor base concentrates around full-portfolio suppliers capable of anchoring large-scale petrochemical project bids alongside focused specialists dominating narrow application segments. Two archetypes dominate: diversified industrial conglomerates bundling explosion-proof systems with power distribution infrastructure, and safety-focused specialists concentrating on gas detection and personal protective equipment integration. Competitive moves center on integrated service contract expansion and manufacturing capacity additions for hydrogen-rated equipment categories.
Within the diversified conglomerate tier, Eaton Corporation and Honeywell International Inc. exemplify full-portfolio positioning across electrical infrastructure and safety system integration. MSA Safety Incorporated occupies the specialist archetype, anchoring personal safety equipment and fixed gas monitoring applications. These three entities represent the dominant competitive anchors across distinct strategic vectors in North American hazardous location markets.
| Leading Market Players |
|---|
| R. STAHL Inc. |
| Honeywell International Inc. |
| Adalet Inc. |
| EX Industries |
| Larson Electronics LLC |
| MSA Safety Incorporated |
| Eaton Corporation |
| Rockwell Automation Inc. |
| Intertek Group PLC |
| Others |
Value Network & Pricing Analysis
The Houston Ship Channel freight corridor transmits cost volatility from Gulf Coast petrochemical clusters through to downstream price differentiation, as enclosure-grade aluminum and copper shipments from Canadian smelters concentrate supply leverage among integrated electrical conglomerates serving Permian Basin operators.
Pricing Analysis
Texas-to-Alberta price spreads widen during peak turnaround seasons as Gulf Coast refineries absorb premium logistics costs for Zone 0-rated apparatus. Project-based contract pricing dominates large-scale LNG terminal developments, with differentiation anchored in UL versus CSA dual-certification status and bundled multi-year service agreements. Cost compression in standard enclosure tiers intensifies as Chinese aluminum extrusions penetrate mid-market specifications. EPC contractors prove least price-sensitive, prioritizing operational continuity guarantees over capital cost minimization.
Supply Chain Analysis
Extended payment terms from integrated service contract structures are concentrating working capital demands on mid-tier enclosure fabricators serving Alberta oil sands electrification. Supply concentrates in the United States, Canada, and Mexico under USMCA frameworks, with critical dependence on Chilean copper cathode, Chinese rare earth magnet feedstock, and domestic cast aluminum foundry capacity. Single-source vulnerability around CSA Group certification testing creates bottleneck risk for new product introductions. Distribution runs through authorized electrical distributor networks anchored in Houston, Edmonton, and Chicago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across hydrogen-rated equipment categories creates niche opportunities as EPA methane rules redirect procurement specifications beyond legacy natural gas certifications.
For Market Incumbents: Insulate core Gulf Coast refinery relationships through captive manufacturing capacity for hydrogen-specific ignition energy thresholds, while accelerating CSA Group pre-certification investments to bottleneck competitor product introductions. Threat substitution from solid-state lighting architectures demands defensive bundling of LED luminaires with legacy enclosure maintenance contracts. For New Entrants and Emerging Players: Establish a beachhead in Saskatchewan potash mining automation, where MSHA-compliant portable lighting specifications remain underserved by integrated conglomerates focused on downstream petrochemical volumes. Target intrinsically safe instrumentation for battery manufacturing gigafactories through direct specification relationships with EPC contractors in California and Texas. For Investors and Strategic Acquirers: Specialized hazardous location fabricators with CSA Group testing laboratory relationships represent prime acquisition targets as certification body concentration intensifies scarcity value. Long-term viability hinges on hydrogen hub infrastructure deployment trajectories across state-level investment programs. Monitor IECEx-ATEX alignment regulatory drafts as inflection signals for engineering cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cast Aluminum Foundry Capacity | Captive supply of enclosure-grade metal insulates margin pressure from LME volatility. |
| CSA Group Pre-Certification Investment | Early testing access accelerates product launch timelines for hydrogen-rated apparatus categories. |
| Integrated Service Contract Expansion | Multi-year maintenance bundling displaces transactional sales in greenfield LNG terminal developments. |
| IIoT Sensor Platform Integration | Wireless gas detection convergence enables predictive maintenance revenue streams in refinery process units. |
| Alberta Manufacturing Footprint Addition | Proximate capacity to oil sands electrification projects compresses logistics cost and lead time. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of OSHA enforcement databases, EPA methane rulemaking dockets, NEC/CEC code revision records, and customs trade data for enclosure-grade metal imports. Plant engineers at Gulf Coast refineries, procurement leads at Alberta oil sands operators, EPC contractor technical directors, and aftermarket service managers provided structured input. Bottom-up equipment shipment analysis triangulates against top-down capital expenditure tracking across petrochemical cluster developments.
Forecast inputs incorporate protection method segmentation, hazardous location class distribution, hydrogen service rating adoption curves, and regional regulatory enforcement intensity across the projection horizon. CAGRs derive from weighted scenario modeling of LNG terminal construction pipelines and refinery turnaround cycles. Modeled dimensions span product type, technology tier, end-use industry, installation category, and state-level hydrogen hub participation.
Sensitivities concentrate around EPA methane rule implementation timing, copper price volatility, and IECEx-ATEX harmonization pressures. Forecasts reflect documented assumptions regarding certification body capacity expansion and trade framework continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Spill Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market