
 Coiled Tubing Manufacturing Market | 2026-2036
Coiled Tubing Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Coiled Tubing Manufacturing Market Intelligence
Aftermarket service revenue is reconfiguring margin distribution across the coiled tubing value chain. Halliburton leverages its integrated well intervention portfolio to capture recurring service attach rates. SLB anchors its position through proprietary continuous-tubing metallurgy and downhole tool integration. Baker Hughes differentiates via geographic density in North American shale basins.
Coiled tubing manufacturing produces continuous-length, seam-welded tubulars typically ranging from 0.75 to 3.5 inches in outer diameter, engineered for repeated deployment into live wellbores under cyclic fatigue conditions. Standard coiled tubing and heavy wall coiled tubing together dominate installed base volumes, while composite coiled tubing represents the fastest-expanding material segment as operators pursue corrosion resistance in sour-gas environments. Steel alloy retains the largest share of raw material consumption, though nickel alloy grades gain traction in high-pressure, high-temperature applications.
API 5ST governs dimensional and mechanical specifications for coiled tubing in the United States, while the EU F-Gas Regulation and REACH framework constrain fluoropolymer-based composite formulations in European supply chains. Saudi Arabia's national oil company procurement standards and China's GB standards for petroleum equipment collectively shape export market access requirements. Stakeholders must monitor regulatory divergence between API-centric North American specifications and emerging national standards in Middle Eastern and Asian markets.

Market Dynamics
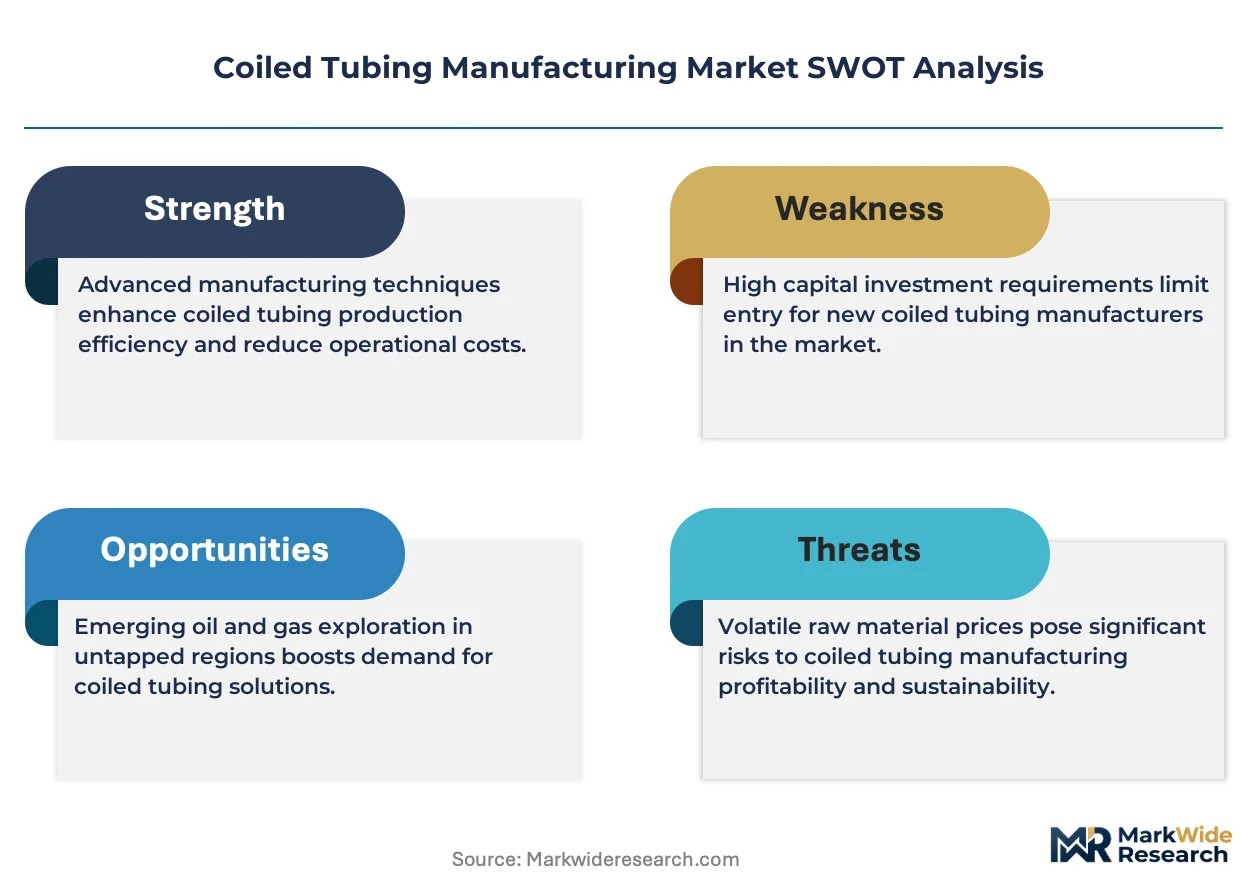
API 5ST specification compliance is compressing supplier margins while simultaneously erecting barriers to entry for non-certified producers. Continuous-milled steel alloy advances and composite material substitution are redistributing competitive advantage toward metallurgy-integrated manufacturers.
Growth Catalysts
- Shale formation development:Operators in the Permian Basin and Saudi Arabian unconventional fields deploy extended-reach laterals requiring longer continuous tubing strings. Fatigue-resistant alloys enable deeper, more complex well architectures.
- REACH framework adaptation:European supply chain reconfiguration toward fluoropolymer-free composite formulations is accelerating corrosion-resistant product development. Manufacturers achieving early compliance capture premium positioning in EU aftermarket channels.
- Continuous-milled processing:Seam-weld elimination through advanced rolling technology improves burst pressure ratings and cycle life. Downhole tool integrators specify these grades for high-pressure, high-temperature applications.
Market Restraints
- Nickel alloy cost volatility:HPHT-grade raw material price swings compress margin predictability for specialty tubing producers. Spot market exposure disproportionately affects mid-cap manufacturers without captive supply.
- Supply concentration in North American steel:Domestic mill capacity constraints for oil country tubular goods create lead time uncertainty. Import alternatives face Section 232 tariff exposure and anti-dumping duty risk.
- Composite fatigue life limitations:Glass and carbon fiber-reinforced thermoplastic pressure barriers exhibit axial load degradation under cyclic bending. Sour-gas operators retain steel preference for critical intervention strings.
Strategic Opportunities
- GB standards alignment:China's petroleum equipment certification requirements for imported coiled tubing create first-mover advantage for early registrants. State-owned operator procurement favors pre-qualified foreign suppliers.
- Subsea intervention systems:Deepwater well access from floating platforms demands corrosion-resistant, lightweight continuous tubing. Composite formulations meeting NORSOK specifications address vessel deck load constraints.
- Digital thread integration:RFID-embedded tubing tracking converges with predictive fatigue modeling to enable condition-based replacement. Service companies monetize data-driven asset management subscriptions.
Industry Challenges
- API 5ST certification timelines:Third-party inspection bottlenecks and destructive testing requirements extend new product qualification to 18-24 months. Smaller manufacturers lack capital to maintain parallel qualification pipelines.
- Metallurgical talent scarcity:Continuous-milled process engineering expertise concentrates at legacy integrated mills. Independent producers compete for finite welding and heat-treatment specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coiled Tubing Manufacturing Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Coiled Tubing, Heavy Wall Coiled Tubing, Composite Coiled Tubing, Coiled Tubing for Hydraulic Fracturing Material: Steel Alloy, Nickel Alloy, Titanium Alloy, Polymer Composites Application: Well Intervention, Drilling, Completion Services, Production Enhancement End User: Oil & Gas Operators, Service Companies, Research Institutions, Independent Producers |
| Companies Covered | Halliburton, Wellpro Group, SLB, LiMAR Oil Tools, Jereh Energy Services, Baker Hughes, Weatherford International, Hunting PLC, NOV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coiled Tubing Manufacturing Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory fragmentation are compressing traditional product lifecycles while opening adjacent application spaces. Manufacturers must simultaneously defend steel alloy dominance and cultivate composite capabilities.
Thermoplastic composite pressure barriers are collapsing the historical performance gap with steel in sour-gas environments. Offshore operators in the North Sea and Gulf of Mexico specify these grades for reduced deck weight and elimination of corrosion inhibitors. The technology is collapsing capital intensity requirements for subsea intervention vessel outfitting.
The EU F-Gas Regulation and its national implementing measures are constraining fluoropolymer liner availability for composite tubing. Manufacturers reformulating with polyamide and polyethylene barrier layers face 12-18 month requalification cycles. European supply chains are responding through backward integration into polymer compounding and accelerated REACH-compliant material development.
Integrated service contracts are unbundling equipment supply from intervention operations. National oil companies in Saudi Arabia and Abu Dhabi now procure tubing strings separately from downhole services, compressing manufacturer margins while expanding addressable market volume. This procurement model shift is most visible in Middle Eastern long-term framework agreements where operators seek to optimize capital versus operating expenditure allocation.
Coiled Tubing Manufacturing Market Segmentation
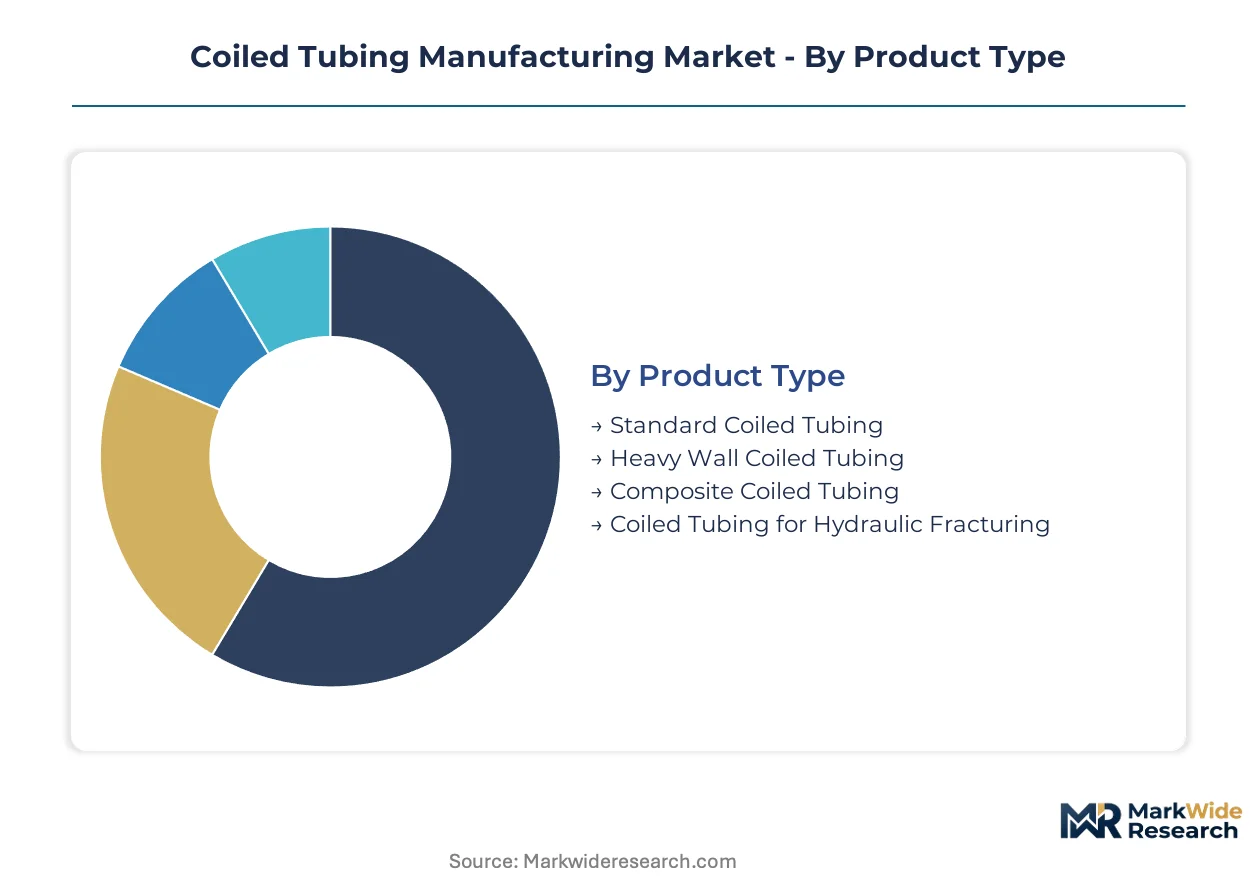
Segmentation in coiled tubing manufacturing directly shapes aftermarket service economics. Intervention frequency, string replacement cycles, and inspection intensity vary dramatically across product grades and material formulations, redistributing lifetime value capture between manufacturers and field service providers.
Product Type:
After-sales-service intensity climbs with wall thickness and composite complexity, creating divergent margin profiles across the installed base.
- Standard Coiled Tubing:Seam-welded carbon steel tubulars meeting API 5ST dimensional tolerances dominate high-volume well intervention programs. Permian Basin operators deploy these strings for routine nitrogen lifts and acid squeezes, driving replacement demand through cycle-fatigue accumulation rather than corrosion failure.
- Heavy Wall Coiled Tubing:Thicker-wall constructions withstand higher internal pressures for extended-reach horizontal interventions. Saudi Aramco's unconventional development in the Jafurah Basin specifies these grades for deeper coiled-tubing drilling operations where burst ratings determine operational feasibility.
- Composite Coiled Tubing:Glass and carbon fiber-reinforced thermoplastic constructions eliminate corrosion inhibitors in sour-gas applications. North Sea operators specify these for reduced deck loading on intervention vessels.
- Coiled Tubing for Hydraulic Fracturing:High-fatigue-alloy formulations engineered for repeated plug millout operations in multistage completions. Extended lateral lengths in West Texas shale drive continuous-length requirements exceeding standard mill capabilities.
By volume, Standard Coiled Tubing leads. By growth pace, Composite Coiled Tubing is ahead.
Material:
Raw material cost tiers stratify manufacturing economics and field replacement economics in opposing directions.
- Steel Alloy:Continuous-milled low-alloy grades retain dominant share through balance of fatigue resistance and cost predictability. Domestic mill concentration in the United States creates supply vulnerability for non-integrated manufacturers.
- Nickel Alloy:HPHT-capable formulations withstand temperatures exceeding 175°C and H2S partial pressures above 10 psi. Chevron's Gulf of Mexico deepwater developments specify these strings where steel sulfide stress cracking risks operational failure.
- Titanium Alloy:Lightweight, corrosion-immune constructions for subsea intervention from dynamically positioned vessels. Norwegian Continental Shelf operators trial these grades to reduce crane load limits and enable deeper water access.
- Polymer Composites:Thermoplastic pressure barriers with fiber reinforcement eliminate metallic corrosion entirely. EU F-Gas Regulation compliance requirements are accelerating fluoropolymer-free formulation development.
Steel Alloy commands the volume base. Nickel Alloy captures the steepest expansion trajectory as HPHT drilling intensifies.
Application:
Application mix determines string utilization rates and inspection protocol rigor, directly affecting manufacturer attach rates for telemetry and fatigue monitoring services.
- Well Intervention:Live-well deployment for stimulation, cleanout, and mechanical operations represents the core revenue pool. Cyclic bending over gooseneck injectors drives predictable replacement scheduling.
- Drilling:Coiled-tubing drilling for slimhole re-entry and unconventional pilot holes demands specialized bottomhole assembly integration. Directional drilling contractors specify continuous-milled grades for improved torque transmission.
- Completion Services:Sand control, packer setting, and perforating operations require pressure-rated strings with real-time downhole communication capability.
- Production Enhancement:Velocity string installation and gas lift conversions extend well life in mature fields. Marginal well economics favor standard-grade tubing with minimal premium specifications.
Well Intervention generates the largest installed base. Drilling applications are climbing fastest as lateral lengths extend.
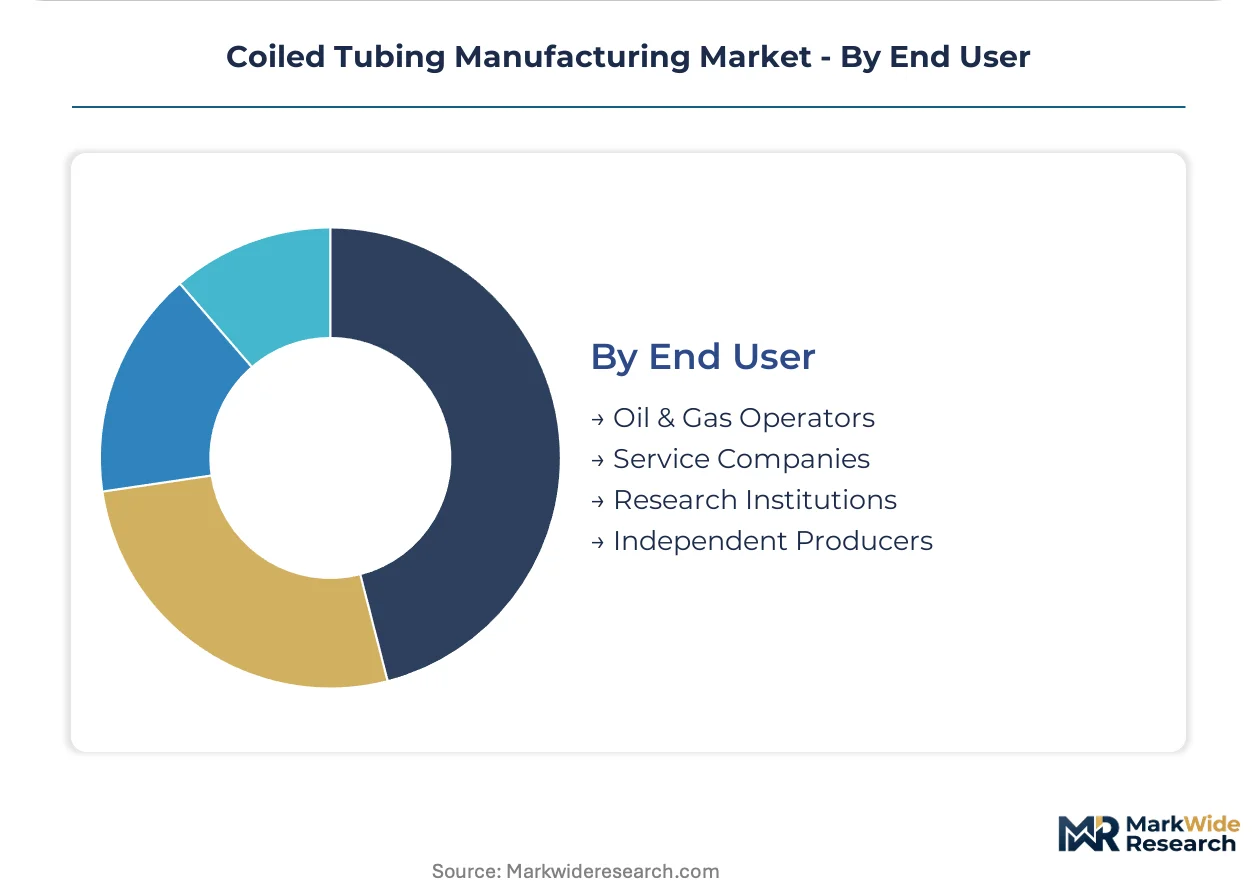
End User:
Procurement sophistication and technical specification authority concentrate differently across operator types, fragmenting sales channel requirements.
- Oil & Gas Operators:Integrated majors and national oil companies wield specification authority and framework agreement leverage. Saudi Aramco's unbundled procurement model separates tubing supply from intervention services.
- Service Companies:Halliburton, SLB, and Baker Hughes maintain captive tubing fleets and specify manufacturer grades for fleet standardization. These entities capture recurring revenue through string rental and fatigue management subscriptions.
- Research Institutions:Limited-volume procurement for metallurgical testing and qualification protocol development. Sandia National Laboratories operates specialized fatigue testing facilities for composite validation.
- Independent Producers:Price-sensitive spot purchasing for single-well interventions without long-term fleet commitments. These operators drive demand for standard-grade reconditioned strings.
Service Companies dominate tubing consumption by unit volume. Independent Producers are expanding fastest as private-equity-backed drilling programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Permian Basin exhibit acute price sensitivity for standard-grade strings, while North Sea operators absorb substantial premiums for corrosion-resistant composites. This elasticity divergence fragments regional pricing architectures and reshapes where manufacturers concentrate premium versus volume production.
United States
Permian Basin operators deploy extended-reach laterals exceeding 15,000 feet, driving demand for fatigue-resistant continuous-milled alloys. API 5ST compliance creates inspection bottlenecks that extend qualification timelines. Houston anchors domestic manufacturing clusters where Halliburton and Baker Hughes coordinate fleet standardization with regional mills.
Saudi Arabia
Jafurah Basin unconventional development requires heavy-wall constructions for deeper coiled-tubing drilling operations. Saudi Aramco's unbundled procurement separates tubing supply from intervention services, compressing manufacturer margins. Dammam industrial corridors concentrate qualification facilities serving state-owned operator framework agreements.
China
Shale formation development in Sichuan and Xinjiang drives demand for high-pressure-rated strings. GB standards for petroleum equipment create registration barriers for imported products. Shanghai and Tianjin manufacturing zones host domestic producers expanding into Southeast Asian export markets.
Norway
North Sea subsea intervention demands lightweight composite formulations reducing vessel deck loads. NORSOK specifications constrain material selection for deepwater applications. Stavanger and Bergen clusters trial titanium alloy grades to access deeper water depths from dynamically positioned vessels.
Germany
EU F-Gas Regulation accelerates fluoropolymer-free composite development for sour-gas environments. REACH framework compliance requires 12-18 month requalification cycles for reformulated barrier layers. Ruhr industrial regions concentrate polymer compounding capabilities serving continental aftermarket channels.
Coiled Tubing Manufacturing Market Key Industry Players
Capability concentration sits with integrated service companies possessing proprietary metallurgy and downhole tool integration expertise; scale advantage sits with independent manufacturers supplying standardized grades to spot markets. The vendor base stratifies across three tiers: captive fleet operators, qualified independent producers, and regional fabricators serving price-sensitive independents. Dominant competitive moves include backward integration into polymer compounding for EU compliance and strategic partnerships with national oil companies for framework agreement positioning.
Among integrated service providers, Halliburton, SLB, and Baker Hughes exemplify the capability-concentrated tier. Halliburton leverages its integrated well intervention portfolio to capture recurring service attach rates. SLB anchors its position through proprietary continuous-tubing metallurgy expertise. Baker Hughes differentiates via geographic density in North American shale basins. These entities represent the archetype of manufacturers monetizing data-driven asset management subscriptions alongside equipment supply.
| Leading Market Players |
|---|
| Halliburton |
| Wellpro Group |
| SLB |
| LiMAR Oil Tools |
| Jereh Energy Services |
| Baker Hughes |
| Weatherford International |
| Hunting PLC |
| NOV |
| Others |
Cost & Logistics Intelligence
Houston's concentrated mill capacity for oil country tubular goods creates asymmetric pricing power that favors integrated service companies over independent manufacturers. Domestic capacity constraints for continuous-milled steel alloys compress margins for spot-market purchasers while reinforcing long-term contract premiums.
Pricing Analysis
Long-term framework agreements with national oil companies anchor volume pricing, while spot procurement for single-well interventions commands substantial premiums. Three-tier pricing structure across premium continuous-milled grades, standard API 5ST-certified strings, and reconditioned economy tiers reflects certification investment and fatigue-resistance differentials. Cost compression in standard-grade segments is intensifying because Permian Basin operators unbundle tubing supply from intervention services. Independent producers exhibit acute price sensitivity, whereas North Sea offshore operators absorb premiums for corrosion-resistant composite formulations.
Supply Chain Analysis
Continuous-cast steel slab feedstock draws from domestic United States mills, Chinese GB-certified producers, and European specialty alloy suppliers. Raw material dependencies center on low-alloy steel billets, nickel-bearing HPHT grades, and fluoropolymer-free thermoplastic barrier layers. Single-source vulnerability concentrates in North American seamless pipe capacity for heavy-wall constructions. Distribution runs through manufacturer-direct fleet sales to integrated service companies, with aftermarket channels serving spot-market independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as extended-reach lateral drilling in unconventional basins accelerates coiled-tubing utilization rates beyond replacement-cycle norms.
For Market Incumbents: Harden API 5ST certification pipelines against third-party inspection bottlenecks that extend qualification timelines to 18-24 months. Deepen backward integration into continuous-milled steel production to offset domestic mill capacity constraints and Section 232 tariff exposure. Capture metallurgical talent scarcity through apprenticeship partnerships with legacy integrated mills.
For New Entrants and Emerging Players: China's GB standards alignment for petroleum equipment certification represents the most penetrable entry point, as state-owned operator procurement favors pre-qualified foreign suppliers. Subsea intervention systems for North Sea and Gulf of Mexico deepwater applications offer white-space opportunity where NORSOK-compliant composite formulations address vessel deck load constraints. Pursue strategic partnerships with national oil companies in Saudi Arabia and Abu Dhabi for framework agreement positioning.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oilfield service companies divesting non-core tubing manufacturing assets to focus on digital service platforms. Long-term viability hinges on manufacturers simultaneously defending steel alloy dominance and cultivating composite capabilities. Monitor Saudi Aramco's unbundled procurement model adoption as the signal for margin compression versus volume expansion trade-offs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Ensures EU F-Gas Regulation compliance for fluoropolymer-free composite barrier layers. |
| Continuous-Milled Process Capacity Expansion | Eliminates seam-weld fatigue points for HPHT applications specified by Chevron and SLB. |
| RFID-Embedded Tubing Tracking Platform | Enables predictive fatigue modeling subscriptions monetized by Halliburton and Baker Hughes. |
| GB Standards Registration for China Market | Unlocks state-owned operator procurement in Sichuan and Xinjiang shale developments. |
| Titanium Alloy Qualification for Subsea | Addresses Norwegian Continental Shelf crane load limits for deeper water access. |
Research Approach
A standing panel of coiled-tubing manufacturing executives, well intervention service managers, national oil company procurement leads, and continuous-milled metallurgy engineers provided ongoing calibration across primary fieldwork. Secondary validation drew from API specification databases, SEC 10-K filings of integrated service companies, Saudi Aramco procurement disclosures, and customs records for oil country tubular goods trade flows. Bottom-up tubing string deployment estimates triangulated against top-down shale drilling activity indices.
Scenario-bracketing anchored volume projections across the analysis window, with segmentation dimensions spanning product type, material grade, application intensity, and end-user procurement sophistication. CAGRs derived from regression against historical replacement-cycle data and lateral-length extension trajectories. Forecast inputs incorporated continuous-milled alloy adoption curves and REACH-compliant composite reformulation timelines.
Practitioners should monitor nickel alloy spot price volatility, API 5ST certification queue lengths, and Saudi Aramco procurement unbundling velocity for early signals requiring forecast revision. Cross-checking against EIA drilling completion statistics and IHS Markit well intervention databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
Agricultural Pipes and Tubes Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Heat Shrink Tubing Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Copper Tube Market