
 Artificial Plants and Flowers Market | 2026-2036
Artificial Plants and Flowers Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Plants and Flowers Market Analysis
Aftermarket service revenue from commercial installation and seasonal refresh programs is reshaping margin distribution across the artificial plants and flowers value chain. Nearly Natural Inc leverages direct-to-consumer digital channels to sustain premium positioning in residential décor. Commercial Silk anchors its competitive position through specification relationships with hospitality procurement teams. Dongyi Artificial Plants Co Ltd dominates manufacturing scale, operating integrated molding and finishing facilities that control cost structures for plastic-based product lines.
Artificial plants and flowers comprise synthetic or preserved botanical replicas manufactured from injection-molded polyethylene, polyurethane-coated silk fibers, or latex foam substrates, designed to simulate natural morphology without irrigation, light, or climate dependency. Silk and fabric materials command margin premiums due to tactile authenticity and compliance with REACH phthalate restrictions, while plastic variants retain volume leadership through landscaping and large-format commercial applications. Event planners and interior designers represent the fastest-growing customer type, with wholesale procurement patterns shifting toward customized plant arrangements for branded environments and experiential retail spaces.
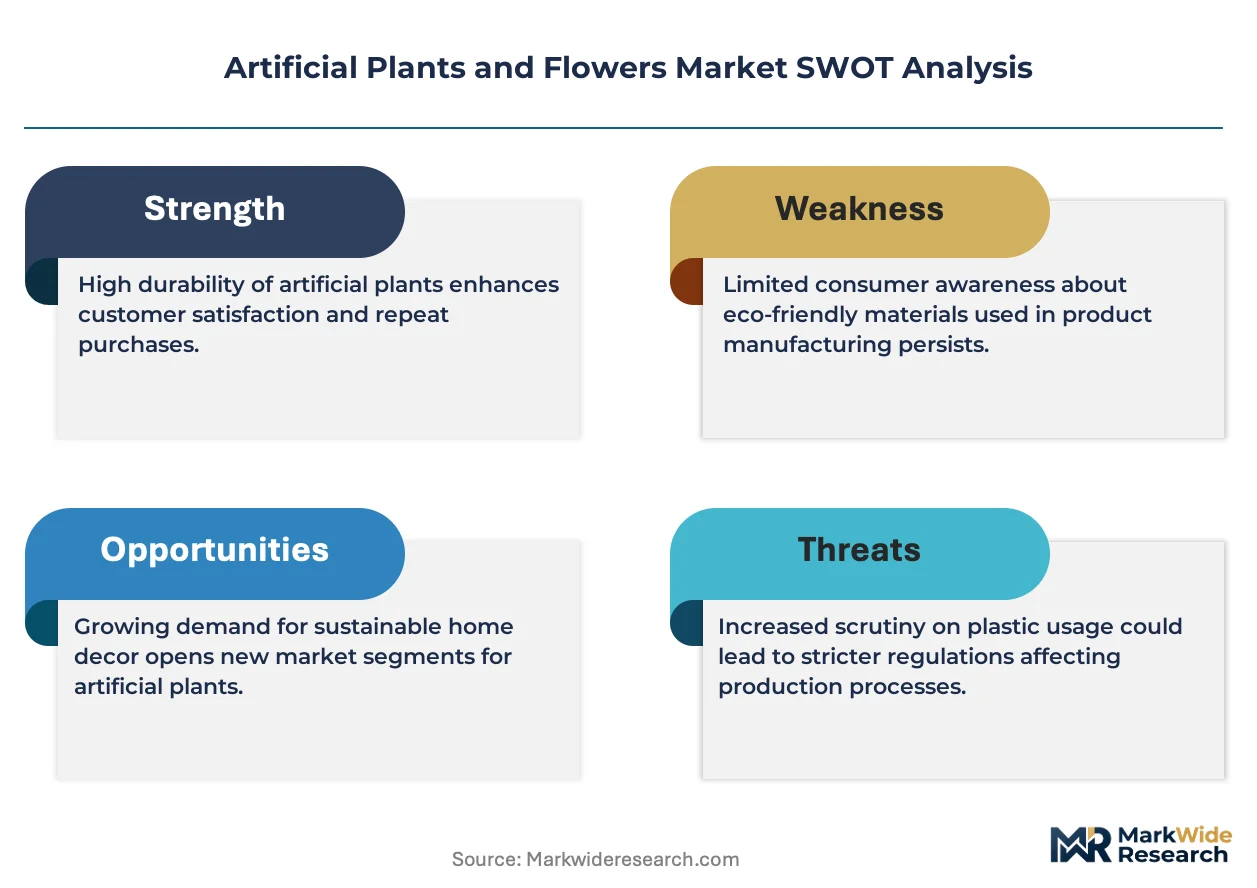
The EU REACH regulation and California Proposition 65 framework restrict volatile organic compound emissions and heavy metal content in synthetic foliage, compelling material transitions toward certified foam and fabric substrates. The US Consumer Product Safety Commission monitors flammability standards for artificial greenery deployed in commercial interiors, particularly hospitality and entertainment venues. Stakeholders must monitor evolving chemical compliance thresholds and assess captive sourcing of silk and recycled polyethylene to secure supply continuity against regulatory tightening.
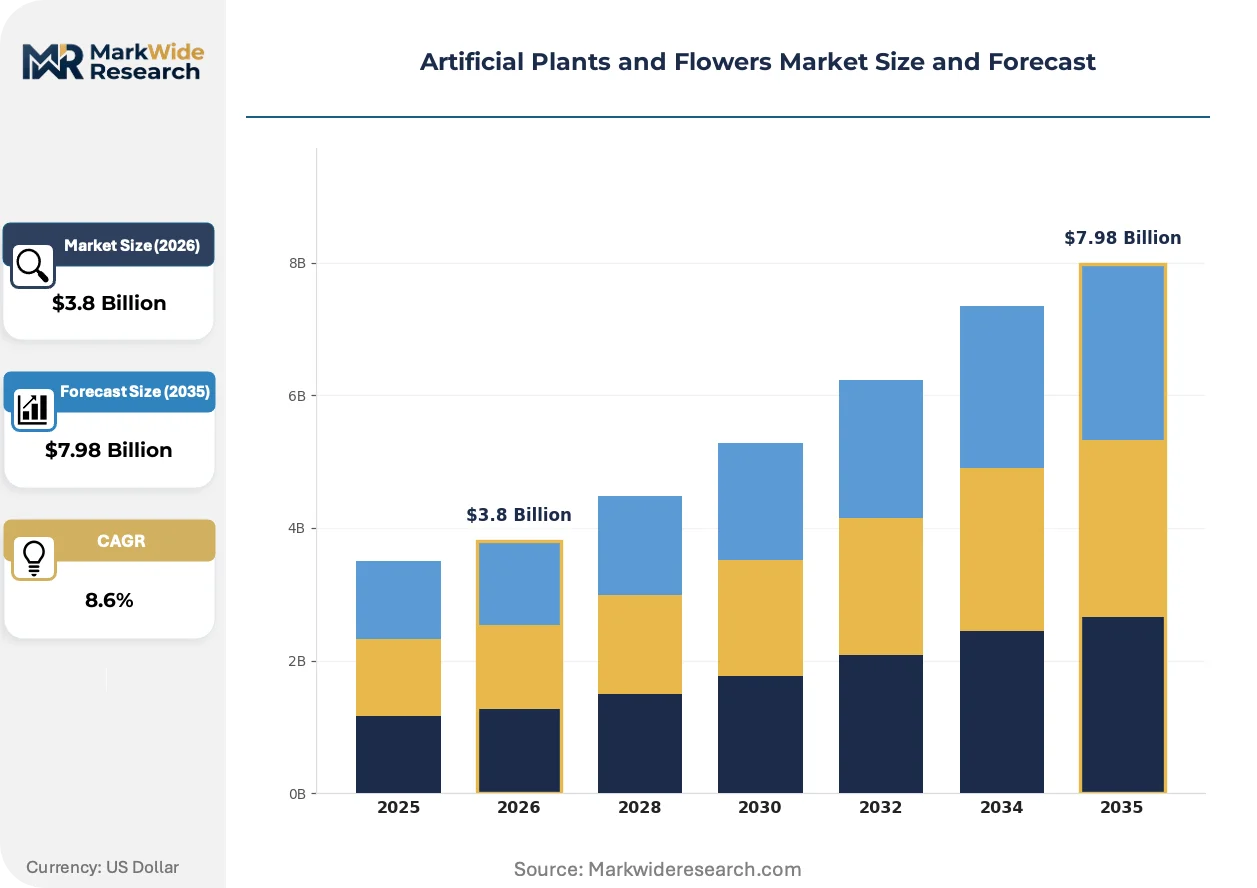
Market Dynamics
EU REACH phthalate restrictions and California Proposition 65 frameworks are forcing material transitions across the artificial plants and flowers supply chain, compressing margins for plastic-based producers while elevating silk and fabric alternatives.
Growth Catalysts
- Hospitality procurement mandates:Hotel chains specify artificial greenery for lobbies and guest rooms to eliminate irrigation infrastructure and reduce maintenance labor costs.
- REACH compliance transitions:ECHA restrictions on volatile organic compounds accelerate certified foam and fabric substrate adoption among European distributors.
- Guangdong-Zhejiang production clusters:Integrated molding and finishing facilities in these Chinese provinces control cost structures for high-volume polyethylene product lines.
Market Restraints
- Petroleum input volatility:Injection-molded polyethylene and polyurethane-coated silk fibers face margin pressure from crude oil price fluctuations.
- Single-source silk dependency:Certified fabric substrate supply concentrates in limited Asian processing facilities, creating captive sourcing risk.
- Flammability certification friction:US Consumer Product Safety Commission standards for commercial interiors extend product approval timelines.
Strategic Opportunities
- Experiential retail installations:Branded environment designers seek customized plant arrangements for pop-up stores and flagship concepts.
- Seasonal refresh service contracts:Commercial installation and maintenance programs generate recurring revenue streams beyond initial product sales.
- Recycled polyethylene mandates:EU Green Deal circular economy requirements create preferential sourcing status for post-consumer content suppliers.
Industry Challenges
- Material science talent scarcity:Formulation chemists with polymer and textile coating expertise command premium compensation in competing industries.
- Multi-jurisdiction certification complexity:Simultaneous compliance with REACH, Proposition 65, and CPSC flammability standards requires dedicated regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Plants and Flowers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flowers, Shrubs, Trees, Plant Arrangements Material: Plastic, Silk, Fabric, Foam Application: Home Décor, Office Décor, Event Decoration, Landscaping Customer Type: Retail Consumers, Wholesalers, Event Planners, Interior Designers |
| Companies Covered | Commercial Silk, Silk Plants Direct, Nearly Natural Inc, Maxifleur Kunstplanten, Artificial Plants Unlimited, Dongyi Artificial Plants Co Ltd, Autograph Foliages, FeelReal, Sunwing Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Plants and Flowers Market Emerging Trajectories
Material science advances and procurement model evolution are compressing traditional competitive advantages in artificial botanicals, rewarding suppliers with captive substrate capabilities and direct specification relationships.
Biomimetic latex foam substrates with micro-textured surface engineering are collapsing the authenticity gap between synthetic and preserved botanicals. Hospitality procurement teams specify these materials for guest-facing installations where tactile inspection occurs. The technology is collapsing price premiums previously commanded by European silk weavers.
REACH Annex XVII phthalate restrictions and associated ECHA guidance documents are eliminating conventional plasticizer formulations from EU-bound product lines. Manufacturers pivot toward citrate-based plasticizers and unplasticized polymer grades, extending R&D cycles by 8-14 months. German and French distributors now require full material disclosure documentation upstream of purchase orders.
Event planners and interior designers increasingly bypass wholesale distributors for direct factory relationships, compressing traditional margin layers. Dongyi Artificial Plants and Sunwing Industries field dedicated specification teams for North American and European design firms. This channel shift concentrates volume with vertically integrated Chinese producers possessing in-house molding, finishing, and logistics capabilities.
Artificial Plants and Flowers Market Segmentation
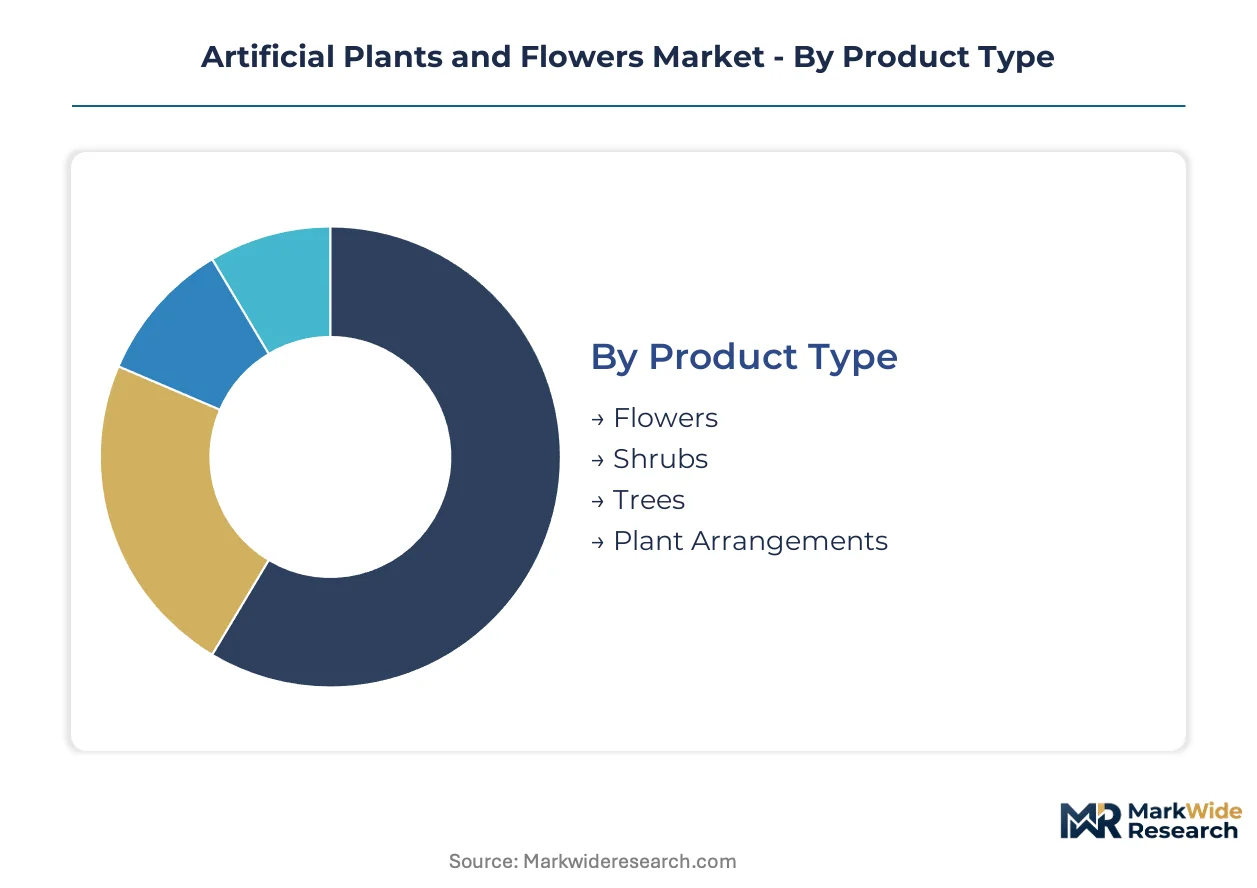
Segmentation in artificial botanicals determines service model intensity, with commercial installations demanding ongoing refresh contracts while residential purchases remain transactional. Material composition and end-use application together dictate margin architecture across the value chain.
Product Type:
After-sales service intensity varies sharply across product categories, with large-format installations requiring recurring maintenance contracts versus single-purchase residential items.
- Flowers:Individual stem and bouquet replicas utilize injection-molded polyethylene petals with wire-reinforced stems for poseability. Demand clusters in event decoration and residential tabletop arrangements, where seasonal color rotation drives repeat procurement cycles.
- Trees:Architectural-scale specimens ranging from tabletop ficus to 12-foot palms employ steel armatures wrapped in polyurethane-coated foliage. Hospitality lobbies and corporate atriums specify these for permanent installations with multi-year maintenance agreements, generating sustained service revenue.
- Shrubs:Compact hedge and bush replicas serve landscaping and space-division applications.
- Plant Arrangements:Pre-composed container installations combine multiple botanical types for turnkey deployment.
By volume, Flowers leads. By growth pace, Trees is climbing the fastest.
Material:
Cost tier stratification separates premium substrates from commodity grades, with certification requirements widening the price spread between compliant and conventional formulations.
- Plastic:Injection-molded polyethylene and polypropylene variants dominate volume through weather resistance and cost efficiency. Landscaping and large-format commercial applications specify these materials, though REACH phthalate restrictions are compressing margins for EU-bound production.
- Silk:Natural protein fiber substrates coated with polyurethane or latex deliver tactile authenticity for guest-facing hospitality installations. European distributors command premium positioning through certified supply chains, with Dongyi and Sunwing capturing specification relationships directly.
- Fabric:Polyester and cotton-polyester blends offer mid-tier positioning between plastic economy and silk premium.
- Foam:Biomimetic latex foam substrates with micro-textured surfaces are collapsing authenticity gaps previously held by European silk weavers.
Plastic retains volume leadership. Silk commands the steepest price expansion trajectory.
Application:
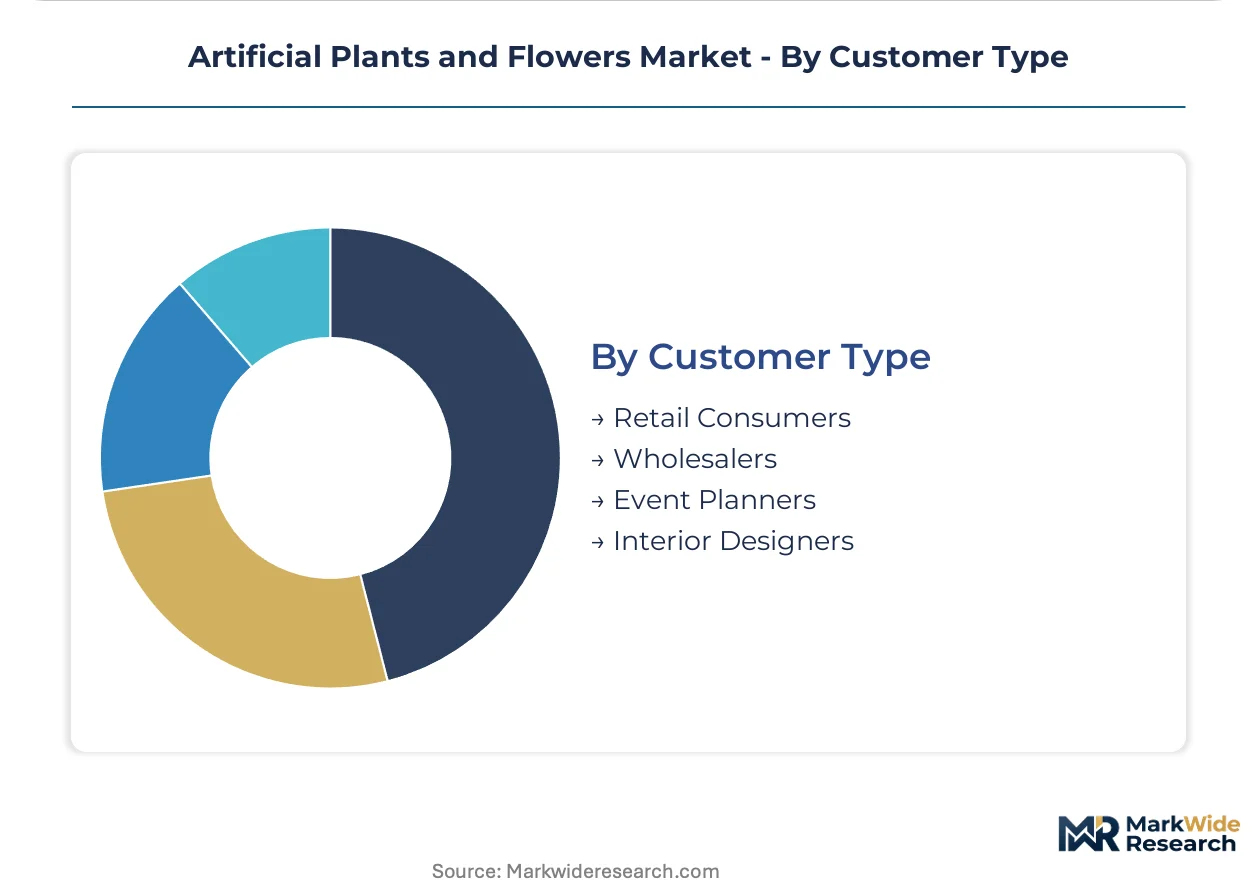
Customer type concentration shapes procurement patterns, with institutional buyers demanding specification support and residential consumers prioritizing visual accessibility.
- Event Decoration:Temporary installations for weddings, corporate functions, and experiential retail demand rapid deployment and strike capabilities. Event planners bypass wholesale distributors for direct factory relationships, compressing traditional margin layers.
- Home Décor:Residential tabletop, shelf, and wall-mounted botanicals sell through direct-to-consumer digital channels. Nearly Natural anchors this segment through premium positioning and visual merchandising investment.
- Office Décor:Corporate reception and workspace installations balance durability with aesthetic requirements.
- Landscaping:Exterior-grade synthetic greenery for commercial and municipal environments emphasizes UV stability and weather resistance.
Home Décor leads by unit volume. Event Decoration is gaining share fastest.
Customer Type:
Procurement authority concentration determines channel strategy, with specification influencers commanding preferential pricing and technical support resources.
- Interior Designers:Commercial and residential specification professionals influence material selection and sourcing decisions. Design firms increasingly field dedicated teams for direct factory engagement, particularly with Guangdong and Zhejiang producers offering integrated molding and finishing capabilities.
- Event Planners:Time-sensitive procurement for temporary installations prioritizes logistics reliability and customization responsiveness over unit economics.
- Retail Consumers:Individual purchasers through e-commerce and specialty retail channels.
- Wholesalers:Traditional distribution intermediaries facing margin compression from direct manufacturer relationships.
Retail Consumers dominate transaction volume. Interior Designers show the steepest procurement value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in artificial botanicals varies sharply by end-use, with hospitality procurement teams absorbing premiums for fire-rated materials while residential buyers in emerging markets gravitate toward entry-grade polyethylene variants.
United States
Hospitality chains and corporate office managers drive specification demand for CPSC-compliant fire-rated installations. California Proposition 65 enforcement continues tightening VOC disclosure requirements for synthetic foliage sold in-state. Los Angeles and Miami serve as design hubs where interior specification firms maintain direct sourcing relationships with Asian manufacturers.
China
Guangdong and Zhejiang provinces anchor global production capacity through integrated molding, finishing, and logistics facilities serving export markets. The MIIT oversees industrial standards for synthetic materials while provincial environmental bureaus enforce emissions controls on coating operations. Dongyi Artificial Plants Co Ltd and Sunwing Industries Limited maintain manufacturing clusters in these regions with captive substrate capabilities.
Germany
REACH Annex XVII compliance mandates dominate procurement criteria for distributors serving hospitality and retail sectors across the EU. ECHA guidance on phthalate restrictions forces material transitions toward citrate-based plasticizers and unplasticized polymer grades. Frankfurt and Hamburg host specification houses that demand full material disclosure documentation upstream of purchase orders.
United Kingdom
Post-Brexit regulatory divergence creates dual-track compliance requirements for importers serving both UK and EU markets. The Office for Product Safety and Standards monitors flammability standards for commercial interior applications. London-based design studios increasingly bypass wholesale distributors for direct factory engagement with Chinese producers.
India
Rising disposable income in metropolitan centers fuels residential décor demand for mid-tier fabric and plastic botanicals. The BIS maintains voluntary standards for textile-based artificial plants while import duties on Chinese finished goods protect domestic assemblers. Mumbai and Delhi-NCR concentrate retail distribution and e-commerce fulfillment infrastructure for the subcontinent.
Artificial Plants and Flowers Market Vendor Landscape
Capability concentration sits with vertically integrated manufacturers possessing in-house substrate formulation; scale advantage sits with high-volume molders serving commodity landscaping applications. The vendor base separates into three tiers: premium specification houses commanding hospitality procurement relationships, mid-market direct-to-consumer brands, and OEM suppliers executing private-label contracts. Dominant competitive moves include backward integration into certified foam and fabric substrate production, plus geographic expansion through dedicated specification teams in North American and European design markets.
Within the premium-tier specification segment, Commercial Silk and Nearly Natural Inc exemplify divergent channel strategies—one anchoring hospitality procurement relationships, the other leveraging digital direct-to-consumer positioning. Dongyi Artificial Plants Co Ltd represents the scale-driven manufacturing archetype with integrated Guangdong facilities. These three occupy positions spanning the value chain from raw substrate through finished installation.
| Leading Market Players |
|---|
| Commercial Silk |
| Silk Plants Direct |
| Nearly Natural Inc |
| Maxifleur Kunstplanten |
| Artificial Plants Unlimited |
| Dongyi Artificial Plants Co Ltd |
| Autograph Foliages |
| FeelReal |
| Sunwing Industries Limited |
| Others |
Supply Flow & Price Mechanics
Guangdong and Zhejiang production clusters anchor global polyethylene foliage capacity, concentrating molding and finishing capabilities that translate into asymmetric pricing power for integrated Chinese manufacturers serving hospitality procurement teams.
Pricing Analysis
Seasonal refresh service contracts and multi-year maintenance agreements drive lifetime value beyond initial product sales. Three-tier pricing structure across premium silk, certified fabric, and commodity plastic tiers separates hospitality specification buyers from residential consumers and landscaping contractors. Price differentiation rests on REACH compliance certification and fire-rating status, with margins tightening for plastic variants facing phthalate reformulation costs. Residential retail consumers exhibit highest price sensitivity, while hospitality procurement teams absorb premiums for CPSC-compliant installations.
Supply Chain Analysis
Petroleum-derived feedstocks—polyethylene pellets, polyurethane resins, and latex foam precursors—anchor material cost structures for injection-molded and coated substrates. Manufacturing concentrates in China, with secondary silk processing clusters in India and Thailand. Supply chain risk centers on single-source dependency for certified fabric substrates in limited Asian finishing facilities. Distribution runs through direct factory relationships with North American and European design firms, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where commercial installation and seasonal refresh programs expand faster than transactional product sales, rewarding suppliers with recurring revenue infrastructure.
For Market Incumbents: Harden specification relationships with hospitality procurement teams through captive substrate certification and dedicated technical support teams. Deepen backward integration into biomimetic foam formulation to defend margin position against European silk weavers. Lock in multi-year service contracts with corporate facility managers to create switching costs.
For New Entrants and Emerging Players: India's metropolitan retail corridors offer underpenetrated white-space for mid-tier fabric botanicals as disposable income rises. Experiential retail installation designers represent a specification entry point with lower incumbent saturation. Pursue direct-to-designer digital platforms with rapid customization turnaround to bypass established wholesale channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with in-house molding and REACH-compliant substrate capabilities over pure-brand distributors. Long-term viability hinges on circular economy compliance and recycled polyethylene sourcing infrastructure. Watch for EU Green Deal recycled content mandates as inflection indicator for preferential supplier status.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Substrates | Captive foam and fabric production secures REACH compliance and compresses cost structures for hospitality specifications. |
| Direct-to-Designer Channel Expansion | Bypassing wholesale distributors captures margin layers and accelerates specification influence with North American and European design firms. |
| Seasonal Refresh Service Infrastructure | Recurring maintenance contracts with hotel chains and corporate campuses generate predictable revenue streams beyond initial installation sales. |
| Recycled Polyethylene Sourcing Program | EU Green Deal circular economy requirements create preferential procurement status for post-consumer content suppliers. |
| Biomimetic Surface Engineering R&D | Micro-textured latex foam substrates collapse authenticity gaps previously held by European silk weavers at lower production cost. |
Methodological Framework
A standing panel of hospitality procurement directors, interior specification designers, event planning agency heads, and synthetic materials plant managers provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation through customs trade databases, hospitality industry procurement reports, and ECHA regulatory guidance documents. Bottom-up volume modeling and top-down value triangulation anchored market size estimation.
Scenario-bracketing framed analytical projections across the analysis window, with segmentation dimensions spanning product type, material composition, end-use application, and customer procurement authority. CAGRs derived from elasticity-adjusted demand curves incorporating hospitality construction cycles, regulatory compliance cost pass-through rates, and petroleum input price volatility. Modeled inputs included REACH phthalate restriction implementation timelines and recycled content mandate adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-scale fabric processors would shift competitive outcomes beyond modeled ranges. Cross-checking against hospitality capital expenditure surveys and interior design firm procurement panel data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Bird House Market
Home & Garden
Preserved Flowers Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
United States Lawn Care Market
Home & Garden
Artificial Plants Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Flower Box Market
Home & Garden
Artificial Flowers Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Landscaping Services Market
Home & Garden
Candle Market
Home & Garden
Global Wind Chime Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
Europe Flower Pots Market