
 United States Landscaping Market | 2026-2036
United States Landscaping Market Size, Share, and Industry Trends Forecast 2026-2036
United States Landscaping Market Analytics
Hispanic immigrant labor availability is reorganizing service capacity across the United States landscaping industry, with seasonal visa bottlenecks and wage compression forcing contractors toward mechanized alternatives. BrightView Holdings Inc. leverages its national footprint and centralized training academies to sustain crew productivity in tight labor markets. TruGreen Inc. competes through technology-enabled route optimization and proprietary fertilization protocols. The Davey Tree Expert Company anchors its position in high-margin arboriculture services where certified arborist credentials create pricing power.
Landscaping encompasses the design, installation, and ongoing maintenance of outdoor environments through biological elements such as turfgrass, ornamental plantings, and trees combined with structural hardscapes including pavers, retaining walls, and drainage systems, typically executed with specified soil depths of 4–12 inches for turf and engineered base courses of 6–8 inches for pedestrian hardscapes. Its primary commercial purpose centers on enhancing property aesthetics, managing stormwater runoff, reducing ambient temperatures through vegetative cover, and preserving asset values for real estate portfolios. Lawn Maintenance represents the largest revenue pool by service type due to recurring contract structures and low customer switching costs, while Irrigation Installation commands premium margins as municipalities tighten water restrictions and property owners face escalating utility penalties. The Residential end user segment leads in transaction volume though Commercial clients generate superior per-site economics through multi-year maintenance agreements and integrated design-build contracts.
EPA stormwater regulations under the Clean Water Act shape erosion control and runoff management requirements for commercial developments, while OSHA mandates govern worker exposure to pesticides, heat illness prevention, and powered equipment operation across landscaping crews. State-level drought ordinances in California, Arizona, and Nevada directly restrict turfgrass installation and mandate flow-rate limits on irrigation systems, redirecting contractor specialization toward native plant palettes and subsurface drip technologies. Stakeholders must monitor evolving municipal water budgets and building code amendments that increasingly tie landscape plans to energy efficiency certifications and carbon accounting disclosures.
Market Dynamics
Water-use ordinances across drought-prone states are compressing traditional turfgrass maintenance revenues while redirecting contractor specialization toward xeriscaping and smart irrigation retrofits. This regulatory pressure is restructuring service mix and capital allocation across the industry.
Growth Catalysts
- EPA Stormwater Regulations:The Clean Water Act mandates for commercial developments expand demand for erosion control and permeable hardscape installations that manage runoff.
- Smart Irrigation Technology:Flow-rate limits and utility penalties in California, Arizona, and Nevada accelerate retrofit demand for soil-moisture sensors and weather-based controllers.
- Commercial Property Managers:Multi-year grounds maintenance contracts provide recurring revenue stability and lower customer acquisition costs for established contractors.
Market Restraints
- Fuel and Equipment Costs:Diesel-powered mowers and commercial-grade utility vehicles expose margins to petroleum price volatility with limited pass-through mechanisms.
- H-2B Visa Bottlenecks:Seasonal worker program caps constrain crew scaling during peak spring installation windows across the Sun Belt.
- Synthetic Turf Substitution:Artificial grass installations in sports facilities and municipal properties reduce long-term maintenance contract opportunities for biological turf specialists.
Strategic Opportunities
- Arboriculture Services:Certified arborist credentials unlock premium pricing in tree risk assessment and preservation consulting for municipal and utility clients.
- Subsurface Drip Irrigation:Convergence of pressure-compensating emitters with IoT soil monitoring creates service bundles for water-budget-constrained California municipalities.
- Native Plant Palettes:State-level drought ordinances generate design-build opportunities for contractors with botanical expertise in region-specific xerophytic species.
Industry Challenges
- Certified Arborist Shortage:The credential pipeline cannot match demand for tree risk assessment services, compressing expansion timelines for high-margin service lines.
- Heat Illness Compliance:OSHA mandates for outdoor worker protection require supervisory training and rest-protocol investments that elevate fixed costs.
- Legacy Equipment Integration:Retrofitting existing mower fleets with GPS route optimization and fuel-monitoring hardware creates downtime and compatibility friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Landscaping Market |
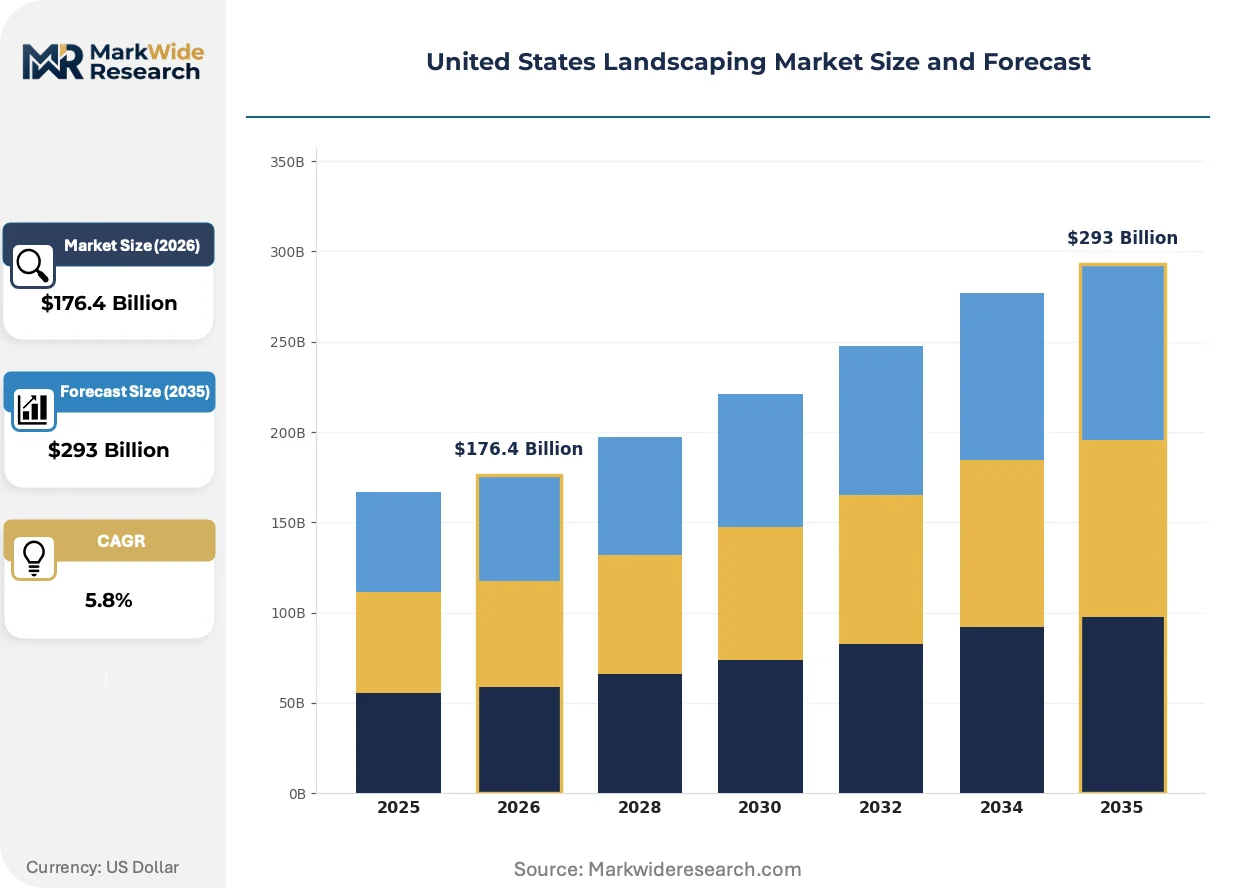
| Market Size in 2026 | $176.4 Billion |
| Market Size in 2035 | $293 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Lawn Maintenance, Landscape Design, Irrigation Installation, Tree Trimming End User: Residential, Commercial, Government, Agricultural Product Type: Plants, Soil, Mulch, Hardscapes Delivery Model: In-House, Subcontractor, Online, Franchise |
| Companies Covered | BrightView Holdings Inc., TruGreen Inc., The Davey Tree Expert Company, The F.A. Bartlett Tree Expert Company, Yellowstone Landscape, Gothic Landscape Inc., Park West Companies, Aspen Grove Landscape Group, Ruppert Landscape Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Landscaping Market Evolving Landscape
Electrification of commercial grounds equipment is disrupting traditional fleet economics while water scarcity mandates accelerate biological design alternatives. These forces are compressing conventional maintenance margins and rewarding contractors with technical specialization.
Battery-powered commercial mowers and handheld equipment are displacing gasoline equivalents in municipal and corporate campus fleets. California municipalities and Fortune 500 campus managers are adopting zero-emission mandates for grounds maintenance contracts. This electrification is displacing small-engine repair networks and petroleum distribution relationships that anchored traditional contractor supplier structures.
OSHA heat illness prevention standards and EPA pesticide exposure limits are tightening operational protocols for outdoor crews. These mandates elevate supervisory training burdens and documentation requirements across commercial landscaping operations. Texas and Florida contractors are responding with GPS-tracked rest-break compliance systems and automated pesticide application logging.
Property managers are unbundling design-build contracts from maintenance agreements to optimize capital versus operating expenditure treatment. Commercial real estate investment trusts are separating hardscape installation from recurring turf care, compressing contractor switching costs. This procurement fragmentation is most visible in Phoenix and Las Vegas where water-budget volatility makes multi-year commitments untenable.
United States Landscaping Market Segmentation
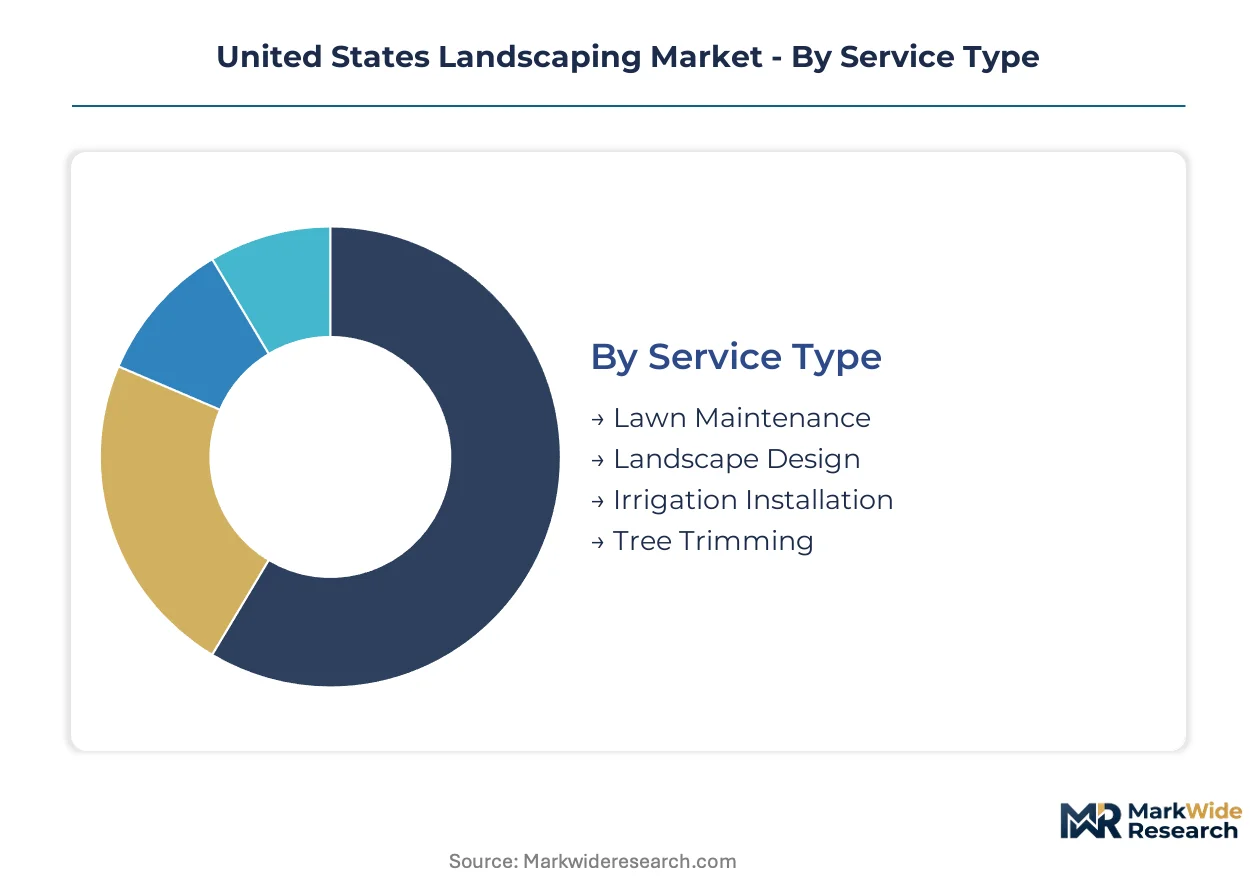
Segmentation in the United States landscaping market reveals how regulatory pressure, labor constraints, and water scarcity reshape contractor specialization and customer procurement patterns. Understanding these divisions exposes where margin compression concentrates and where premium pricing endures.
Service Type:
EPA stormwater mandates and OSHA heat-illness protocols differentiate compliance burdens across service lines, elevating capital requirements for some while compressing margins for others.
- Lawn Maintenance:Recurring weekly or biweekly mowing, edging, and fertilization cycles dominate transaction volume through subscription-based contracts. Residential subdivisions in Texas and Florida generate the highest contract density, though drought ordinances in California and Nevada are shrinking addressable turf acreage and forcing service mix pivots toward xeriscape maintenance.
- Irrigation Installation:Design and deployment of sprinkler systems, drip lines, and smart controllers with flow-rate compliance features. Municipal water budgets in Arizona and California are accelerating retrofit demand, with contractors bundling soil-moisture sensors and weather-based controllers to avoid utility penalties for commercial property managers.
- Landscape Design:Site planning integrating biological and hardscape elements for aesthetic and functional outcomes. Native plant expertise unlocks premium pricing in drought-prone jurisdictions.
- Tree Trimming:Canopy management and risk mitigation requiring certified arborist credentials. Utility vegetation management contracts in the Southeast provide stable revenue pools.
Established volume favors Lawn Maintenance; emerging adoption favors Irrigation Installation.
End User:
Procurement sophistication and contract duration vary sharply by customer type, with multi-year agreements concentrating in segments where asset value preservation drives spending authority.
- Commercial:Property managers and real estate investment trusts contract integrated grounds maintenance for office campuses, retail centers, and industrial parks. Fortune 500 sustainability mandates in California and Texas are embedding zero-emission equipment requirements into RFP specifications, favoring contractors with electrified fleets.
- Residential:Homeowners purchase discrete installation projects and seasonal maintenance subscriptions. Sun Belt metro areas including Phoenix, Dallas, and Atlanta generate the highest per-household spending on outdoor living upgrades.
- Government:Municipal parks departments and federal facilities procurement emphasizes prevailing wage compliance and small-business set-asides. EPA stormwater enforcement elevates permeable hardscape specifications for public projects.
- Agricultural:Orchard and vineyard operators contract specialized irrigation and erosion control services. California Central Valley water restrictions are redirecting capital toward subsurface drip retrofit specialists.
Recurring contract value concentrates in Commercial; transaction volume leadership sits with Residential.
Product Type:
Material sourcing and inventory carrying costs segment supplier economics, with perishability and freight exposure differentiating working capital intensity across categories.
- Plants:Nursery stock including turfgrass sod, ornamental shrubs, and trees selected for climate zone compatibility. California and Texas nurseries are pivoting production toward xerophytic species as municipal turf bans expand.
- Soil:Engineered growing media and amendments specified by pH, drainage, and organic content. Commercial development in Florida and Georgia drives bulk topsoil demand for grading and stormwater bioretention installations.
- Mulch:Organic groundcover products for moisture retention and weed suppression. Regional hardwood availability in the Southeast creates cost advantages for local producers.
- Hardscapes:Pavers, retaining walls, and drainage structures requiring engineered base courses. Permeable concrete and porous asphalt installations are climbing fastest in jurisdictions with MS4 stormwater permit requirements.
Margin stability favors Hardscapes; volume velocity favors Plants.
Delivery Model:
Capital structure and scaling economics diverge across fulfillment approaches, with asset-light models gaining traction in fragmented metropolitan markets.
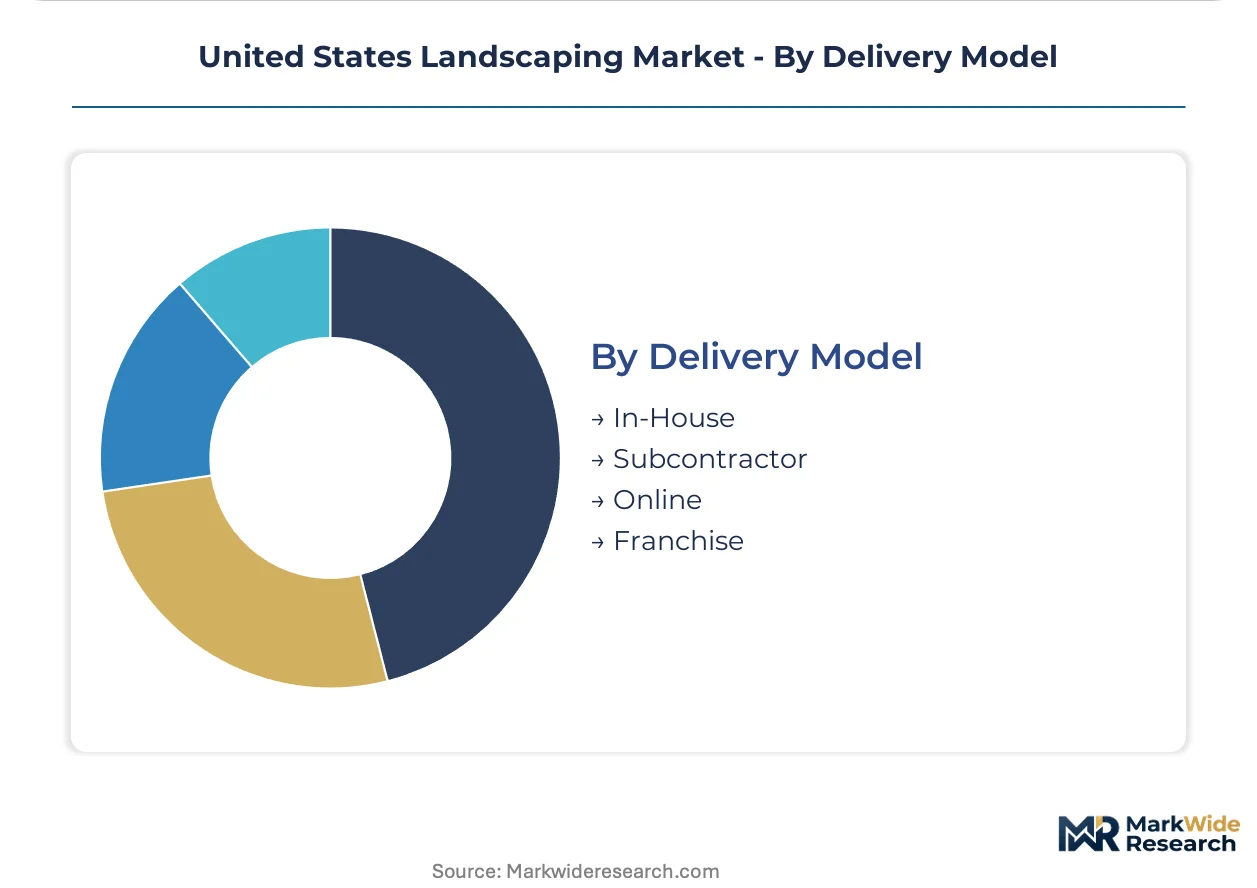
- In-House:Vertically integrated operations employing direct labor and owned equipment fleets. BrightView Holdings and TruGreen deploy this model to capture route density economies in major metro corridors.
- Subcontractor:Prime contractors sourcing specialized labor and equipment from third-party providers. This model dominates municipal and utility vegetation management where certified arborist scarcity necessitates external credential access.
- Online:Digital platforms connecting homeowners with vetted local contractors for discrete projects. Customer acquisition costs in this channel are compressing as Google Local Services ads saturate top metro search results.
- Franchise:Licensed operators leveraging brand recognition and centralized procurement. The Davey Tree Expert Company utilizes this structure to extend arboriculture expertise into secondary markets.
Operational control favors In-House; geographic expansion velocity favors Franchise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA stormwater enforcement under the Clean Water Act anchors regulatory pressure across the United States, with state-level drought ordinances fragmenting contractor specialization along climatic and hydrological boundaries. Regional demand concentrates in jurisdictions where water scarcity intersects with commercial real estate density.
California
Municipal water budgets in Los Angeles and San Diego metro areas are accelerating smart irrigation retrofits and xeriscape conversions. State Model Water Efficient Landscape Ordinance mandates flow-rate limits and turfgrass restrictions for new commercial developments. The Central Valley agricultural corridor is redirecting capital toward subsurface drip specialists as groundwater sustainability regulations tighten.
Texas
Fortune 500 campus sustainability mandates in Dallas-Fort Worth and Houston are embedding zero-emission equipment requirements into grounds maintenance RFPs. Texas Commission on Environmental Quality stormwater permits elevate permeable hardscape specifications for commercial developments. The Austin-San Antonio corridor generates dense contract volume for native plant design-build services amid persistent drought conditions.
Florida
Residential outdoor living upgrades in Miami-Dade and Orlando metro areas drive per-household landscaping expenditure leadership. Florida Department of Environmental Protection nutrient management rules restrict fertilizer application timing and composition for turfgrass maintenance. The Tampa Bay industrial cluster concentrates erosion control contractors serving phosphate mining and phosphate processing facility remediation.
Arizona
Phoenix and Tucson municipal water departments are phasing out non-functional turfgrass on public property and requiring xeriscape standards for private commercial installations. Arizona Department of Water Resources assured water supply rules condition development approvals on landscape water budgets. The Scottsdale-Paradise Valley corridor sustains premium pricing for desert botanical expertise in luxury residential design.
Nevada
Las Vegas Valley Water District turf removal rebate programs are dismantling residential and commercial grass acreage at accelerated rates. Nevada Division of Environmental Protection stormwater discharge permits mandate erosion control plans for construction sites exceeding one acre. The Reno-Sparks industrial zone anchors demand for wildfire-defensible space vegetation management around exurban residential development.
United States Landscaping Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around national footprint scale and technical credential depth. Route density economies favor operators with concentrated metro presence, while arboriculture and irrigation specializations sustain premium pricing outside commodity maintenance. Two strategic archetypes dominate: vertically integrated national platforms capturing commercial multi-year contracts, and certified-specialist regional operators anchoring high-margin niche services. Competitive moves center on fleet electrification investments and H-2B visa program navigation for seasonal labor access.
Within the national platform tier, BrightView Holdings Inc. and TruGreen Inc. exemplify scale-driven route optimization and centralized training infrastructure. The Davey Tree Expert Company occupies a distinct position anchoring arboriculture specialization through certified credential networks. These three operators represent contrasting strategic postures: integrated facilities management, technology-enabled residential services, and technical specialist depth.
| Leading Market Players |
|---|
| BrightView Holdings Inc. |
| TruGreen Inc. |
| The Davey Tree Expert Company |
| The F.A. Bartlett Tree Expert Company |
| Yellowstone Landscape |
| Gothic Landscape Inc. |
| Park West Companies |
| Aspen Grove Landscape Group |
| Ruppert Landscape Inc. |
| Others |
Value Network & Pricing Analysis
Artificial turf substitution in sports facilities and municipal properties is simultaneously compressing biological maintenance contract values and rerouting supplier relationships toward synthetic fiber distributors and infill material networks. This displacement is redrawing procurement geography as contractors pivot from perishable nursery stock toward engineered surface products with extended inventory cycles and different freight economics.
Pricing Analysis
California and Texas command 15-25% pricing premiums over Southeast markets for equivalent commercial maintenance contracts due to drought-ordinance compliance costs and certified arborist scarcity. Three-tier pricing structure across premium certified-arborist services, standard licensed-crew maintenance, and economy subcontractor labor dominates contract segmentation. Pricing pressure stems from H-2B visa bottlenecks elevating wage floors faster than contract escalation clauses permit. Residential homeowners exhibit highest price sensitivity with switching costs below $200 annually, while Fortune 500 campus managers prioritize compliance assurance over marginal cost differences.
Supply Chain Analysis
Oregon and Washington State anchor nursery production for xerophytic species and ornamental stock serving drought-prone Southwest markets. Diesel-powered commercial equipment draws from assembly plants in Wisconsin and Ohio, while smart irrigation controllers source from electronics manufacturing clusters in Mexico and Taiwan. Single-source vulnerability concentrates in pressure-compensating drip emitter supply where two California manufacturers dominate municipal retrofit specifications. Distribution runs through regional equipment dealers with exclusive territory agreements, constraining contractor procurement flexibility during peak spring demand windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic turf and hardscape substitution threatens biological maintenance revenue pools, requiring incumbents to defend service attach rates through technical specialization that artificial alternatives cannot replicate.
For Market Incumbents: Fortify arboriculture credential pipelines through ISA-certified training academies to preserve pricing power against synthetic turf displacement in municipal sports contracts. Secure backward integration into native plant nursery production in Texas and Arizona to capture margin from xeriscape conversion demand. Vertical equipment electrification investments in California metro corridors defend RFP eligibility under Fortune 500 zero-emission mandates. For New Entrants and Emerging Players: Differentiate on subsurface drip irrigation expertise bundled with IoT soil monitoring for California Central Valley agricultural clients facing groundwater sustainability cutbacks. Target Phoenix and Las Vegas commercial property managers unbundling design-build from maintenance agreements, where procurement fragmentation lowers incumbent switching costs. Pursue certified arborist subcontractor relationships to access utility vegetation management contracts without credential pipeline delays. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors technical-specialist regional operators over undifferentiated maintenance scale. Long-term viability hinges on water-scarcity adaptation capabilities and electrified fleet positioning rather than route density alone. Acquisition targets should demonstrate native plant botanical expertise or certified arborist density in drought-ordinance jurisdictions. Monitor municipal turf removal rebate program expansion rates as inflection indicator for biological maintenance addressable market contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Arborist Training Academy Investment | ISA credential pipelines unlock premium pricing in utility vegetation management contracts across the Southeast. |
| Native Plant Nursery Backward Integration | Captive xerophytic species production secures margin from Arizona and Nevada municipal xeriscape mandates. |
| Commercial Fleet Electrification Program | Battery-powered mower deployment satisfies California Fortune 500 zero-emission RFP specifications. |
| Smart Irrigation Technology Partnership | Soil-moisture sensor bundling differentiates retrofit offerings for Las Vegas Valley Water District compliance. |
| Subcontractor Network Certification | External arborist credential access accelerates entry into high-margin tree risk assessment services. |
Research Methodology
Initial hypotheses were tested against primary input from commercial property managers, certified arborists, irrigation contractors, and municipal parks procurement officers and refined through secondary validation. Landscaping-specific secondary sources included EPA stormwater permit databases, state drought ordinance filings, H-2B visa program disclosure data, and municipal water budget appropriations. SEC 10-K filings from publicly traded grounds maintenance operators, nursery trade association shipment reports, and equipment manufacturer dealer network disclosures provided additional triangulation. Bottom-up contract value estimates across service types were reconciled against top-down market size benchmarks.
Variance decomposition across service type, end user, and state regulatory jurisdiction shaped the analytical framework over the projection horizon. Segmentation modeling incorporated delivery model, equipment fleet composition, and certified credential intensity as industry-specific dimensions. CAGRs were derived from regression-based trend extrapolation calibrated to historical contract escalation patterns and regulatory implementation timelines. Forecast inputs included municipal water budget volatility indices and H-2B visa approval rate assumptions.
Decision-makers should treat outputs as directional under sustained drought-ordinance expansion and stable seasonal labor program caps; material deviation in either assumption would warrant model refresh. Recalibration cycles align with material shifts in EPA stormwater enforcement intensity and state-level groundwater sustainability regulation adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Automated Blinds and Shades Market
Home & Garden
Christmas Decorations Market
Home & Garden
North America Flowerpots Market
Home & Garden
United States Lawn Care Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Candle Market
Home & Garden
Incense Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Preserved Flowers Market
Home & Garden
Flower Box Market
Home & Garden
Artificial Plants Market
Home & Garden
Bird House Market