
 Global Motorized and Smart Awnings Market | 2026-2036
Global Motorized and Smart Awnings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Motorized and Smart Awnings Market Intelligence
Project finance for smart home infrastructure rollouts is reconfiguring competitive entry barriers across the awning value chain. Somfy Systems, Inc. leverages its motorization IP portfolio to dominate European distribution channels. Hunter Douglas N.V. sustains manufacturing scale across North American assembly plants. Markilux GmbH & Co. KG anchors premium positioning through specialized architectural integration capabilities.
Motorized and smart awnings comprise electromechanical shading systems integrating tubular motors, weather sensors, and wireless control interfaces to modulate solar heat gain and ultraviolet exposure in built environments. Fabric substrates typically incorporate solution-dyed acrylics rated for colorfastness and tensile loads exceeding specific wind resistance thresholds. Smart retractable awnings command disproportionate margin pools as Wi-Fi enabled connectivity shifts from premium add-on to baseline expectation among property developers. Folding arm awnings retain volume leadership in residential patios across mature European markets where installation heritage spans decades.
The EU Green Deal and REACH chemical compliance frameworks constrain fabric sourcing and motor component material selection for suppliers serving European demand. The U.S. Energy Star program and state-level building codes in California shape product efficiency benchmarks and installation incentive eligibility across North American markets. Stakeholders must monitor evolving interoperability standards between voice-activated control platforms and legacy remote-controlled motor architectures as smart home ecosystem consolidation accelerates.
Market Dynamics
The integration of photovoltaic fabrics with building-integrated photovoltaics (BIPV) architectures is forcing a fundamental restructuring of supplier capabilities across the motorized awning value chain. Electromechanical shading systems now function as distributed energy assets rather than passive solar control devices, compressing traditional equipment margins while opening new revenue pools in energy arbitrage and grid services.
Growth Catalysts
- EU Green Deal building efficiency mandates:The European Commission's directive on energy performance of buildings requires automated solar shading in new commercial construction across Germany, France, and Italy. This regulatory pressure accelerates specification of smart awnings with integrated sensors and motorization.
- Suburban patio retrofit demand in the United States:Post-pandemic residential investment in outdoor living spaces concentrates in Texas, Florida, and California housing developments. Property owners prioritize Wi-Fi-enabled retractable systems with voice control compatibility.
- Photovoltaic fabric maturation:Solution-dyed acrylic substrates with embedded thin-film solar cells achieve commercial viability for residential installations. These materials convert awning surface area into distributed generation capacity.
Market Restraints
- Aluminum alloy and copper motor component volatility:Tubular motor manufacturing depends on non-ferrous metal supply chains concentrated in Chinese smelting operations. Price fluctuations in LME-traded commodities compress OEM margins during contract bidding cycles.
- REACH chemical compliance complexity:ECHA restrictions on per- and polyfluoroalkyl substances (PFAS) in fabric coatings force reformulation of water-repellent treatments. European suppliers face 18-24 month requalification timelines for substitute chemistries.
- Fixed external shading substitution:Brise-soleil and perforated metal screens compete for commercial facade projects in Mediterranean climates. These passive systems require no maintenance, motors, or electrical infrastructure.
Strategic Opportunities
- India's smart city infrastructure programs:The Ministry of Housing and Urban Affairs mandates automated shading in government building retrofits across Delhi, Mumbai, and Bangalore. Local manufacturing incentives under PLI schemes attract component assembly investment.
- Voice-activated control platform convergence:Integration with Amazon Alexa, Google Home, and Apple HomeKit ecosystems transforms awning motorization from standalone hardware to smart home infrastructure. Developers bundle these systems in new multifamily construction.
- Heat pump and HVAC load management:Smart awnings with predictive weather algorithms coordinate with building management systems to reduce cooling demand. This application penetrates commercial office markets in Singapore and Sydney.
Industry Challenges
- Interoperability standard fragmentation:Competing wireless protocols (Zigbee, Z-Wave, Thread, proprietary RF) create integration complexity for installers serving mixed-vendor smart home environments. End-users experience control system incompatibilities.
- Certification timeline compression:CE marking under the EU Machinery Directive and electromagnetic compatibility testing require 6-9 month validation cycles. Product launches delay behind software update cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Motorized and Smart Awnings Market |
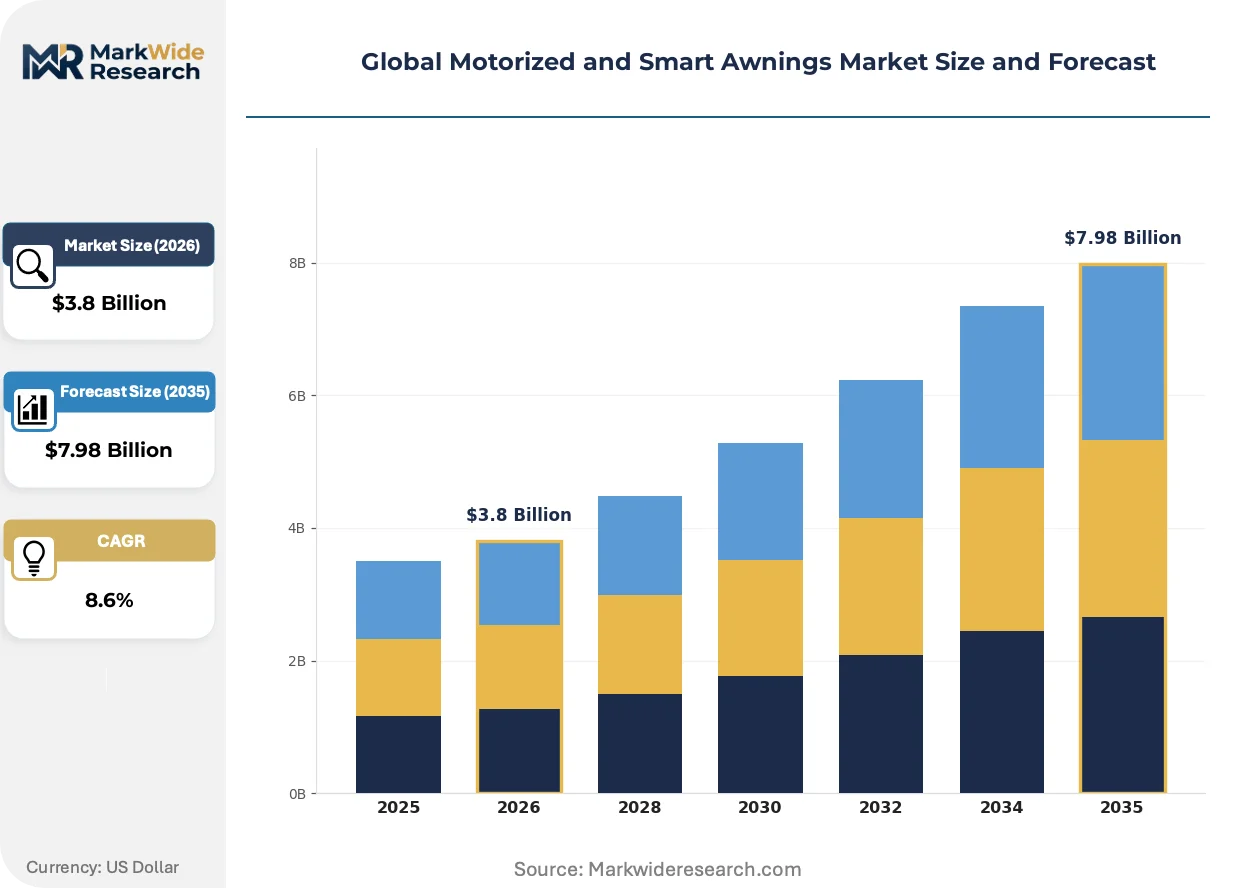
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorized Awnings, Smart Retractable Awnings, Folding Arm Awnings, Window Awnings Technology: Wi-Fi Enabled, Bluetooth Control, Solar Powered, Voice Activated, Remote Controlled Application: Residential Patios, Commercial Facades, Outdoor Cafes, Sunrooms, Hospitality Spaces End User: Homeowners, Property Developers, Restaurateurs, Facility Managers |
| Companies Covered | Brustor, Hunter Douglas N.V., Somfy Systems, Inc., Sunesta Awnings, ADVANING, SunSetter Products LP, Awntech, Markilux GmbH & Co. KG, Stobag AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Motorized and Smart Awnings Market Strategic Shifts & Innovations
Photovoltaic fabric technology is collapsing the boundary between passive shading and active energy generation in building envelope design. This convergence demands new competencies from traditional awning manufacturers while attracting solar equipment suppliers into adjacent markets.
Perovskite-enhanced thin-film solar cells embedded in solution-dyed acrylic substrates is collapsing the cost differential between standard and energy-generating awning fabrics. Commercial property developers in Germany and the Netherlands specify these systems for net-zero building certifications. The technology compresses payback periods for building-integrated photovoltaics from 12-15 years toward 7-9 years.
The EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants indirectly affects motorized awning demand through tightened building envelope performance standards. Member states implement stricter solar heat gain coefficient requirements that favor dynamic shading over static glazing solutions. Southern European markets respond fastest, with Spanish and Italian building codes mandating automated external shading in new construction above 500 square meters.
Builder and contractor procurement of complete outdoor living systems displaces component-level awning purchasing in North American residential markets. Homebuyers in Arizona, Nevada, and Colorado expect integrated packages combining pergolas, motorized screens, climate control, and lighting. This concentration forces specialized awning fabricators to partner with landscape architecture firms or risk exclusion from specification channels.
Global Motorized and Smart Awnings Market Segmentation
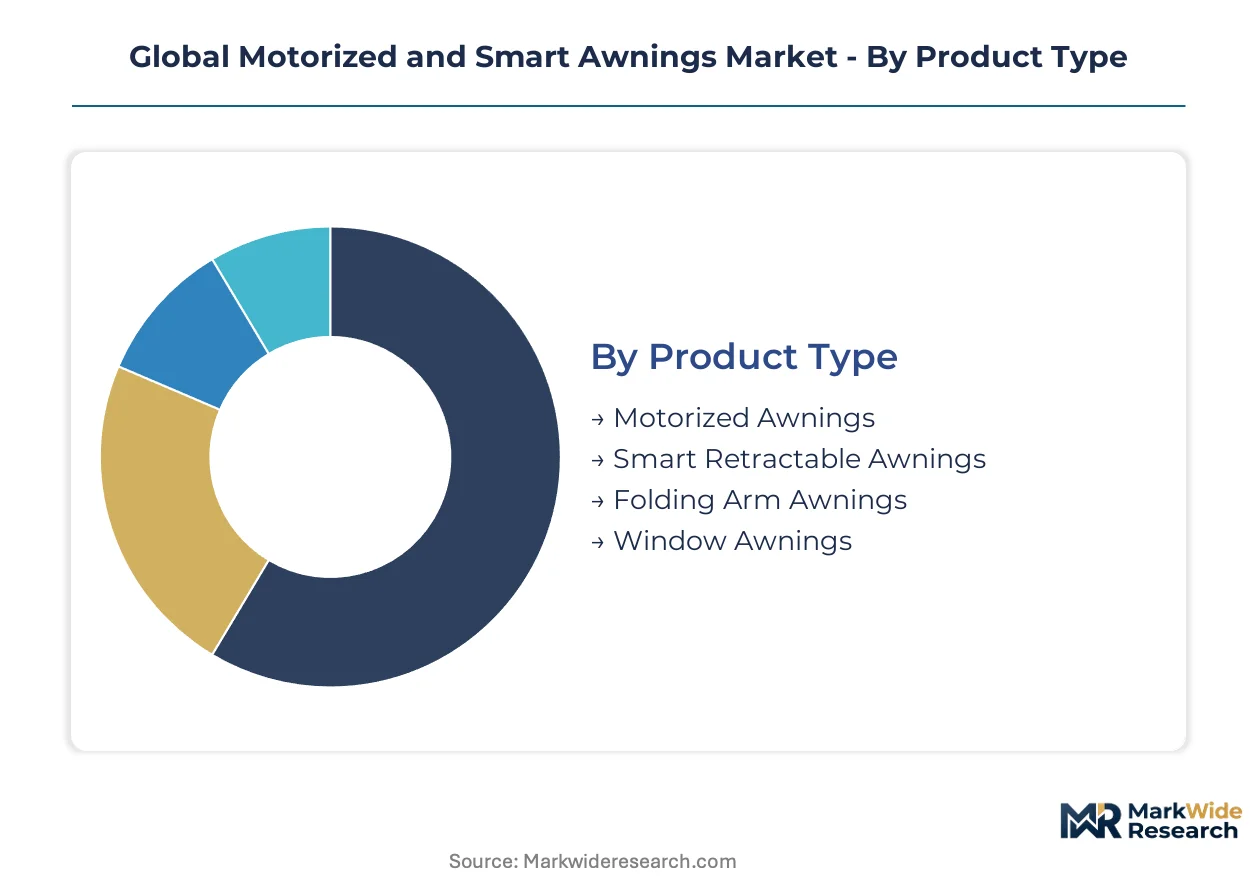
Motorized and smart awning manufacturers configure product portfolios across four intersecting dimensions. Each segmentation axis reveals distinct margin structures, specification channels, and technology integration requirements that reshape competitive positioning.
Product Type:
Application context determines structural design — residential patios favor retractable convenience while commercial facades demand wind-load engineering.
- Motorized Awnings:Tubular motor systems housed in aluminum cassettes deliver automated extension and retraction. Demand concentrates in Germany's Rhine-Ruhr corridor where smart home retrofit rates outpace neighboring regions, driven by EU Green Deal building efficiency mandates requiring automated solar shading.
- Smart Retractable Awnings:Wi-Fi connectivity, weather sensors, and predictive algorithms coordinate sun tracking with building management systems. Property developers in Texas, Florida, and California specify these for post-pandemic outdoor living investments, prioritizing voice control compatibility.
- Folding Arm Awnings:Scissor-arm mechanisms support fabric tension across extended projections without vertical supports. Decades of installation heritage sustain volume leadership in mature European residential markets.
- Window Awnings:Compact projection systems designed for individual glazing units rather than full patio coverage. Specification channels run through architectural practices serving heritage building renovations.
Folding arm awnings hold installed capacity. Smart retractable awnings is rotating up the share rankings.
Technology:
Control interface selection reflects end-user technical sophistication and smart home ecosystem maturity.
- Wi-Fi Enabled:Direct cloud connectivity enables smartphone control, scheduling algorithms, and remote monitoring. Builder procurement of complete outdoor living systems in Arizona, Nevada, and Colorado bundles these as baseline expectations in new multifamily construction.
- Bluetooth Control:Short-range wireless protocols suit standalone installations without home network dependency. Cost-sensitive residential retrofits in suburban United States housing developments favor this simplified architecture.
- Solar Powered:Photovoltaic fabric substrates with embedded thin-film cells convert awning surface area into distributed generation. Commercial developers in Germany and the Netherlands specify these for net-zero building certifications, compressing BIPV payback periods toward seven to nine years.
- Voice Activated:Native integration with Amazon Alexa, Google Home, and Apple HomeKit transforms motorization from standalone hardware to smart home infrastructure.
- Remote Controlled:Proprietary RF handsets and wall switches serve legacy installations and markets with fragmented interoperability standards.
Remote controlled systems hold installed capacity. Voice activated control is rotating up the share rankings.
Application:
End-use environment dictates fabric specification, motor sizing, and sensor configuration.
- Residential Patios:Suburban housing developments across the United States accelerate uptake of automated shading systems. Post-pandemic outdoor living investments concentrate specification of Wi-Fi-enabled retractable systems with climate control integration.
- Commercial Facades:Brise-soleil and perforated metal screens compete for Mediterranean climate projects, though dynamic systems gain share where EU F-Gas Regulation phase-down tightens building envelope performance standards.
- Outdoor Cafes:Seasonal deployment requirements favor rapid-install folding arm configurations with weather-reactive automation.
- Sunrooms:Integrated conservatory systems demand specialized glazing coordination and thermal performance engineering.
- Hospitality Spaces:Brand-standard outdoor environments in hotel and resort portfolios specify complete outdoor living system packages combining pergolas, motorized screens, and lighting.
Residential patios hold installed capacity. Commercial facades is rotating up the share rankings.
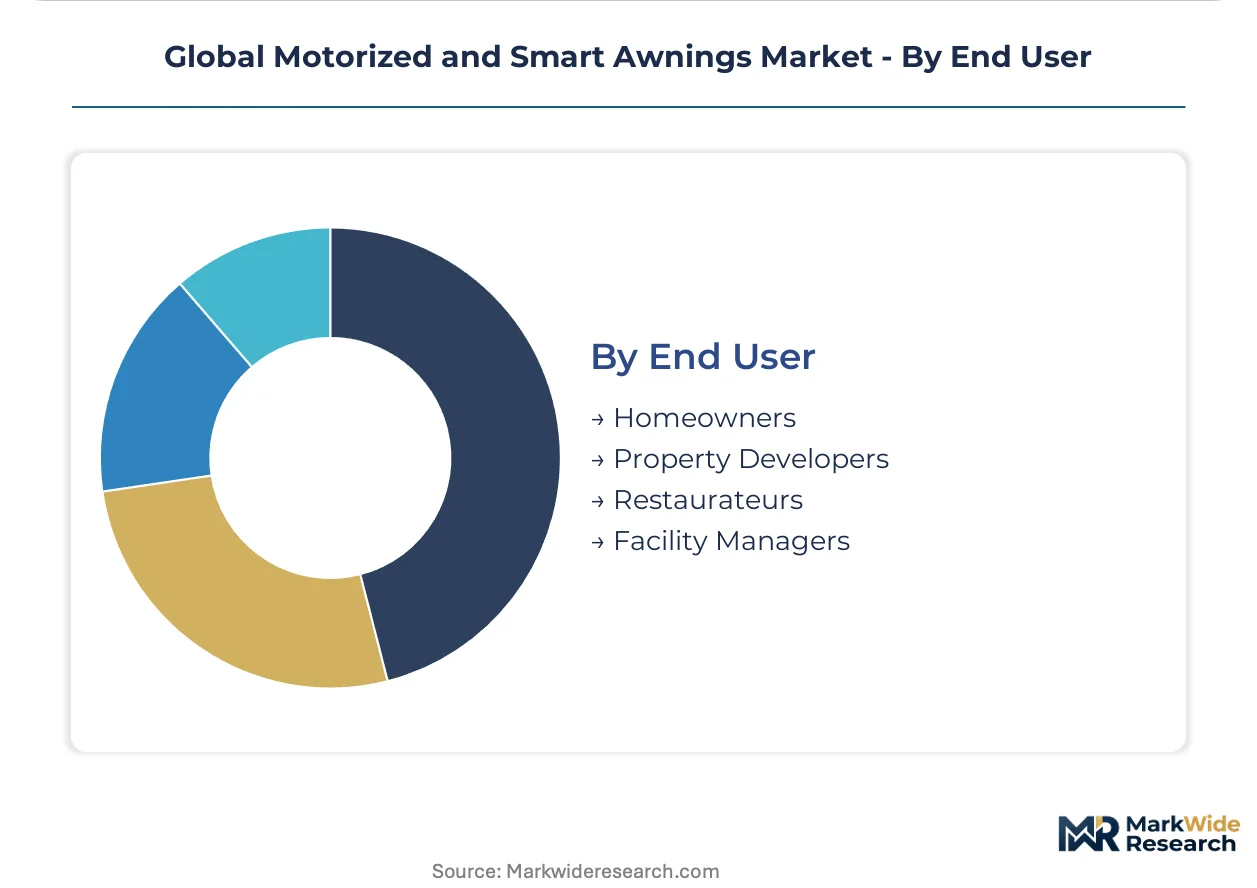
End User:
Procurement authority and specification influence separate fragmented consumer markets from concentrated project channels.
- Homeowners:Direct retail and contractor-mediated purchases dominate suburban retrofit activity. Voice-activated control platform convergence shifts purchase criteria toward smart home ecosystem compatibility.
- Property Developers:Volume procurement of integrated outdoor living systems in North American multifamily construction bundles awnings with landscape architecture packages.
- Restaurateurs:Seasonal revenue dependency drives demand for rapid-deployment seasonal systems with minimal structural modification.
- Facility Managers:Commercial office markets in Singapore and Sydney deploy predictive weather algorithms coordinating with HVAC load management to reduce cooling demand.
Homeowners hold installed capacity. Property developers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Germany and the United States as net exporters of motorized awning components, while India and China absorb growing volumes of tubular motors and sensor assemblies. Trade flows concentrate in specialized electromechanical components rather than finished systems.
Germany
The Rhine-Ruhr metropolitan corridor sustains Europe's densest concentration of smart home retrofit activity. EU Green Deal building efficiency mandates require automated solar shading in new commercial construction. Manufacturers in North Rhine-Westphalia coordinate fabric sourcing with REACH-compliant coating facilities across the Benelux region.
United States
Post-pandemic outdoor living investments concentrate specification in Texas, Florida, and California housing developments. State-level building codes in California shape product efficiency benchmarks for installation incentive eligibility. Suburban patio retrofits in the Mountain West accelerate uptake of Wi-Fi-enabled retractable systems.
India
The Ministry of Housing and Urban Affairs mandates automated shading in government building retrofits across Delhi, Mumbai, and Bangalore. PLI schemes attract component assembly investment for tubular motor manufacturing. Local fabricators in Maharashtra and Gujarat expand capacity to serve smart city infrastructure programs.
Netherlands
Commercial property developers specify photovoltaic fabric systems for net-zero building certifications. EU F-Gas Regulation phase-down tightens building envelope performance standards favoring dynamic shading. Rotterdam and Amsterdam architectural practices integrate BIPV-awning hybrids into waterfront redevelopment projects.
Australia
Commercial office markets in Sydney deploy predictive weather algorithms coordinating with HVAC load management. Building codes in New South Wales mandate external shading for thermal performance compliance. Facility managers prioritize smart awning integration with building management systems to reduce cooling demand.
Global Motorized and Smart Awnings Market Key Industry Players
On the supply side, the industry is consolidating around electromechanical component specialists and fabric-integrated system integrators. Tiered competitive structure separates premium architectural specification channels from mass-market retail distribution. Three archetypes dominate: motorization IP holders, scale manufacturing platforms, and premium architectural integration specialists. Capacity expansion and technology licensing represent the dominant competitive moves as photovoltaic fabric maturation attracts adjacent solar equipment suppliers.
Within the motorization tier, Somfy Systems, Inc. and Hunter Douglas N.V. occupy positions as scale-driven electromechanical platforms. Markilux GmbH & Co. KG exemplifies the premium architectural integration archetype, anchoring specialized specification channels where building-integrated design capabilities command margin premiums. These three firms represent distinct competitive vectors—IP-based motorization, North American manufacturing scale, and European architectural premium positioning—that structure rivalry across the value chain.
| Leading Market Players |
|---|
| Brustor |
| Hunter Douglas N.V. |
| Somfy Systems, Inc. |
| Sunesta Awnings |
| ADVANING |
| SunSetter Products LP |
| Awntech |
| Markilux GmbH & Co. KG |
| Stobag AG |
| Others |
Cost & Logistics Intelligence
North Rhine-Westphalia's fabric coating and motor assembly cluster concentrates European supply capacity, translating regional manufacturing density into pricing leverage for tier-one suppliers serving Rhine-Ruhr smart home retrofits. This geographic anchoring compresses procurement timelines for REACH-compliant substrates while amplifying margin pressure on smaller fabricators lacking captive coating facilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on CE marking tier under the EU Machinery Directive and after-sales service bundling with predictive maintenance algorithms. Cost compression in economy-tier tubular motors is intensifying because Chinese smelting volatility transmits directly to LME-linked component contracts. Property developers exhibit lowest price sensitivity due to bundled outdoor living system procurement, while suburban homeowner retrofits show highest elasticity to voice-control premiums.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for tubular motor manufacturers. Production gravity centers on China, Germany, and the United States for electromechanical components, with solution-dyed acrylic substrates drawing from Belgian and Turkish textile operations. Single-source vulnerability concentrates in thin-film solar cell supply for photovoltaic fabric variants. Distribution runs through specialized architectural specification channels in Europe and landscape architecture firm partnerships in North American residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motorized and smart awnings market operates as a defensive-moat industry where regulatory entrenchment through EU Green Deal compliance creates durable switching costs for specification-grade suppliers.
For Market Incumbents: Harden defensible positioning through backward integration into REACH-compliant coating facilities and captive sensor assembly capacity in North Rhine-Westphalia. Cement channel control by embedding predictive weather algorithms directly into building management system partnerships, neutralizing emerging solar equipment suppliers entering from adjacent BIPV markets. For New Entrants and Emerging Players: Pursue white-space penetration in India's smart city infrastructure programs, specifically government building retrofits across Delhi and Mumbai where PLI schemes reduce capital barriers. Attack the voice-activated control segment through native HomeKit and Alexa integration, bypassing incumbent proprietary RF architectures that dominate legacy replacement cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical component specialists with photovoltaic fabric integration capabilities over pure-play motorization vendors. Long-term viability rests on energy arbitrage revenue streams from building-integrated generation assets. Watch for perovskite-enhanced thin-film commercialization timelines as the inflection signal compressing BIPV payback periods and accelerating specification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Fabric Integration | Converts passive shading assets into distributed generation capacity qualifying for EU Green Deal subsidies. |
| Voice Control Platform Certification | Native Alexa, Google Home, and HomeKit integration transforms hardware into smart home infrastructure. |
| REACH-Compliant Coating Capacity | ECHA PFAS restrictions force 18-24 month requalification timelines that captive facilities circumvent. |
| Predictive Weather Algorithm Development | HVAC load coordination with building management systems penetrates commercial office markets in Singapore and Sydney. |
| Landscape Architecture Firm Partnerships | Builder procurement of complete outdoor living systems in Arizona and Colorado requires specification channel access. |
Research Approach
A spread of perspectives from tubular motor engineering directors, fabric coating facility managers, smart home platform integration specialists, and architectural specification consultants converged on the working assumptions. Primary fieldwork combined with secondary validation against ECHA regulatory filings, EU building code databases, and customs trade flows for aluminum alloy and copper components. Bottom-up installation data triangulated against top-down construction spending patterns across the analysis window.
Demand-supply balance modeling segmented volume and value across product type, control interface technology, application environment, and end-user procurement authority. CAGRs derived from fitted growth curves applied to retrofit penetration rates and new construction mandates. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down timelines and perovskite solar cell commercialization curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese motorization platforms or breakthrough perovskite manufacturing scale would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Aquarium Decor Market
Home & Garden
Incense Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
US Garden Planter Market
Home & Garden
Flower Box Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
United Kingdom Homeware Market
Home & Garden
Automated Blinds and Shades Market
Home & Garden
North America Flowerpots Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Wine Racks Market
Home & Garden
Global Wind Chime Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Residential Snow Blower Market