
 North America Flower Pots and Planters Market | 2026-2036
North America Flower Pots and Planters Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flower Pots and Planters Market Insights
Multi-source resin procurement is realigning supply strategies across the industry. HC Companies leverages vertical integration in recycled polypropylene to control feedstock quality across its Ohio manufacturing footprint. Bloem Living anchors its position through exclusive color-compounding capabilities that differentiate shelf presence at major garden retailers. East Jordan Plastics sustains volume leadership through dedicated thermoforming lines serving big-box home improvement channels.
Flower pots and planters comprise molded or fabricated vessels engineered to contain growing media for ornamental or edible plants, typically specified by drainage porosity, UV stabilization rating, and wall thickness measured in millimeters. Plastic Pots dominates unit volume due to injection molding economies and lightweight logistics, though margin pools concentrate in Ceramic Planters where artisan glazing commands price premiums. Biodegradable Pots registers the fastest structural expansion as municipal composting infrastructure spreads across the Pacific Coast and Northeast corridors. Commercial Horticulture application demand tracks directly with controlled-environment agriculture buildouts in Ontario and Michigan greenhouse clusters.
The U.S. EPA regulates volatile organic compound emissions from solvent-based coatings applied to metal containers, while California's Department of Toxic Substances Control oversees restricted substance thresholds in colored plastics through Safer Consumer Products regulations. Health Canada and PMRA coordinate on pesticide container labeling that indirectly shapes planter drainage and reservoir design standards for edible gardening applications. Stakeholders must monitor evolving extended producer responsibility frameworks in British Columbia and Quebec that could impose end-of-life collection obligations on plastic planter manufacturers.
Market Dynamics
Post-consumer resin procurement mandates from California and British Columbia are forcing manufacturers to reconfigure compounding operations and supplier relationships across the North American supply base.
Growth Catalysts
- Extended Producer Responsibility frameworks:British Columbia's recycling regulations and Quebec's pending packaging laws create collection infrastructure that normalizes recycled-content planters in retail channels.
- Controlled-environment agriculture clusters:Greenhouse buildouts in Ontario and Michigan drive commercial-grade container demand for hydroponic vegetable propagation.
- Urban balcony gardening:Dense Canadian and U.S. metropolitan housing stock converts unused outdoor space into active growing areas, sustaining replacement purchase cycles.
Market Restraints
- Resin price volatility:Post-consumer polypropylene availability fluctuates with municipal collection program funding, squeezing margin predictability for recycled-content product lines.
- Thermoforming equipment concentration:Dedicated production lines serving big-box home improvement channels lock capital into single-format output, limiting flexibility during demand shifts.
- California Safer Consumer Products thresholds:Restricted substance testing for colored plastics adds compliance overhead that smaller compounders struggle to absorb.
Strategic Opportunities
- Municipal composting infrastructure spread:Pacific Coast and Northeast corridor expansion of industrial composting facilities enables biodegradable pot categories previously limited to backyard disposal.
- Edible gardening certification alignment:Health Canada and PMRA pesticide container labeling coordination shapes drainage design standards, creating first-mover advantage for compliant reservoir systems.
- Direct-to-grower digital channels:Commercial horticulture buyers in Michigan and Ontario greenhouse clusters increasingly bypass distributor markup through manufacturer-hosted procurement platforms.
Industry Challenges
- Color-matching talent scarcity:Exclusive compounding capabilities that differentiate shelf presence require polymer chemists with specialized pigment dispersion expertise, a skill pool concentrated among legacy Ohio manufacturers.
- Legacy thermoforming line conversion:Dedicated equipment serving high-volume retail channels resists rapid retooling for thinner-wall biodegradable formats demanded by municipal composting programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flower Pots and Planters Market |
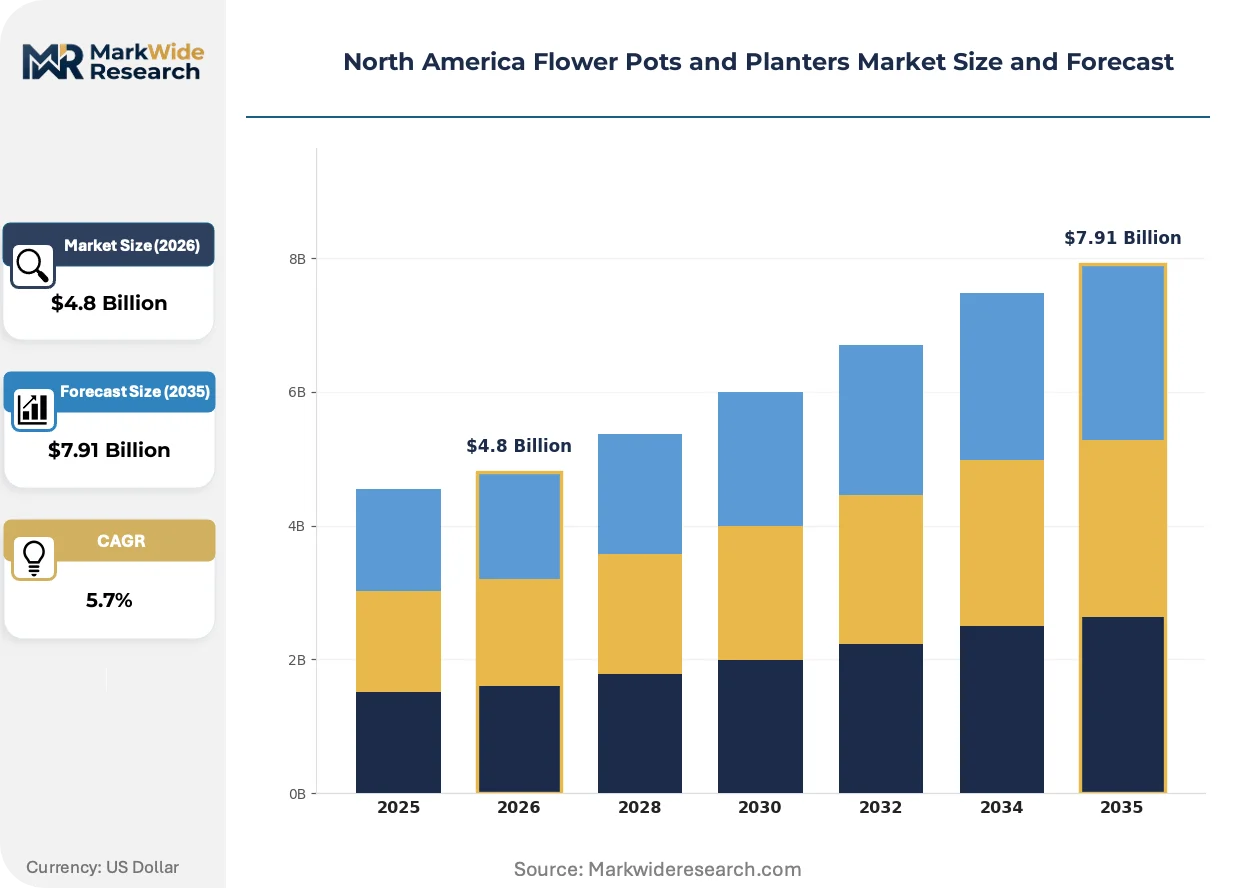
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Pots, Ceramic Planters, Metal Containers, Biodegradable Pots Application: Indoor Gardening, Outdoor Living, Commercial Horticulture, Landscaping Size: Small Pots, Medium Planters, Large Containers, Extra Large Distribution Channel: Online Retail, Garden Centers, Home Improvement Stores, Wholesale Distributors |
| Companies Covered | HC Companies, Bloem Living, East Jordan Plastics, Keter, Deroma, Crescent Garden Company, Mayne Inc., Tusco Products, Novelty Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flower Pots and Planters Market Trends and Innovations
Material science advances and procurement model evolution are compressing traditional category boundaries between disposable and durable planter formats across North American retail and commercial channels.
Post-consumer recycled polypropylene formulations are consolidating supply chain control among manufacturers with backward integration into resin sourcing. Injection molders serving mass-market garden retailers now specify minimum recycled content thresholds that exclude non-integrated compounders. This consolidation of feedstock access is compressing the viable supplier base for price-competitive plastic pots.
California's Department of Toxic Substances Control Safer Consumer Products regulations are forcing reformulation of colorant packages across the entire North American production footprint. Pigment suppliers must now certify heavy metal content below restricted thresholds, adding testing overhead that disadvantages smaller regional compounders. Ceramic planter manufacturers with legacy lead-based glaze inventories face accelerated write-downs or costly reformulation.
Commercial horticulture buyers in Ontario and Michigan greenhouse clusters are unbundling after-sales service from container procurement, treating planters as pure commodity inputs rather than bundled growing systems. This disintermediation of technical support compresses margin pools for manufacturers previously capturing service premiums. Direct digital procurement platforms are capturing volume previously flowing through distributor networks with field technical staff.
North America Flower Pots and Planters Market Segmentation
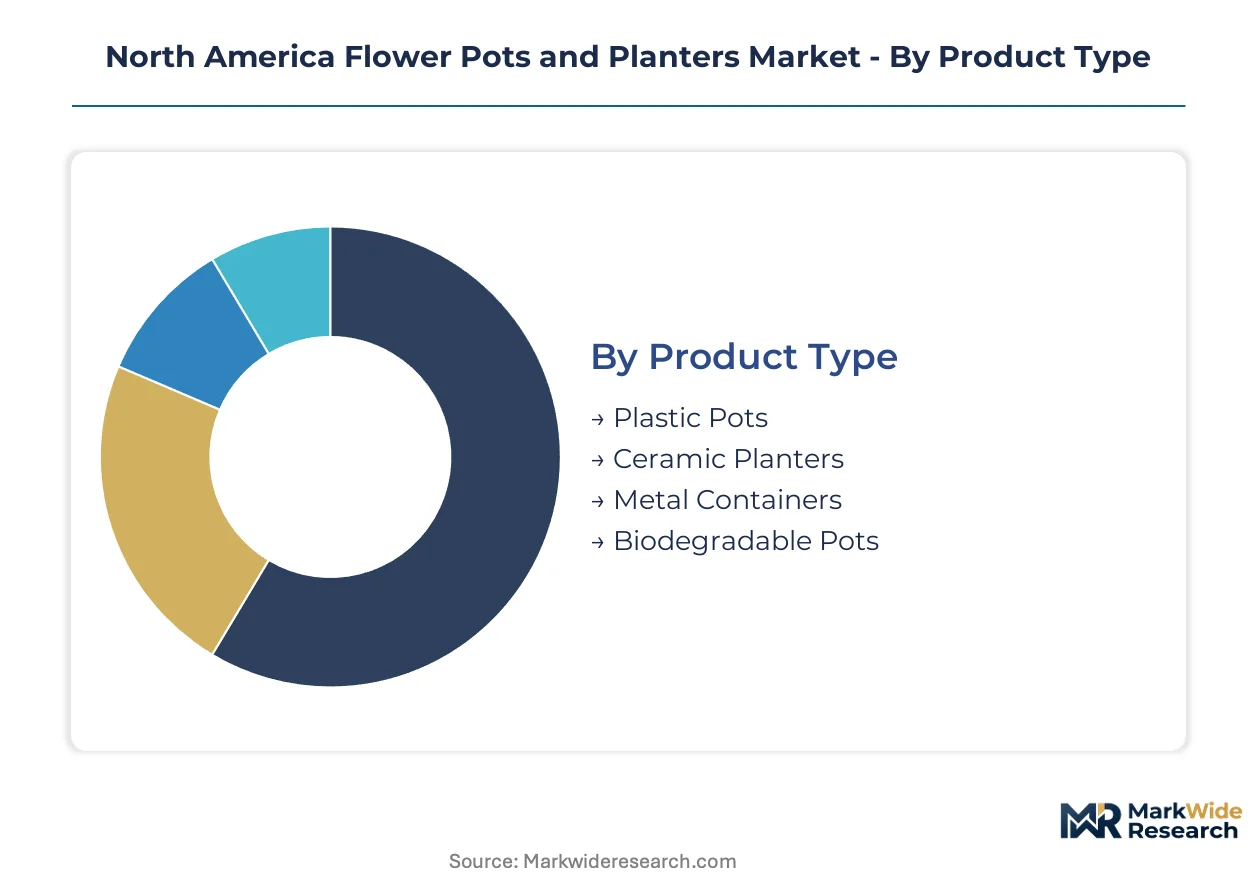
Segmentation in the North America Flower Pots and Planters Market reveals divergent compliance burdens and margin architectures across material formats and procurement channels. Manufacturers must align product development with California's Safer Consumer Products thresholds for colored plastics, Health Canada reservoir design standards for edible applications, and municipal composting infrastructure availability for biodegradable formats.
Product Type:
California's Department of Toxic Substances Control enforces restricted substance thresholds on colored plastics, while Health Canada and PMRA coordinate pesticide container labeling that shapes drainage specifications for edible gardening vessels.
- Plastic Pots:Injection-molded polypropylene vessels specified by wall thickness in millimeters and UV stabilization ratings. Demand concentrates in U.S. Sun Belt states where year-round outdoor living sustains replacement cycles, though post-consumer resin availability fluctuations squeeze margin predictability for recycled-content lines.
- Ceramic Planters:Kiln-fired clay vessels with artisan glazing commanding price premiums in specialty retail. California's heavy metal content restrictions force reformulation of legacy lead-based glaze inventories, accelerating write-downs for manufacturers with dated stock.
- Biodegradable Pots:Plant-fiber or bio-resin vessels engineered for industrial composting degradation. Municipal infrastructure expansion across Pacific Coast and Northeast corridors enables category growth previously limited to backyard disposal.
- Metal Containers:Fabricated steel or aluminum vessels with solvent-based coating applications. The U.S. EPA regulates volatile organic compound emissions from coating operations, adding compliance overhead distinct from plastic and ceramic formats.
Leading the category by volume: Plastic Pots. Growing fastest: Biodegradable Pots.
Application:
Cost tier stratification separates premium designer vessels from commodity propagation trays, with commercial buyers in Ontario and Michigan greenhouse clusters treating containers as pure commodity inputs.
- Indoor Gardening:Compact vessels engineered for controlled-environment residential cultivation. Dense Canadian and U.S. metropolitan housing stock converts unused interior space into active growing areas.
- Outdoor Living:Weather-resistant vessels specified for balcony, patio, and deck deployment. Year-round outdoor living in Sun Belt states sustains replacement purchase cycles absent in seasonal climates.
- Commercial Horticulture:Standardized propagation and production containers for greenhouse vegetable and ornamental operations. Controlled-environment agriculture buildouts in Ontario and Michigan drive demand for hydroponic-compatible reservoir designs.
- Landscaping:Heavy-duty vessels for municipal, corporate, and residential installation projects. Specified by drainage porosity and structural load ratings for permanent outdoor placement.
Volume concentrates in Outdoor Living. Steepest expansion trajectory: Commercial Horticulture.
Size:
Logistics economics and retail shelf dimensions constrain viable size ranges, with big-box home improvement channels favoring stackable formats that maximize cube utilization.
- Small Pots:Vessels under 6 inches in diameter for seed starting and herb cultivation. Urban balcony gardeners in Vancouver, Toronto, and Chicago purchase these as entry-level formats.
- Medium Planters:6-12 inch diameter vessels for mixed container gardening. The workhorse format for residential replacement cycles across North American garden retailers.
- Large Containers:12-24 inch diameter vessels for specimen plantings and small trees. Premium pricing tier with concentrated demand in affluent suburban markets.
- Extra Large:Vessels exceeding 24 inches for commercial landscaping and estate installations. Limited retail distribution; primarily procured through wholesale landscape supply channels.
Medium Planters dominate unit movement. Large Containers capture disproportionate margin pools.
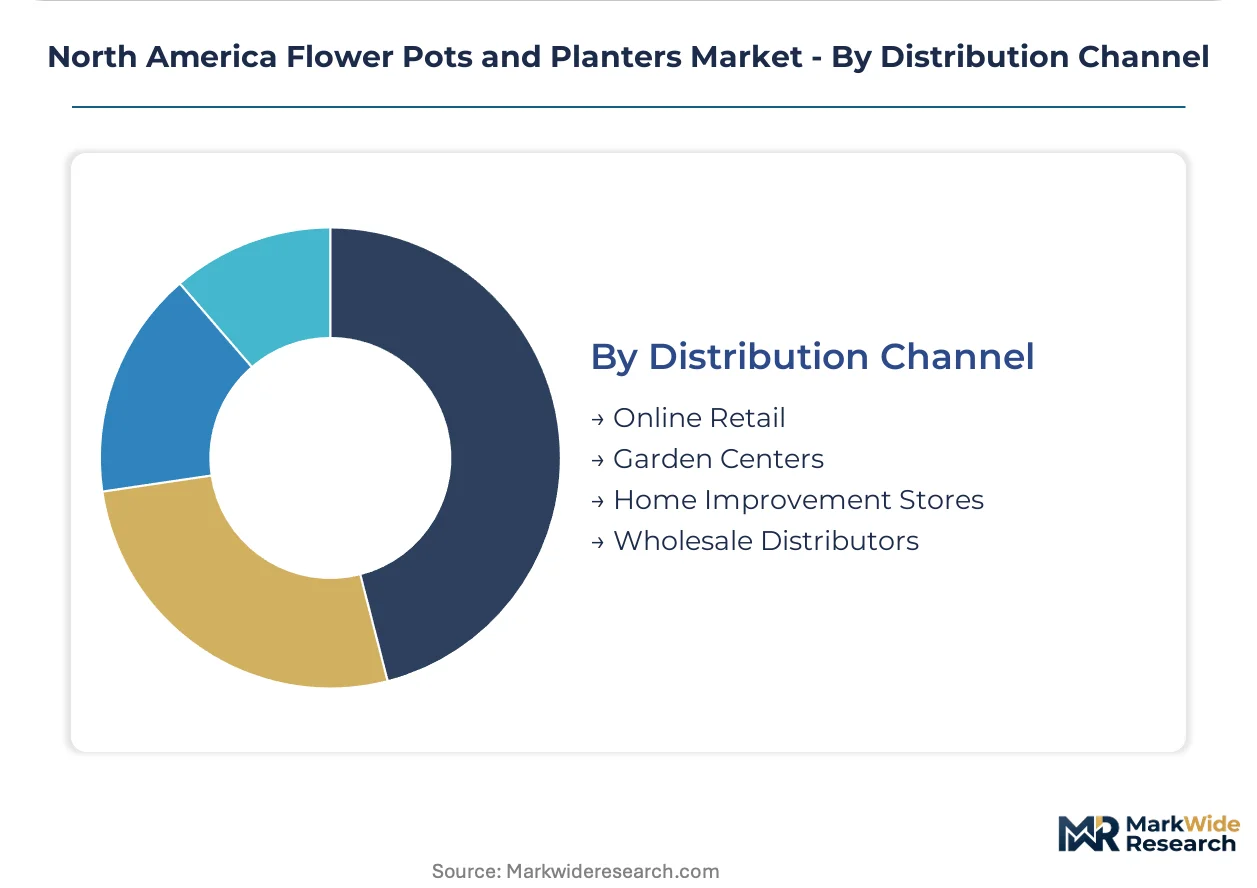
Distribution Channel:
Customer type bifurcation separates price-sensitive mass-market purchasers from service-seeking commercial buyers, with digital platforms capturing volume previously flowing through field-staffed distributor networks.
- Online Retail:Direct-to-consumer and marketplace platforms with logistics-optimized packaging. Amazon and specialized garden platforms capture urban balcony gardening demand with subscription replenishment models.
- Garden Centers:Independent and chain specialty retailers with trained horticultural staff. Survive on color-matching expertise and exclusive compounding capabilities that differentiate shelf presence.
- Home Improvement Stores:Big-box channels with dedicated thermoforming lines and high-volume procurement. Lowe's and Home Depot specify minimum recycled content thresholds that exclude non-integrated compounders.
- Wholesale Distributors:Landscape supply and commercial horticulture channels with field technical staff. Losing volume to manufacturer-hosted digital procurement platforms as Ontario and Michigan greenhouse buyers unbundle after-sales service.
Home Improvement Stores lead by volume. Online Retail climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the U.S. Sun Belt states where year-round outdoor living sustains planter replacement cycles, while Canadian urban centers drive balcony gardening adoption. California's regulatory leadership on recycled content and restricted substances shapes manufacturing decisions across the entire North American supply base.
United States
Sun Belt states from Florida to Arizona sustain replacement purchase cycles absent in seasonal climates. The EPA regulates volatile organic compound emissions from solvent-based coatings applied to metal containers. Injection molders in Ohio leverage vertical integration in recycled polypropylene to control feedstock quality across Midwest distribution networks.
Canada
Dense metropolitan housing stock in Vancouver, Toronto, and Montreal converts unused balcony space into active growing areas. Health Canada and PMRA coordinate on pesticide container labeling that indirectly shapes drainage and reservoir design standards for edible gardening applications. Ontario greenhouse clusters drive commercial-grade container demand for hydroponic vegetable propagation.
California
Statewide restrictions on single-use plastics push manufacturers toward post-consumer resin formulations with minimum recycled content thresholds. The Department of Toxic Substances Control enforces restricted substance thresholds in colored plastics through Safer Consumer Products regulations. Pacific Coast municipal composting infrastructure expansion enables biodegradable pot categories previously limited to backyard disposal.
British Columbia
Extended producer responsibility frameworks impose end-of-life collection obligations on plastic planter manufacturers operating in provincial retail channels. Municipal recycling regulations create collection infrastructure that normalizes recycled-content planters. Vancouver's urban density sustains balcony gardening demand with logistics-optimized procurement through digital platforms.
Quebec
Pending packaging laws align with British Columbia's regulatory trajectory on producer responsibility for plastic goods. Health Canada coordination on edible gardening standards shapes reservoir design specifications for containers used in food production. Montreal's metropolitan housing stock converts unused outdoor space into active growing areas with compact vessel demand.
North America Flower Pots and Planters Market Competitive Landscape
Backward integration into resin sourcing dominates the current landscape as manufacturers reconfigure compounding operations to meet California and British Columbia procurement mandates. The vendor base compresses between integrated compounders with captive recycled polypropylene supply and smaller regional players struggling to absorb compliance overhead. Three archetypes occupy distinct positions: vertically integrated molders controlling feedstock quality, color-compounding specialists differentiating shelf presence, and dedicated thermoforming operators serving high-volume retail channels. M&A activity and strategic partnerships concentrate among compounders seeking geographic expansion to offset resin price volatility.
Within the integrated manufacturing tier, HC Companies anchors positions through Ohio-based production footprinting, while Bloem Living occupies the color-differentiation vector with proprietary compounding capabilities. East Jordan Plastics exemplifies the scale-driven thermoforming archetype serving big-box home improvement channels with dedicated production lines. These three entities collectively represent the structural segmentation of supply-side control across feedstock access, shelf presence, and volume throughput.
| Leading Market Players |
|---|
| HC Companies |
| Bloem Living |
| East Jordan Plastics |
| Keter |
| Deroma |
| Crescent Garden Company |
| Mayne Inc. |
| Tusco Products |
| Novelty Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Post-consumer polypropylene resin costs cascade through three distinct pricing tiers as recycled-content mandates from California and British Columbia reshape procurement economics across the North American supply base.
Pricing Analysis
Volume concentrates in commodity plastic pots where injection-molded polypropylene competes on per-unit cost, while margin pools accrue to ceramic planters with artisan glazing and certified biodegradable formats for municipal composting infrastructure. Price differentiation hinges on recycled-content certification thresholds and exclusive color-compounding capabilities that command shelf-premiums at garden retailers. Pricing pressure intensifies in standard plastic tiers as post-consumer resin availability fluctuates with municipal collection funding. Commercial horticulture buyers in Ontario and Michigan greenhouse clusters exhibit highest price sensitivity, unbundling after-sales service to treat containers as pure commodity inputs.
Supply Chain Analysis
Recycled polypropylene feedstock rests on municipal collection programs in Ohio, California, and British Columbia, with compounders drawing from post-industrial regrind streams and curbside recovery operations. Virgin resin alternatives anchor in Gulf Coast petrochemical corridors, while pigment and additive packages source from specialty chemical producers in Ohio and New Jersey. Single-source vulnerability concentrates in color-matching talent pools among legacy Ohio manufacturers with polymer chemistry expertise. Distribution runs through big-box home improvement channels with dedicated thermoforming lines, garden centers with trained horticultural staff, and direct digital platforms capturing commercial horticulture volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Flower Pots and Planters Market functions as a vertical-integration race where control over post-consumer resin feedstock separates viable competitors from margin-squeezed assemblers.
For Market Incumbents: Extend backward integration into municipal recycling partnerships and post-consumer resin compounding to lock in feedstock access before British Columbia and Quebec extended producer responsibility frameworks consolidate supply. Acquire color-matching technical talent from legacy Ohio manufacturers to defend shelf-differentiation premiums against private-label encroachment. Secure dedicated thermoforming line contracts with Home Depot and Lowe's to maintain volume throughput against digital-platform disintermediation. For New Entrants and Emerging Players: Direct-to-grower digital procurement platforms offer the most penetrable route for bypassing distributor markups in Ontario and Michigan commercial horticulture clusters. Target biodegradable pot categories enabled by Pacific Coast and Northeast municipal composting infrastructure expansion, where category development lags infrastructure deployment. Pursue edible gardening certification alignment with Health Canada reservoir design standards as a first-mover positioning lever. For Investors and Strategic Acquirers: California Safer Consumer Products regulatory enforcement actions against non-compliant compounders serve as the leading indicator that feedstock-access consolidation will accelerate among integrated manufacturers. Position acquisition screens around Ohio-based molders with captive recycled polypropylene supply and proprietary color-compounding capabilities. Watch municipal composting infrastructure buildout rates across Vancouver, Toronto, and Pacific Coast corridors as the demand-trigger for biodegradable format scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive post-consumer polypropylene supply secures margin predictability under California procurement mandates. |
| Color-Compounding Capability Investment | Proprietary pigment dispersion expertise commands shelf-premiums at garden center channels. |
| Municipal Composting Infrastructure Partnership | Biodegradable pot distribution aligns with Pacific Coast and Northeast corridor facility expansion. |
| Direct Digital Platform Development | Manufacturer-hosted procurement captures commercial horticulture volume from field-staffed distributors. |
| Edible Gardening Certification Alignment | Health Canada reservoir compliance creates first-mover advantage in food-production container segments. |
Research Methodology
Trade association filings, municipal procurement databases, and EPA regulatory dockets formed the secondary backbone, cross-referenced with primary interviews involving plant managers at Ohio injection molding facilities, procurement leads at big-box home improvement retailers, composting facility operators in California and British Columbia, and regulatory affairs specialists at state environmental agencies. Bottom-up and top-down triangulation validated volume estimates across material formats and distribution channels.
Bottom-up modeling aggregated unit economics by product type, application, and regional regulatory cluster, while top-down approaches cross-checked aggregate market sizing against customs data and channel shipment disclosures. Segmentation dimensions included material format, size tier, distribution channel, and regional compliance framework. CAGRs derived from trend extrapolation of replacement cycle frequencies, infrastructure buildout timelines, and regulatory enforcement trajectories. Forecast inputs incorporated greenhouse cluster expansion rates in Ontario and Michigan, municipal composting capacity additions, and post-consumer resin availability indices.
The model holds under steady regulatory enforcement and resin supply continuity; deviation in California Safer Consumer Products threshold tightening or British Columbia extended producer responsibility acceleration would shift competitive positioning toward integrated compounders. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Aquarium LED Lighting Market
Home & Garden
Global Hot Tub Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Preserved Flowers Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
Incense Market
Home & Garden
Flower Box Market
Home & Garden
Gardening Pots Market
Home & Garden
Automated Blinds and Shades Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Bird House Market
Home & Garden
North America Flowerpots Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Landscaping Products Market
Home & Garden
Flowerpots and Planters Market