
 Artificial Plants Market | 2026-2036
Artificial Plants Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Plants Market Analysis
Buyer concentration across the hospitality and commercial real estate sectors is recalibrating procurement patterns for artificial foliage. Nearly Natural Inc leverages direct-to-hotel contracts to sustain recurring revenue from property management groups. Commercial Silk anchors its position through specification-grade fire-retardant certifications that meet North American building codes. ULAND competes on manufacturing scale, operating integrated production facilities that control cost structures across polyester and silk product lines.
Artificial plants encompass fabricated botanical replicas constructed from injection-molded plastics, woven polyester fibers, or hand-assembled silk components, designed to mimic natural morphology without biological maintenance requirements. The manufacturing process employs UV-stabilized pigments and wire-reinforced stems to achieve dimensional stability under prolonged indoor exposure. Indoor plants dominate volume demand from residential and corporate interiors, while silk and polyester material grades capture premium margin pools through tactile realism. Online retail channels are expanding fastest, displacing traditional department store distribution as consumers prioritize visual verification through high-resolution imagery and augmented reality preview tools.
The US Consumer Product Safety Commission enforces flammability standards under the Flammable Fabrics Act, while California Proposition 65 mandates disclosure of phthalate content in plastic-based decorative goods. The EU REACH regulation restricts certain flame retardants and plasticizers, compelling reformulation of PVC-heavy outdoor product lines. ISO 4892 weathering test protocols shape durability claims for exterior-grade artificial plants. Stakeholders must monitor evolving state-level chemical disclosure mandates and third-party green certification schemes that threaten to bifurcate compliant from non-compliant supplier bases.
Market Dynamics
REACH compliance in Europe and evolving fire-retardant standards in commercial spaces are elevating material specifications across the artificial plants supply base. Procurement teams at hospitality chains now require third-party certification documentation before contract execution.
Growth Catalysts
- Hospitality sector expansion:Hotel chains in China and the United States are standardizing lifelike foliage installations across property portfolios. Property management groups issue recurring purchase orders for lobby and guest room refreshes.
- E-commerce channel maturation:Augmented reality preview tools reduce return rates for online artificial plant purchases. Digital-native retailers capture volume previously held by department store distribution.
- REACH and Prop 65 alignment:European and Californian chemical disclosure mandates filter non-compliant suppliers from specification-grade procurement lists. Compliant manufacturers access restricted commercial real estate channels.
Market Restraints
- Petroleum-based input volatility:Polyester resin and PVC prices fluctuate with crude oil benchmarks. Margin compression hits mid-tier producers lacking long-term polymer supply contracts.
- Guangdong-Zhejiang supply concentration:Production clusters in China's Pearl River and Yangtze River deltas create geographic risk exposure. Buyers face single-source vulnerability for hand-assembled silk components.
- Live plant substitution in premium residential:Biophilic design purists reject synthetic alternatives for high-end interiors. Organic horticulture services capture budget allocations from affluent homeowners.
Strategic Opportunities
- Underpenetrated Indian commercial real estate:Grade-A office stock expansion in Bengaluru and Mumbai lacks established artificial foliage procurement norms. Early entrants shape specification standards.
- EU Green Deal procurement incentives:Public sector tenders increasingly weight lifecycle environmental assessments. Recyclable polyethylene terephthalate product lines qualify for preferential scoring.
- Fire-retardant certification convergence:UL 94 and BS 5852 testing protocols merge into unified commercial building code language. Dual-certified suppliers reduce buyer compliance overhead.
Industry Challenges
- Skilled hand-assembly labor scarcity:Silk flower crafting requires trained artisans capable of wire-wrapping and petal-dyeing techniques. Wage inflation in Dongguan and Yiwu erodes cost advantages.
- ISO 4892 weathering test compliance timelines:Exterior-grade product development cycles extend 18-24 months for UV-stabilization validation. Accelerated aging protocols demand capital-intensive testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Plants Market |
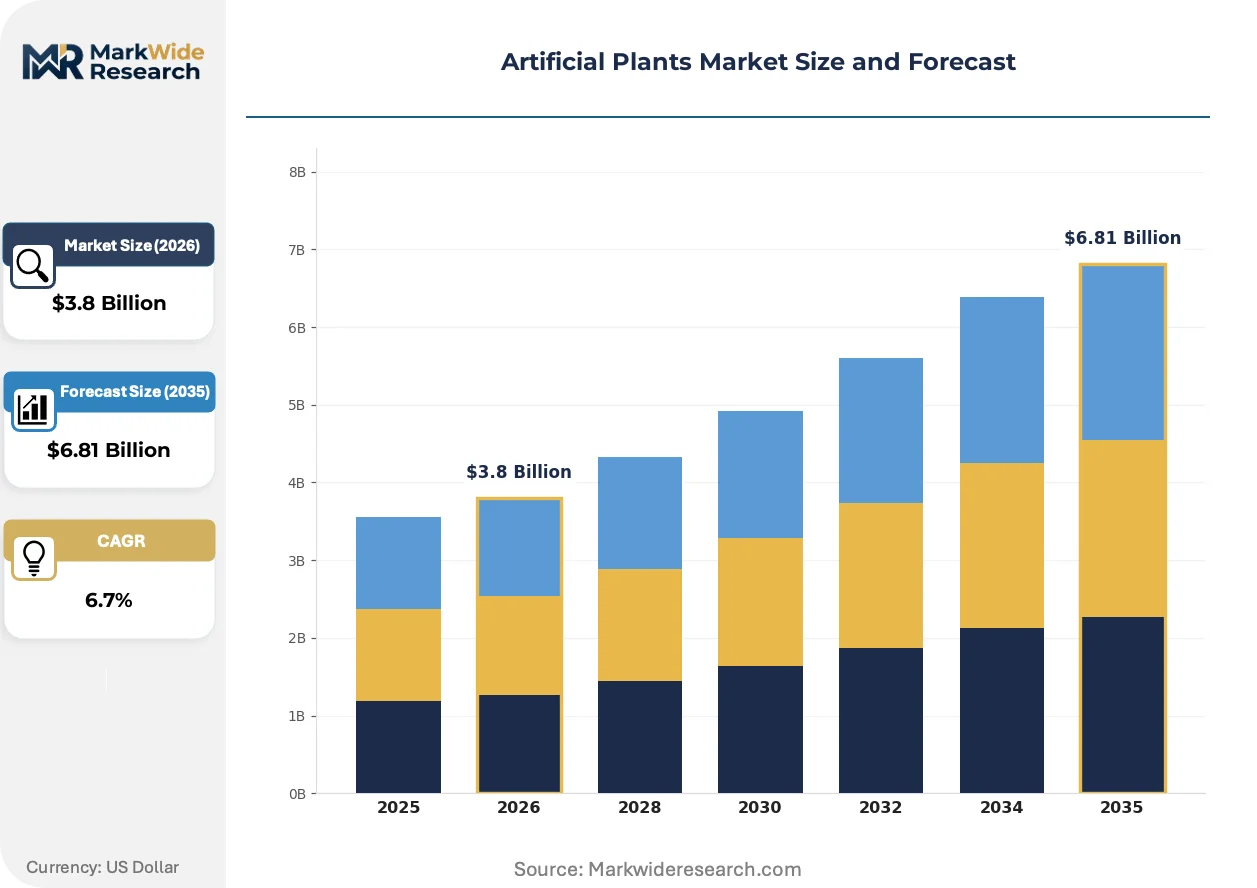
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Plants, Outdoor Plants, Flower Arrangements, Miniatures Material: Plastic, Silk, Polyester, Foam Use Case: Home Decor, Office Decor, Event Decoration, Gifts Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Dongyi Artificial Plants Co Ltd, Commercial Silk, National Tree Company, ULAND, Sunwing Industries Limited, Nearly Natural Inc, HRtrees, Maxifleur Kunstplanten, EdenVert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Plants Market Emerging Trajectories
Material science advances and digital distribution infrastructure are compressing traditional competitive advantages in artificial foliage manufacturing. Three developments warrant particular attention from procurement strategists.
Injection-molded polyethylene foliage is consolidating quality tiers previously separated by hand-assembly labor intensity. Hospitality procurement teams at Marriott and Hilton property groups now accept machine-molded alternatives for high-traffic installations. The technology compresses price bands between premium silk and standard polyester grades.
California Proposition 65 enforcement actions against phthalate-containing decorative goods are forcing reformulation of legacy PVC-heavy outdoor lines. Manufacturers serving the US market must disclose chemical content or face litigation exposure. Exterior-grade artificial plants face the steepest compliance costs due to plasticizer dependency for weathering performance.
Direct contracting between hotel ownership groups and manufacturing facilities is bypassing traditional wholesale distribution layers. Marriott's procurement consortium negotiates volume commitments with Dongyi and Sunwing production clusters directly. This channel compression is most visible in China, where domestic hospitality chains replicate the model for property rollout programs.
Artificial Plants Market Segmentation
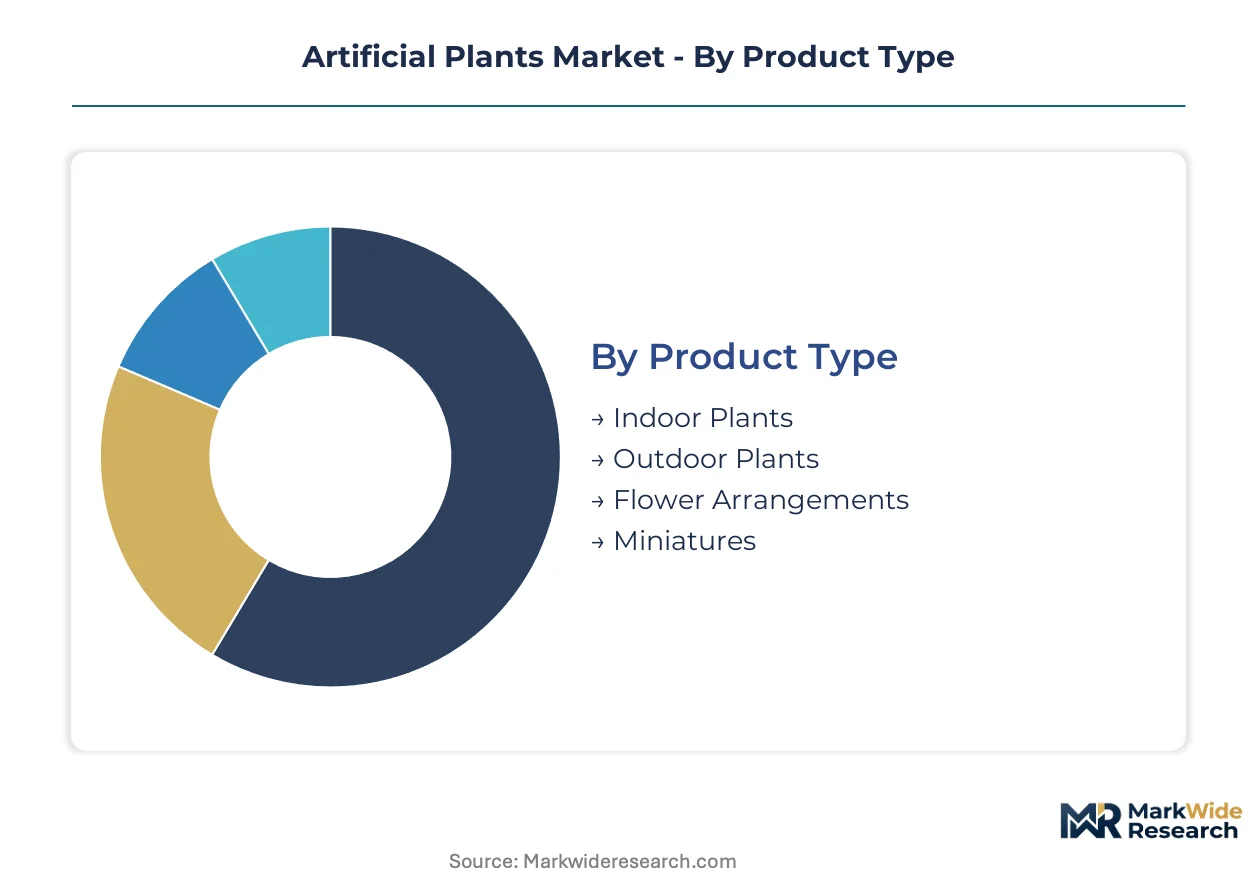
Artificial plants segment across four dimensions that determine manufacturing complexity, margin structure, and channel strategy. Product type and material composition shape production economics, while use case and distribution channel dictate pricing power and customer acquisition costs.
Product Type:
Customization intensity varies sharply across this category, from standardized mass-produced stems to bespoke architectural installations requiring site-specific dimensioning.
- Indoor Plants:UV-stabilized polyethylene and silk-polyester blends replicate tropical and temperate species for residential and corporate interiors. Hospitality procurement teams at Marriott and Hilton property groups specify fire-retardant grades for lobby installations, with recurring refresh cycles driving contract renewal rates.
- Outdoor Plants:PVC-heavy formulations with ISO 4892 weathering certification withstand prolonged UV exposure and thermal cycling. California Proposition 65 enforcement has forced reformulation of legacy plasticizer-dependent lines, elevating compliance costs for exterior-grade production.
- Flower Arrangements:Hand-assembled silk components with wire-reinforced stems serve event decoration and premium residential segments. Dongguan and Yiwu artisan clusters supply the skilled labor for petal-dyeing and botanical arrangement.
- Miniatures:Injection-molded micro-scale replicas target tabletop displays and architectural model applications. Scale constraints favor automated production over hand-assembly, compressing unit economics toward commodity tiers.
Leading the category by volume: Indoor Plants. Expanding most quickly: Outdoor Plants.
Material:
Cost tier alignment separates specification-grade procurement from mass-market retail, with certification requirements and tactile realism driving material selection.
- Plastic:Injection-molded PVC and polyethylene dominate high-volume production for commercial installations. REACH compliance in Europe and evolving fire-retardant standards in North America elevate material specifications, filtering non-compliant suppliers from specification-grade channels.
- Silk:Hand-woven natural fiber replicas command premium positioning through tactile authenticity. Wage inflation in Guangdong and Zhejiang provinces erodes cost advantages for artisan-dependent production.
- Polyester:Woven synthetic fibers balance durability and cost across mid-market residential and corporate segments. Integrated production facilities in China control cost structures across standard and premium grades.
- Foam:Molded polyurethane and latex formulations enable lightweight, hyper-realistic botanical sculptures for event and theatrical applications. Limited production scale constrains distribution beyond specialty channels.
Highest margin capture: Silk. Steepest volume climb: Polyester.
Use Case:
Customer type determines purchase frequency, with institutional buyers issuing recurring contracts versus one-off residential transactions.
- Home Decor:Individual consumers prioritize visual verification through augmented reality preview tools, accelerating channel shift toward online retail. Return rate reduction from AR adoption improves unit economics for digital-native sellers.
- Office Decor:Corporate facilities managers specify fire-retardant certifications under North American building codes. Commercial Silk and similar suppliers anchor positioning through UL 94 and BS 5852 documentation.
- Event Decoration:Rental and purchase cycles concentrate demand around seasonal peaks, with wedding and hospitality event planners driving bulk procurement. Quality tiers separate disposable single-use from archival rental inventory.
- Gifts:Compact formats and premium packaging target occasion-based purchasing with limited repeat rates. Department store distribution retains residual share despite channel compression.
Dominant by revenue: Home Decor. Gaining share fastest: Office Decor.
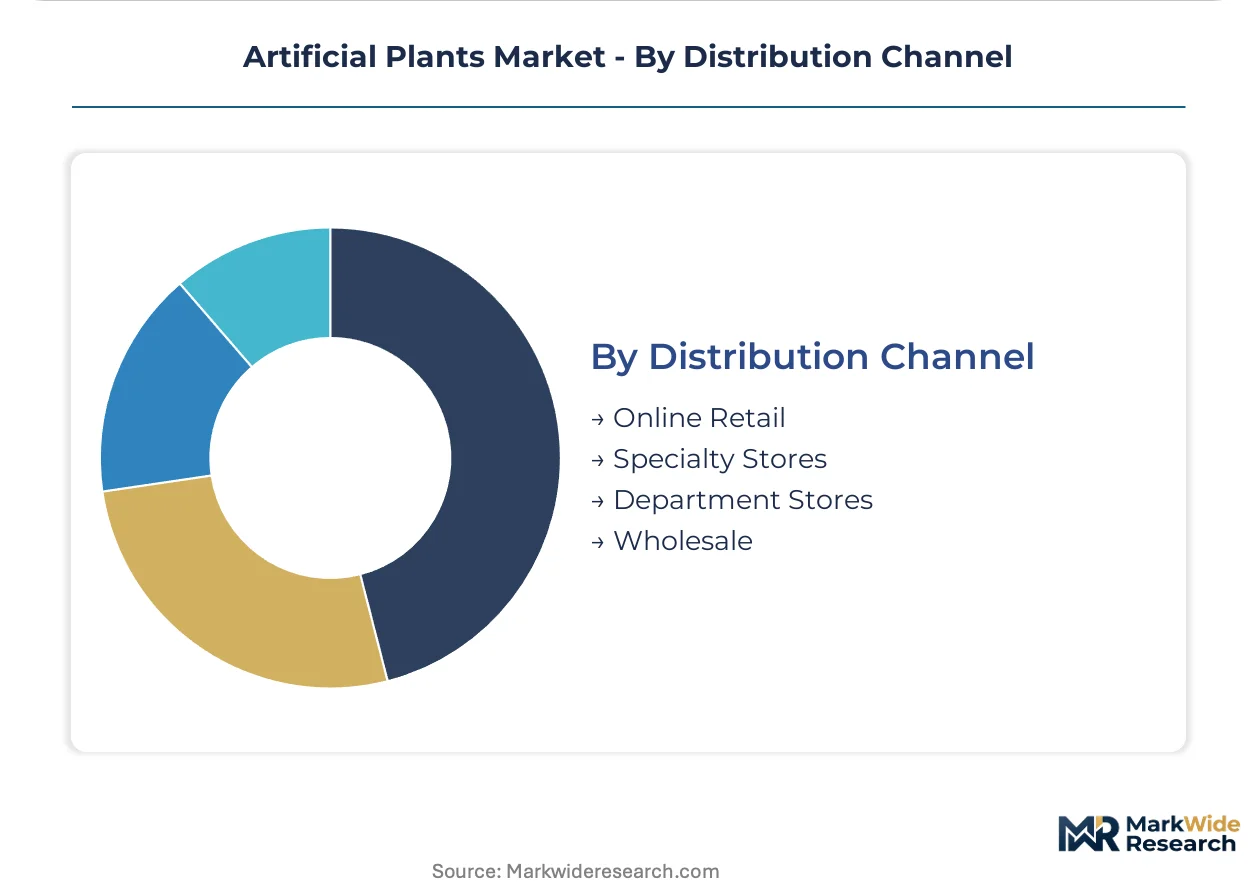
Distribution Channel:
Supply concentration in China's Pearl River and Yangtze River deltas shapes channel economics, with direct contracting bypassing traditional wholesale layers.
- Online Retail:Digital-native platforms capture volume previously held by department stores through high-resolution imagery and AR visualization. Nearly Natural Inc leverages direct-to-hotel contracts alongside consumer-facing e-commerce.
- Specialty Stores:Curated assortments with tactile evaluation serve premium residential and design professional segments. Limited footprint constrains scale but preserves margin through service differentiation.
- Department Stores:Legacy distribution faces displacement as consumers prioritize digital discovery and verification. Remaining share concentrates in gift-oriented impulse purchasing.
- Wholesale:Traditional distribution layers face compression from direct contracting between hotel ownership groups and Dongyi and Sunwing production clusters. Volume commitments bypass intermediary markups for large-scale property rollouts.
Largest volume flow: Online Retail. Channel compression hitting hardest: Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality procurement teams in China and the United States issue the largest recurring contracts for fire-retardant foliage installations. European regulatory pressure through REACH compliance filters supplier bases in commercial real estate channels. Production gravity concentrates in Guangdong and Zhejiang provinces, with secondary clusters emerging in India and Southeast Asia.
United States
Marriott and Hilton property groups standardize lifelike foliage across portfolio rollouts, driving recurring purchase orders for lobby and guest room refreshes. California Proposition 65 enforcement mandates phthalate disclosure in PVC-heavy decorative goods, elevating compliance costs for exterior-grade lines. Los Angeles and Miami hospitality markets anchor demand concentration for specification-grade installations.
China
Domestic hotel chains replicate direct contracting models with manufacturing facilities, bypassing traditional wholesale distribution layers. MIIT oversees industrial standards for synthetic fiber production under GB certification frameworks. Dongguan and Yiwu artisan clusters supply hand-assembled silk components, though wage inflation erodes cost advantages for labor-intensive petal-dyeing techniques.
Germany
Grade-A office stock expansion in Frankfurt and Munich creates procurement opportunities for fire-retardant certified installations. ECHA administers REACH restrictions on flame retardants and plasticizers, compelling reformulation of legacy product lines. Bavaria-based distributors serve as specification gatekeepers for EU commercial real estate channels.
India
Bengaluru and Mumbai commercial real estate expansion lacks established artificial foliage procurement norms, opening channels for early entrants to shape standards. BIS certification requirements for imported decorative goods create compliance thresholds for foreign suppliers. Maharashtra industrial corridors host emerging assembly operations targeting domestic hospitality demand.
United Arab Emirates
Dubai and Abu Dhabi hospitality developments prioritize UV-stabilized exterior-grade installations for desert climate exposure. MOHAP oversees product safety standards for imported decorative goods entering Gulf Cooperation Council markets. Jebel Ali logistics zones facilitate re-export distribution to Saudi Arabia and Qatar project sites.
Artificial Plants Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-hotel contracting and sustainability-certified positioning. The vendor base stratifies across three capability tiers: integrated manufacturers with captive polyester production, specification-grade specialists holding dual fire-retardant certifications, and digital-native retailers leveraging augmented reality visualization. Consolidation pressure concentrates among mid-tier wholesalers facing channel compression from direct procurement relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers securing long-term polymer supply contracts and hospitality ownership groups.
Within the integrated manufacturing tier, Dongyi Artificial Plants Co Ltd and Sunwing Industries Limited occupy positions anchoring Guangdong and Zhejiang production clusters. Among specification-grade specialists, Commercial Silk exemplifies certification-driven positioning through UL 94 and BS 5852 documentation. Nearly Natural Inc represents the direct-contracting archetype, leveraging digital-native distribution alongside hospitality procurement relationships.
| Leading Market Players |
|---|
| Dongyi Artificial Plants Co Ltd |
| Commercial Silk |
| National Tree Company |
| ULAND |
| Sunwing Industries Limited |
| Nearly Natural Inc |
| HRtrees |
| Maxifleur Kunstplanten |
| EdenVert |
| Others |
Supply Flow & Price Mechanics
Hand-assembly artisan clusters in Dongguan and Yiwu compress pricing-tier spreads by tethering premium silk-grade margins to wage-inflation differentials rather than raw material costs. REACH compliance investments and fire-retardant certification overhead widen the gap between specification-grade commercial contracts and mass-market polyester lines.
Pricing Analysis
Volume concentrates in injection-molded polyethylene tiers while margin pools accrue to hand-woven silk grades with wire-reinforced stem construction. Price differentiation hinges on UL 94 and BS 5852 certification status alongside tactile realism benchmarks. Pricing pressure stems from petroleum-based input volatility hitting mid-tier producers lacking long-term polymer contracts. Hospitality procurement teams show lowest price sensitivity due to recurring refresh cycles, while individual residential buyers prioritize visual verification tools that reduce return-rate risk.
Supply Chain Analysis
Reverse-logistics flows for e-commerce returns concentrate refurbishment capacity in Guangdong province, where secondary sorting facilities feed artisan clusters with recoverable silk components. Production gravity centers on China, with secondary assembly emerging in India and Vietnam for regional hospitality markets. Raw material dependencies span polyester resin, PVC formulations, and UV-stabilized pigments. Single-source vulnerability for hand-assembled components creates structural risk exposure. Distribution runs through direct contracting between hotel ownership groups and integrated manufacturers, bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Channel compression from direct procurement relationships forces consolidation among mid-tier wholesalers lacking certification depth or captive production capacity.
For Market Incumbents: Hedge against margin erosion by securing long-term polymer supply contracts and deepening backward integration into UV-stabilized pigment production. Invest in dual UL 94 and BS 5852 certification to maintain specification-grade access as commercial building codes converge. Counter live-plant substitution threats in premium residential through hyper-realistic foam-sculpture product lines. For New Entrants and Emerging Players: Direct-to-hotel digital contracting routes offer the lowest barrier to recurring revenue capture. Target underpenetrated Grade-A office stock in Bengaluru and Mumbai where procurement norms remain unformed. Lead with augmented reality visualization tools that reduce return rates and accelerate online retail share capture. For Investors and Strategic Acquirers: The window for entry favors integrated manufacturers with captive polyester production and established REACH compliance documentation. Long-term viability rests on scale advantages in injection-molded polyethylene and direct-contracting relationships with hospitality ownership groups. Monitor EU Green Deal procurement incentive expansion as the inflection signal for recyclable PET product line valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Fire-Retardant Certification Investment | UL 94 and BS 5852 documentation unlocks specification-grade commercial real estate channels. |
| Direct-to-Hotel Contracting Expansion | Marriott and Hilton procurement consortiums bypass wholesale layers for volume commitment pricing. |
| Recyclable PET Product Line Development | EU Green Deal tender scoring advantages reshape public sector procurement eligibility. |
| Backward Integration into Pigment Production | Captive UV-stabilized supply hedges petroleum-based input volatility for exterior-grade lines. |
| AR Visualization Platform Deployment | Digital-native retailers reduce return rates through high-resolution preview tools displacing department stores. |
Methodological Framework
Trade association filings, customs export records, and hospitality procurement databases formed the secondary backbone, supplemented by primary interviews with plant managers at integrated manufacturing facilities, procurement leads at property management groups, and channel sales heads at specialty distributors. Bottom-up volume estimates triangulated against top-down spending analysis across the analysis window.
Historical trendline analysis anchored the projection framework, with CAGR derivation reflecting segment-specific growth trajectories across product type, material composition, use case, and distribution channel dimensions. Modeled inputs included hospitality property rollout schedules, e-commerce penetration curves, and regulatory compliance cost trajectories for REACH and Proposition 65 alignment.
The model holds under stable polymer supply contracting and continued hospitality sector expansion; deviation in crude oil benchmark volatility or live-plant biophilic design preference would shift volume forecasts. Practitioners should monitor EU Green Deal procurement weighting adjustments and California Proposition 65 enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Flexible Garden Hoses Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Landscaping Services Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Japan Flower Pots Market
Home & Garden
North America Floral Gifting Market
Home & Garden
Wine Racks Market
Home & Garden
Incense Market
Home & Garden
Aquarium Decor Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
Aquarium LED Lighting Market
Home & Garden
Bird House Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Preserved Flowers Market
Home & Garden
Automated Blinds and Shades Market
Home & Garden
Flowerpots and Planters Market