
 Cups and Pots Market | 2026-2036
Cups and Pots Market Size, Share, and Industry Trends Forecast 2026-2036
Cups and Pots Market Insights
Buyer concentration among café and restaurant chains is hardening as multi-location operators consolidate procurement under national supply agreements. Thermos leverages its vacuum-insulation patents to dominate commercial hot-beverage accounts. Tiger Corporation anchors its position through Japanese manufacturing precision that commands premium placement in specialty retail. Zojirushi competes on programmable temperature control that extends product utility into outdoor and travel segments.
Cups and pots comprise rigid food-service and consumer vessels engineered from ceramics, glass, metals, or polymers, with wall thickness, thermal conductivity, and leach-test compliance defining functional grade. Injection-molded polypropylene and slip-cast stoneware represent the dominant production methods, with fired ceramics requiring lead-free glaze certification for food contact. Stainless steel mugs lead the product-type hierarchy in value terms due to durability premiums in commercial channels, while bone china occupies the highest margin pool among household buyers. The design-style dimension shows modern minimalist forms outpacing vintage revival SKUs in replenishment velocity across European and Asian specialty retailers.
China's SAMR enforces GB 4806 food-contact material standards that mandate migration testing for heavy metals in ceramic glazes, directly shaping supplier qualification costs. The EU's REACH framework and F-Gas Regulation indirectly pressure manufacturers to eliminate certain blowing agents and surface treatments in insulated double-wall construction. India's FSSAI has begun aligning import clearance rules with Codex Alimentarius guidelines for melamine migration limits. Stakeholders must monitor how divergent national testing regimes fragment compliance architectures and reshape sourcing geography.
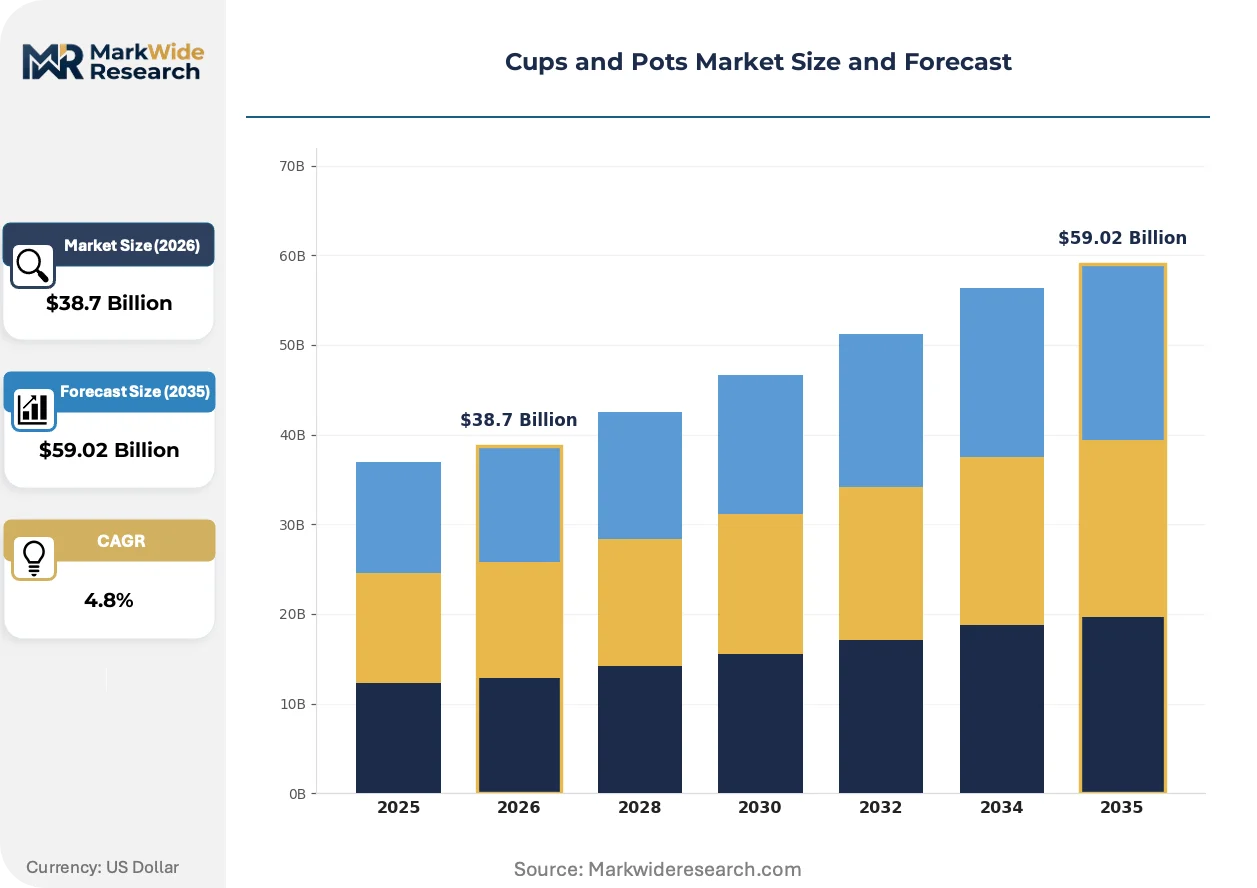
Market Dynamics
Café chain procurement consolidation is compressing supplier margins while China's GB 4806 ceramic glaze testing mandates reshape qualification economics for export-oriented manufacturers.
Growth Catalysts
- Specialty coffee chain expansion:Branded drinkware programs at multi-location operators in the United States and Canada are pulling vacuum-insulated stainless steel into high-visibility retail placement.
- REACH F-Gas Regulation compliance:European manufacturers eliminating hydrofluorocarbon blowing agents in double-wall construction are accelerating adoption of water-based foam insulation alternatives.
- Tier-two urban café culture:Coffee shop proliferation in Indian cities including Pune, Ahmedabad, and Jaipur is generating incremental demand for commercial-grade ceramic and glass serveware.
Market Restraints
- Raw material volatility:Nickel price fluctuations directly impact stainless steel mug production costs, squeezing margin buffers for mid-tier manufacturers without long-term ore contracts.
- Supplier concentration risk:Vacuum-insulation equipment and expertise clusters in Japanese and Chinese manufacturing zones, creating geographic single-point vulnerability for Western brands.
- Technical substitution ceiling:Melamine-formaldehyde resins face persistent displacement pressure from polypropylene in food-service applications due to migration limit uncertainties.
Strategic Opportunities
- Underpenetrated Indian household segment:Premium bone china and borosilicate glass remain below saturation in South Indian urban markets outside Bangalore and Chennai.
- Outdoor recreation application expansion:Programmable temperature control technology from travel mug categories is integrating into camping and overlanding equipment lines.
- FSSAI-Codex alignment:India's harmonization of import clearance rules with international food-contact standards reduces friction for compliant exporters entering the subcontinent.
Industry Challenges
- Lead-free glaze certification timelines:Ceramic producers face extended SAMR testing queues for GB 4806 compliance, delaying China market entry by six to twelve months.
- Skill scarcity in precision metalworking:Vacuum chamber welding and seamless double-wall fabrication expertise concentrates in aging Japanese technician populations.
- Legacy ERP integration friction:Smaller slip-cast ceramics houses struggle to connect batch traceability systems with downstream café chain procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cups and Pots Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Cups, Glass Pots, Stainless Steel Mugs, Plastic Containers End User: Households, Cafés, Restaurants, Catering Services Design Style: Modern, Vintage, Minimalist, Artistic Material: Bone China, Stoneware, Earthenware, Melamine |
| Companies Covered | Thermos, Tiger Corporation, Zojirushi, Tafuco, Fuguang, HAERS, TOMIC, Zhejiang Waya Cups, Zhejiang Xiongtai Houseware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cups and Pots Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are reconfiguring production methods while buyer consolidation forces channel restructuring across food-service and household segments.
Smart temperature control circuitry is integrating into mid-premium travel mug lines, enabling Bluetooth-connected heating elements that maintain beverage temperature within two degrees of user-set targets. Outdoor recreation buyers and long-haul commuters are adopting these units at triple the rate of conventional vacuum vessels. This functionality is integrating hardware margins with recurring app ecosystem revenue, compressing traditional price-tier boundaries between commodity and premium positioning.
China's SAMR enforcement of GB 4806.4-2016 ceramic glaze migration limits is eliminating small-batch artisan producers unable to fund third-party laboratory certification. Export-oriented manufacturers in Dehua and Jingdezhen are consolidating testing relationships with accredited Shanghai and Beijing laboratories to maintain EU and North American market access. Fired ceramics destined for food contact now carry documentation burdens comparable to polymer food-service materials, reshaping supplier qualification costs and minimum viable scale thresholds.
Consolidated procurement at North American café chains is compressing distributor layers, with national supply agreements directly linking roaster-retailers to contract manufacturers. Independent specialty retailers in Germany and the Netherlands are responding through curated direct-import relationships with Japanese and Korean precision metalworkers. This channel restructuring is most visible in the United States, where three multi-location operators now control a majority of commercial hot-beverage vessel specification.
Cups and Pots Market Segmentation
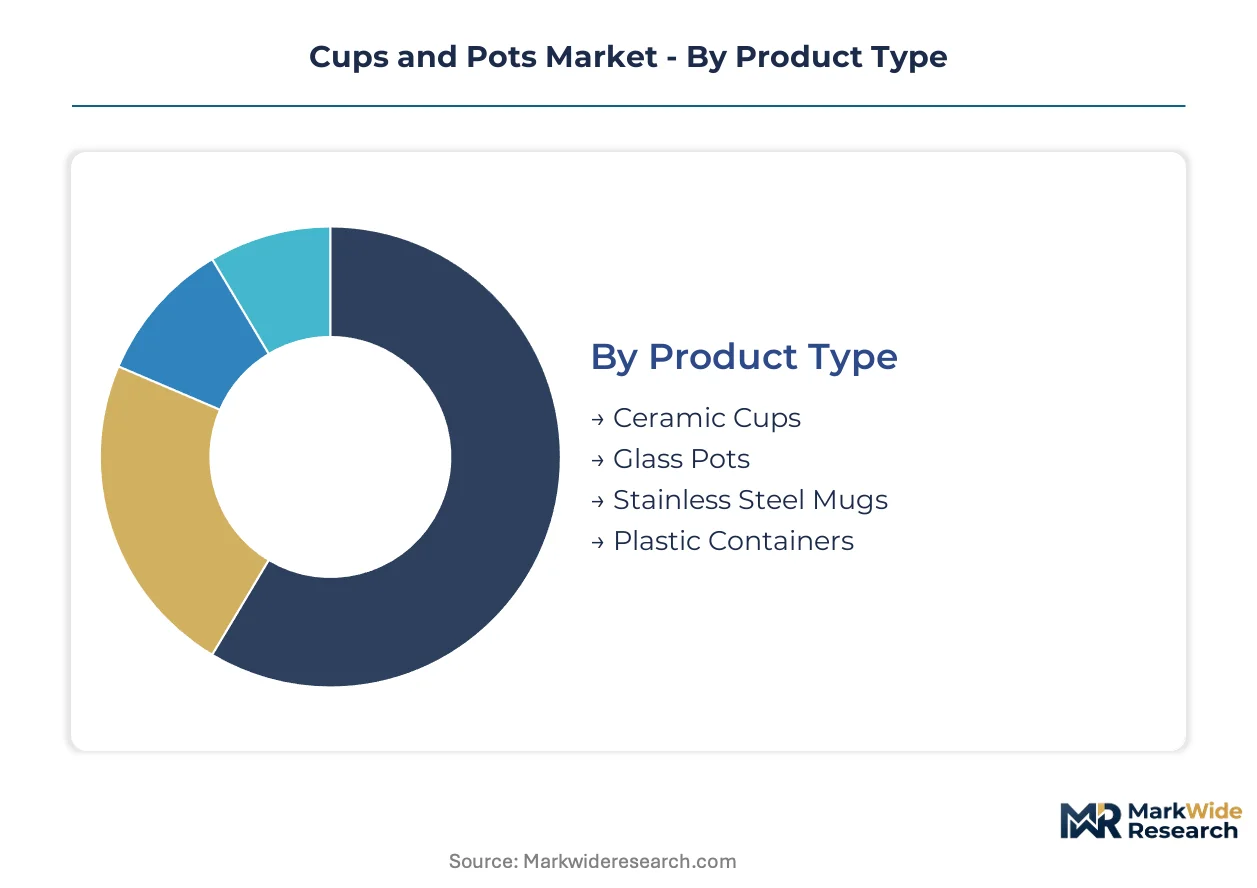
Segmentation in the cups and pots market exposes divergent margin structures across material science capabilities and procurement scale. Buyer requirements split sharply between food-service durability demands and household aesthetic preferences, forcing manufacturers to choose specialization paths.
Product Type:
Buyers differentiate by thermal performance needs and breakage tolerance in commercial versus residential settings.
- Stainless Steel Mugs:Vacuum-insulated double-wall construction delivers temperature retention exceeding six hours for hot beverages. Demand concentrates in North American specialty coffee chains where branded travel mugs generate repeat visibility and customer loyalty program attachment.
- Ceramic Cups:Slip-cast or jiggered vitrified bodies with lead-free glaze certification for food contact. Procurement is hardening in Indian tier-two cities as café culture spreads beyond Mumbai and Delhi into Pune, Ahmedabad, and Jaipur.
- Glass Pots:Borosilicate thermal shock resistance enables direct flame and microwave exposure. European specialty retailers favor these for pour-over coffee service.
- Plastic Containers:Injection-molded polypropylene dominates food-service disposables and budget household storage. Migration limit uncertainties under India's FSSAI-Codex alignment pressure substitution toward polymer alternatives.
Volume sits with Plastic Containers; growth tilts toward Stainless Steel Mugs.
End User:
Procurement scale and specification complexity separate institutional buyers from dispersed consumer demand.
- Cafés:Multi-location operators consolidate national supply agreements that mandate batch traceability, custom branding, and durability warranties. Three North American chains now control majority commercial hot-beverage vessel specification.
- Households:Fragmented purchase patterns favor aesthetic differentiation and gift-market positioning. Premium bone china and borosilicate glass remain underpenetrated in South Indian urban markets outside Bangalore and Chennai.
- Restaurants:Full-service operators prioritize stackability and dishwasher resilience over thermal performance. Procurement runs through broadline distributors with private-label programs.
- Catering Services:Event-based demand favors disposable and rental-compatible formats with minimal cleaning logistics. Volume spikes concentrate in wedding season and corporate calendar peaks.
Cafés command specification authority; households offer the steepest expansion trajectory for premium materials.
Design Style:
Aesthetic positioning determines retail channel placement and replenishment velocity in specialty versus mass-market distribution.
- Modern:Clean geometric lines and matte surface treatments align with contemporary kitchen appliance aesthetics. European and Asian specialty retailers show fastest replenishment for this category.
- Minimalist:Reduced ornamentation and neutral palettes target urban apartment dwellers with space constraints. This segment gains share fastest among younger household formations.
- Vintage:Revival patterns and distressed finishes appeal to gift markets and hospitality styling. Velocity lags modern forms in replenishment cycles.
- Artistic:Hand-painted or sculpted limited editions command collector premiums. China's SAMR testing queues for GB 4806 compliance eliminate small-batch artisan producers from food-contact eligibility.
Modern and Minimalist dominate current velocity; Artistic faces regulatory compression.
Material:
Compliance architecture and sourcing geography fragment supplier qualification economics across material categories.
- Bone China:High kaolin content and bone ash yield translucency and chip resistance for premium tableware. UK and Japanese heritage brands anchor positioning through manufacturing origin claims.
- Stoneware:High-fire vitrification produces durable, non-porous bodies suitable for oven-to-table service. Dehua and Jingdezhen export manufacturers consolidate testing relationships with accredited laboratories for EU and North American access.
- Earthenware:Low-fire porous bodies require glaze sealing for liquid containment. Cost positioning sustains presence in casual dining and developing market household segments.
- Melamine:Thermoset amino resin enables bright colors and drop resistance in food-service applications. Persistent displacement pressure from polypropylene intensifies as migration limit scrutiny tightens.
Stoneware holds volume leadership; Bone China delivers margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty coffee chain procurement in the United States is concentrating demand for vacuum-insulated stainless steel vessels, while regulatory tightening across China and India reshapes supplier qualification economics for ceramic and polymer producers.
United States
Three multi-location café operators now control the majority of commercial hot-beverage vessel specification, consolidating national supply agreements that bypass traditional distributor layers. FDA food-contact regulations govern migration limits for polymer and ceramic materials entering food-service channels. Pacific Northwest roasting clusters and Southern California beverage innovation hubs anchor branded drinkware program development.
China
Export-oriented ceramic manufacturers in Dehua and Jingdezhen face extended SAMR testing queues for GB 4806.4-2016 glaze compliance, delaying market entry timelines. SAMR enforcement of food-contact material standards is eliminating small-batch artisan producers unable to fund third-party laboratory certification. Yangtze River Delta and Pearl River Delta manufacturing zones concentrate vacuum-insulation equipment and double-wall fabrication expertise.
India
Café culture proliferation in Pune, Ahmedabad, and Jaipur generates incremental demand for commercial-grade ceramic and glass serveware beyond Mumbai and Delhi saturation. FSSAI alignment of import clearance rules with Codex Alimentarius guidelines reduces friction for compliant exporters entering the subcontinent. South Indian urban markets outside Bangalore and Chennai remain underpenetrated for premium bone china and borosilicate glass.
Japan
Precision metalworking expertise for vacuum chamber welding and seamless double-wall fabrication concentrates in aging technician populations, creating capability scarcity. METI industrial standards and consumer safety frameworks shape premium positioning for temperature-control technologies. Osaka and Nagoya manufacturing clusters anchor heritage brands commanding placement in specialty retail through manufacturing origin claims.
Germany
European specialty retailers in Germany and the Netherlands respond to distributor compression through curated direct-import relationships with East Asian precision metalworkers. ECHA REACH framework and F-Gas Regulation pressure manufacturers to eliminate hydrofluorocarbon blowing agents in double-wall construction. Bavaria and North Rhine-Westphalia retail clusters favor borosilicate glass for pour-over coffee service and modern minimalist form replenishment.
Cups and Pots Market Competitive Landscape
Japanese producers anchor the premium tier through precision manufacturing heritage; Chinese fabricators hold scale-driven supply positions for export-oriented ceramics and polymers. The vendor base splits between consolidated vacuum-insulation specialists and fragmented slip-cast ceramics houses. Three archetypes dominate: heritage precision metalworkers, export-consolidated ceramic manufacturers, and programmable temperature-control integrators. Competitive moves center on testing relationship consolidation with accredited laboratories and backward integration into glaze chemistry control.
Among heritage precision metalworkers, Thermos, Tiger Corporation, and Zojirushi exemplify the premium-tier archetype through manufacturing origin positioning and vacuum-insulation patent portfolios. These Japanese entities occupy positions that command placement in North American specialty coffee chains and European specialty retail through perceived quality differentiation. Chinese fabricators including Fuguang and HAERS represent the scale-driven export tier, consolidating production relationships with Dehua and Jingdezhen ceramic clusters to serve food-service and household demand. The competitive terrain separates along capability lines: precision metalworking expertise versus ceramic glaze compliance scale, with limited overlap in operational competencies.
| Leading Market Players |
|---|
| Thermos |
| Tiger Corporation |
| Zojirushi |
| Tafuco |
| Fuguang |
| HAERS |
| TOMIC |
| Zhejiang Waya Cups |
| Zhejiang Xiongtai Houseware |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap ceramics houses in Dehua and Jingdezhen anchor supply-side discipline through generational glaze-chemistry expertise, translating into pricing power for GB 4806-certified export grades while compressing margins for uncertified artisan competitors.
Pricing Analysis
Volume concentrates in injection-molded polypropylene food-service disposables where commoditization runs deepest, while margins pool in vacuum-insulated stainless steel and bone china tiers where Japanese manufacturing origin and lead-free glaze certification command premiums. Three-tier pricing structure across premium, standard, and economy levels separates programmable temperature-control travel mugs from conventional vacuum vessels from unbranded ceramic commodity serveware. Cost compression in mid-tier stainless steel intensifies because nickel price volatility erodes contract-manufacturing buffers. National café chains exhibit lowest price sensitivity through consolidated procurement scale, while independent specialty retailers in Germany and the Netherlands face acute margin pressure from direct-import competition.
Supply Chain Analysis
Ocean freight rate volatility from Yangtze River Delta ports to North American West Coast terminals directly shapes landed cost economics for export-oriented ceramic manufacturers. Supply concentrates in China for vacuum-insulation equipment and double-wall fabrication, Japan for precision metalworking expertise, and India for tier-two urban distribution expansion. Raw material dependencies span nickel ore for stainless steel production, high-purity kaolin for bone china translucency, and borosilicate glass feedstock for thermal shock-resistant serveware. Single-source vulnerability clusters in Japanese technician populations aging out of vacuum chamber welding specializations. Distribution runs through broadline food-service distributors for restaurant accounts, direct national supply agreements for café chains, and specialty retail curated imports for European household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over glaze chemistry laboratories and accredited testing relationships determines qualification speed for China export access.
For Market Incumbents: Acquire certified testing laboratory relationships in Shanghai and Beijing to compress GB 4806 compliance timelines from twelve months to six. Secure long-term nickel ore contracts to buffer stainless steel production cost volatility against spot market swings. Consolidation of vacuum-insulation equipment fabrication in Yangtze River Delta manufacturing zones addresses geographic single-point vulnerability threatening Western brand supply continuity. For New Entrants and Emerging Players: Specialty retailers in South Indian urban markets outside Bangalore and Chennai offer penetrable white-space for premium bone china and borosilicate glass distribution. Programmable temperature-control camping equipment lines present application expansion opportunities with triple adoption velocity against conventional vacuum vessels. Direct-import partnerships with Dehua export manufacturers bypass distributor compression squeezing European specialty retail margins. For Investors and Strategic Acquirers: Distressed-cycle entries favor GB 4806-compliant ceramic manufacturers with consolidated laboratory testing relationships in China's Pearl River Delta. Long-term viability over the next decade hinges on regulatory chemistry restriction trajectories and automation feasibility for precision metalworking skills concentrated in aging Japanese technician populations. Watch FSSAI-Codex alignment implementation pace as inflection indicator for India import friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glaze Chemistry Control | In-house lead-free formulation accelerates SAMR compliance timelines versus third-party laboratory dependency. |
| Direct National Supply Agreement Expansion | Bypassing distributor layers captures margin compression from consolidated café chain procurement consolidation. |
| Programmable Temperature-Control Platform Extension | Bluetooth-connected heating elements integrate hardware margins with recurring app ecosystem revenue streams. |
| Accredited Testing Laboratory Partnership Consolidation | Exclusive relationships with Shanghai and Beijing laboratories secure GB 4806 certification queue priority. |
| South India Specialty Retail Channel Development | Underpenetrated urban markets in Pune, Ahmedabad, and Jaipur offer premium bone china expansion runway. |
Research Methodology
Trade customs data, SAMR regulatory filings, and specialty coffee chain procurement disclosures formed the secondary backbone, cross-referenced against primary interviews with ceramics plant managers, café chain supply directors, vacuum-insulation equipment engineers, and specialty retail category buyers. Bottom-up demand modeling across product type, end user, design style, and material dimensions triangulated against top-down value chain analysis.
Historical trendline analysis tracked shipment volumes and pricing trajectories across the projection horizon, with CAGR derivation reflecting segment-specific growth coefficients for vacuum-insulated stainless steel, ceramic serveware, and borosilicate glass categories. Modeled dimensions encompassed thermal performance tier, food-service versus household end-use, regulatory compliance grade, and regional manufacturing origin positioning. Forecast inputs incorporated nickel price volatility assumptions and café chain procurement consolidation velocity.
Caveats apply where SAMR testing queue extensions, nickel ore supply disruptions, or Japanese precision metalworking labor scarcity could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Silicone Soap Mold Market
Household Items
Folded Tissues Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Ceramic Travel Mug Market
Household Items
Mirror Holder Market
Household Items
Candle Air Fresheners Market
Household Items
Oman Gas Hobs Market
Household Items
Insulated Water Bottles Market
Household Items
Range Hood Cleaning Service Market
Household Items
Hydralight Lanterns Market
Household Items
Dishwashing Products Market
Household Items
UV Sanitizer Travel Wand Market
Household Items
Smart Bathroom Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Electric Hedge Trimmer Market
Household Items
Insulated Tumblers Market