
 US Garden Planter Market | 2026-2036
US Garden Planter Market Size, Share, and Industry Trends Forecast 2026-2036
US Garden Planter Market Insights
ASTM D6400 compostability certification is collapsing the competitive field for plastic planter entrants, forcing reformulation investments that strain mid-tier suppliers. The HC Companies leverages its thermoforming scale across Ohio and Georgia to sustain national retail shelf presence. Bloem anchors its position through proprietary colorant systems and Made-in-USA labeling that commands premium placement at home improvement chains. Crescent Garden competes on design-forward resin formulations targeting landscape professionals with fade-resistant warranties.
A garden planter constitutes a manufactured vessel—typically injection-molded polypropylene, rotomolded polyethylene, or pressure-treated cedar—engineered with drainage perforations and UV stabilizers to contain soil and support cultivated plants in non-ground environments. The primary commercial purpose centers on enabling cultivation in spatially constrained or climatically controlled settings, from urban balconies to commercial hospitality terraces. Plastic dominates unit volume due to cost parity and color versatility, though raised beds in cedar and redwood capture disproportionate margin pools among homeowners pursuing organic certification. Vertical planters represent the fastest-expanding product type as balcony agriculture and green wall installations gain traction in dense metropolitan housing stock.
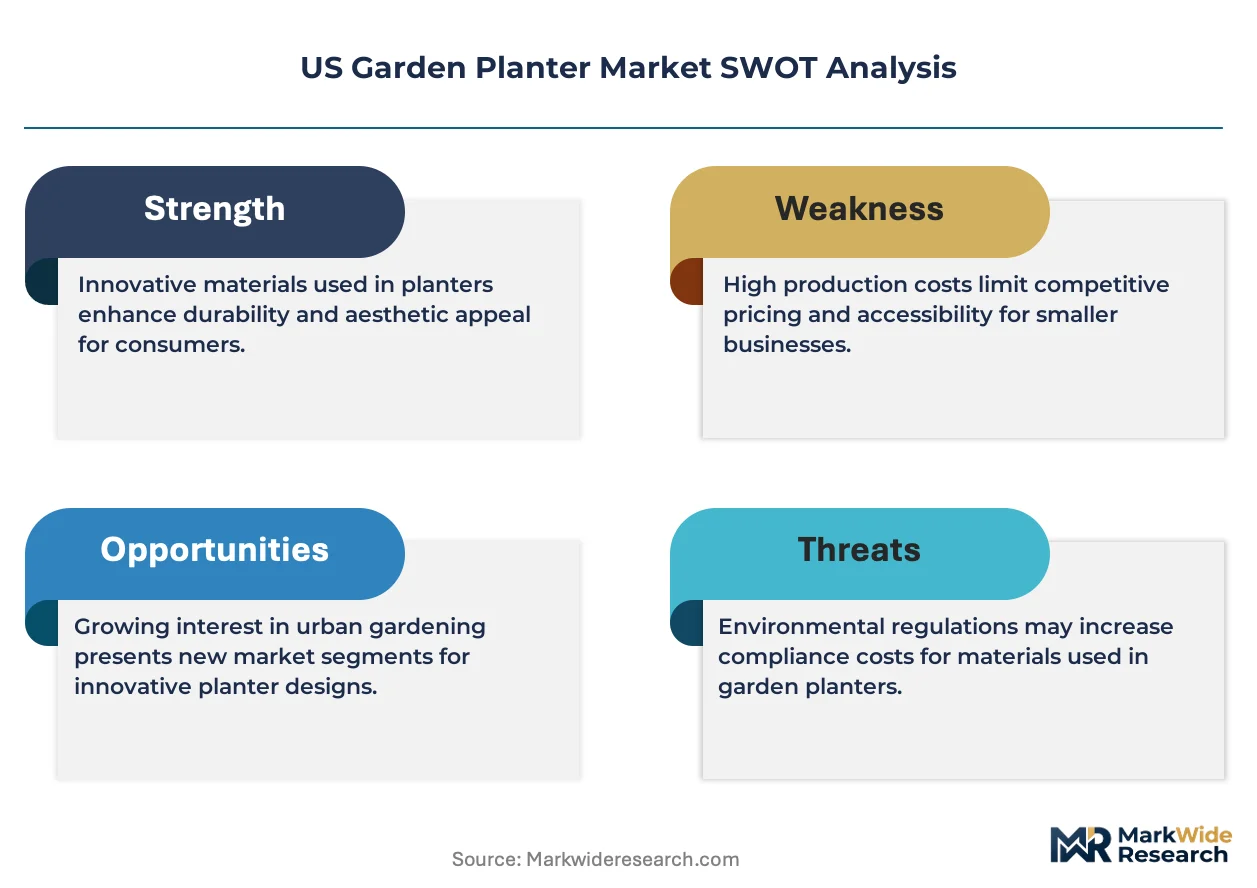
EPA regulations on pressure-treated wood leachate shape material substitution patterns, accelerating polyethylene and recycled resin adoption in ground-contact applications. The USDA BioPreferred program confers federal procurement preference on planters meeting minimum biobased content thresholds, redirecting R&D budgets toward soy-based polyols and post-consumer recycled feedstocks. California's Department of Toxic Substances Control maintains heightened scrutiny on phthalate plasticizers, creating compliance asymmetries between domestic molders and import-reliant distributors. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that could impose end-of-life recovery obligations on resin-based planter lines.
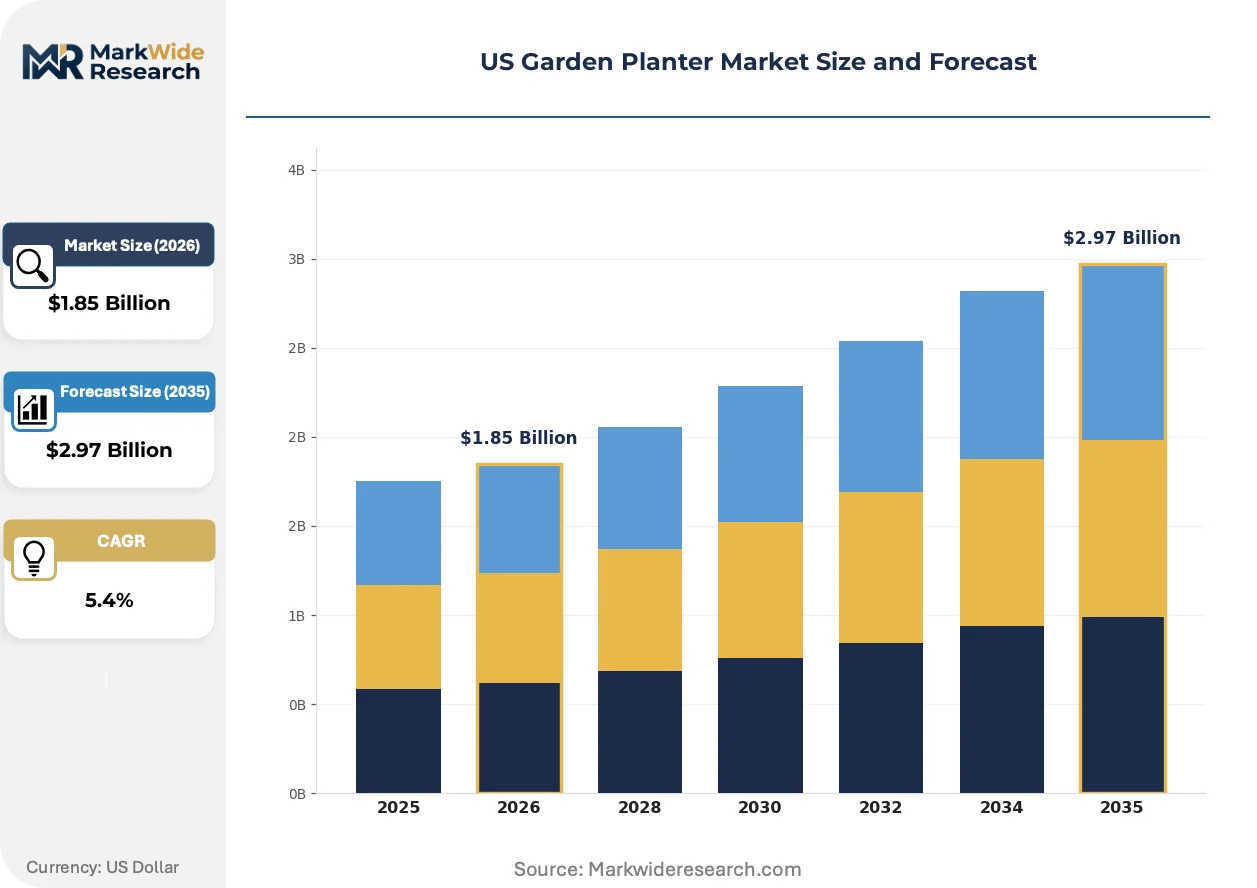
Market Dynamics
California's Model Water Efficient Landscape Ordinance is accelerating demand for drought-tolerant container systems while EPA leachate rules on pressure-treated wood redirect material substitution toward resin-based alternatives. These overlapping regulatory pressures are compressing supplier margins and reshaping competitive positioning across material categories.
Growth Catalysts
- Residential outdoor living investment:Homeowners are prioritizing balcony and terrace cultivation spaces, driving replacement cycles for container systems in metropolitan housing stock.
- USDA BioPreferred procurement preference:Federal purchasing mandates for biobased content redirect R&D budgets toward soy-based polyols and post-consumer recycled feedstocks.
- Sun Belt growing season extension:Year-round cultivation potential in southern states sustains higher planter turnover rates compared to seasonal northern markets.
Market Restraints
- ASTM D6400 compliance costs:Compostability certification requirements strain mid-tier suppliers with reformulation investments that erode margin buffers.
- Phthalate plasticizer scrutiny:California's Department of Toxic Substances Control maintains asymmetric compliance burdens between domestic molders and import-reliant distributors.
- Resin price volatility:Polypropylene and polyethylene feedstock exposure creates margin compression for injection-molded and rotomolded product lines.
Strategic Opportunities
- Vertical planter installations:Green wall and balcony agriculture systems represent underpenetrated white space in dense metropolitan housing markets.
- Extended producer responsibility frameworks:Emerging state-level end-of-life recovery obligations create first-mover advantages for closed-loop resin recovery infrastructure.
- Organic certification alignment:Cedar and redwood raised beds capture disproportionate margin pools among homeowners pursuing USDA organic cultivation standards.
Industry Challenges
- Colorant formulation expertise:Proprietary UV-stable pigment systems require specialized technical talent that concentrates among established compounders.
- Thermoforming scale requirements:National retail shelf presence demands multi-facility capital deployment across Ohio and Georgia manufacturing corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Garden Planter Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raised Beds, Window Boxes, Hanging Planters, Vertical Planters Material: Wood, Plastic, Metal, Fabric Size: Small, Medium, Large, Extra Large End User: Homeowners, Community Gardens, Retailers, Landscape Professionals |
| Companies Covered | The HC Companies, Bloem, Crescent Garden, Mayne Inc., Tusco Products, Planters Unlimited, Akro-Mils Lawn & Garden Products, Classic Home & Garden, Novelty Manufacturing Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Garden Planter Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape competitive advantage in container systems. Suppliers must navigate certification complexity while responding to spatial constraints in urban cultivation environments.
Recycled ocean-bound polyethylene is fragmenting the premium resin segment by enabling fade-resistant warranties that meet landscape professional specifications. Commercial installers are specifying these formulations for hospitality terrace projects. The technology is fragmenting procurement patterns as buyers separate certified-recycled stock from virgin resin alternatives.
California's Department of Toxic Substances Control maintains heightened scrutiny on phthalate plasticizers in consumer products. This regulatory friction accelerates substitution toward bio-based plasticizers and alternative polymer systems. Domestic molders with in-house compounding capabilities are capturing shelf space from import-reliant distributors.
Landscape architects are bundling container specification with irrigation design services, unbundling traditional planter-only transactions. This service integration compresses distributor margins while elevating design-forward resin suppliers with technical support capabilities. The pattern concentrates in Sun Belt metropolitan markets with active hospitality development pipelines.
US Garden Planter Market Segmentation
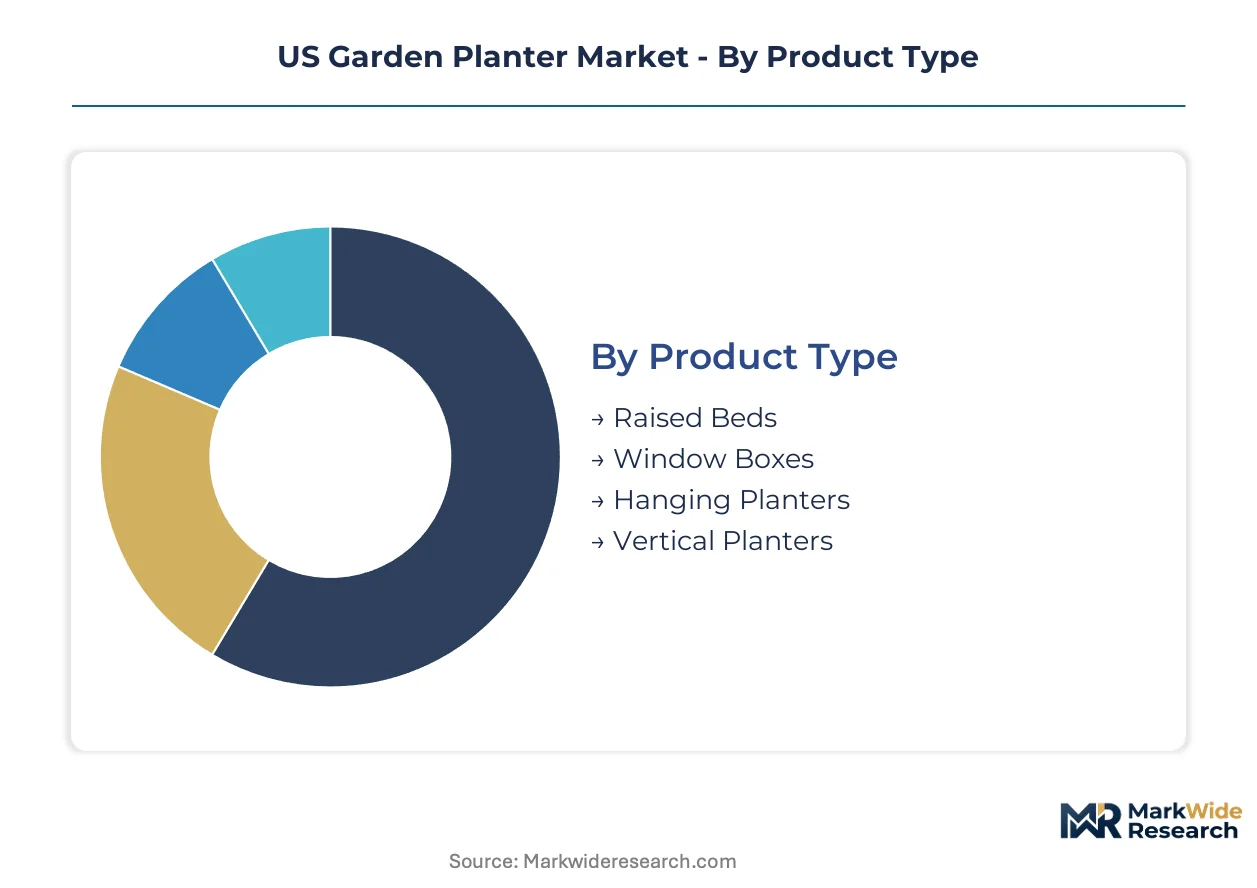
US garden planter procurement patterns diverge sharply across product configurations, material substrates, and end-user sophistication levels. Residential balcony agriculture and commercial hospitality installations are pulling demand toward fundamentally different specification sets, forcing suppliers to maintain parallel product architectures.
Product Type:
Domestic manufacturing capacity concentrates in raised bed and window box extrusion, while vertical planter systems rely heavily on imported subassemblies from Mexican and Chinese molding facilities.
- Raised Beds:Pressure-treated cedar and redwood constructions dominate ground-contact applications, capturing premium placement at home improvement chains serving organic certification-seeking homeowners. Sun Belt metropolitan markets sustain year-round turnover as extended growing seasons accelerate replacement cycles.
- Vertical Planters:Modular resin systems with integrated irrigation channels are displacing traditional container stacks in dense urban housing stock. Balcony agriculture adoption in California and Texas metropolitan corridors is driving specification toward lightweight, fade-resistant formulations with warranty-backed color retention.
- Window Boxes:Rotomolded polyethylene dominates volume production, with color-matched brackets and self-watering reservoirs commanding placement in suburban renovation projects.
- Hanging Planters:Coir-lined wire forms and injection-molded resin baskets split the market between decorative annual displays and functional herb cultivation.
Raised beds hold the largest share; momentum sits with vertical planters.
Material:
Cost tier stratification separates commodity resin volumes from certified-sustainable premium positioning, with mid-tier wood-plastic composites struggling to defend placement.
- Plastic:Polypropylene and polyethylene formulations account for unit volume leadership, with ASTM D6400 compostability certification collapsing the competitive field for entry-grade suppliers. California's Department of Toxic Substances Control phthalate scrutiny is accelerating bio-based plasticizer substitution among domestic compounders.
- Wood:Cedar and redwood raised beds capture disproportionate margin pools among homeowners pursuing USDA organic cultivation standards. EPA leachate regulations on pressure-treated alternatives are redirecting specification toward naturally rot-resistant species.
- Metal:Powder-coated aluminum and corten steel target landscape professional specifications for hospitality terrace installations requiring structural longevity.
- Fabric:Geotextile grow bags serve temporary cultivation and commercial nursery staging applications with minimal capital deployment.
Plastic commands volume leadership; wood maintains margin concentration.
Size:
Application-driven dimension requirements split procurement between space-constrained balcony specifications and commercial-scale growing operations.
- Large:Residential raised bed installations and community garden allotments drive specification toward 4x8 foot and 4x12 foot modular systems with depth-optimized root zones.
- Small:Apartment balcony rail planters and kitchen herb systems concentrate demand in Northeast and Midwest metropolitan markets with limited outdoor square footage.
- Medium:Patio container collections and mixed annual displays represent the replacement-cycle core for mass-market retail channels.
- Extra Large:Commercial hospitality terraces and institutional green roof installations require custom-fabricated resin or metal systems with engineered drainage.
Large formats anchor residential investment; small formats are expanding most quickly in urban housing stock.
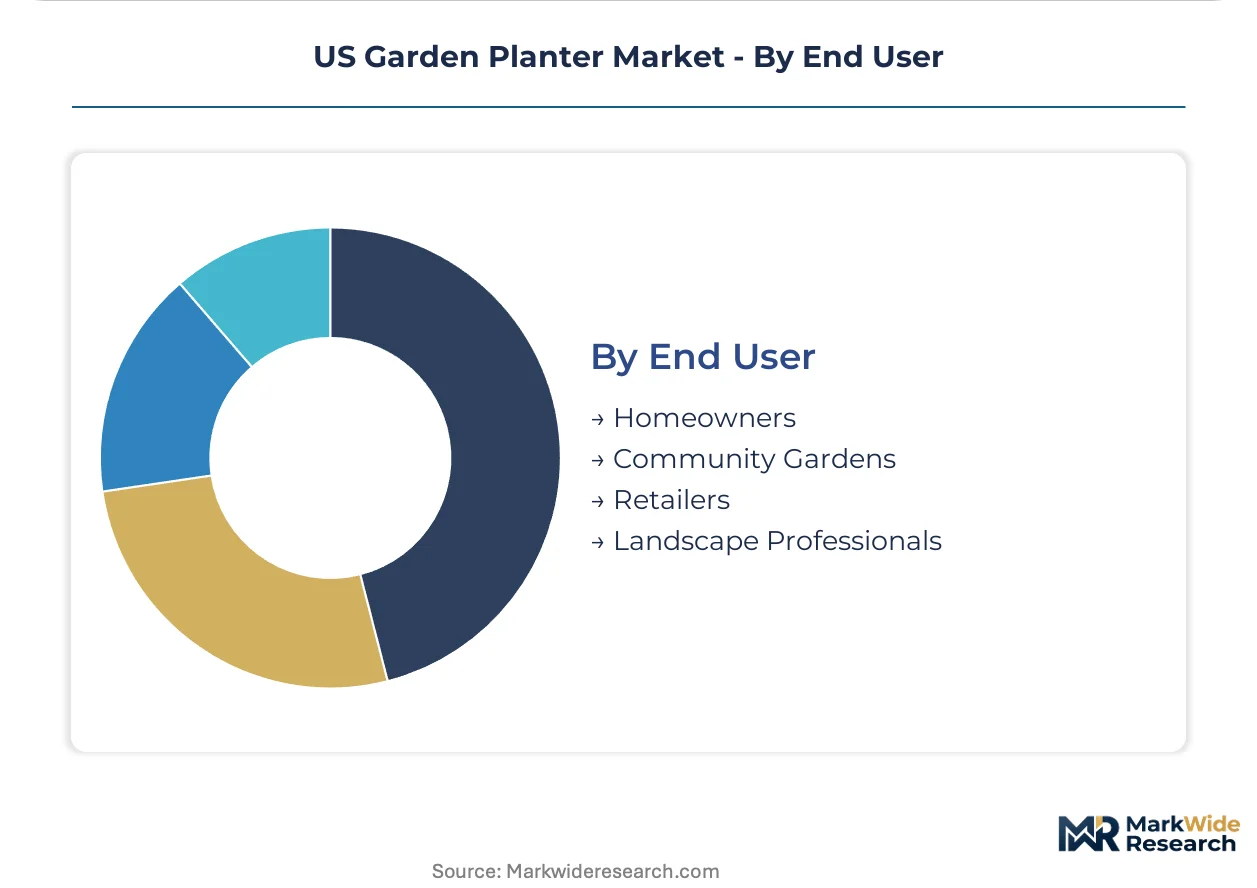
End User:
Customer sophistication tiers separate specification-driven professional procurement from price-sensitive residential replacement cycles.
- Homeowners:DIY renovation spending and outdoor living prioritization are sustaining replacement cycles across Sun Belt states, with color versatility and Made-in-USA labeling commanding shelf space premiums.
- Landscape Professionals:Commercial installers are bundling container specification with irrigation design services, elevating design-forward resin suppliers with technical support capabilities and fade-resistant warranty programs.
- Community Gardens:Municipal grant funding and food security initiatives are driving volume procurement of cedar raised beds and shared irrigation infrastructure.
- Retailers:Mass-market and specialty garden center channels maintain divergent assortment strategies, with big-box placement emphasizing price-point plastic and independent stores stocking premium wood and metal alternatives.
Homeowners represent the largest addressable base; landscape professionals deliver the steepest expansion trajectory in commercial hospitality development corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Model Water Efficient Landscape Ordinance drives drought-tolerant container demand across the Sun Belt, while EPA leachate regulations redirect material substitution toward resin-based alternatives in ground-contact applications. State-level procurement preferences and municipal grant programs are reshaping planter specification patterns.
California
Metropolitan balcony agriculture and hospitality terrace development sustain premium resin demand in Los Angeles and San Diego corridors. The Department of Toxic Substances Control enforces heightened phthalate plasticizer scrutiny, accelerating bio-based substitution among domestic compounders. Sacramento Valley distribution clusters concentrate injection-molded polypropylene capacity serving western retail channels.
Texas
Year-round growing seasons in Dallas-Fort Worth and Houston metropolitan areas sustain elevated replacement cycles for container systems. Municipal water conservation initiatives mirror California's ordinance structure, favoring self-watering and drought-tolerant specifications. Austin's design-forward residential construction pipeline elevates demand for fade-resistant warranty-backed resin formulations.
Florida
Coastal hospitality development and retirement community outdoor living investment drive commercial-scale procurement in Miami and Orlando markets. Hurricane-resistant construction codes indirectly favor heavier resin and metal planter specifications over lightweight alternatives. Tampa Bay logistics hubs facilitate Gulf Coast distribution of rotomolded polyethylene product lines.
New York Metro
Space-constrained balcony cultivation in Brooklyn and Manhattan residential stock concentrates demand for vertical and rail-mounted systems. Urban agriculture grant programs under the USDA Urban Agriculture Toolkit redirect community garden procurement toward certified-sustainable materials. Hudson Valley cedar sourcing supports premium raised bed placement in suburban renovation channels.
Pacific Northwest
Seattle and Portland metropolitan markets prioritize organic certification alignment and naturally rot-resistant wood species in raised bed applications. Extended wet seasons compress plastic planter replacement cycles due to UV degradation acceleration. Regional retail cooperatives emphasize Made-in-USA labeling and post-consumer recycled content in assortment decisions.
US Garden Planter Market Competitive Landscape
Player mix skews toward regional thermoforming specialists and design-forward resin compounders competing on certification compliance and colorant durability. Mid-tier suppliers face margin compression from ASTM D6400 reformulation investments and California phthalate regulatory asymmetries. Two strategic archetypes dominate: scale-driven national retail shelf presences and specialized landscape professional specification holders. Competitive moves concentrate on thermoforming capacity expansion across Ohio and Georgia corridors and proprietary UV-stable pigment system development.
Within the scale-driven tier, The HC Companies and Bloem occupy positions anchored by multi-facility manufacturing footprints and home improvement chain placement. Crescent Garden represents the design-forward specialization archetype targeting commercial installers with technical support capabilities. Mayne Inc. and Tusco Products exemplify regional fabrication specialists with concentrated distribution in specific metropolitan corridors. Akro-Mils Lawn & Garden Products and Classic Home & Garden sit within the mass-market volume tier serving price-sensitive residential replacement cycles.
| Leading Market Players |
|---|
| The HC Companies |
| Bloem |
| Crescent Garden |
| Mayne Inc. |
| Tusco Products |
| Planters Unlimited |
| Akro-Mils Lawn & Garden Products |
| Classic Home & Garden |
| Novelty Manufacturing Co. |
| Others |
Pricing and Supply Chain Analysis
Sixty-day resin inventory cycles among Ohio and Georgia thermoforming clusters concentrate pricing power with compounders possessing in-house colorant formulation capabilities. This lead-time compression amplifies margin pressure on mid-tier molders lacking backward integration into polypropylene feedstock sourcing.
Pricing Analysis
Certification level creates the primary spread across the US garden planter market. ASTM D6400 compostability compliance separates premium resin tiers from commodity polyethylene alternatives, with bio-based plasticizer substitution adding cost premiums in California-facing product lines. Pricing pressure stems from California's Department of Toxic Substances Control phthalate scrutiny, which forces reformulation investments that erode margin buffers for import-reliant distributors. Mass-market retail channels exhibit acute price sensitivity, while landscape professional specifications tolerate premiums for fade-resistant warranty-backed formulations.
Supply Chain Analysis
Port congestion at Long Beach and Savannah underwrites delivery uncertainty for injection-molded subassemblies originating from Mexican and Chinese molding facilities. Domestic manufacturing concentrates in Ohio and Georgia thermoforming corridors, with resin feedstock drawing from Gulf Coast petrochemical complexes. Supply chain risk centers on polypropylene price volatility tied to natural gas liquid cracking economics. Distribution runs through Sacramento Valley and Tampa Bay logistics hubs serving western and Gulf Coast retail channels respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among home improvement chains with national shelf space allocation authority, fragmenting supplier negotiating leverage across the US garden planter market.
For Market Incumbents: Fortify thermoforming scale advantages across Ohio and Georgia manufacturing corridors to defend against resin price volatility. Prioritize proprietary UV-stable pigment system development to maintain colorant formulation differentiation as import-reliant distributors face California phthalate compliance asymmetries. Channel control through exclusive home improvement chain placement remains the priority lever against emerging design-forward competitors. For New Entrants and Emerging Players: USDA BioPreferred certification fast-tracks federal procurement access and redirects R&D budgets toward soy-based polyol formulations. Vertical planter systems in California and Texas metropolitan corridors represent the most penetrable white space, with balcony agriculture adoption outpacing established supplier capacity. Specification bundling with irrigation design services offers a defensible go-to-market angle against transaction-only distributors. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium play because extended producer responsibility frameworks will impose end-of-life recovery obligations on resin-based product lines. Acquisition targets should display closed-loop resin recovery infrastructure or biobased content certification capabilities. Monitor state-level EPR legislation progression as the primary inflection indicator for valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM D6400 Certification Investment | Compostability compliance collapses competitive field and secures premium retail placement. |
| Backward Integration into Resin Compounding | In-house polypropylene formulation defends margin against feedstock price volatility. |
| Vertical Planter Product Line Expansion | Balcony agriculture adoption in Sun Belt metros outpaces existing supplier capacity. |
| Closed-Loop Recovery Infrastructure Buildout | State EPR frameworks create first-mover advantage in end-of-life resin recovery. |
| Landscape Professional Technical Support Capability | Specification bundling with irrigation design compresses distributor margins. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with thermoforming plant managers, home improvement chain category buyers, landscape professional installers, and resin compounder technical directors; and secondary validation through EPA leachate regulation filings, California Department of Toxic Substances Control product safety databases, USDA BioPreferred procurement records, and customs trade data on polyethylene imports. Bottom-up shipment estimates from manufacturing clusters triangulated against top-down retail channel audit data.
Across the projection horizon, the analytical framework modeled volume and value outputs across product type, material substrate, end-user sophistication tier, and regional regulatory cluster dimensions. CAGRs derived from replacement cycle frequency analysis in Sun Belt versus seasonal northern markets, with resin price elasticity and certification adoption curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Sun Belt outdoor living investment or accelerated California water conservation mandate enforcement would require recalibration. Forecasts reflect assumptions regarding ASTM D6400 certification penetration rates and state EPR framework implementation timelines. Practitioners should keep alternative scenarios live as federal biobased procurement preference thresholds and resin feedstock cracking economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Gardening Pots Market
Home & Garden
Landscaping Services Market
Home & Garden
United Kingdom Homeware Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Incense Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
North America Floral Gifting Market
Home & Garden
Aquarium Decor Market
Home & Garden
Preserved Flowers Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Flower Box Market