
 Garage Organization and Storage Market | 2026-2036
Garage Organization and Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Garage Organization and Storage Market Intelligence
A divergence between professionally installed, custom cabinet systems and mass-market, DIY-focused plastic shelving is restructuring the competitive landscape. NewAge Products specializes in high-end modular metal cabinetry, targeting the premium segment. In contrast, Rubbermaid and Sterilite dominate the commodity plastic container and shelving space through extensive retail distribution. Stanley Black & Decker leverages its established brand in tools to offer integrated tool organizer solutions for automotive enthusiasts and DIY users.
Garage organization and storage comprises systems designed to maximize usable space and securely store items in residential or commercial garages. These products often feature specific load-bearing capacities, with steel racks engineered to support hundreds of pounds per shelf. Wall-mounted systems represent the fastest-growing functionality segment due to their space-saving benefits in smaller garages. Within materials, metal cabinets command higher price points while plastic shelving leads in volume for the homeowner and DIY user segments.
Product safety and material composition are governed by multiple regulatory frameworks. In the United States, the EPA monitors volatile organic compounds (VOCs) in composite wood products, while the EU's REACH regulation restricts certain chemicals in plastics and metal coatings. This compliance adds complexity for manufacturers selling across different geographies. Manufacturers must decide whether to pursue sustainability-focused material certifications or compete on the basis of durability and cost alone.
Market Dynamics
The primary force shaping the garage organization market is a bifurcation between high-end, professionally installed systems and mass-market, DIY solutions. This split is driven by homeowner demand for both premium, customized functionality and accessible, low-cost storage options.
Growth Catalysts
- Suburban Housing Growth:The prevalence of larger homes with multi-car garages in suburban regions of the United States and Canada creates inherent demand for comprehensive storage systems to manage household and vehicle-related items.
- Smart Home Integration:The incorporation of smart features, such as app-controlled locking mechanisms and integrated LED lighting, into cabinetry and storage units is creating a new premium product tier for tech-savvy homeowners.
- Wall-Mounted Systems:Demand for wall-mounted racks, cabinets, and shelving is accelerating due to their ability to maximize floor space, a critical benefit for consumers with smaller garages or those seeking to park vehicles without obstruction.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the price of steel and high-grade aluminum directly impact the cost structure for manufacturers of durable metal cabinetry, creating margin pressure and pricing instability for premium products.
- Cross-Border Regulatory Compliance:Adherence to differing chemical regulations, such as the EPA's rules on VOCs in the US and the EU's REACH framework, adds significant complexity and cost for manufacturers operating global supply chains.
- Threat from Low-Cost Alternatives:The availability of low-cost, general-purpose shelving and repurposed indoor furniture acts as a substitute, placing a ceiling on pricing for the entry-level segment of the dedicated garage storage market.
Strategic Opportunities
- EV Charging Integration:Developing specialized storage solutions designed to house and organize electric vehicle charging equipment, cables, and battery maintenance accessories represents a significant greenfield opportunity.
- New Geographic Expansion:Expanding into markets with growing suburban middle-class populations, such as Australia and parts of Western Europe, offers new avenues for growth beyond the mature North American market.
- Home Automation Convergence:Deeper integration with whole-home automation platforms allows for the creation of a connected garage ecosystem, linking storage security and lighting with the broader smart home network.
Industry Challenges
- Logistical Complexity:The shipment of large, heavy, and often irregularly shaped products like metal cabinets and long shelving units presents significant logistical challenges, leading to high freight costs and risk of damage.
- Installer Skill Scarcity:The premium segment for custom-installed systems is constrained by the availability of skilled and trained installation professionals, creating bottlenecks that can slow project completion and limit growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garage Organization and Storage Market |
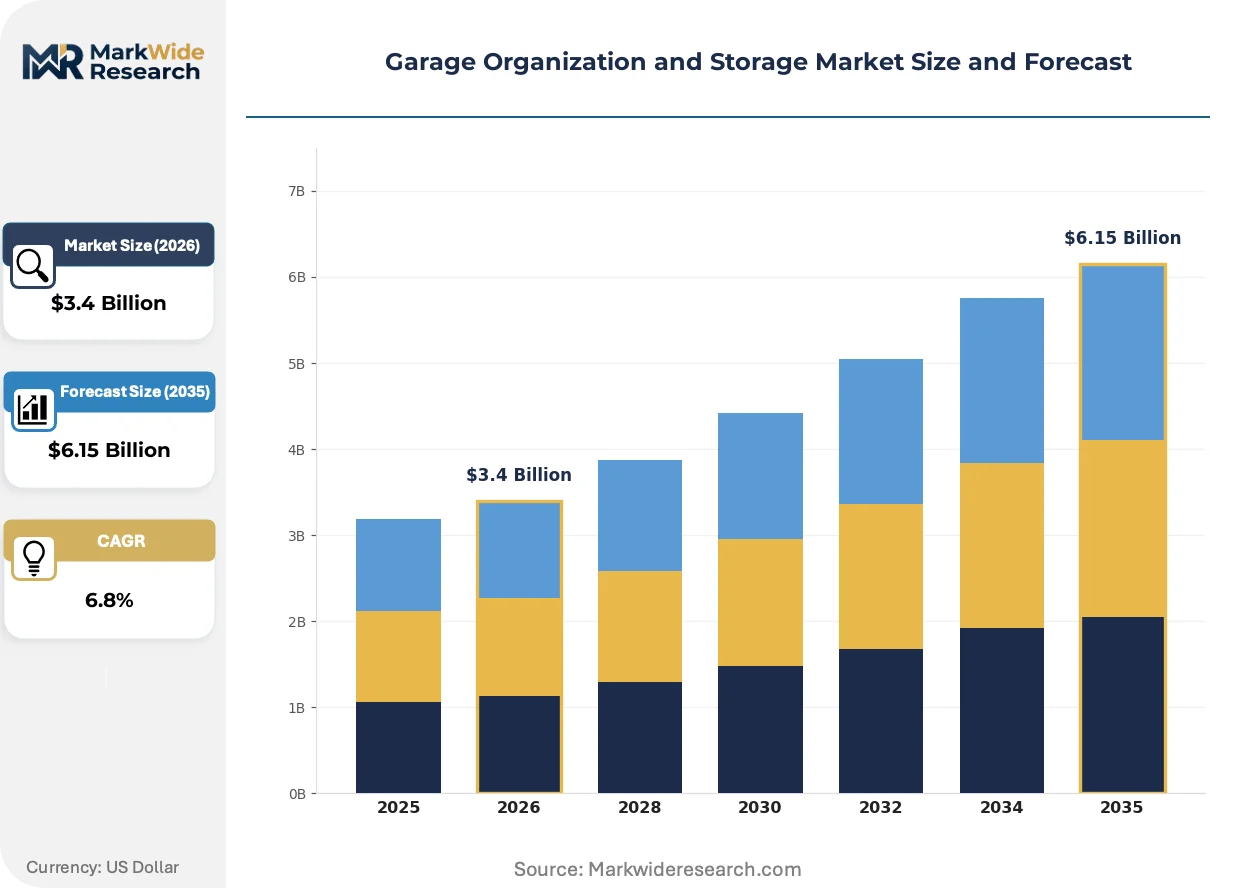
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Racks, Shelves, Cabinets, Tool Organizers Material: Plastic, Metal, Wood, Composite Functionality: Wall-Mounted, Free-Standing, Modular, Multi-Functional End User: Homeowners, Contractors, Automotive Enthusiasts, DIY Users |
| Companies Covered | Gladiator GarageWorks, GarageTek, Stanley Black & Decker, ClosetMaid Corporation, NewAge Products, The Home Depot, Rubbermaid, Sterilite, Lowe's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garage Organization and Storage Market Strategic Shifts & Innovations
The evolution of the garage from a utility space into a functional extension of the home is a central theme. This transformation is propelled by innovations in material science that enhance durability and aesthetics, alongside digital integrations that add convenience and security.
Advanced powder-coating and composite material technologies provide superior resistance to chemicals, moisture, and impacts common in a garage environment. Homeowners in the premium and mid-tier segments are rapidly adopting these finishes for their clean aesthetic and long-term durability. This advanced material science is absorbing the need for separate rust-proofing, painting, and finishing steps into a single, factory-applied surface that simplifies manufacturing and reduces lifetime maintenance.
Europe’s REACH regulation places strict controls on chemicals used in manufacturing, including those in plastics and metal coatings. This directly forces global producers to reformulate products to ensure market access, often leading to the adoption of more expensive but environmentally safer compounds. Metal cabinet and plastic container manufacturers are most affected, frequently standardizing on REACH-compliant materials for all products to streamline their global supply chains.
A notable behavioral shift sees consumers purchasing complete, pre-configured garage systems rather than individual, disparate components. This trend disrupts the traditional retail model of selling standalone shelving units or bins, favoring online direct-to-consumer channels that offer sophisticated visualization and configuration tools. The pattern is most pronounced in North American suburban markets where homeowners plan and purchase entire garage makeovers online.
Garage Organization and Storage Market Segmentation
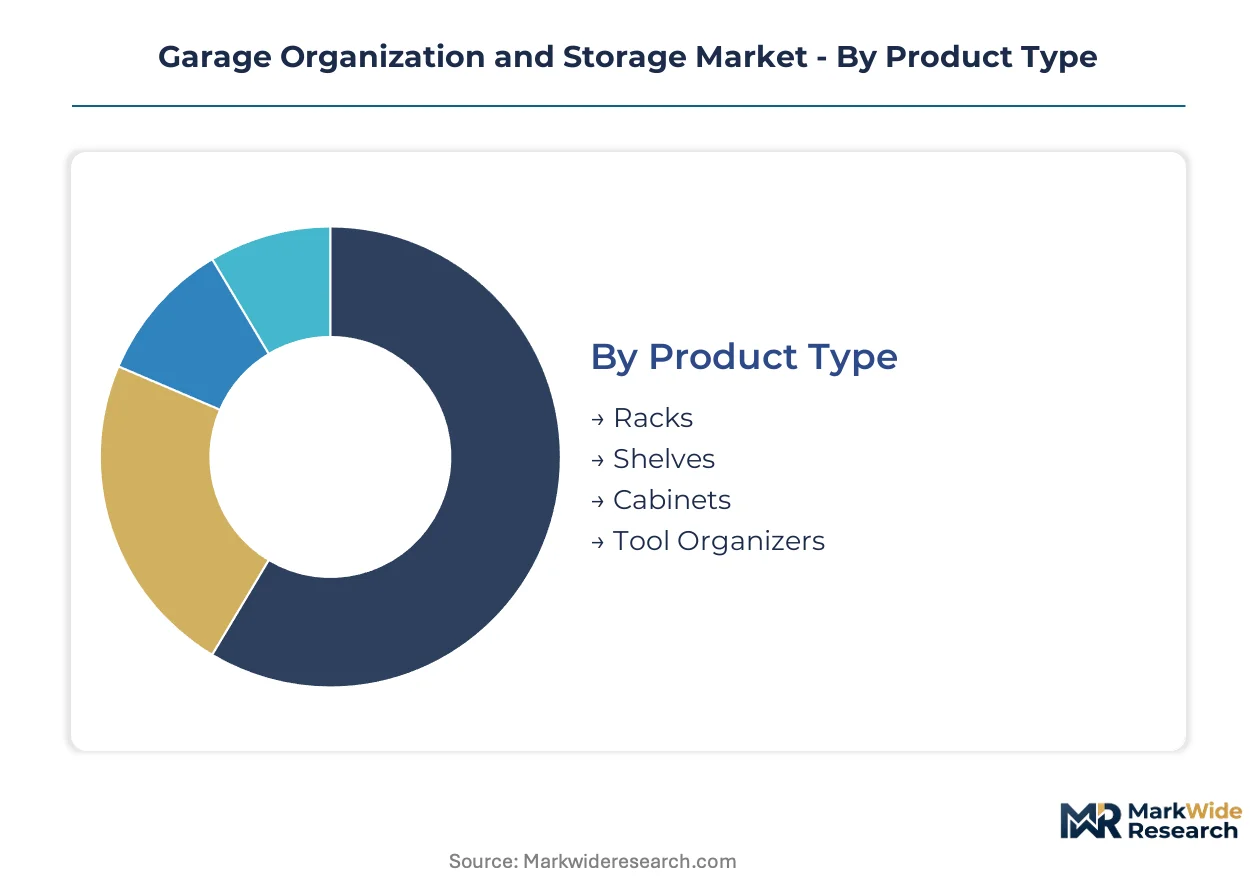
The garage organization and storage market bifurcates across distinct product types, materials, functionalities, and end-user demographics. Understanding these segments clarifies the varied consumer needs and manufacturer strategies shaping market evolution. This segmentation reveals how diverse product offerings cater to both premium, custom installations and accessible, mass-market solutions.
Product Type:
Segments within product type vary significantly in their upfront capital requirements for manufacturing and installation. High-end cabinetry involves complex fabrication and professional setup, demanding greater investment from both producers and consumers.
- Cabinets:These enclosed units typically feature steel or high-density polyethylene construction, providing secure, dust-free storage for tools and household items. Demand concentrates in suburban North American homes seeking integrated, clean aesthetics for their garage spaces.
- Racks:Heavy-duty steel frameworks constitute these systems, engineered for significant load-bearing capacity, often exceeding hundreds of pounds per shelf. Commercial garages and large residential workshops in Germany and Canada drive demand for robust, high-capacity racking.
- Shelves:Open shelving units, constructed from plastic, metal, or wood, offer accessible storage for frequently used items. Homeowners in the United States often purchase these for general-purpose garage organization.
- Tool Organizers:These specialized solutions, including pegboards and drawer inserts, provide dedicated storage for hand tools and power tools. DIY users and automotive enthusiasts in Australia prioritize these systems for efficient workspace management.
Cabinets absorb the bulk of installed capacity; Tool Organizers are expanding most quickly.
Material:
Material selection dictates the cost tier for garage storage solutions, directly influencing consumer accessibility and product durability. Manufacturers balance material cost with performance characteristics like load capacity and chemical resistance.
- Metal:Steel and aluminum alloys form the basis for premium cabinets and heavy-duty shelving, offering superior strength and longevity. Demand for metal solutions is strong in markets like the United States and the United Kingdom, where durability is a key purchasing factor.
- Plastic:Polypropylene and high-density polyethylene are common in lightweight shelving, bins, and containers, providing cost-effective and moisture-resistant storage. Homeowners across Europe and Canada frequently choose plastic options for budget-friendly organization.
- Wood:Plywood and engineered wood products are used for custom shelving and workbench tops, offering a traditional aesthetic and moderate strength. Consumers in rural areas of the US and Canada favor wood for its natural appearance and customizability.
- Composite:Blends of wood fibers and plastic resins create durable panels for cabinet backs and drawer bottoms, providing enhanced moisture resistance. Builders in new housing developments often specify composite components for their balance of cost and performance.
Metal materials lead in durability and premium positioning; plastic materials achieve the highest volume sales.
Functionality:
Functionality segments define how garage space is utilized, with distinct applications driving demand for specific system types. Innovations in this category focus on maximizing usable area and improving accessibility within constrained environments.
- Wall-Mounted:These systems, including slatwall, track systems, and hanging cabinets, free up floor space by utilizing vertical surfaces. Consumers in urban areas of the United States and Japan with smaller garages highly value wall-mounted solutions.
- Free-Standing:Self-supporting racks, cabinets, and shelving units offer flexible placement and are easily reconfigured as storage needs change. Large suburban homes in Canada and Australia often incorporate free-standing units for their versatility.
- Modular:Components designed for interchangeable configurations allow users to customize and expand their storage systems over time. Homeowners with evolving storage requirements in Germany and the UK increasingly adopt modular designs.
- Multi-Functional:Products combining several uses, such as workbenches with integrated storage or cabinets with fold-out tables, optimize utility in limited spaces. DIY enthusiasts and small business owners seek multi-functional items for efficiency.
Wall-mounted systems are gaining share fastest due to space-saving benefits; free-standing units offer flexible placement.
End User:
End-user segments highlight diverse purchasing behaviors and specific storage needs across the market. Each group seeks solutions tailored to their unique requirements, from professional-grade durability to DIY accessibility.
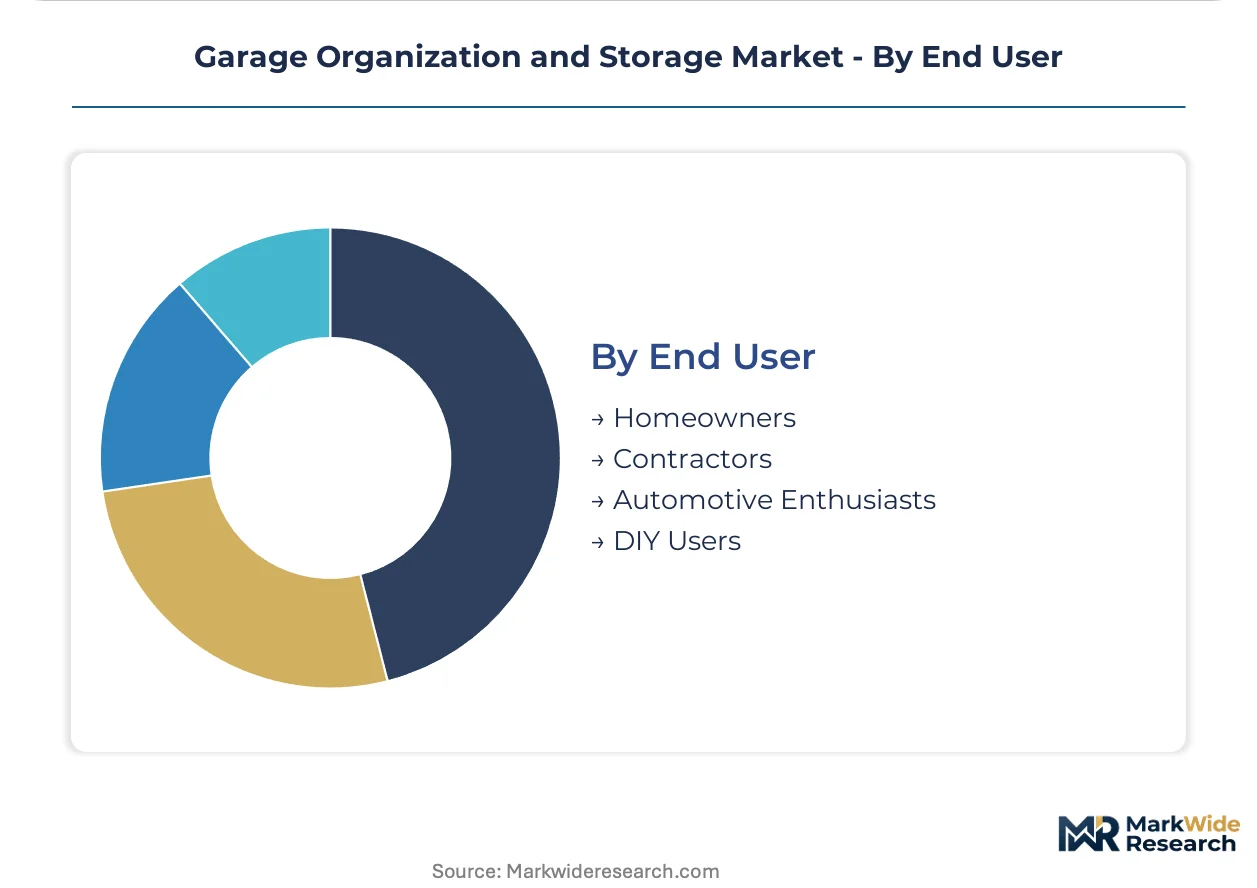
- Homeowners:This segment includes individuals seeking to organize personal belongings, vehicles, and seasonal items within their residential garages. Homeowners in the United States and Canada represent the largest consumer base for general garage storage products.
- Contractors:Professionals in trades such as construction and landscaping require robust, portable, and secure storage for tools and equipment. Small construction firms in the UK and Germany invest in durable, heavy-duty storage solutions.
- Automotive Enthusiasts:Individuals passionate about vehicle maintenance and restoration demand specialized storage for automotive parts, tools, and detailing supplies. Enthusiasts in Australia and the US prioritize systems that protect valuable equipment and maintain an organized workspace.
- DIY Users:Consumers who undertake home improvement projects themselves seek affordable, easy-to-assemble storage solutions for their tools and materials. This segment, prevalent across North America, drives demand for mass-market plastic and basic metal shelving.
Homeowners represent the largest customer base; automotive enthusiasts seek specialized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suburban areas around major US cities like Dallas-Fort Worth, Phoenix, and Atlanta lead regional demand for garage organization systems. This market responds to specific local needs, including diverse regulatory environments and homeowner preferences for storage solutions.
United States
Homeowner demand for integrated, clean aesthetics and wall-mounted solutions for smaller garages drives significant market activity. The EPA monitors volatile organic compounds (VOCs) in composite wood products, influencing material selection for manufacturers. Suburban communities across California and Texas exhibit strong adoption of comprehensive garage systems.
Canada
Larger homes with multi-car garages and the need for robust, high-capacity racking in commercial workshops propel product sales. Health Canada sets consumer product safety standards, impacting material choices for plastic and wood components. Toronto and Vancouver's expanding suburban areas drive significant purchases of versatile free-standing units.
Germany
Commercial garages and large residential workshops, alongside a preference for modular designs, characterize German market demand. The EU's REACH regulation restricts chemicals in plastics and metal coatings, requiring product reformulation from global producers. Industrial regions like North Rhine-Westphalia show strong adoption of heavy-duty steel frameworks.
United Kingdom
Durability as a key purchasing factor for metal solutions and a growing interest in modular designs shape consumer choices. UKCA marking requirements apply to certain construction products, influencing product standards for market access. London's commuter belt and surrounding areas exhibit demand for space-saving wall-mounted systems.
Australia
Automotive enthusiasts seeking specialized tool organizers and demand for versatile free-standing units in large suburban homes drive market growth. Australian Consumer Law ensures product safety and quality standards for all storage solutions sold within the country. Melbourne and Sydney's sprawling residential areas are key markets for complete garage makeovers.
Garage Organization and Storage Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the garage organization market. This landscape bifurcates between premium, custom-installed systems and mass-market, DIY-focused solutions. Strategic archetypes include high-end modular cabinetry specialists, commodity plastic storage providers, and integrated tool organizer manufacturers. Competitive moves often involve product differentiation through smart features and expanding retail distribution networks.
On the premium-tier vector, NewAge Products exemplifies specialized high-end modular metal cabinetry, targeting discerning homeowners. Rubbermaid occupies a position in the mass-market commodity plastic container and shelving space, leveraging extensive retail distribution. Stanley Black & Decker represents a different archetype, offering integrated tool organizer solutions for automotive enthusiasts and DIY users.
| Leading Market Players |
|---|
| Gladiator GarageWorks |
| GarageTek |
| Stanley Black & Decker |
| ClosetMaid Corporation |
| NewAge Products |
| The Home Depot |
| Rubbermaid |
| Sterilite |
| Lowe's |
| Others |
Cost & Logistics Intelligence
Skilled installation professionals in suburban North America represent a concentrated workforce. Labor-cost differentials for these specialists directly influence the premium pricing of custom garage systems, contrasting with mass-market DIY options.
Pricing Analysis
Value derived from optimized space utilization anchors pricing for high-end garage organization systems. Price differentiation stems from material quality, such as steel versus plastic, and the level of professional installation and customization. Pricing softness affects the entry-level segment due to readily available low-cost alternatives. DIY users exhibit high price sensitivity, while homeowners seeking complete garage makeovers prioritize integrated solutions over cost.
Supply Chain Analysis
Availability of skilled labor in manufacturing hubs like China, Vietnam, and Mexico underpins the supply chain for garage storage products. Production relies heavily on steel, high-density polyethylene, and composite wood inputs. Raw material price volatility represents a significant structural risk, impacting cost structures for metal cabinetry. Distribution runs through extensive retail networks for mass-market products and online direct-to-consumer channels for premium systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The garage organization market is evolving into a consolidation play. Intense pricing pressure from low-cost alternatives is forcing smaller, undifferentiated manufacturers to exit or be acquired.
For Market Incumbents: Extend product differentiation by integrating advanced smart home technology into premium cabinet systems. Consolidate market share by acquiring smaller regional installers to control the service delivery channel. Commoditization of basic plastic shelving threatens margins, necessitating investment in material science R&D for superior durability. Securing exclusive retail partnerships for high-end modular systems protects against general market erosion.
For New Entrants and Emerging Players: Launch via online direct-to-consumer channels, leveraging sophisticated visualization and configuration tools. Target the greenfield opportunity in specialized EV charging storage solutions for tech-savvy homeowners. Australia and parts of Western Europe present penetrable suburban markets with growing middle-class populations. Focus on modular, multi-functional designs that offer clear space-saving benefits for smaller garages.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers targeting vertically integrated mid-cap specialists in premium modular metal systems. Long-term viability over the next 5-10 years remains strong for companies addressing specific functional needs like EV charging integration. Acquisition profiles should prioritize firms with strong R&D in advanced materials and established installation networks. A signal to watch is successful market adoption of whole-home automation platforms incorporating garage security and access.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-powered inventory management for storage units. | Homeowners gain real-time visibility into stored items, enhancing convenience and security. |
| Expand direct-to-consumer sales channels with 3D configurators. | North American suburban homeowners can design and purchase complete garage systems online, bypassing traditional retail. |
| Invest in REACH-compliant composite material R&D. | Global producers standardize on safer compounds, streamlining supply chains and ensuring EU market access. |
| Acquire regional professional garage installation service providers. | Premium segment manufacturers gain control over service quality and alleviate installer skill scarcity bottlenecks. |
| Integrate EV charging infrastructure into modular cabinet designs. | Automotive enthusiasts receive specialized storage for electric vehicle equipment, addressing a new functional demand. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary research involved interviews with homeowners, contractors, automotive enthusiasts, and leading manufacturers and retail buyers. This approach combined bottom-up market sizing with top-down validation from industry experts. EPA filings, Health Canada reports, and EU REACH documents provided critical regulatory context.
Data stream reconciliation integrated historical trends and expert projections to develop the forecast framework across the analysis window. Segmentation dimensions modeled included product type, material, functionality, end-user, and regional regulatory environments. Compound annual growth rates were derived from these inputs, alongside new housing starts and electric vehicle adoption rates. This provided a comprehensive view of market evolution.
Raw material price shocks, regulatory shifts, and economic downturns are the dominant revision risks for these forecasts. The projections reflect assumptions about technological adoption and consumer spending patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Global Wind Chime Market
Home & Garden
Wine Racks Market
Home & Garden
Global Hot Tub Market
Home & Garden
Bird House Market
Home & Garden
Europe Flower Pots Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Flower Box Market
Home & Garden
Aquarium LED Lighting Market
Home & Garden
US Garden Planter Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
Landscaping Services Market
Home & Garden
United States Lawn Care Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Residential Snow Blower Market