
 Flowerpots and Planters Market | 2026-2036
Flowerpots and Planters Market Size, Share, and Industry Trends Forecast 2026-2036
Flowerpots and Planters Market Insights
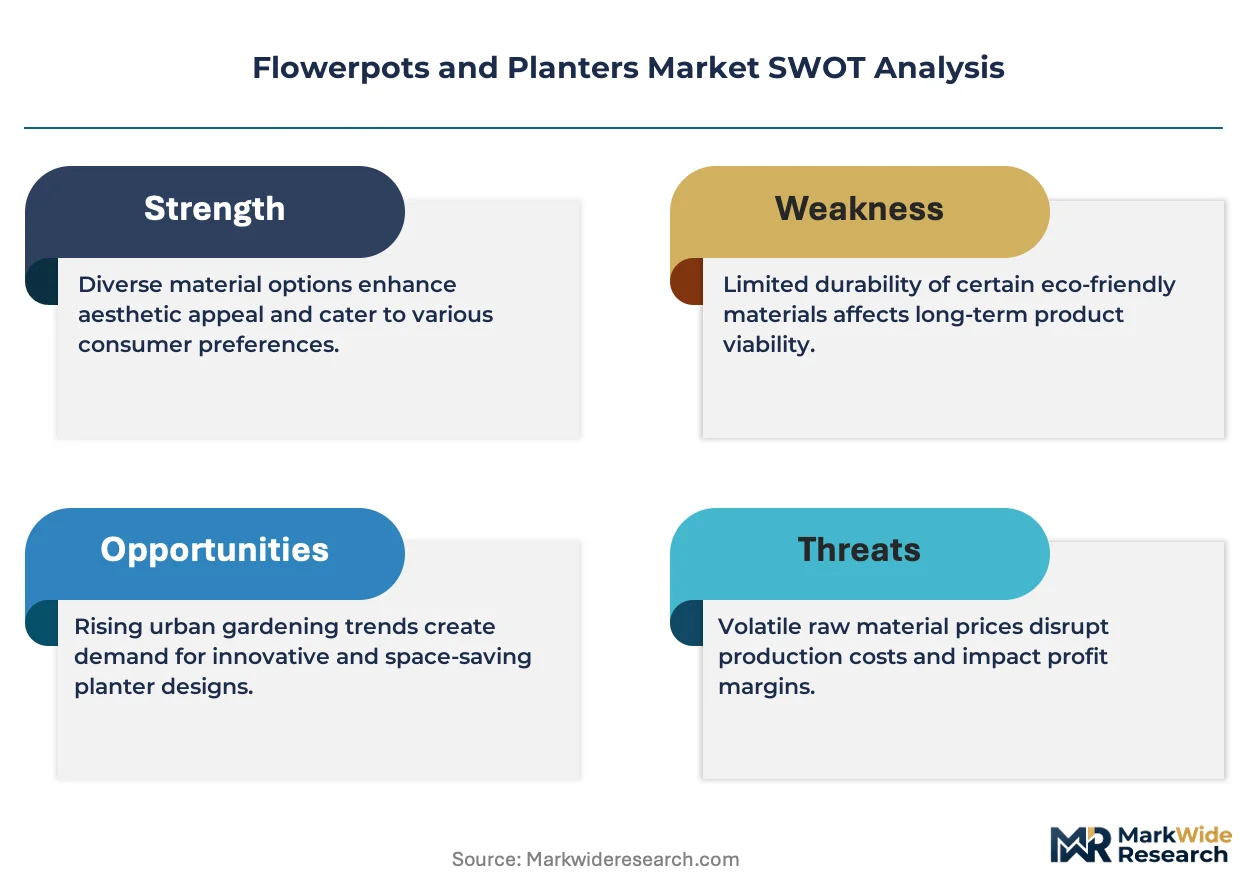
Capital-intensity divergence between automated rotational molding operations and hand-thrown ceramic workshops is redrawing competitive boundaries in the Flowerpots and Planters Market. The HC Companies leverages large-scale thermoforming infrastructure to dominate North American big-box retail channels. ELHO anchors its position through proprietary self-watering reservoir systems that reduce consumer maintenance burden. Scheurich sustains German market share via decades-old terracotta firing expertise that newer entrants cannot readily replicate.
Flowerpots and planters comprise rigid or semi-rigid containers manufactured from clay, thermoplastic resins, fired ceramics, or metal alloys, typically ranging from 0.5 to 200 liters in volumetric capacity, designed to contain soil substrate and support vascular plant root systems in non-ground environments. Plastic variants dominate unit volume due to injection molding scalability and UV-stabilized polypropylene durability exceeding seven years in outdoor exposure. Terracotta retains premium positioning in residential segments where porosity and aesthetic patina command price premiums. Wall-mounted and stackable forms represent the fastest-expanding configuration category as vertical gardening systems penetrate compact urban dwellings.
REACH restrictions on phthalate plasticizers and heavy metal pigments constrain formulation choices for European manufacturers, while China's GB standards govern cadmium and lead leaching limits in ceramic glazes. The US EPA oversees volatile organic compound emissions from solvent-based decorative coatings applied to metal planters. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and California that could mandate recycled content minimums and end-of-life take-back obligations.
Market Dynamics
REACH compliance on phthalate plasticizers and heavy metal pigments is forcing European manufacturers to reformulate resin compositions, while China's Jiangsu and Zhejiang manufacturing clusters concentrate global supply capacity. These dual pressures are reshaping material sourcing and competitive positioning across the Flowerpots and Planters Market.
Growth Catalysts
- Residential balcony gardening:Urban German households are converting limited outdoor space into container gardens, driving demand for compact, stackable planter configurations suited to apartment living.
- REACH additive restrictions:ECHA's evolving substance restrictions are accelerating bio-based polymer development, opening formulation pathways for corn-derived PLA and mycelium-composite alternatives.
- Rotational molding automation:Thermoforming scalability is compressing unit economics for large-format planters, enabling mass-market penetration of UV-stabilized polypropylene vessels exceeding 50-liter capacity.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, squeezing margin predictability for injection-molding operations.
- Jiangsu-Zhejiang supply concentration:Over 60 percent of global ceramic planter output originates from these adjacent Chinese provinces, creating geographic risk exposure.
- Terracotta porosity limitations:Clay's moisture permeability restricts application in hydroponic and self-watering systems where water retention is critical.
Strategic Opportunities
- India balcony gardening:Tier-1 Indian cities show nascent container-gardening adoption with minimal organized retail penetration, presenting first-mover positioning for modular vertical systems.
- EU extended producer responsibility:Pending EU-wide take-back mandates for plastic packaging will favor manufacturers with established recycling infrastructure and post-consumer resin capabilities.
- IoT-sensor convergence:Integration of soil-moisture sensors with self-watering reservoirs is creating premium smart-planter categories for tech-adopter households.
Industry Challenges
- Ceramic kiln operator scarcity:Traditional terracotta firing expertise is aging out in Germany and Italy, constraining authentic artisanal output.
- GB standard compliance timelines:China's cadmium and lead leaching limits for ceramic glazes require third-party laboratory certification cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flowerpots and Planters Market |
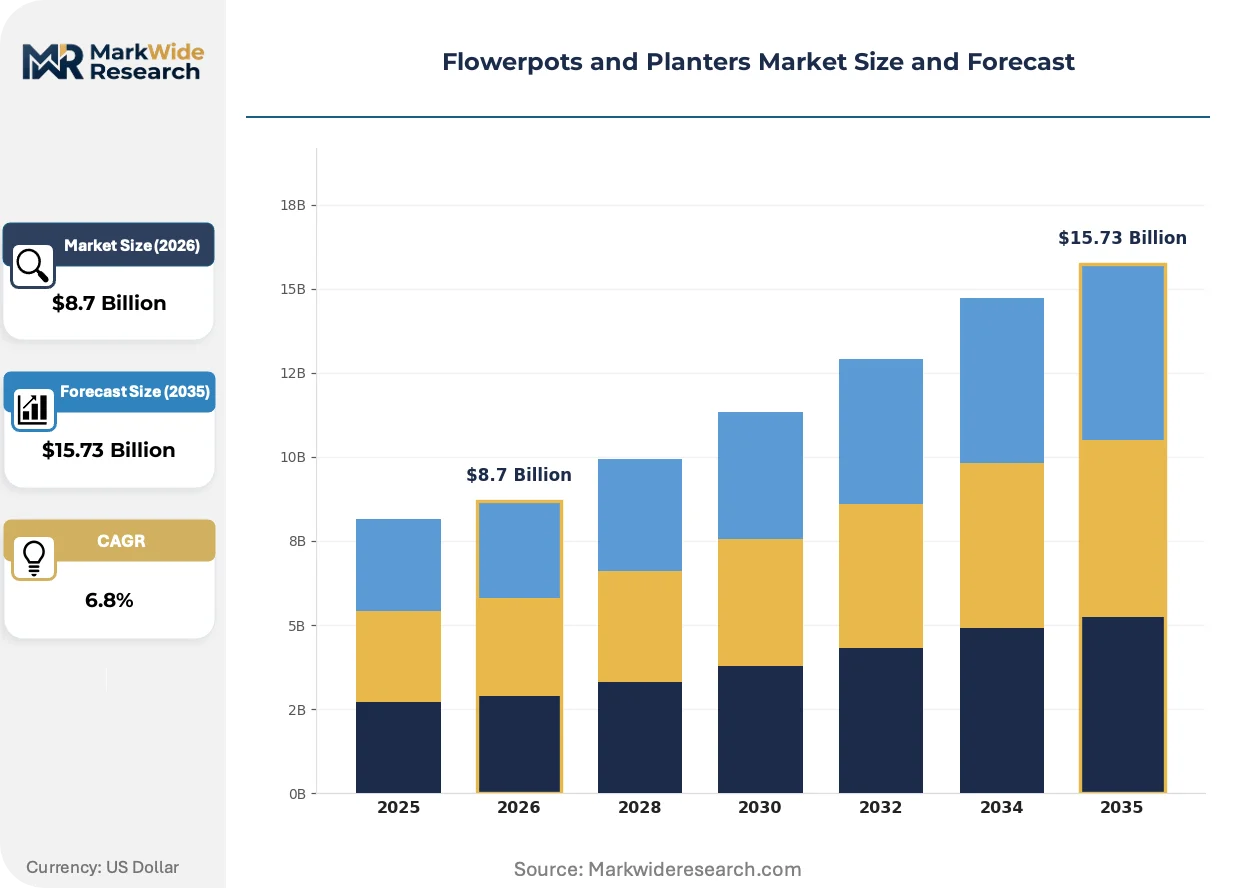
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terracotta, Plastic, Ceramic, Metal Form: Hanging, Wall-mounted, Standalone, Stackable Size: Small, Medium, Large, Extra Large End User: Residential, Commercial, Institutional, Agricultural |
| Companies Covered | The HC Companies, ELHO, Scheurich, Southern Patio/Ames, Lechuza, Keter Group, Planters Unlimited, Nursery Supplies, East Jordan Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flowerpots and Planters Market Trends and Innovations
Material science advances and regulatory chemistry constraints are decomposing established manufacturing paradigms. Three convergent developments are reconfiguring product architecture, compliance frameworks, and channel economics.
Biodegradable polymer formulations derived from agricultural waste streams are decomposing the seven-year durability standard that UV-stabilized polypropylene established. German garden-center buyers are piloting these materials in seasonal disposable applications. The structural consequence is compression of the replacement-cycle premium that conventional plastics commanded.
REACH authorization requirements for cobalt-based pigments are tightening colorant sourcing for European ceramic producers. Manufacturers must submit substitution plans or secure time-limited exemptions. Italian terracotta specialists face the steepest reformulation burden given their reliance on traditional mineral glazes.
Direct-to-consumer subscription models for seasonal planter rotations are bypassing traditional garden-center intermediaries. Millennial apartment-dwellers in Amsterdam and Copenhagen receive quarterly curated vessels matched to light conditions. This channel shift is most pronounced in Nordic markets where e-commerce penetration in home-and-garden already exceeds 35 percent.
Flowerpots and Planters Market Segmentation
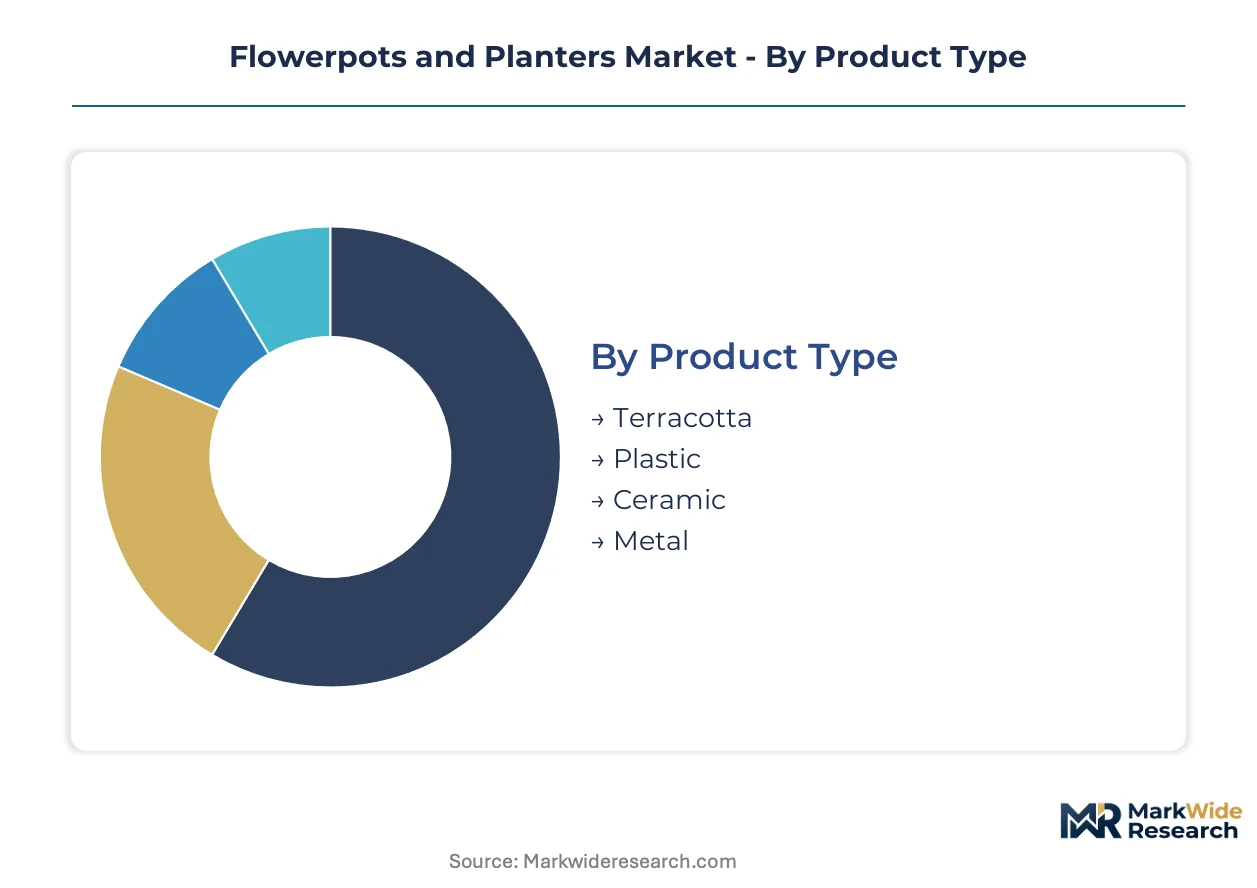
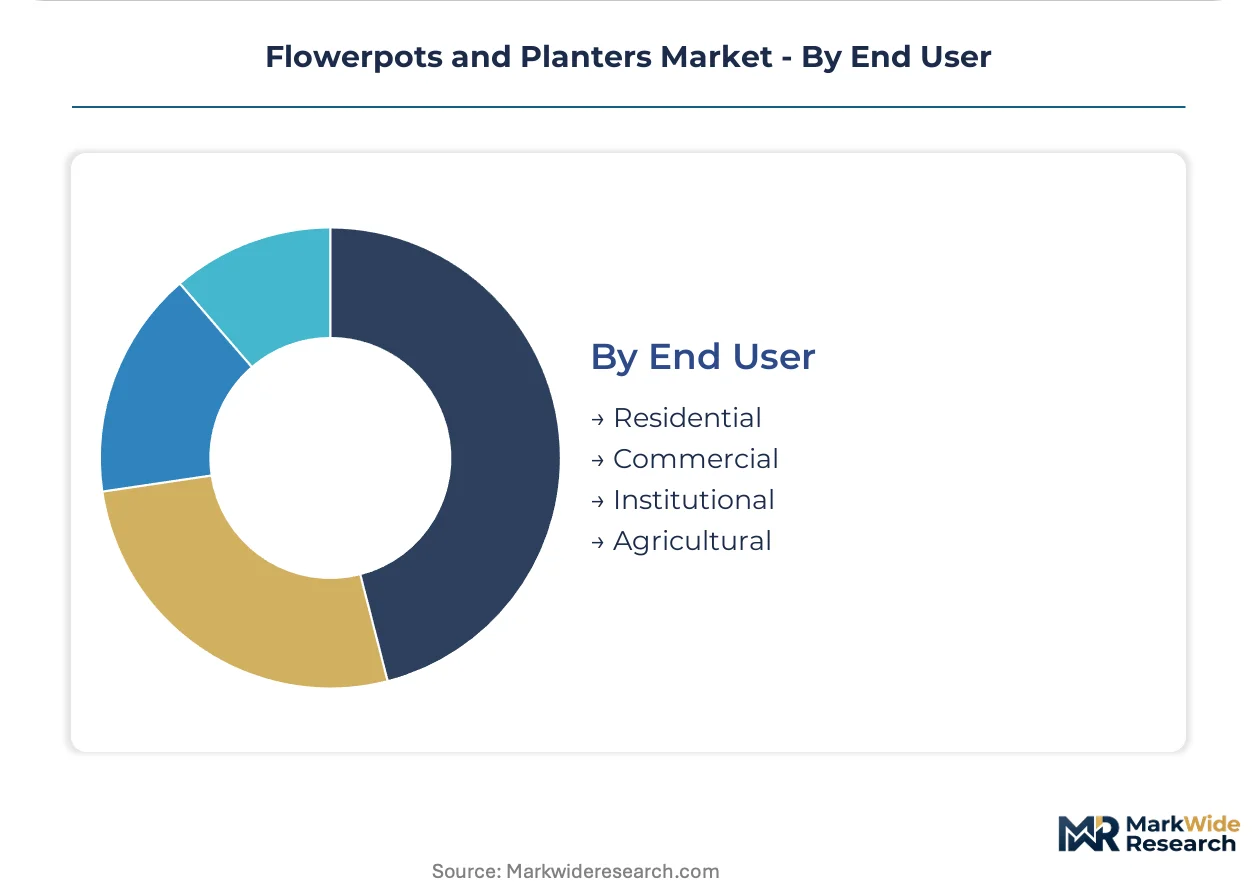
Segmentation in the Flowerpots and Planters Market reveals how material substitution pressures and form-factor innovation are fragmenting traditional demand pools. Manufacturers must align production assets with specific technical requirements rather than pursuing undifferentiated volume.
Product Type:
Substitution pressure runs strongest against petroleum-derived segments as bio-based polymers and mineral composites capture regulatory tailwinds and sustainability premiums.
- Terracotta:Fired clay vessels with natural porosity enabling root aeration and moisture wicking. German garden centers and Italian specialty retailers sustain demand for artisanal patina finishes despite higher unit costs and weight logistics.
- Plastic:Injection-molded polypropylene and polyethylene containers dominate mass-market unit economics through rotational molding scalability. UV stabilization formulations now face REACH-driven reformulation costs as ECHA restricts phthalate plasticizers.
- Ceramic:Glazed stoneware and porcelain variants offer non-porous water retention for indoor applications. Jiangsu and Zhejiang kilns supply global demand but must navigate China's GB standards for cadmium and lead leaching certification.
- Metal:Powder-coated aluminum and galvanized steel planters serve commercial landscaping for durability exceeding fifteen years. US EPA oversight of VOC emissions from solvent-based coatings adds compliance overhead.
Plastic retains volume leadership; ceramic holds the steepest expansion curve as urban balcony gardening drives premium positioning.
Form:
Form-factor segmentation tracks space-constraint adaptation across residential and commercial environments, with vertical solutions gaining disproportionate investment.
- Hanging:Suspended vessels with integrated drainage and mounting hardware. Balcony railings in Amsterdam and Copenhagen apartment complexes drive specification for lightweight polymer constructions.
- Wall-mounted:Modular pocket systems and bracket-fixed containers enabling vertical gardens on limited facade surfaces. Tier-1 Indian cities show nascent adoption with minimal organized retail penetration.
- Standalone:Traditional floor-positioned containers across all material classes. Ground-level commercial landscaping in German urban districts sustains demand for large-format vessels.
- Stackable:Interlocking modular systems optimizing soil volume in compact footprints. Self-watering reservoir integration from Dutch manufacturers like ELHO differentiates premium offerings.
Standalone forms retain volume leadership; wall-mounted configurations climb the fastest as vertical gardening penetrates dense urban housing.
Size:
Size segmentation correlates directly with end-use application scale and logistics economics, from apartment herb cultivation to municipal tree planting.
- Small:Sub-5-liter capacity for countertop herbs and succulents. German residential balcony gardening concentrates demand for compact vessels suited to apartment living.
- Medium:5-20 liter range serving patio container gardens and office greenery. Retail garden centers in Nordic markets move significant volume through direct-to-consumer subscription rotations.
- Large:20-50 liter vessels for specimen shrubs and small trees. Automated rotational molding operations compress unit economics for UV-stabilized polypropylene at this scale.
- Extra Large:50-200+ liter capacity for commercial landscaping and urban tree installations. Thermoforming scalability enables mass-market penetration previously constrained by ceramic weight and fragility.
Medium sizes retain volume leadership; extra large formats gain share fastest as commercial landscaping specification shifts toward polymer durability.
End User:
End-user segmentation exposes diverging procurement priorities between maintenance-minimization in commercial settings and aesthetic curation in residential channels.
- Residential:Individual households purchasing through garden centers, big-box retail, and e-commerce platforms. Millennial apartment-dwellers in Amsterdam and Copenhagen drive subscription-model adoption for seasonal rotations.
- Commercial:Property management, hospitality, and retail environments prioritizing durability and low maintenance. Self-watering reservoir systems reduce labor burden for facility managers.
- Institutional:Schools, hospitals, and government facilities with public procurement requirements. Extended producer responsibility frameworks in the EU shape vendor selection criteria.
- Agricultural:Nursery operations and controlled-environment farming using standardized containers for propagation. Hydroponic system integration favors non-porous materials over traditional terracotta.
Residential channels retain volume leadership; commercial applications expand most quickly as urban greening mandates intensify across European municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics tilt toward Asian manufacturing clusters supplying European and North American retail channels. China's Jiangsu and Zhejiang provinces dominate ceramic planter fabrication, while German and Dutch brands capture premium positioning through design differentiation and self-watering technology integration.
China
Jiangsu and Zhejiang manufacturing clusters produce over sixty percent of global ceramic planter volume. GB standards for cadmium and lead leaching in ceramic glazes require third-party laboratory certification cycles that delay product launches. Yixing in Jiangsu maintains specialized terracotta firing expertise for export markets.
Germany
Urban balcony gardening in Berlin, Hamburg, and Munich drives compact planter specification for apartment dwellers. REACH restrictions on phthalate plasticizers force resin reformulation across domestic injection-molding operations. Bavaria-based manufacturers leverage decades-old terracotta craftsmanship for premium garden-center positioning.
United States
Big-box retail channels concentrate procurement through large-scale thermoforming suppliers. EPA oversight of VOC emissions from solvent-based decorative coatings adds compliance overhead for metal planter imports. California's extended producer responsibility frameworks shape recycled content mandates for plastic vessel categories.
Netherlands
Amsterdam and Copenhagen apartment complexes drive specification for lightweight polymer hanging planters suited to balcony railings. Self-watering reservoir technology from Dutch manufacturers reduces consumer maintenance burden. Direct-to-consumer subscription models for seasonal rotations bypass traditional garden-center intermediaries.
India
Tier-1 cities including Mumbai, Bangalore, and Delhi show nascent container-gardening adoption with minimal organized retail penetration. BIS certification requirements for plastic household articles create entry barriers for unorganized manufacturers. Modular vertical systems present first-mover positioning opportunities for international brands.
Flowerpots and Planters Market Competitive Landscape
Concentration sits with diversified polymer processors and specialized ceramic fabricators rather than integrated conglomerates. Large-scale rotational molding operations compress unit economics for mass-market volume, while artisanal terracotta workshops defend premium positioning through aesthetic differentiation. Two strategic archetypes dominate: thermoforming scale players and design-led self-watering specialists. Competitive moves center on capacity expansion in automated molding infrastructure and portfolio diversification into bio-based polymer formulations.
Among European specialists, ELHO and Scheurich occupy distinct positioning vectors. ELHO anchors the self-watering technology tier through proprietary reservoir systems. Scheurich exemplifies heritage ceramic craftsmanship sustained across generations of terracotta firing expertise. The HC Companies represent North American scale-driven fabrication, leveraging thermoforming infrastructure for big-box retail channel penetration.
| Leading Market Players |
|---|
| The HC Companies |
| ELHO |
| Scheurich |
| Southern Patio/Ames |
| Lechuza |
| Keter Group |
| Planters Unlimited |
| Nursery Supplies |
| East Jordan Plastics |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Jiangsu and Zhejiang ceramic kiln operators lock in both terracotta supply access and price visibility for European garden-center buyers facing REACH-driven reformulation costs elsewhere in their portfolios.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Flowerpots and Planters Market. Price differentiation rests on material grade and certification tier, with GB-standard compliant ceramic glazes commanding premiums over uncertified alternatives. Pricing pressure stems from petrochemical input volatility squeezing injection-molding margins. Mass-market retail channels exhibit highest price sensitivity, while institutional procurement prioritizes lifecycle durability over unit cost.
Supply Chain Analysis
Yixing terracotta firing expertise in Jiangsu province underwrites artisanal planter quality benchmarks that newer manufacturing regions struggle to replicate. Raw material dependencies center on polypropylene resin, cobalt-based ceramic pigments, and aluminum alloy sheet. Supply chain risk concentrates in single-source vulnerability for traditional kiln craftsmanship as German and Italian artisan populations age. Distribution runs through big-box retail consolidation in North America and direct-to-consumer subscription platforms in Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated big-box retail procurement in North America and subscription-platform aggregators in Europe, fragmenting traditional garden-center intermediaries.
For Market Incumbents: Secure backward integration into bio-based polymer feedstocks before REACH restrictions harden material substitution economics. ELHO-style self-watering reservoir patents and Scheurich-grade terracotta firing expertise provide defensible moats against commoditized injection-molding entrants from Asian manufacturing clusters. For New Entrants and Emerging Players: Direct-to-consumer subscription gaps in Tier-1 Indian cities expose white-space where organized retail penetration remains minimal. Modular vertical systems for Mumbai and Bangalore balcony gardening represent the most penetrable segment, with BIS certification compliance as the critical go-to-market enabler. For Investors and Strategic Acquirers: Capital is best deployed toward design-led self-watering specialists with proprietary reservoir technology rather than undifferentiated thermoforming scale players. Long-term viability favors manufacturers with established post-consumer resin capabilities ahead of EU extended producer responsibility mandates. Watch GB standard compliance timelines as inflection indicators for Chinese ceramic export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | REACH restrictions on phthalate plasticizers accelerate corn-derived PLA and mycelium-composite development pathways. |
| Self-Watering Reservoir Patent Expansion | ELHO-style proprietary systems reduce consumer maintenance burden and command premium positioning in residential channels. |
| Direct-to-Consumer Subscription Launch | Amsterdam and Copenhagen millennial apartment-dwellers bypass traditional garden-center intermediaries for seasonal rotations. |
| GB Standard Compliance Investment | Third-party laboratory certification for cadmium and lead leaching unlocks Jiangsu-Zhejiang ceramic export access. |
| Post-Consumer Resin Infrastructure Buildout | EU extended producer responsibility frameworks favor manufacturers with established recycling and take-back capabilities. |
Research Methodology
Desk research of customs trade records, SEC 10-K filings, and ECHA substance restriction databases preceded structured interviews with injection-molding plant managers, garden-center category buyers, ceramic kiln operators, and REACH compliance officers. Primary fieldwork with Dutch self-watering technology developers and German terracotta artisans combined with secondary validation from Jiangsu export statistics and Nordic e-commerce penetration data. Bottom-up unit economics modeling triangulated against top-down market sizing across material and form-factor segments.
Variance decomposition across the projection horizon isolates volume drivers by product type, form configuration, size tier, and end-user channel. CAGRs derive from segmented growth rate application to baseline consumption estimates. Modeled inputs include urban balcony gardening adoption curves, REACH authorization timelines for cobalt pigments, and rotational molding automation penetration rates in large-format planter production.
Underlying assumptions cover sustained petrochemical price volatility and stable GB standard enforcement, with deviation risk concentrated in EU extended producer responsibility implementation speed and traditional terracotta craftsmanship attrition rates. Practitioners should keep alternative scenarios live as bio-based polymer durability benchmarks and Indian organized retail development trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Aquarium LED Lighting Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Candle Market
Home & Garden
Global Wind Chime Market
Home & Garden
Christmas Decorations Market
Home & Garden
United States Landscaping Market
Home & Garden
Aquarium Decor Market
Home & Garden
Gardening Pots Market
Home & Garden
Wine Racks Market
Home & Garden
Landscaping Products Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
Garage Organization and Storage Market