
 Garden Solar Lights Market | 2026-2036
Garden Solar Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Garden Solar Lights Market Analytics
A capital-intensity divergence between integrated solar cell producers and assembly-only brands is rotating competitive advantage toward firms with captive photovoltaic supply. Kemeco leverages in-house polycrystalline wafer production to control cost curves across its pathway and spotlight ranges. The Solar Centre sustains UK market presence through specialized coastal-grade corrosion finishes. Lights4fun competes on seasonal design velocity, releasing proprietary string-light form factors ahead of retail buying cycles.
Garden solar lights are self-contained outdoor luminaires integrating photovoltaic panels, rechargeable storage cells, and LED emitters within weather-resistant housings; crystalline silicon panels typically achieve 15-20% conversion efficiency while lithium-ion phosphate packs now displace nickel-metal hydride across premium tiers. Their primary purpose is to eliminate grid dependency for landscape, security, and decorative illumination in exterior residential and commercial spaces. Pathway lights occupy the largest volume tier due to standardized form factors and mass-retail distribution, while spotlights capture margin concentration through higher lumen output and adjustable beam architecture. LED technology dominates unit economics with declining emitter costs and 50,000-hour rated lifespans, yet amorphous silicon retains share in ultra-low-price entry products where conversion efficiency matters less than panel flexibility.
EPA Energy Star certification and FCC Part 15 emissions compliance shape product design requirements for US-bound garden solar lights, while EU RoHS and REACH restrictions constrain solder compositions and housing plastics across European exports. China's GB standards for solar consumer products and MEE carbon-intensity benchmarks are tightening manufacturing footprints for export-oriented producers. Stakeholders must monitor whether emerging efficiency thresholds in California Title 24 and analogous state codes fragment certification burdens or consolidate demand behind pre-certified product platforms.
Market Dynamics
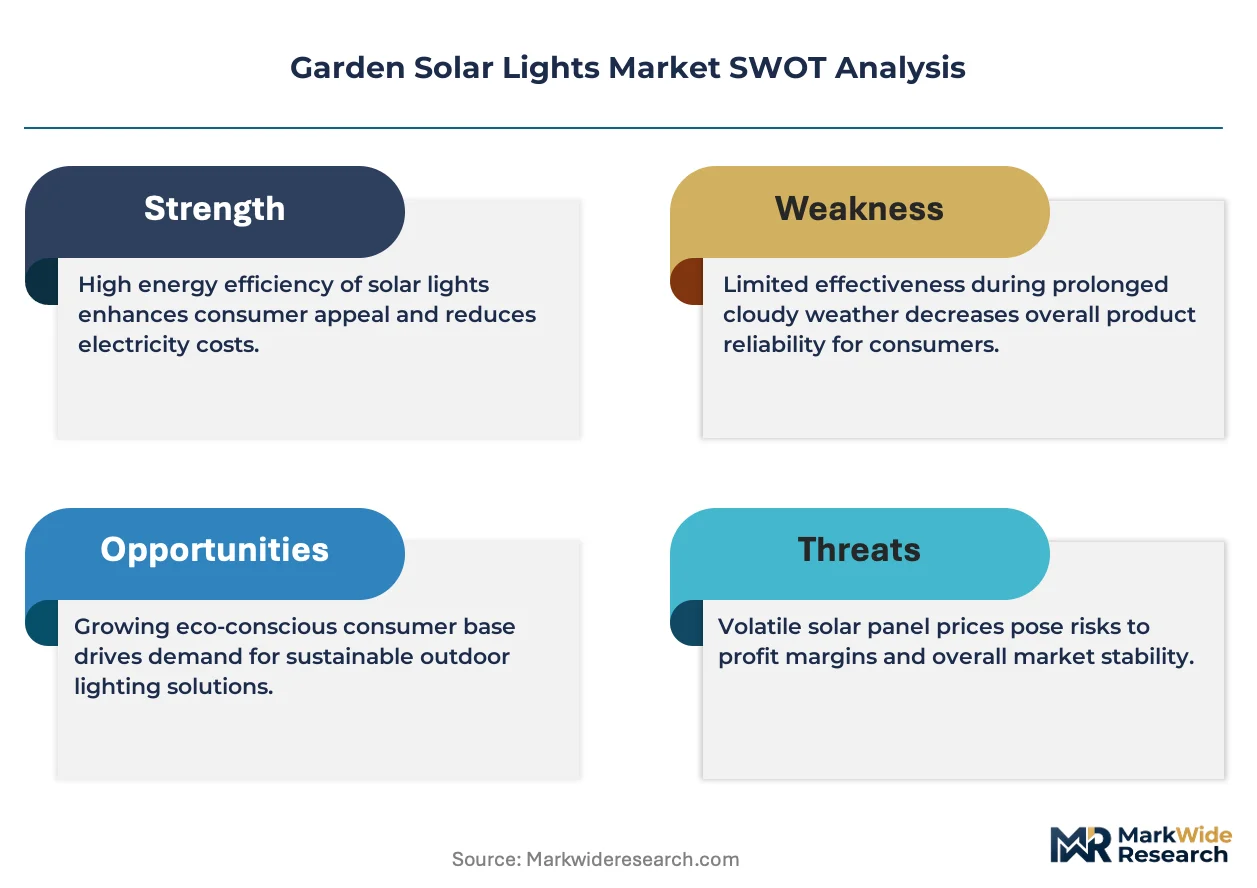
The Garden Solar Lights Market is undergoing a fundamental reconfiguration as lithium-ion phosphate battery chemistry displaces nickel-metal hydride across premium product tiers, compressing replacement cycles and reshaping supplier qualification requirements for residential buyers.
Growth Catalysts
- MEE Carbon-Intensity Benchmarks:China's Ministry of Ecology and Environment mandates are accelerating factory automation and higher-conversion photovoltaic cell adoption among export-oriented manufacturers serving North American and European buyers.
- Sun Belt Residential Development:Suburban homeowners across Arizona, Texas, and Florida are installing pathway and spotlight systems at elevated rates due to solar irradiance levels supporting year-round autonomous operation.
- Perovskite Tandem Research:Laboratory-scale perovskite-silicon tandem cells achieving 26%+ conversion efficiency are drawing venture funding toward next-generation consumer solar applications.
Market Restraints
- Lithium Price Volatility:Battery-grade lithium carbonate spot markets expose premium-tier manufacturers to input cost swings that compress margin stability on lithium-ion phosphate packs.
- Polysilicon Supply Concentration:Xinjiang-based polysilicon refineries supply over 40% of global photovoltaic-grade silicon, creating geographic concentration risk for crystalline panel sourcing.
- Amorphous Silicon Efficiency Ceiling:Thin-film amorphous panels plateau at 8-12% conversion efficiency, limiting their deployment to ultra-low-price entry products where performance trade-offs are acceptable.
Strategic Opportunities
- Coastal Corrosion-Resistant Finishes:Salt-air degradation in UK, Australian, and Japanese coastal markets creates demand for specialized anodized aluminum housings and marine-grade seals.
- Smart Home Integration:Matter protocol compatibility and voice-control modules enable solar lighting systems to converge with residential automation platforms.
- California Title 24 Outdoor Lighting Mandates:Stricter efficiency thresholds in the state's building code are consolidating demand behind pre-certified product platforms for new residential construction.
Industry Challenges
- IP Licensing Complexity:LED emitter and battery management system patent thickets create royalty stacking and freedom-to-operate clearance delays for new market entrants.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA Energy Star, FCC Part 15, and EU RoHS compliance testing extends product launch cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden Solar Lights Market |
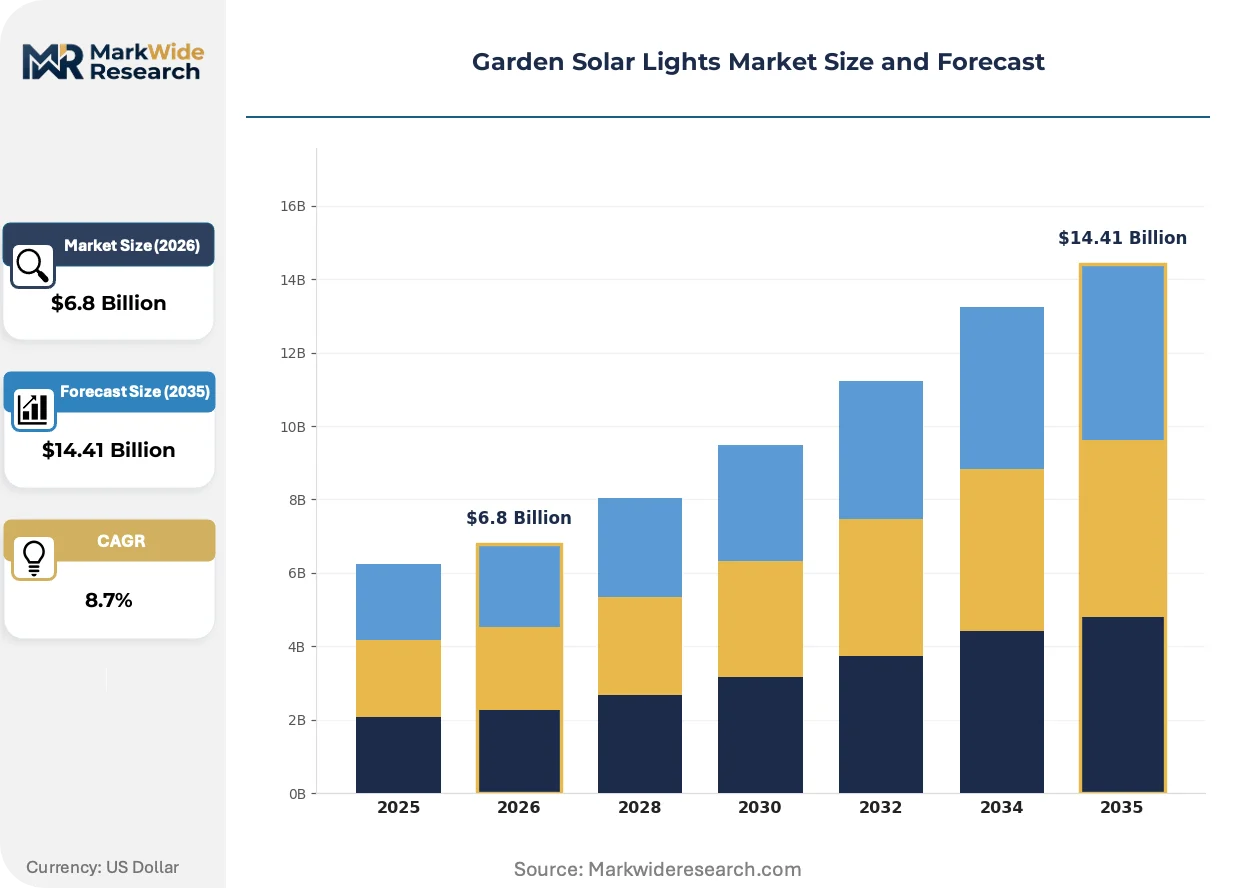
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pathway Lights, Flood Lights, String Lights, Spotlights Technology: LED, Lithium-ion, Polycrystalline, Amorphous Silicon End User: Residential, Commercial, Landscape Designers, Municipal Size: Small, Medium, Large, Extra Large |
| Companies Covered | 4lite, AloftSun, Better Homes & Gardens, Koda, ASMA, Kemeco, The Solar Centre, Cyhkee, Lights4fun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden Solar Lights Market Evolving Landscape
Product architecture and buyer expectations are diverging as performance-tier segmentation hardens and connectivity features migrate from novelty to baseline specification.
Perovskite-silicon tandem photovoltaic research is displacing conventional crystalline silicon as the reference efficiency benchmark for next-generation consumer solar panels. Residential buyers in premium suburban developments now expect 20%+ conversion efficiency as standard, forcing manufacturers to accelerate R&D partnerships or risk commoditization in the pathway light segment. This chemistry shift is compressing the performance gap between commercial and consumer-grade solar harvesting.
REACH substance restrictions and EU Green Deal circularity mandates are constraining solder compositions and housing plastics across European export channels. Manufacturers must reformulate ABS and polycarbonate housings to eliminate restricted phthalates and heavy metal stabilizers, adding material qualification costs that favor larger producers with dedicated compliance teams. The spotlight and security light categories face the steepest reformulation burden due to metal-to-plastic bonding requirements in adjustable beam housings.
Seasonal design velocity now determines retail shelf access, with mass-market buyers placing orders 8-10 months ahead of spring selling seasons. Lights4fun and comparable specialists are compressing product development cycles to 90-day turnaround for proprietary string-light form factors, displacing traditional 12-month category planning. This cadence shift is most visible in UK and German garden center channels where early listing commitments secure end-cap placement.
Garden Solar Lights Market Segmentation
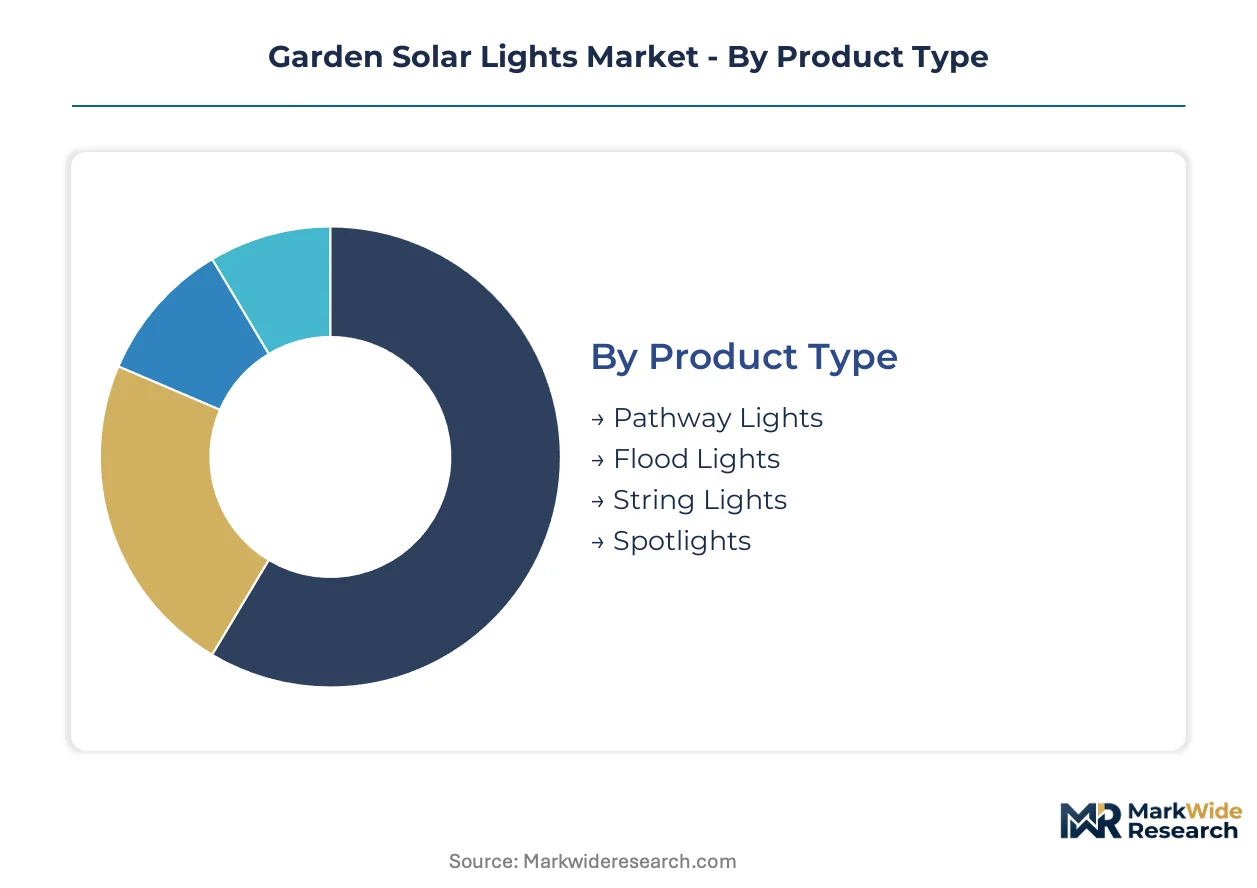
Garden solar lights manufacturers align R&D budgets and distribution partnerships around distinct segment performance profiles. Product type and technology choices determine margin capture, while end user and size categories shape channel strategy and warranty terms.
Product Type:
Margin pools concentrate in adjustable-beam architectures and decorative form factors where design differentiation commands pricing power.
- Pathway Lights:Standardized stake-mounted housings integrate monocrystalline panels with 15-20% conversion efficiency and automatic dusk-to-dawn sensors. Demand clusters in Arizona, Texas, and Florida suburban developments where solar irradiance supports year-round autonomous operation and HOAs mandate uniform landscape aesthetics.
- Spotlights:Adjustable beam housings with 200-800 lumen output and lithium-ion phosphate storage target security-conscious residential buyers. Higher unit economics reflect metal-to-plastic bonding complexity and IP65 ingress protection requirements.
- Flood Lights:Wide-coverage emitters for perimeter illumination prioritize lumen density over design differentiation.
- String Lights:Seasonal decorative form factors compete on design velocity and retail shelf timing.
The dominant share belongs to Pathway Lights, while Spotlights is closing the gap fastest.
Technology:
Cost tier stratification separates premium conversion efficiency from entry-level flexibility trade-offs.
- LED:Solid-state emitters with 50,000-hour rated lifespans dominate unit economics as chip costs decline. Residential buyers in premium suburban developments now expect color temperature adjustability and dimming compatibility as baseline specifications.
- Polycrystalline:Multi-crystalline silicon panels achieve 15-18% conversion efficiency at mid-tier price points. Kemeco leverages in-house wafer production to control cost curves across volume pathway and spotlight ranges.
- Lithium-ion:Phosphate chemistry packs displace nickel-metal hydride across premium tiers, compressing replacement cycles.
- Amorphous Silicon:Thin-film flexibility suits ultra-low-price entry products where 8-12% efficiency ceilings are acceptable trade-offs.
LED holds the installed base majority, though Polycrystalline panel integration is expanding most quickly.
End User:
Application context determines specification rigor and procurement channel.
- Residential:Suburban homeowners across Sun Belt states drive volume through mass-retail and direct-to-consumer channels. EPA Energy Star certification and FCC Part 15 emissions compliance shape product design requirements for US-bound shipments.
- Commercial:Hospitality and retail property managers prioritize durability warranties and bulk procurement terms.
- Landscape Designers:Specification professionals influence project-level decisions for high-end installations.
- Municipal:Public sector procurement follows extended qualification timelines and prevailing wage requirements.
Residential commands current volume leadership, with Commercial expanding at the steepest trajectory.
Size:
Physical scale correlates with panel area, battery capacity, and installation complexity.
- Small:Compact stake lights and accent fixtures suit container gardens and balcony installations.
- Medium:Standard pathway and entry-level spotlight configurations balance portability with performance.
- Large:Extended runtime systems with expanded photovoltaic surface area target security applications.
- Extra Large:Commercial-grade flood and area lighting with integrated pole mounting and remote monitoring capability.
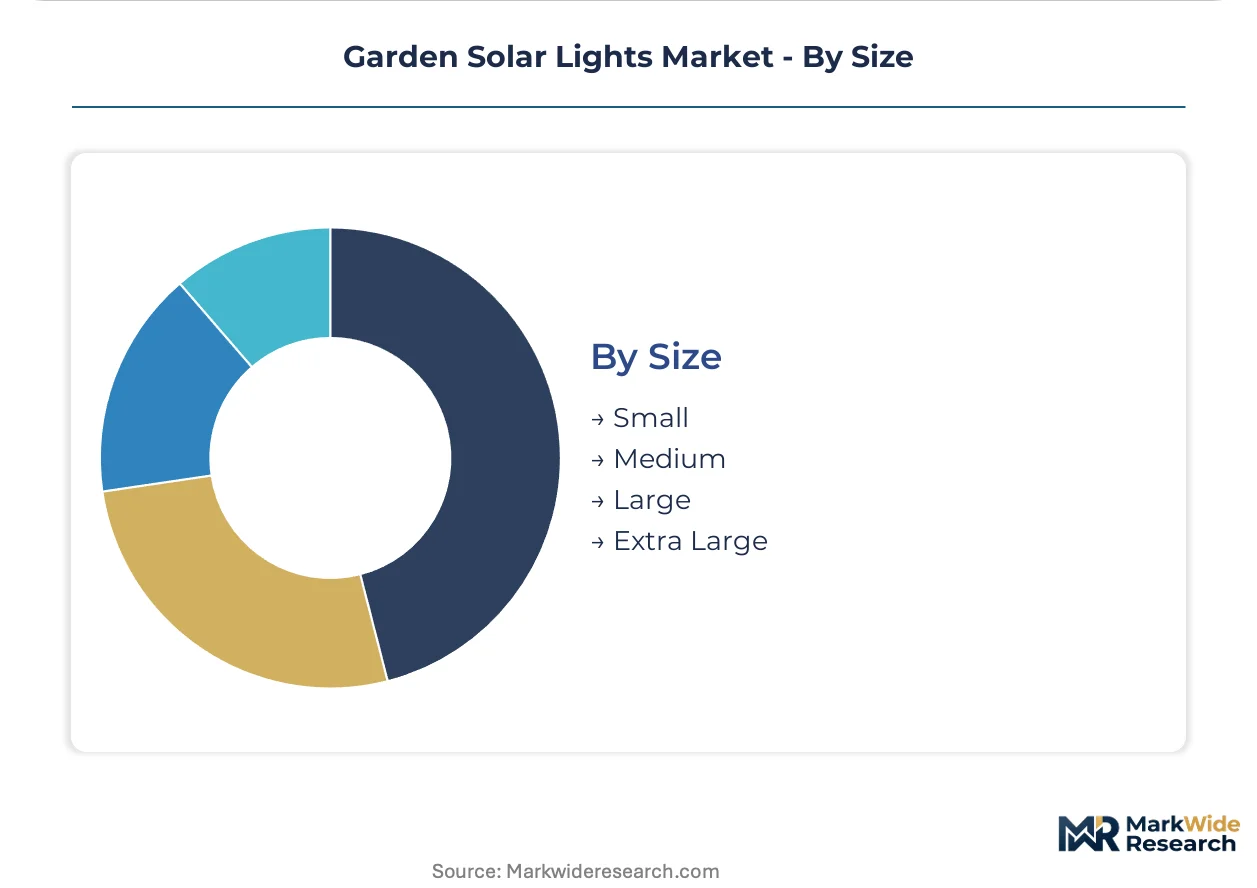
Medium size specifications anchor current production volumes, while Large formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Garden solar lights consumption patterns diverge sharply by geography. Sun Belt homeowners prioritize year-round autonomous operation, while European buyers emphasize circularity compliance and corrosion resistance for coastal installations.
United States
Arizona, Texas, and Florida suburban developments drive volume through mass-retail channels and HOA-mandated landscape uniformity. EPA Energy Star certification and FCC Part 15 emissions compliance shape product design requirements for domestic-bound shipments. Dallas-Fort Worth corridor retailers report accelerated pathway light turnover ahead of spring selling seasons.
China
Export-oriented manufacturers serving North American and European buyers dominate production capacity. MEE carbon-intensity benchmarks and GB standards for solar consumer products tighten manufacturing footprints. Yangtze River Delta factory clusters automate crystalline silicon panel assembly to meet dual carbon goals efficiency mandates.
Germany
Garden center channels demand early listing commitments 8-10 months ahead of spring cycles. EU RoHS restrictions and REACH substance constraints constrain solder compositions and housing plastics. Bavaria-based distributors specialize in corrosion-resistant finishes for North Sea coastal properties.
United Kingdom
Salt-air degradation in coastal markets creates demand for marine-grade seals and anodized aluminum housings. The Solar Centre sustains market presence through specialized coastal-grade corrosion finishes. Southeast England retail clusters emphasize seasonal design velocity for proprietary string-light form factors.
Japan
Residential buyers in premium suburban developments expect 20%+ conversion efficiency as baseline specification. METI efficiency guidelines influence lithium-ion phosphate battery chemistry adoption across premium tiers. Kanto region retailers stock extended runtime systems with expanded photovoltaic surface area for security applications.
Garden Solar Lights Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. Capital-intensity divergence between photovoltaic cell producers and assembly-only brands rotates competitive advantage toward firms with captive supply. Three archetypes populate the landscape: in-house wafer producers controlling cost curves, coastal corrosion specialists, and seasonal design velocity players. Dominant competitive moves include backward integration into polycrystalline production and accelerated product development cycles compressing 12-month planning to 90-day turnaround.
Within the integrated production tier, Kemeco leverages in-house polycrystalline wafer production to exemplify cost curve control. Among UK-based specialists, The Solar Centre occupies a position anchored in coastal-grade corrosion finishes. Lights4fun represents the design velocity archetype, with seasonal specialists releasing proprietary form factors ahead of retail buying cycles.
| Leading Market Players |
|---|
| 4lite |
| AloftSun |
| Better Homes & Gardens |
| Koda |
| ASMA |
| Kemeco |
| The Solar Centre |
| Cyhkee |
| Lights4fun |
| Others |
Value Network & Pricing Analysis
EPA Energy Star certification gates both supplier qualification and price differentiation simultaneously, creating tiered access to premium retail channels where certified products command measurable positioning advantages over uncertified alternatives. This regulatory filter compresses margins for assembly-only brands while rewarding integrated manufacturers with captive photovoltaic supply.
Pricing Analysis
Long-term offtake contracts for lithium-ion phosphate cells dominate procurement among premium-tier manufacturers, insulating them from spot-market volatility that erodes margin stability for spot-buying competitors. Three-tier pricing structure across premium, standard, and economy levels reflects conversion efficiency grades and certification status rather than brand equity alone. Cost compression in the amorphous silicon entry tier is intensifying because panel efficiency ceilings limit differentiation to housing aesthetics alone. Commercial property managers exhibit lowest price sensitivity due to durability warranty requirements, while mass-market residential buyers in suburban developments drive volume through promotional pricing responsiveness.
Supply Chain Analysis
China and South Korea anchor crystalline silicon wafer and cell production, with Yangtze River Delta factory clusters supplying the majority of photovoltaic-grade components for export-oriented garden light assembly. The supply chain draws from Xinjiang polysilicon refineries, lithium carbonate processing facilities in Qinghai, and LED emitter foundries in Taiwan and South Korea. Single-source vulnerability concentrates in polysilicon purification capacity where geographic concentration creates tariff and logistics chokepoint exposure. Distribution runs through mass-retail big-box channels in Sun Belt states, direct-to-consumer platforms for design-velocity specialists, and garden center networks across UK and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perovskite tandem cell commercialization is reshaping competitive positioning as laboratory-scale efficiency breakthroughs threaten to obsolete incumbent crystalline silicon architectures across premium product tiers.
For Market Incumbents: Shield market position by accelerating backward integration into lithium-ion phosphate cell production to control input cost curves against commodity volatility. Prioritize EPA Energy Star pre-certification investments to consolidate demand from California Title 24 compliance-driven new construction segments before efficiency thresholds tighten further. For New Entrants and Emerging Players: California Title 24 fast-track certification creates entry pathways for specialized coastal corrosion-resistant finishes targeting UK, Australian, and Japanese salt-air degradation markets. White-space concentrates in smart home integration modules compatible with Matter protocol specifications, where voice-control convergence remains underdeveloped relative to baseline consumer expectations. For Investors and Strategic Acquirers: China's MEE carbon-intensity benchmarks reshape the acquisition landscape by favoring export-oriented manufacturers with automated crystalline silicon assembly lines over legacy nickel-metal hydride-dependent operations. Long-term viability centers on firms with demonstrated phosphate chemistry transition completion and established coastal-grade finish capabilities. Monitor perovskite tandem pilot production announcements as the critical signal for next-generation panel architecture inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photovoltaic Cells | Kemeco's in-house polycrystalline wafer production exemplifies cost curve control across pathway and spotlight ranges. |
| Coastal Corrosion-Resistant Finish Development | The Solar Centre's marine-grade anodized aluminum housings capture UK salt-air degradation replacement cycles. |
| Seasonal Design Velocity Acceleration | Lights4fun's 90-day turnaround for proprietary string-light form factors secures end-cap placement ahead of spring cycles. |
| Smart Home Protocol Integration | Matter compatibility enables convergence with residential automation platforms where voice-control modules are migrating to baseline specification. |
| Perovskite Tandem R&D Partnerships | Laboratory-scale 26%+ efficiency achievements are drawing venture funding toward next-generation consumer solar applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, SEC filings from lighting and battery manufacturers, EPA Energy Star certification databases, and EU REACH substance restriction updates. Primary interviews engaged product development directors at integrated solar cell producers, procurement leads at mass-retail channel partners, regulatory compliance officers at export-oriented manufacturers, and category buyers at UK and German garden center networks. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction across the analysis window.
Segmentation dimensions modeled include product type architecture, photovoltaic cell technology tier, battery chemistry class, end-user application context, and physical size category. CAGRs derive from trend-line extrapolation of historical shipment data adjusted for technology substitution effects and regulatory mandate implementation timelines. Forecast inputs incorporate lithium carbonate spot price trajectory assumptions and perovskite tandem commercialization readiness indicators.
Decision-makers should treat outputs as directional under assumptions of continued lithium-ion phosphate cost decline and stable Sun Belt residential construction activity; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in MEE enforcement intensity and perovskite pilot production scale-up announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
Camping Utensils Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Golf Stand Bag Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Compound Bow and Crossbows Market
Outdoor & Sports
Kids Scooter Market