
 United States Lawn Care Market | 2026-2036
United States Lawn Care Market Size, Share, and Industry Trends Forecast 2026-2036
United States Lawn Care Market Analytics
Florida's commercial landscaping sector is consolidating as national providers absorb regional operators to capture year-round maintenance contracts. TruGreen Limited Partnership leverages its direct-to-consumer subscription model to sustain recurring revenue across suburban markets. BrightView Holdings, Inc. anchors its position through municipal and institutional contracts that span multi-year service agreements. Ruppert Landscape Inc. specializes in high-end commercial grounds management, differentiating through design-build capabilities that extend beyond routine maintenance.
United States lawn care encompasses the cultivation, treatment, and mechanical management of turfgrass across residential, commercial, and public properties, involving scheduled mowing, aeration, fertilization, and integrated pest management to maintain aesthetic and functional ground cover. The practice relies on calibrated equipment with cutting heights typically set between 2.5 and 4 inches depending on grass species and seasonal growth patterns, plus soil testing protocols that determine nutrient application rates. Lawn Maintenance generates the largest revenue pool within service type segmentation due to its recurring nature and high contract renewal rates, while Pest Control commands premium pricing because of specialized licensing requirements and liability exposure. Residential clients dominate client type segmentation by volume, though Commercial and Municipal accounts yield superior margins through scale economies and multi-site agreements.
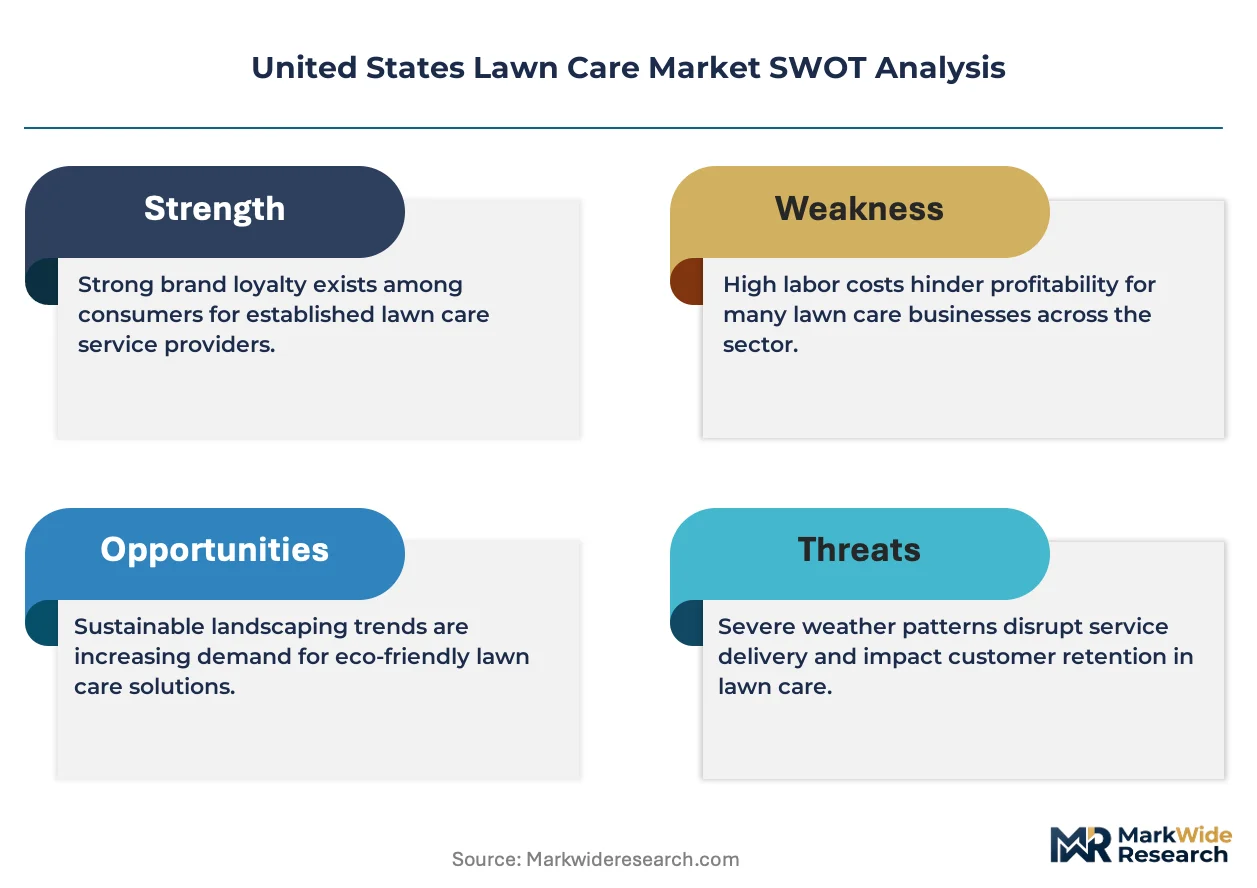
EPA oversight of pesticide applications under the Federal Insecticide, Fungicide, and Rodenticide Act shapes product availability and applicator certification requirements, while OSHA standards govern worker exposure limits during chemical handling and equipment operation. State-level regulations in California, Florida, and Texas impose additional restrictions on nitrogen fertilizer formulations and application timing near water bodies. Stakeholders must monitor evolving local ordinances restricting gasoline-powered equipment as municipalities advance electrification mandates that could reshape equipment procurement and service cost structures.
Market Dynamics
Subscription-based service models are compressing customer acquisition costs and locking in recurring revenue streams across residential lawn care, while electrification mandates in California and New York are forcing equipment fleet turnover ahead of natural replacement cycles.
Growth Catalysts
- EPA FIFRA enforcement:Tighter pesticide certification requirements raise barriers to entry, protecting incumbent service providers with established compliance infrastructure and trained applicator workforces.
- Year-round growing seasons:Sun Belt states from Florida to Arizona sustain continuous maintenance demand, eliminating seasonal revenue troughs that plague northern operators.
- Smart irrigation integration:IoT-enabled soil moisture sensors allow precision water delivery, reducing waste and enabling premium service tiers for water-conscious residential clients.
Market Restraints
- Labor cost volatility:H-2B visa caps constrain seasonal worker availability, forcing wage premiums in peak spring and fall application windows.
- Fertilizer input concentration:Nitrogen and phosphorus supply chains concentrate among Gulf Coast petrochemical producers, exposing margins to energy price shocks.
- Gasoline equipment phase-outs:California Air Resources Board mandates and similar ordinances in Denver and Washington D.C. compress usable equipment lifecycles.
Strategic Opportunities
- Texas municipal contracts:Rapid suburban expansion in Dallas-Fort Worth and Houston creates multi-site grounds management opportunities with decade-long service horizons.
- Carbon credit monetization:Soil carbon sequestration protocols under developing USDA conservation programs could unlock new revenue from lawn aeration and organic amendment services.
- Direct-to-consumer apps:On-demand scheduling platforms bypass traditional telemarketing, capturing younger homeowner demographics in Atlanta and Phoenix metro areas.
Industry Challenges
- Certified applicator shortages:State-level pesticide licensing exams face backlogs in Florida and Texas, delaying crew expansion during peak season.
- Electrification capex burdens:Battery-powered commercial mowers and blowers require 2-3x upfront capital versus gasoline equivalents, straining regional operator balance sheets.
- Legacy route density:Suburban sprawl patterns fragment service territories, raising drive-time costs and complicating technician scheduling optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Lawn Care Market |
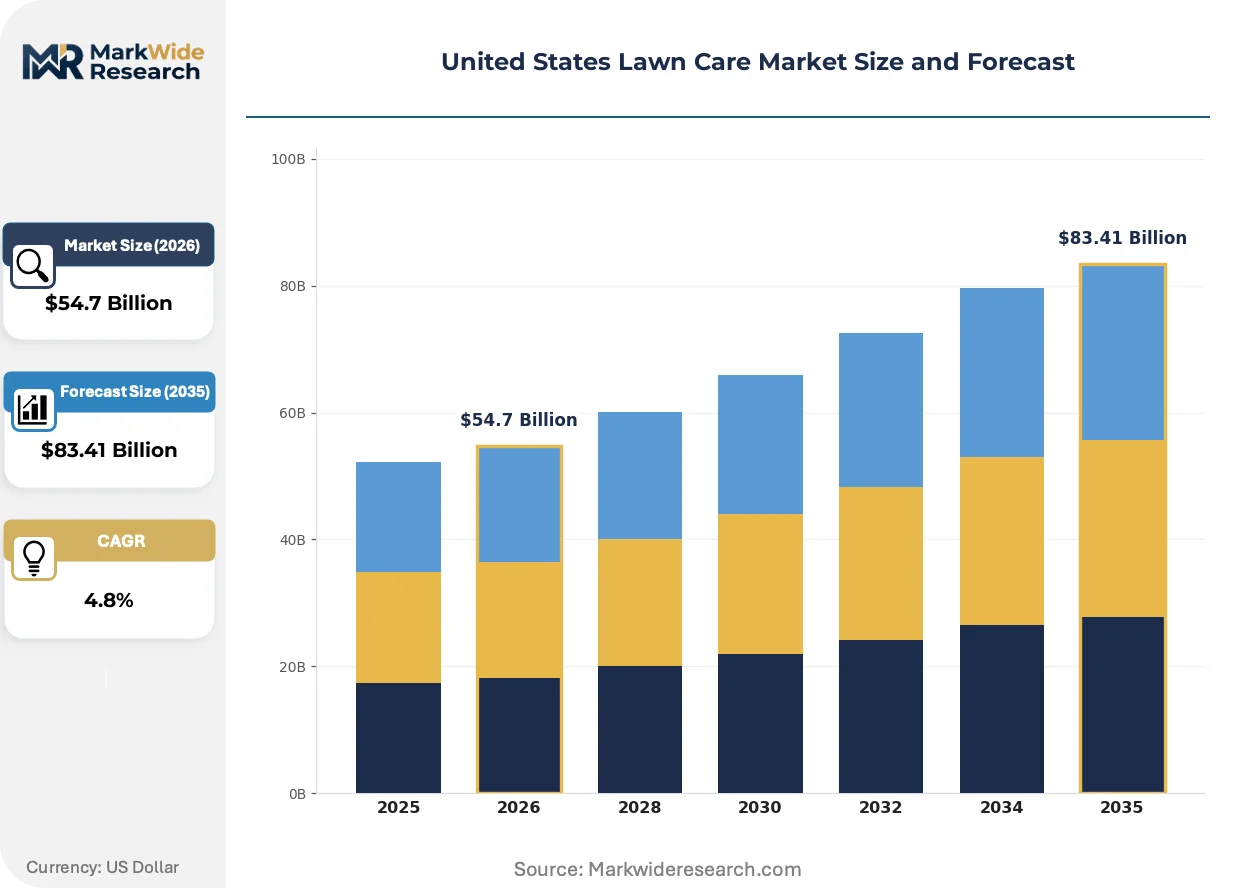
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $83.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Lawn Maintenance, Pest Control, Fertilization, Landscaping Client Type: Residential, Commercial, Municipal, Institutional Product Type: Grass Seed, Fertilizers, Herbicides, Equipment Distribution Channel: Online Retail, Garden Centers, Home Improvement Stores, Distributors |
| Companies Covered | Ruppert Landscape Inc., Lawn Doctor, BrightView Holdings, Inc., Monarch Landscape Companies, HeartLand LLC, The Davey Tree Expert Company, Gothic Landscaping Inc., Spring Green Lawn Care Corp., TruGreen Limited Partnership, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Lawn Care Market Evolving Landscape
Equipment electrification and precision application technologies are compressing operational margins for traditional operators while opening premium service tiers. Regulatory fragmentation across states is forcing national providers to maintain multiple compliance protocols.
Battery-powered commercial mowers and handheld equipment are decentralizing service operations by eliminating fuel logistics and enabling indoor storage in dense urban markets. Mid-sized operators in Miami and Los Angeles are retrofitting fleets faster than national chains, capturing municipal contracts with zero-emission mandates. This technology is decentralizing competitive advantage toward regional players with localized electrification expertise.
EPA Region-specific nutrient management plans are tightening nitrogen application windows near Chesapeake Bay and Great Lakes watersheds. The restrictions force split-application protocols that raise service visit frequency and labor intensity. Residential customers in Maryland and Wisconsin face higher annual contract costs as providers pass through compliance-driven operational complexity.
Homeowner association bulk contracting is consolidating individual subscriptions into negotiated multi-property agreements in master-planned communities. Arizona and Nevada retirement developments now procure lawn care through HOA boards rather than individual households. This shift compresses customer acquisition costs for winning bidders while locking out competitors from entire subdivisions.
United States Lawn Care Market Segmentation
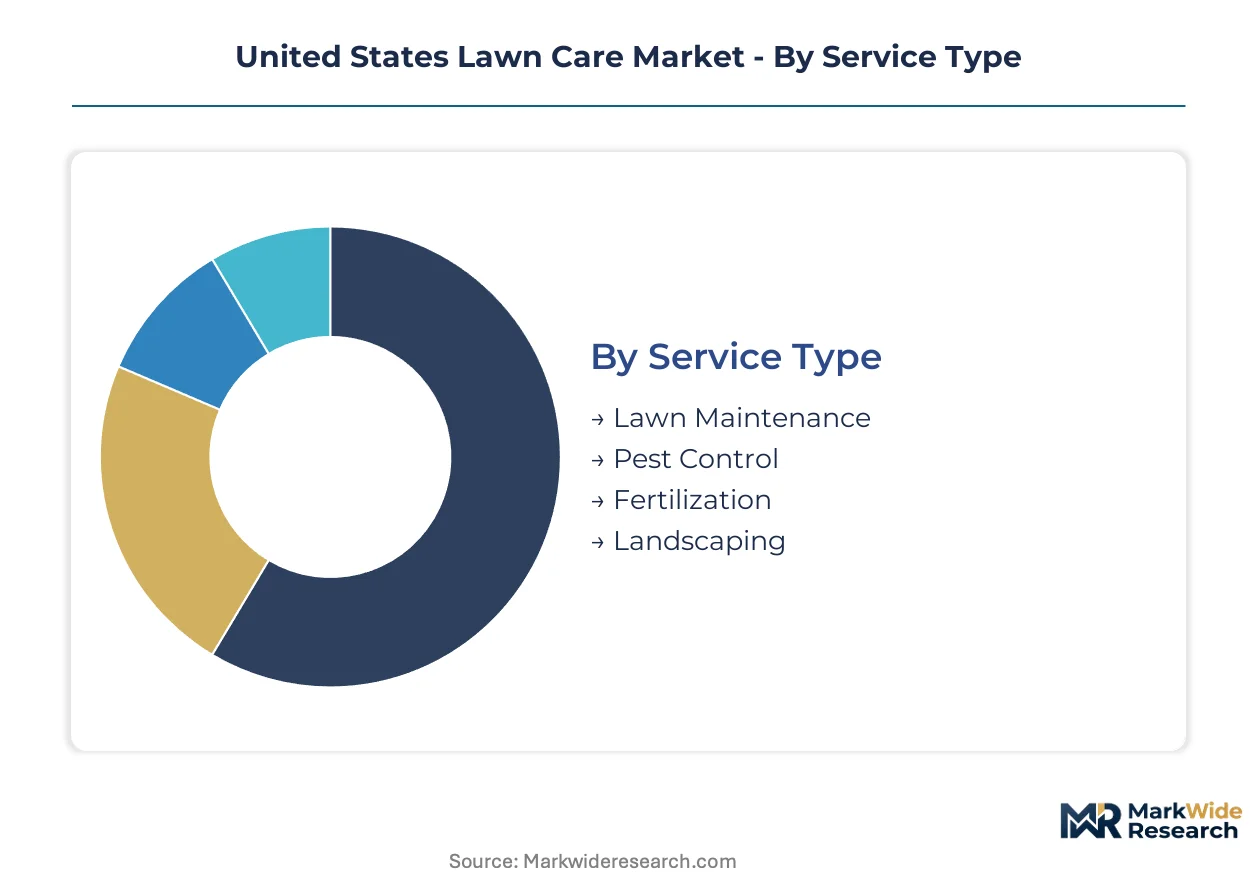
Service mix and client concentration patterns determine margin structure and regulatory exposure across the United States lawn care landscape. Segmentation reveals where EPA FIFRA licensing burdens concentrate and which channels capture recurring versus episodic demand.
Service Type:
EPA applicator certification requirements vary sharply by service category, with pesticide-intensive segments demanding licensed technicians and specialized liability coverage.
- Lawn Maintenance:Scheduled mowing, edging, and debris removal performed with calibrated equipment across weekly or biweekly intervals. Demand concentrates in Sun Belt suburban markets where year-round growing seasons eliminate seasonal contract suspensions and sustain continuous crew utilization.
- Pest Control:Integrated pest management combining biological controls with targeted pesticide applications under FIFRA-mandated protocols. Commercial property managers in Florida and Texas drive premium pricing due to fire ant, grub, and chinch bug pressures that threaten turf viability.
- Fertilization:Soil-test-driven nutrient application with split-dose protocols near Chesapeake Bay and Great Lakes watersheds. Maryland and Wisconsin operators face compressed application windows under EPA Region-specific nutrient management plans.
- Landscaping:Design-build and hardscape installation extending beyond recurring maintenance into capital-intensive property transformation. Arizona retirement communities and Texas master-planned developments generate concentrated project pipelines.
Lawn Maintenance sits at the top of the volume ranking, with Pest Control climbing the fastest.
Client Type:
Contract structure and procurement sophistication separate price-sensitive residential subscriptions from multi-year municipal agreements with performance bonding requirements.
- Residential:Individual homeowners purchasing subscription services through direct-to-consumer channels or HOA-negotiated bulk contracts. Atlanta and Phoenix metro areas show accelerating app-based scheduling adoption among younger demographics.
- Commercial:Office parks, retail centers, and multi-family housing requiring consistent aesthetic standards across dispersed locations. Dallas-Fort Worth suburban expansion creates multi-site grounds management opportunities with decade-long service horizons.
- Municipal:City parks, street medians, and public facilities procuring through competitive bidding with prevailing wage and minority contractor requirements. California cities increasingly specify zero-emission equipment in RFPs.
- Institutional:Universities, hospitals, and government campuses with dedicated facilities staff and capital planning cycles. BrightView Holdings anchors market position through multi-year service agreements in this segment.
Residential commands the largest transaction count, with Commercial expanding most quickly as suburban office construction accelerates.
Product Type:
Input procurement patterns reveal supply chain concentration risks and margin pressure points across fertilizer, chemistry, and equipment categories.
- Grass Seed:Cool-season and warm-season cultivars selected for regional climate adaptation and drought tolerance. Kentucky bluegrass dominates northern markets while Bermuda and St. Augustine varieties concentrate in southern states.
- Fertilizers:Nitrogen-phosphorus-potassium formulations with controlled-release technologies reducing application frequency. Gulf Coast petrochemical supply concentration exposes pricing to natural gas feedstock volatility.
- Herbicides:Pre-emergent and post-emergent chemistries governed by FIFRA registration and state-level restricted-use designations. California and New York impose additional formulation restrictions beyond federal baselines.
- Equipment:Commercial mowers, aerators, and handheld tools facing accelerated replacement cycles under California Air Resources Board electrification mandates. Battery-powered platforms require 2-3x upfront capital versus gasoline equivalents.
Fertilizers generate the highest input spend, with Equipment showing the steepest cost inflation trajectory.
Distribution Channel:
Channel selection determines customer acquisition economics and inventory carrying costs across fragmented retail and professional supply networks.
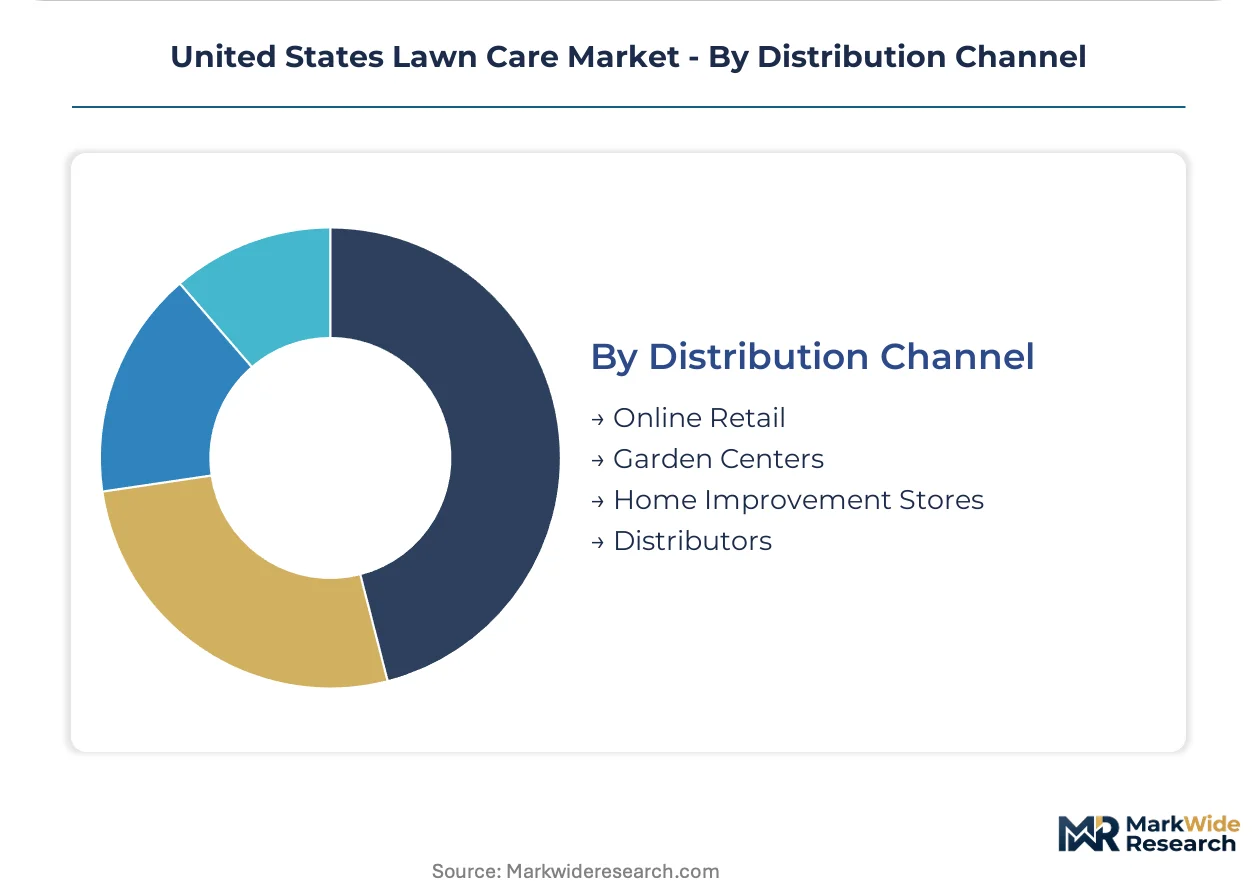
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing younger homeowners in Atlanta and Phoenix metro areas. Subscription replenishment models lock in recurring fertilizer and seed purchases.
- Garden Centers:Independent and regional chains offering localized cultivar expertise and seasonal merchandising. Sun Belt states sustain year-round foot traffic absent in northern seasonal markets.
- Home Improvement Stores:Big-box retailers with private-label chemistry and equipment lines competing on price transparency. DIY maintenance segments concentrate here amid rising labor cost sensitivity.
- Distributors:Professional supply houses serving licensed applicators with bulk formulations and technical support. EPA certification requirements restrict access to restricted-use products.
Home Improvement Stores lead transaction volume, with Online Retail gaining share fastest among suburban millennials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping operator migration patterns as state-level electrification mandates and fertilizer restrictions create compliance-cost gaps. Service providers gravitate toward jurisdictions with lighter equipment-phase-out timelines and extended growing seasons. The Sun Belt corridor captures disproportionate expansion capital as northern operators confront compressed revenue windows and accelerated fleet replacement cycles.
Florida
Year-round maintenance demand sustains continuous crew utilization across the peninsula's subtropical climate. EPA Region-specific nutrient management plans tighten phosphorus application windows near the Everglades watershed. Miami-Dade and Orlando metropolitan clusters concentrate commercial landscaping consolidation as national providers absorb regional operators for recurring municipal contracts.
Texas
Rapid suburban expansion in Dallas-Fort Worth and Houston generates multi-site grounds management agreements with decade-long service horizons. H-2B visa constraints force wage premiums during peak spring application windows. Austin and San Antonio metropolitan areas anchor electrification pilot programs as municipal RFPs increasingly specify zero-emission equipment mandates.
California
California Air Resources Board mandates compress usable equipment lifecycles ahead of natural replacement schedules. OSHA standards govern worker exposure limits during chemical handling in the state's intensive agricultural-adjacent turf markets. Los Angeles and San Diego metropolitan operators retrofit battery-powered fleets faster than national chains to capture zero-emission municipal contracts.
Arizona
Retirement community master-planned developments consolidate individual subscriptions into HOA-negotiated bulk procurement agreements. Smart irrigation integration penetrates deepest here as water scarcity drives premium service tier adoption. Phoenix and Tucson metropolitan clusters concentrate design-build capabilities for capital-intensive property transformation projects.
Georgia
Atlanta metropolitan expansion drives app-based scheduling adoption among younger homeowner demographics seeking on-demand service platforms. EPA FIFRA enforcement raises barriers to entry, protecting incumbent providers with established compliance infrastructure. Savannah and Augusta regional markets sustain traditional subscription models with lower technology penetration rates.
United States Lawn Care Market Competitive Landscape
Sun Belt operators anchor the volume-driven tier; Midwest and Northeast specialists hold position through seasonal contract density and municipal relationship depth. The vendor base stratifies across national subscription platforms, regional design-build specialists, and local maintenance operators. Three archetypes dominate: direct-to-consumer subscription providers, institutional contract anchors, and high-end commercial grounds management specialists. Consolidation through regional operator absorption and fleet electrification partnerships represent the dominant competitive vectors reshaping market structure.
Within the subscription-model tier, TruGreen Limited Partnership exemplifies recurring revenue architecture through direct-to-consumer channels. BrightView Holdings, Inc. occupies the institutional anchor position, securing multi-year service agreements with municipal and campus clients. Ruppert Landscape Inc. represents the high-end commercial specialist archetype, differentiating through design-build capabilities that extend beyond routine maintenance protocols. These three entities collectively illustrate the strategic segmentation governing competitive positioning across service type and client sophistication levels.
| Leading Market Players |
|---|
| Ruppert Landscape Inc. |
| Lawn Doctor |
| BrightView Holdings, Inc. |
| Monarch Landscape Companies |
| HeartLand LLC |
| The Davey Tree Expert Company |
| Gothic Landscaping Inc. |
| Spring Green Lawn Care Corp. |
| TruGreen Limited Partnership |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up regional specialists dominate the vendor base, concentrating procurement leverage and enforcing pricing discipline through centralized fertilizer purchasing and fleet standardization. Their scale-driven cost absorption creates margin pressure on family-owned operators while enabling subscription-model price anchoring across suburban markets.
Pricing Analysis
Distributor margins on professional-grade equipment and bulk chemistry compress as national providers negotiate direct manufacturer relationships. Three-tier pricing structure across premium organic services, standard synthetic programs, and economy DIY products separates EPA-certified applicator bundles from unlicensed maintenance-only tiers. Pricing pressure stems from battery-powered fleet replacement cycles mandated by California Air Resources Board rules. Residential subscription clients show highest price sensitivity, while municipal contracts with zero-emission specifications tolerate premium positioning.
Supply Chain Analysis
H-2B visa processing backlogs in Mexico and Central America constrain seasonal technician availability, forcing wage premiums that propagate through service pricing. Nitrogen fertilizer production concentrates along the Gulf Coast petrochemical corridor, with phosphorus sourcing anchored in Florida and imported Moroccan rock phosphate. Single-source vulnerability to natural gas feedstock volatility threatens margin stability. Distribution runs through professional supply houses for restricted-use chemistry and big-box retailers for consumer DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States lawn care market represents a late-cycle quality story as water-conscious homeowners shift demand toward smart irrigation-integrated premium service tiers with measurable conservation outcomes.
For Market Incumbents: Extend route density through targeted absorption of suburban operators in Dallas-Fort Worth and Atlanta corridor markets. Consolidate backward into captive fertilizer blending capacity to offset Gulf Coast petrochemical price volatility. Defend against battery-electric fleet mandates by accelerating California pilot programs ahead of regulatory deadlines. For New Entrants and Emerging Players: Begin with app-based on-demand scheduling platforms targeting younger homeowner demographics in Phoenix and Atlanta metro areas where traditional subscription penetration lags. White-space opportunities concentrate in HOA-negotiated bulk procurement for Arizona retirement developments and Texas master-planned communities. Go-to-market positioning should emphasize zero-emission equipment specifications to capture municipal RFP preferences. For Investors and Strategic Acquirers: Valuations sit cheapest among regional design-build specialists with established municipal relationships and underutilized fleet capacity. Long-term viability hinges on electrification transition execution and carbon credit protocol participation under developing USDA conservation programs. Monitor EPA Region-specific nutrient management plan expansions as signal for compliance-cost inflection that favors scaled operators.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Battery-powered mower procurement agreements with California municipalities lock in multi-year zero-emission contract eligibility. |
| Smart Irrigation Platform Integration | IoT sensor deployment enables premium water-conscious service tiers with measurable conservation outcomes for Scottsdale and Phoenix homeowners. |
| Regional Operator Consolidation | Absorption of Dallas-Fort Worth specialists captures decade-long multi-site grounds management agreements with suburban office developers. |
| Carbon Credit Protocol Development | Soil carbon sequestration certification through USDA conservation programs unlocks new revenue from aeration and organic amendment services. |
| Direct-to-Consumer App Launch | On-demand scheduling platforms bypass traditional telemarketing to capture millennial homeowner segments in Atlanta corridor markets. |
Research Methodology
Direct dialogue with lawn care operations managers, EPA-certified applicator training directors, municipal procurement officers, and HOA board representatives grounded qualitative findings in field-level operational realities. Secondary validation drew from EPA FIFRA registration databases, state-level pesticide licensing records, California Air Resources Board equipment certification filings, and municipal RFP archives. Bottom-up crew utilization models and top-down market size estimates triangulated volume and value outputs across service type and client segments.
Bottom-up modeling aggregated route-level productivity assumptions, contract renewal rates, and input cost trajectories across geographic clusters. Segmentation dimensions included service type intensity, client procurement sophistication, equipment propulsion category, and regional regulatory stringency. CAGRs derived from historical growth pattern analysis applied to projected subscription penetration and electrification mandate compliance timelines. Forecast inputs incorporated H-2B visa allocation trends and Gulf Coast petrochemical capacity utilization.
Several conditions sit outside the modeled scope, including unscheduled EPA FIFRA re-registration withdrawals, abrupt H-2B program suspension, and municipal bankruptcy cascades affecting multi-year contract enforceability. Forecasts reflect assumptions about steady electrification subsidy continuity and stable natural gas feedstock pricing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Hedge Trimmer Market
Home & Garden
Artificial Plants Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Christmas Decorations Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Candle Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Automated Blinds and Shades Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Gardening Pots Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
Incense Market
Home & Garden
Outdoor Cooking Table Market