
 Saudi Arabia Refrigerated Trailer Market | 2026-2036
Saudi Arabia Refrigerated Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Refrigerated Trailer Market Insights
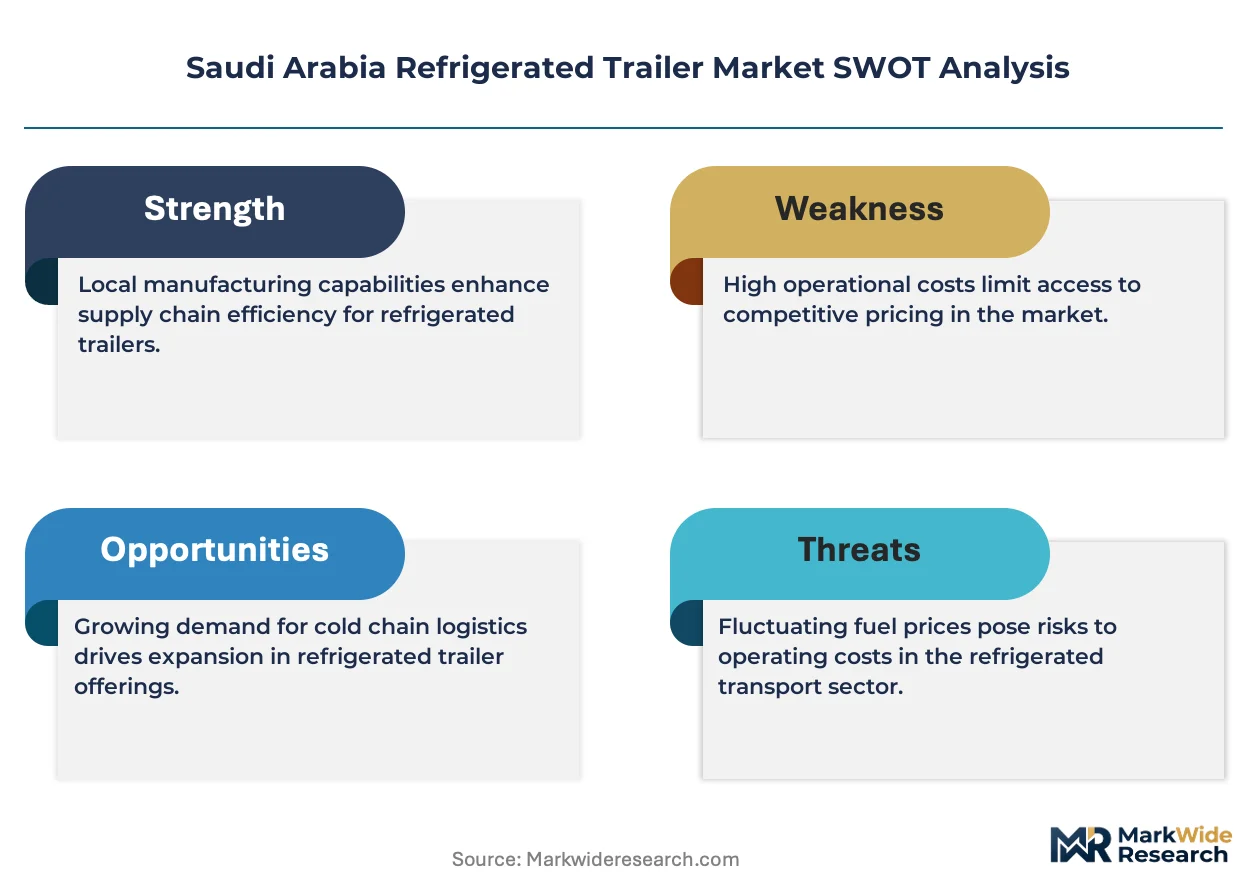
Saudi Arabia is tilting toward cold-chain infrastructure expansion under Vision 2030 food security targets. Coldstores Group of Saudi Arabia leverages vertical integration across warehousing and fleet operations. DHL Group sustains cross-border pharmaceutical logistics dominance through temperature-validated corridors. TSSC Group anchors domestic manufacturing with insulated panel production for regional trailer assembly.
A refrigerated trailer is a thermally insulated vehicle coupled to a tractor unit, equipped with integrated refrigeration units capable of maintaining cargo temperatures between minus 25 degrees Celsius and plus 25 degrees Celsius for perishable goods transport. Its primary commercial purpose is preserving product integrity across pharmaceutical, food, and grocery distribution networks. Tri-axle configurations lead the type segment due to payload efficiency on Saudi long-haul routes between Riyadh and Dammam. Reefer-based temperature control commands the technology dimension as SFDA mandates tighten pharmaceutical cold-chain documentation. Heavyweight vehicle sizes occupy the margin pool where fleet operators prioritize cubic capacity over fuel economy on highway corridors.
SFDA enforcement of Good Distribution Practice for pharmaceuticals directly shapes trailer specification requirements across Saudi fleets. SASO energy-efficiency labeling and GCC-wide Euro V/VI emission standards restrict import eligibility for older refrigeration engine technologies. Stakeholders must monitor how Saudi Ports Authority cold-chain expansion at King Abdulaziz Port reshapes fleet deployment patterns between maritime gateways and inland distribution centers.
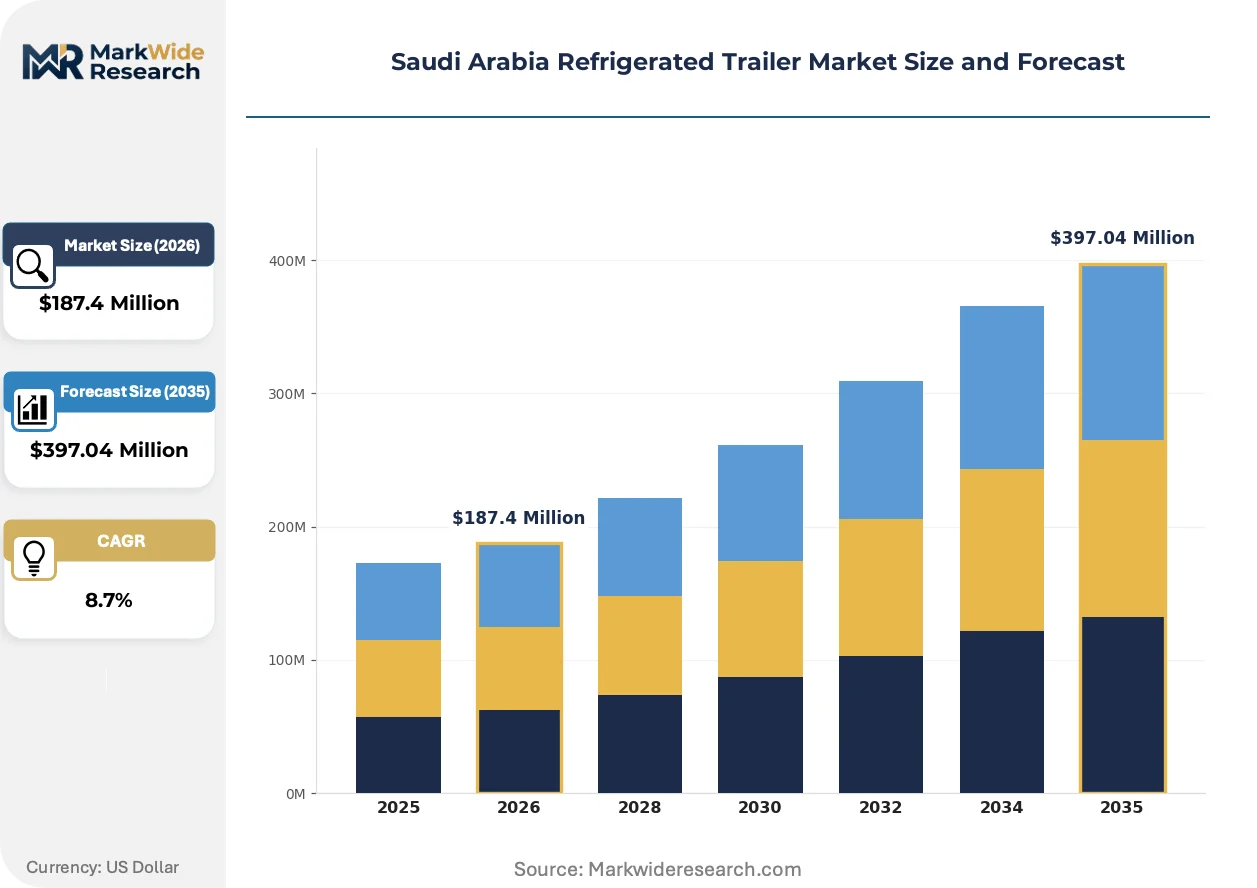
Market Dynamics
SFDA enforcement of pharmaceutical Good Distribution Practice is compressing fleet replacement cycles and forcing specification upgrades across Saudi cold-chain operators. This regulatory pressure is virtualizing equipment procurement priorities toward temperature-validated documentation systems.
Growth Catalysts
- Vision 2030 food security mandates:Government targets for domestic food production are expanding refrigerated distribution capacity from farm-gate to retail shelf.
- Euro V/VI engine standards:SASO import restrictions on older refrigeration units are accelerating fleet modernization toward compliant engine technologies.
- Pharmaceutical cold-chain expansion:Biologics and vaccine distribution requirements are pulling specialized reefer specifications into Riyadh and Jeddah logistics corridors.
Market Restraints
- Refrigeration unit import dependency:Core compressor and engine systems concentrate in European and East Asian manufacturing bases, exposing operators to currency volatility and lead-time extension.
- Specialized technician scarcity:Thermo King and Carrier Transicold systems require certified maintenance capacity that remains underdeveloped outside major urban centers.
- Insulated panel material costs:Polyurethane foam and aluminum skin pricing fluctuates with petrochemical feedstock indices, compressing trailer assembler margins.
Strategic Opportunities
- Asir and Tabuk agricultural zones:Underpenetrated highland farming regions are developing export-oriented cold-chain infrastructure for temperature-sensitive produce.
- Red Sea coastal logistics:King Abdullah Port expansion is creating demand for port-to-inland refrigerated shuttle services connecting to Riyadh distribution centers.
- Telematics integration:Convergence of IoT sensors and blockchain documentation is enabling real-time temperature verification for SFDA audit compliance.
Industry Challenges
- Certification timeline compression:SFDA validation protocols for pharmaceutical transport equipment are extending procurement cycles and delaying fleet deployment.
- Legacy fleet integration:Older trailers lack sensor retrofit compatibility, forcing parallel fleet operations during multi-year replacement transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Refrigerated Trailer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single Axle, Dual Axle, Tri-Axle, Multi-Axle End User: Food Distribution, Pharmaceutical Transport, Grocery Chains, Catering Services Temperature Control: Reefer, Insulated, Active Cooling, Passive Cooling Vehicle Size: Lightweight, Medium, Heavyweight, Ultra-Heavyweight |
| Companies Covered | Coldstores Group of Saudi Arabia, DHL Group, Yarres International Logistics, ALBA, Alshehili, TSSC Group, Transworld Group, Al-Jomaih Equipment Company, Arabian Refrigeration Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Refrigerated Trailer Market Trends and Innovations
Telematics penetration is rewiring how Saudi fleet operators manage temperature compliance and asset utilization. Three concurrent developments are restructuring equipment specifications and service delivery models across the Kingdom.
Sensor-enabled cargo monitoring is virtualizing documentation workflows for pharmaceutical shipments. Biologics distributors in Riyadh are deploying integrated temperature-logging systems that stream data directly to SFDA audit portals. This connectivity layer is compressing manual record-keeping overhead while tightening liability exposure for cold-chain breaks.
SFDA's phased enforcement of Good Distribution Practice documentation is mandating redundant temperature verification across all pharmaceutical transport tiers. Fleet operators must now maintain calibrated backup sensors and automated alert protocols. The heaviest compliance burden falls on regional distributors serving hospital networks in Jeddah and Dammam.
Leasing structures are displacing outright purchase for mid-sized pharmaceutical logistics providers. Operators facing SFDA-mandated equipment refresh cycles are shifting toward full-service lease arrangements that bundle maintenance and compliance documentation. This preference is most pronounced among emerging distributors in the Eastern Province seeking to preserve working capital.
Saudi Arabia Refrigerated Trailer Market Segmentation
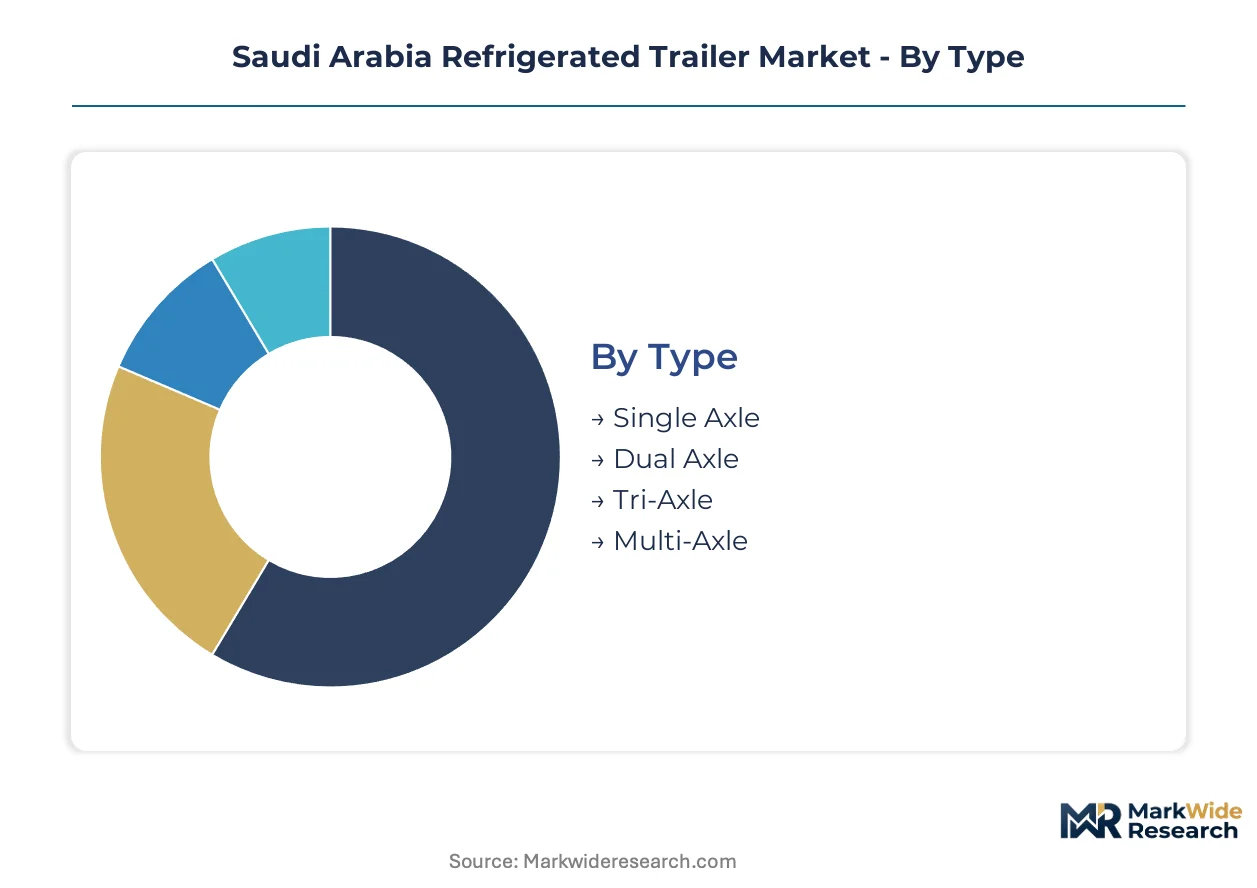
Saudi Arabia's refrigerated trailer market fragments across axle configuration, payload capacity, and temperature precision requirements. Each dimension reflects distinct operational economics shaped by Vision 2030 logistics corridors and SFDA pharmaceutical mandates.
Type:
Mature configurations dominate long-haul corridors while emerging multi-axle variants penetrate specialized heavy-lift segments.
- Single Axle:Compact urban delivery platforms with 10-12 ton capacity. Riyadh's last-mile grocery distributors favor these for tight maneuverability in dense retail zones.
- Dual Axle:Mid-range payload chassis serving intercity food distribution. Jeddah-to-Makkah refrigerated routes concentrate demand here due to balanced fuel economy and cubic capacity.
- Tri-Axle:Heavy-duty highway configurations with 30+ ton gross vehicle weight rating. The Riyadh-Dammam logistics corridor drives fleet procurement for pharmaceutical and frozen food consolidation.
- Multi-Axle:Specialized platforms exceeding four axles for oversized cargo. King Abdulaziz Port container drayage operators deploy these for combined reefer-heavyweight loads.
Tri-Axle retains volume leadership; Multi-Axle holds the steepest expansion curve.
End User:
Application intensity varies from high-frequency grocery replenishment to compliance-heavy pharmaceutical circuits.
- Food Distribution:Backbone segment spanning frozen proteins, dairy, and fresh produce. Domestic food security targets under Vision 2030 are expanding cold-chain coverage from Asir's highland farms to Riyadh retail terminals.
- Pharmaceutical Transport:Temperature-validated fleets serving biologics and vaccine distribution. SFDA Good Distribution Practice mandates force redundant sensor arrays and calibrated backup systems across hospital supply chains in Jeddah and Dammam.
- Grocery Chains:High-velocity replenishment networks for hypermarket operators. Daily delivery windows to Danube and Panda retail locations compress turnaround times and favor standardized trailer specifications.
- Catering Services:Event-driven and institutional foodservice logistics. Hajj and Umrah seasonal peaks create surge demand for temporary refrigerated capacity around Makkah and Madinah.
Food Distribution retains volume leadership; Pharmaceutical Transport holds the steepest expansion curve.
Temperature Control:
Technology tiers separate precision-dependent pharmaceutical applications from basic insulated transport.
- Reefer:Integrated mechanical refrigeration with compressor-driven temperature modulation. SFDA audit requirements for pharmaceutical corridors mandate these units with blockchain-enabled logging capabilities.
- Insulated:Passive thermal retention without active cooling. Short-haul frozen food transfers between Riyadh cold stores and retail DCs exploit these for cost containment on sub-four-hour routes.
- Active Cooling:Electric or cryogenic systems for ultra-low temperature maintenance. Vaccine distribution networks deploy these for minus 70 degrees Celsius stability requirements.
- Passive Cooling:Phase-change materials and gel packs for temporary temperature buffering. Last-mile pharmaceutical deliveries in Eastern Province hospital zones leverage these for compliance on short segments.
Reefer retains volume leadership; Active Cooling holds the steepest expansion curve.
Vehicle Size:
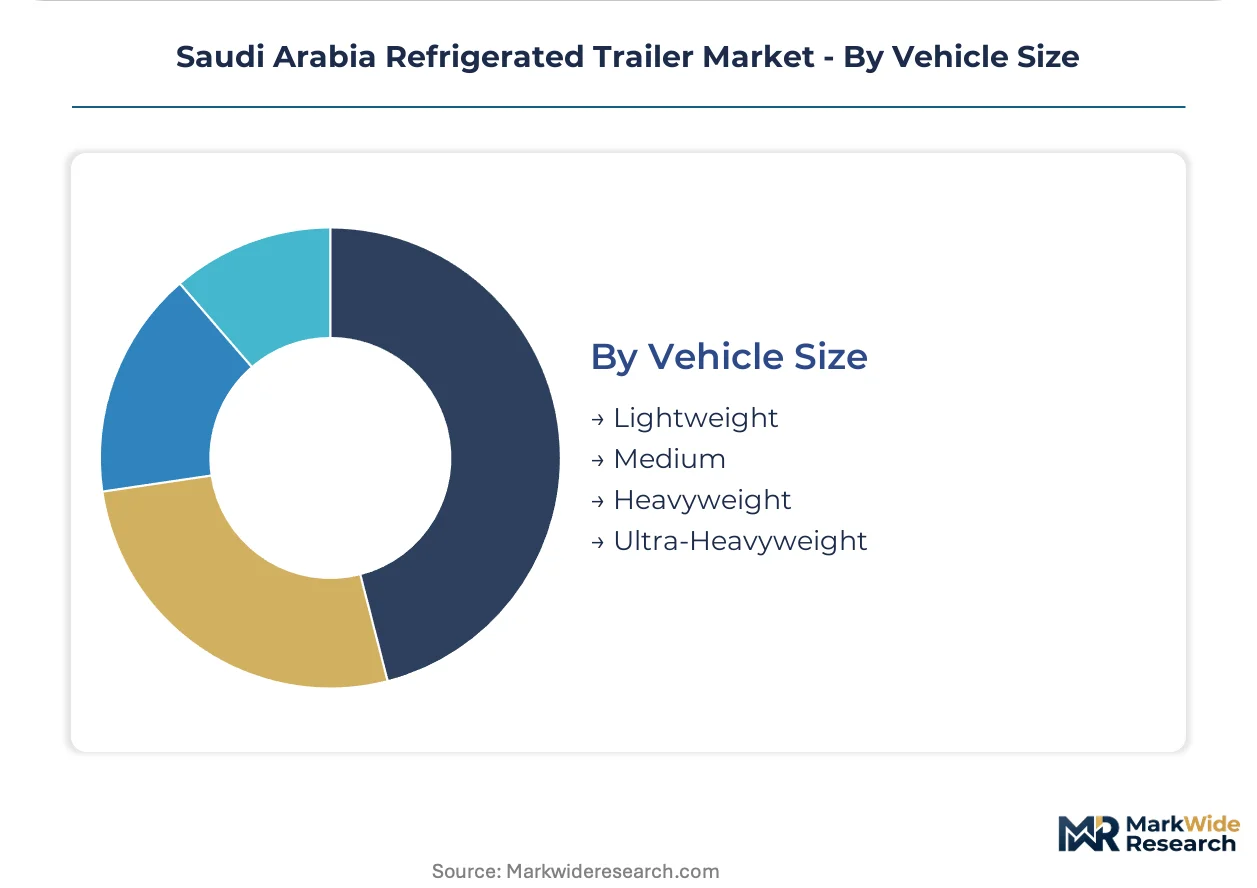
Payload economics favor heavyweight configurations on highway corridors while lightweight units penetrate constrained urban access points.
- Lightweight:Sub-3.5 ton gross vehicle weight for unlicensed operator access. Small-scale catering contractors and specialty food producers in Jeddah's old city districts prefer these for regulatory simplicity.
- Medium:3.5-12 ton range bridging urban and regional distribution. Regional dairy cooperatives in Qassim deploy these for farm-to-processor milk collection circuits.
- Heavyweight:12-20 ton configurations dominating intercity freight. Fleet operators prioritize cubic capacity over fuel economy on highway corridors connecting Riyadh, Dammam, and Jeddah.
- Ultra-Heavyweight:Exceeding 20 tons with specialized permitting requirements. King Abdullah Port's containerized reefer imports drive demand for these in port-to-inland shuttle services.
Heavyweight retains volume leadership; Ultra-Heavyweight holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's logistics corridor consumes refrigerated trailers for pharmaceutical consolidation while Jeddah's port-centric zones prioritize container drayage capacity. Eastern Province demand splits between petrochemical feedstock transport and hospital supply chains. Regional consumption patterns diverge sharply by cargo type and compliance burden.
Riyadh
Central Region food security distribution and biologics cold-chain consolidation dominate fleet procurement. SFDA pharmaceutical mandates force temperature-validated documentation systems across hospital supply networks. King Khalid International Airport's cargo zone anchors air-pharma shuttle operations linking to domestic distribution centers.
Eastern Province
King Abdulaziz Port container throughput and Jubail petrochemical complexes generate dual demand streams for reefer-heavyweight configurations. SASO import inspection protocols at Dammam customs points delay equipment clearance for non-compliant refrigeration units. Ras Al-Khair industrial zone's protein processing plants expand farm-to-port cold-chain coverage.
Jeddah
King Abdulaziz Port reefer container volumes and Makkah pilgrimage foodservice logistics concentrate demand in Western Region corridors. Red Sea coastal humidity accelerates insulated panel degradation, compressing fleet replacement cycles. King Abdullah Economic City's logistics park development redirects some port traffic inland.
Asir
Highland agricultural export zones and coffee cultivation regions develop temperature-controlled collection infrastructure. Vision 2030 rural development programs subsidize cold-store construction in previously unserved farming communities. Abha Regional Airport's perishable cargo terminal expansion targets GCC produce export markets.
NEOM Northwest
Giga-project construction logistics and planned food-tech vertical farming clusters pre-position specialized cold-chain capacity. Regulatory sandbox provisions for next-generation transport technologies attract pilot fleet deployments. Oxagon industrial city's port-to-inland corridor design integrates automated refrigerated shuttle concepts.
Saudi Arabia Refrigerated Trailer Market Competitive Landscape
Capability concentration sits with domestic fabricators possessing SFDA compliance documentation expertise; scale advantage sits with diversified logistics groups operating multi-modal cold-chain networks. The vendor base stratifies across three tiers: integrated warehousing-fleet operators, specialized trailer assemblers, and international logistics platforms with captive Saudi capacity. Two strategic archetypes dominate competitive positioning—vertically integrated cold-chain specialists and asset-light logistics orchestrators. Portfolio diversification into temperature-validated services and geographic expansion along Red Sea coastal corridors represent the dominant competitive moves.
Among domestic integrated operators, Coldstores Group of Saudi Arabia exemplifies the warehousing-fleet vertical integration archetype, while TSSC Group anchors the manufacturing-tier position through insulated panel production. DHL Group occupies the international logistics platform tier, representing cross-border pharmaceutical corridor dominance. Each entity sits within a distinct capability layer rather than competing directly across identical service definitions.
| Leading Market Players |
|---|
| Coldstores Group of Saudi Arabia |
| DHL Group |
| Yarres International Logistics |
| ALBA |
| Alshehili |
| TSSC Group |
| Transworld Group |
| Al-Jomaih Equipment Company |
| Arabian Refrigeration Company |
| Others |
Pricing and Supply Chain Analysis
Underutilized manufacturing capacity in European refrigeration compressor plants is compressing equipment pricing power while extending lead times for Saudi fleet operators. This capacity imbalance forces trailer assemblers toward longer-term procurement contracts that lock in component availability at the expense of pricing flexibility.
Pricing Analysis
Long-term offtake agreements dominate procurement for tri-axle pharmaceutical trailers serving SFDA-mandated corridors, insulating operators from spot volatility in compressor engine markets. Price differentiation hinges on Euro V/VI certification tier and bundled telematics documentation packages. Cost compression in standard food-distribution configurations is intensifying because polyurethane panel feedstock prices track volatile petrochemical indices. Grocery chain buyers exhibit highest price sensitivity due to thin margins on high-velocity replenishment routes, while biologics distributors prioritize compliance-grade specifications over unit economics.
Supply Chain Analysis
Export-control restrictions on precision refrigeration compressor technology from Germany and Japan limit component flows into Saudi assembly plants. Core engine systems draw from Italy, South Korea, and the United States, while insulated panel aluminum skins source from China and Turkey. Single-source vulnerability concentrates in Carrier Transicold and Thermo King distribution networks for post-sale service parts. Distribution runs through Jeddah and Dammam port customs clearance points before inland trucking to Riyadh assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's phased enforcement of blockchain-enabled temperature documentation is disrupting fleet procurement cycles and creating first-mover advantages for compliance-ready equipment suppliers.
For Market Incumbents: Pre-empt regulatory obsolescence by accelerating sensor retrofit programs for legacy pharmaceutical trailers before SFDA audit deadlines tighten. Deepen captive supply of insulated panel production through backward integration into polyurethane foam manufacturing, neutralizing petrochemical feedstock volatility that compresses assembler margins against emerging domestic competitors. For New Entrants and Emerging Players: Establish a beachhead in Asir's highland agricultural export corridor where Vision 2030 rural development subsidies are expanding cold-store construction without matching refrigerated fleet capacity. Target port-to-inland shuttle services at King Abdullah Port with telematics-integrated trailer leasing models that bundle SFDA compliance documentation for mid-sized pharmaceutical distributors seeking working capital preservation. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated cold-chain operators possessing both warehousing assets and captive fleet operations, as SFDA mandates favor end-to-end temperature accountability over fragmented service layers. Watch for inflection signals in King Abdulaziz Port reefer container throughput volumes, which indicate downstream fleet replacement demand intensity across the Eastern Province.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables real-time SFDA audit compliance for pharmaceutical corridor operators in Riyadh and Jeddah. |
| Backward Integration into Insulated Panel Production | Captures margin pool from polyurethane foam and aluminum skin cost volatility affecting trailer assemblers. |
| Geographic Expansion to Red Sea Coastal Logistics | Positions fleet assets at King Abdullah Port for port-to-inland shuttle demand connecting to Riyadh distribution centers. |
| Full-Service Lease Model Launch | Preserves working capital for mid-sized Eastern Province distributors facing compressed SFDA equipment refresh cycles. |
| Certification Investment for Euro V/VI Compliance | Secures SASO import eligibility as emission standards restrict older refrigeration engine technologies from European and East Asian sources. |
Research Methodology
A spread of perspectives from fleet operations managers, trailer assembly plant engineers, SFDA regulatory compliance officers, pharmaceutical logistics procurement leads, and cold-store facility directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SASO technical regulations, SFDA Good Distribution Practice guidelines, GCC customs trade databases, and Euro V/VI emission standard documentation. Bottom-up unit economics from individual trailer configurations were triangulated against top-down market sizing from logistics corridor freight volume indices.
Demand-supply balance modeling anchored forecasts across the analysis window, with segmentation dimensions spanning axle configuration, temperature control technology tier, end-use application intensity, and vehicle size classification. CAGRs were derived from installed base replacement cycles intersecting with regulatory mandate phase-in schedules. Industry-specific inputs incorporated SFDA audit protocol timelines, King Abdulaziz Port reefer container throughput trends, and Vision 2030 food security infrastructure allocation patterns.
Sensitivities concentrate around SFDA enforcement intensity for pharmaceutical documentation, Euro V/VI emission standard adoption timing, and petrochemical feedstock price volatility affecting insulated panel material costs. Forecasts reflect assumptions about regulatory compliance timelines and fleet modernization cadence. Material shifts in SFDA blockchain documentation mandates or SASO import restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
EGR Valve Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Car Modification Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Air Ride Suspension Systems Market