
 Game Streaming Market | 2026-2036
Game Streaming Market Size, Share, and Industry Trends Forecast 2026-2036
Game Streaming Market Analysis
GDPR enforcement in Europe is broadening compliance costs for platforms storing viewer data and processing microtransactions. Amazon.com, Inc. leverages its AWS backbone to sustain low-latency delivery across multiple continents. Microsoft Corporation anchors its Game Pass streaming tier through deep Xbox ecosystem integration. NVIDIA Corporation differentiates via GeForce NOW's hardware-agnostic model that operates across devices competitors cannot reach.
Game streaming delivers interactive video content from remote servers to end-user displays, typically requiring sub-50ms latency and adaptive bitrate protocols to maintain playability over variable network conditions. Its primary commercial purpose is to eliminate local hardware dependency while generating recurring revenue through access fees and in-stream monetization. Mobile platforms now lead subscriber additions across emerging markets where smartphone penetration outpaces console ownership. The freemium service model captures the largest user base but generates lower per-account yield than subscription tiers, while e-sports content commands premium advertising rates due to concentrated viewer engagement.
The FCC's broadband labeling rules in the United States and the EU's Digital Services Act together reshape how platforms disclose network requirements and content moderation practices to prospective subscribers. Japan's MIC enforces telecommunications quality standards that directly affect cloud gaming latency commitments in that market. Stakeholders must monitor evolving spectrum allocation decisions and data localization mandates that could reroute infrastructure investment toward specific regulatory environments.
Market Dynamics
Cloud gaming infrastructure is compressing hardware dependency while fragmenting platform control across console manufacturers, telecom operators, and pure-play streamers competing for recurring subscriber revenue.
Growth Catalysts
- 5G network densification:South Korea's spectrum allocation for millimeter-wave bands enables sub-20ms latency commitments that mobile-first platforms exploit for competitive gaming delivery.
- GDPR Article 17 compliance frameworks:Streamlined data portability rules across EU member states reduce friction for cross-border subscriber migration between competing services.
- Edge computing node deployment:Municipal fiber backhaul investments in São Paulo and Rio de Janeiro position Brazil's infrastructure for cloud gaming expansion without console hardware penetration.
Market Restraints
- Input cost volatility:GPU allocation contracts with foundries concentrate supply risk in Taiwan Semiconductor Manufacturing's capacity scheduling.
- Last-mile bandwidth asymmetry:Upload speed limitations in rural United States broadband deployments constrain interactive streaming quality for user-generated content creators.
- Substitute platform threat:Native mobile gaming app stores on iOS and Android capture casual session time that cloud services cannot economically reclaim.
Strategic Opportunities
- Underpenetrated geography:Indonesia's smartphone-first gaming population lacks domestic cloud infrastructure, creating first-mover positioning for regional data center investors.
- Regulatory tailwind:India's PLI scheme for electronics manufacturing incentivizes local server assembly that reduces import duty burdens on streaming hardware.
- Technology convergence:AI-driven upscaling algorithms paired with low-resolution base streams are integrating to cut bandwidth requirements by half without perceptible quality loss.
Industry Challenges
- Encoding talent scarcity:Real-time video compression engineers with H.266/VVC expertise command compensation premiums that inflate platform R&D budgets.
- Cross-platform certification complexity:Content rating harmonization between ESRB, PEGI, and CERO systems delays simultaneous multi-territory launches.
- Legacy codec migration friction:Subscriber devices lacking AV1 hardware decode force platforms to maintain parallel H.264 encoding pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Game Streaming Market |
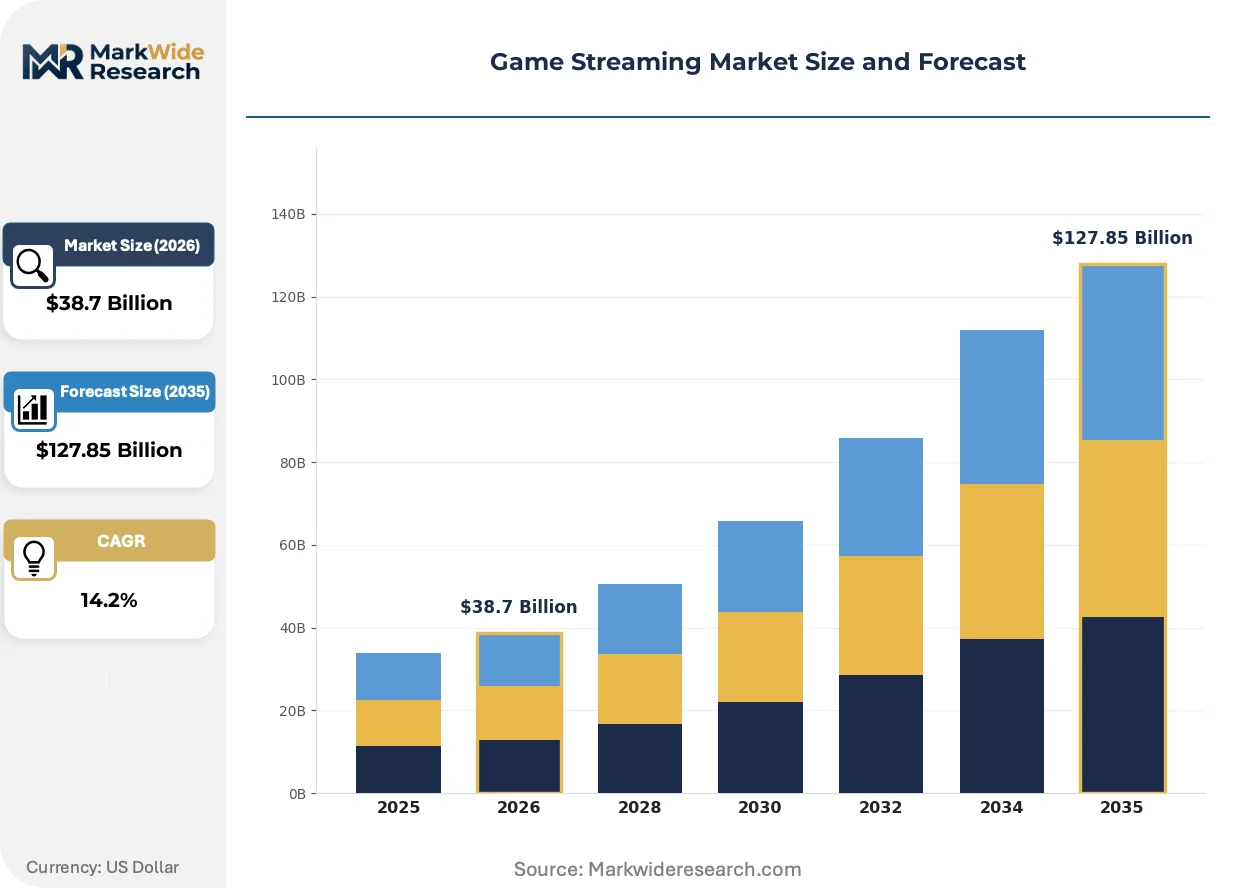
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Console, PC, Mobile, Smart TV Service Model: Subscription, Ad-supported, Transaction-based, Freemium Content Type: AAA Titles, Indie Games, Classic Games, E-Sports End User: Casual Gamers, Competitive Players, Content Creators, Viewers |
| Companies Covered | Amazon.com, Inc., Meta Platforms, Inc., Microsoft Corporation, Sony Group Corporation, NVIDIA Corporation, Alphabet Inc., Twitch, Huya Inc., DouYu International Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Game Streaming Market Emerging Trajectories
Adaptive bitrate protocols and AI-generated content moderation are compressing operational costs while expanding addressable device categories beyond traditional gaming hardware.
Server-side neural upscaling is integrating temporal anti-aliasing with machine learning inference to reconstruct high-resolution frames from computationally cheap base renders. Mid-tier mobile chipsets from MediaTek and Qualcomm now ship with dedicated NPU blocks that accelerate this workload locally. The structural consequence is that platform operators can serve premium visual quality to hardware that previously required discrete GPU allocation.
The EU Digital Services Act mandates algorithmic transparency for content recommendation systems that prioritize addictive engagement metrics. Platforms must disclose ranking parameters and provide user opt-out mechanisms for profile-based suggestions. Cloud gaming services operating in Germany and France are restructuring their home screen curation to comply while defending session duration metrics through manual editorial programming.
Consumption patterns among Gen Z subscribers favor bite-sized session formats under fifteen minutes that conflict with traditional AAA game design. Platforms are unbundling full titles into chapter-based access models that align with mobile attention spans. South Korean and Brazilian operators report highest adoption of this micro-session architecture where commute-time usage dominates peak traffic.
Game Streaming Market Segmentation
Streaming architectures vary dramatically across hardware endpoints and monetization mechanics, forcing platform operators to maintain parallel encoding pipelines and differentiated latency commitments. Understanding how subscriber behavior fragments across these axes determines infrastructure capex allocation and partnership prioritization.
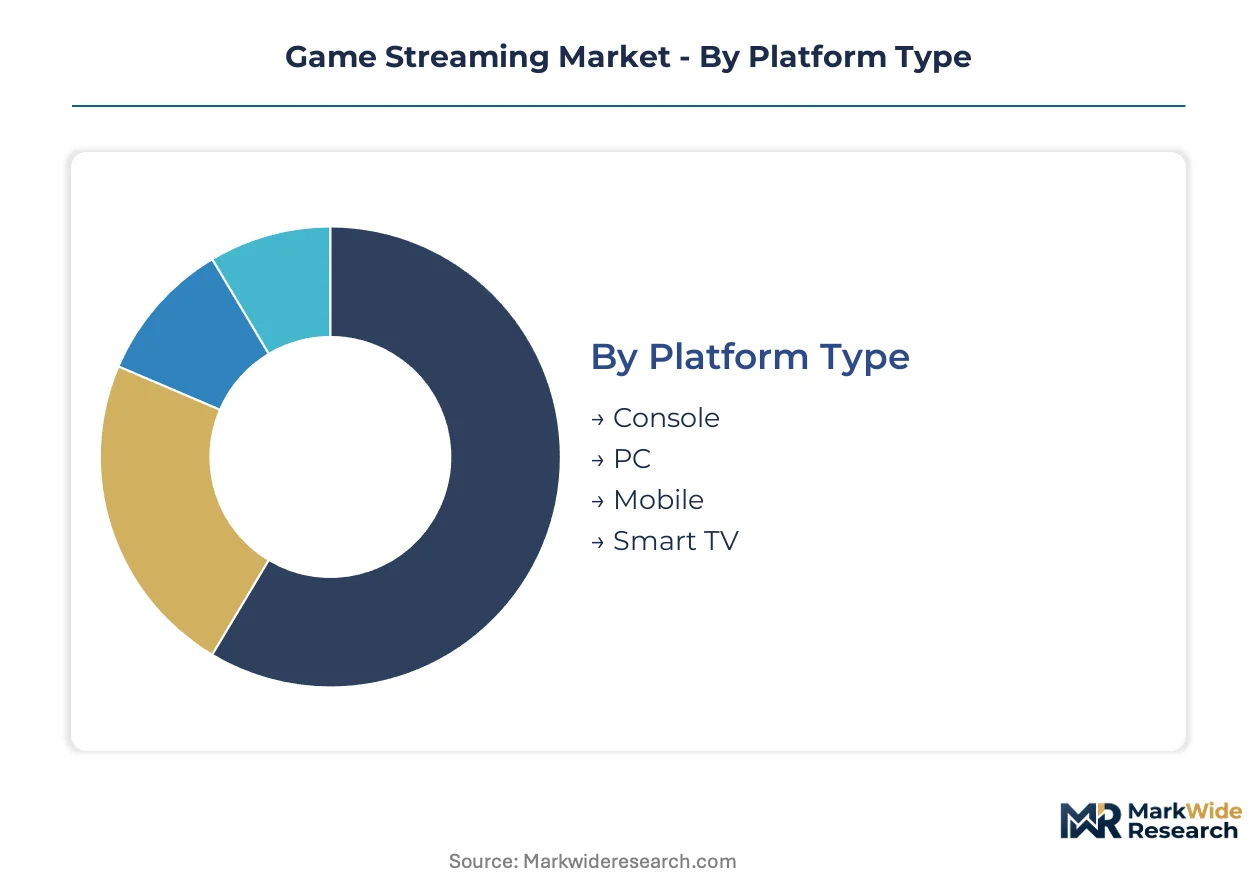
Platform Type:
Processing specifications and input latency tolerances diverge sharply across display categories, shaping server allocation topology and edge node placement strategy.
- Console:Dedicated decode hardware in PlayStation and Xbox units enables 4K60 streams with fixed 16ms frame pacing. Demand concentrates in the United States and South Korea where fiber-to-the-home penetration supports sustained bandwidth for HDR pipelines. Microsoft's Xbox Cloud Gaming anchors this segment through direct OS integration that eliminates third-party client friction.
- Mobile:ARM-based chipsets with heterogeneous compute clusters handle adaptive bitrate switching across cellular handoffs. Brazil and Indonesia drive subscriber additions where smartphone-first usage patterns dominate and console household penetration remains below fifteen percent. 5G millimeter-wave rollouts in São Paulo and Seoul compress latency variability for competitive multiplayer sessions.
- PC:Browser-based WebRTC clients leverage existing GPU decode capabilities without native application installation. Steam Deck and similar handheld x86 devices expand addressable hardware beyond traditional desktop towers.
- Smart TV:Embedded SoC limitations force platforms to stream at 1080p maximum on pre-2020 display panels, constraining visual fidelity for premium tier subscribers.
Console leads on scale; Mobile leads on momentum.
Service Model:
Revenue recognition timing and customer acquisition cost structures vary fundamentally across payment architectures, dictating cash flow profiles and churn mitigation tactics.
- Subscription:Recurring monthly fees generate predictable revenue streams that fund multi-year content licensing commitments. Xbox Game Pass Ultimate and NVIDIA GeForce NOW Priority tier anchor this model with priority server access guarantees.
- Ad-supported:Pre-roll and mid-session advertising inventory commands CPM premiums during e-sports broadcasts where viewer engagement concentrates. South Korean platforms report highest ad load tolerance among competitive gaming audiences.
- Transaction-based:Individual title rentals appeal to episodic players unwilling to maintain standing subscriptions. Japan's MIC telecommunications quality standards enforce latency SLAs that support this pay-per-use architecture.
- Freemium:Session time limits and resolution caps convert unpaid users toward premium tiers through graduated feature restriction. Brazilian operators deploy this model most aggressively given price-sensitive market dynamics.
Subscription captures the revenue base; Freemium expands the addressable funnel most rapidly.
Content Type:
Encoding complexity and concurrent viewer density fluctuate across game development budget tiers, requiring dynamic server provisioning algorithms.
- AAA Titles:Cinematic frame rates and ray-traced lighting demand GPU allocation ratios of one discrete card per concurrent stream. Publishers like Microsoft and Sony leverage first-party exclusives to anchor platform differentiation.
- E-Sports:Simplified visual fidelity enables 120fps delivery at 1080p with minimal server-side rendering overhead. South Korea's millimeter-wave infrastructure supports sub-20ms round-trip commitments essential for professional competitive integrity.
- Indie Games:Lower polygon counts and stylized aesthetics permit higher density per physical server, improving unit economics for price-sensitive segments.
- Classic Games:Emulation-layer overhead dominates compute requirements rather than raw graphics processing, favoring CPU-optimized instance types.
AAA Titles anchor platform prestige; E-Sports commands the steepest expansion trajectory in concurrent viewership metrics.
End User:
Session duration patterns and input device preferences segment the subscriber base into cohorts with diverging support cost profiles and lifetime value curves.
- Competitive Players:Sub-50ms latency requirements and frame-perfect input responsiveness drive premium tier subscriptions with priority server queue placement. South Korea and Brazil produce the highest density of ranked multiplayer participants per capita.
- Content Creators:Simultaneous stream ingestion and gameplay capture demand asymmetric upload bandwidth that rural United States broadband deployments often fail to provision. Twitch and YouTube Gaming integration shapes platform selection for this cohort.
- Casual Gamers:Intermittent session patterns under thirty minutes tolerate higher latency variance and standard tier server allocation. Mobile-first emerging markets concentrate this behavior.
- Viewers:Passive consumption of live streams and recorded content generates advertising inventory without requiring interactive compute resources, improving platform margin structure.
Viewers expand the user base most broadly; Competitive Players generate the highest per-account yield.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure engineers and video compression specialists cluster in Seoul, São Paulo, and Seattle, anchoring regional platform development. These talent concentrations shape where latency-critical data centers deploy and which regulatory frameworks operators must navigate.
United States
FCC broadband labeling rules mandate transparent network requirement disclosures for prospective subscribers. Microsoft's Azure data centers in Virginia and Iowa sustain Xbox Cloud Gaming's domestic server mesh. Content creators in Austin and Los Angeles drive asymmetric upload bandwidth demand that rural last-mile deployments often fail to provision.
South Korea
Millimeter-wave spectrum allocation enables sub-20ms latency commitments for competitive gaming delivery. The Korea Communications Commission enforces telecommunications quality standards that directly affect cloud gaming SLAs. Seoul's Gangnam district hosts the densest concentration of professional e-sports training facilities and streaming production studios in Asia.
Brazil
Smartphone-first gaming populations in São Paulo and Rio de Janeiro outpace console household penetration. Municipal fiber backhaul investments position southeastern metros for cloud gaming expansion without traditional hardware ecosystems. ANVISA's data localization guidance shapes how platforms structure subscriber information storage for regional compliance.
Japan
Japan's Ministry of Internal Affairs and Communications enforces strict latency commitments that support pay-per-use streaming architectures. Tokyo's Akihabara district remains the commercial center for gaming culture and streaming hardware retail. Transaction-based service models achieve highest penetration here due to regulatory scaffolding around quality guarantees.
Germany
GDPR Article 17 compliance frameworks streamline cross-border subscriber migration between competing EU services. The Federal Network Agency monitors telecommunications infrastructure quality affecting cloud gaming reliability. Munich and Frankfurt host major AWS and Azure availability zones that reduce intercontinental latency for Central European users.
Game Streaming Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across infrastructure, content, and distribution layers. Platform control fragments between console manufacturers, cloud hyperscalers, and telecom operators seeking recurring subscriber revenue. Three archetypes dominate: ecosystem-integrated hardware vendors, hardware-agnostic streaming pure-plays, and social platforms with live streaming adjacencies. Competitive moves concentrate on exclusive content licensing and edge computing partnerships that compress latency.
Among ecosystem-integrated operators, Microsoft Corporation and Sony Group Corporation anchor their respective console-native streaming tiers through deep OS integration. NVIDIA Corporation occupies a distinct position as a hardware-agnostic pure-play, leveraging its GPU architecture across devices competitors cannot reach. Amazon.com, Inc. exemplifies the hyperscaler archetype, deploying its AWS backbone to sustain low-latency delivery across multiple continents without proprietary gaming hardware dependency.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Meta Platforms, Inc. |
| Microsoft Corporation |
| Sony Group Corporation |
| NVIDIA Corporation |
| Alphabet Inc. |
| Twitch |
| Huya Inc. |
| DouYu International Holdings Ltd. |
| Others |
Supply Flow & Price Mechanics
Subscriber preference for sub-20ms latency commitments in South Korea and Brazil is forcing platform operators to densify edge computing deployments, which concentrates infrastructure capex in fiber-rich metros and compresses margin structures for services unable to secure municipal backhaul partnerships.
Pricing Analysis
Bundled subscription tiers dominate revenue recognition while unbundled chapter-based access gains traction among Gen Z subscribers with fragmented session patterns. Three-tier pricing structure across premium, standard, and economy levels separates priority server queue placement from standard allocation and ad-supported entry tiers. Price differentiation stems from latency guarantees and resolution ceilings rather than content library depth. Pricing pressure stems from GPU allocation contract volatility with Taiwan Semiconductor Manufacturing capacity scheduling. Casual gamers in Brazil exhibit highest price sensitivity; competitive players in South Korea demonstrate lowest elasticity due to professional gaming career pathways.
Supply Chain Analysis
Reverse-logistics flows for datacenter GPU refurbishment and server decommissioning anchor circular economy initiatives at Microsoft Azure and Amazon AWS facilities. Hardware concentration centers on Taiwan, South Korea, and the United States for GPU silicon and server assembly. Component dependencies include HBM memory stacks from SK Hynix, custom ASICs from NVIDIA, and cooling systems from Japanese suppliers. Single-source vulnerability in TSMC's advanced node capacity creates supply chain risk for streaming hardware procurement. Distribution runs through hyperscaler-owned facilities and telecom operator edge nodes rather than traditional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where subscriber retention now depends on sub-50ms latency consistency rather than content volume, favoring platforms with captive cloud infrastructure over licensing-dependent competitors.
For Market Incumbents: Acquire municipal fiber backhaul partnerships in São Paulo and Jakarta to lock in latency advantages that pure-play streamers cannot replicate. Defend against hyperscaler encroachment by deepening Xbox ecosystem integration and securing exclusive first-party title pipelines. Prioritize AV1 codec migration to cut bandwidth costs and extend service to legacy Smart TV hardware without parallel encoding overhead. For New Entrants and Emerging Players: Rural United States content creators represent an underserved buyer archetype with asymmetric upload bandwidth needs that incumbent platforms fail to provision. White-space targets include Indonesia's smartphone-first gaming population lacking domestic cloud infrastructure and India's PLI scheme-incentivized server assembly ecosystem. A direct-to-creator revenue share model bypassing traditional platform intermediation offers viable go-to-market positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with hardware-agnostic streaming pure-plays with GPU architecture licensing leverage across device categories. Long-term viability favors operators with vertical integration into silicon design and hyperscaler-scale datacenter footprints. Monitor 5G millimeter-wave spectrum allocation decisions in target markets as inflection indicators for competitive latency positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Partnership | Municipal fiber deployments in São Paulo and Rio de Janeiro reduce last-mile latency for competitive gaming delivery. |
| Codec Migration Investment | AV1 hardware decode adoption across MediaTek and Qualcomm chipsets cuts platform bandwidth requirements by half. |
| Exclusive Content Licensing | First-party AAA titles anchor Xbox Cloud Gaming differentiation against hardware-agnostic competitors. |
| AI Upscaling Integration | Server-side neural inference enables premium visual quality on mid-tier mobile chipsets without discrete GPU allocation. |
| Regulatory Compliance Framework | GDPR Article 17 data portability and EU Digital Services Act algorithmic transparency mandates reshape platform architecture. |
Methodological Framework
Bottom-up subscriber modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with platform engineering leads, content licensing executives, telecom infrastructure planners, and competitive gaming league operators combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie mobile engagement data, and national spectrum allocation records. Triangulation across these sources ensures convergence between reported subscriber metrics and physical server deployment patterns.
Input-output matrices map encoding complexity by content type against regional bandwidth availability and device decode capabilities across the projection horizon. Segmentation dimensions include platform type, service model, content tier, and end-user archetype with regional regulatory cluster overlays. CAGRs derive from subscriber growth curves weighted by average revenue per account trajectories and infrastructure cost deflation assumptions. Forecast inputs incorporate 5G rollout schedules, GPU foundry capacity expansion timelines, and data localization mandate enforcement patterns.
Underlying measurement precision varies by segment; e-sports concurrent viewership and subscription tier breakdowns carry tighter precision than ad-supported freemium conversion rates. Forecasts reflect assumptions around network latency improvement trajectories and content licensing cost inflation. Practitioners should monitor spectrum auction outcomes, foundry capacity allocation announcements, and cross-border data flow regulatory developments for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Media Streaming Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
United States OTT Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market
Video Streaming (OTT) Services
Streaming Services Market