
 Animation, VFX & Game Market | 2026-2036
Animation, VFX & Game Market Size, Share, and Industry Trends Forecast 2026-2036
Animation, VFX & Game Market Insights
The EU AI Act is restructuring compliance obligations for studios deploying generative algorithms in character animation and environmental design. Sony leverages proprietary motion capture stages across Tokyo and Culver City to sustain premium content pipelines. Tencent anchors its dominance through backward integration into cloud gaming infrastructure spanning Shenzhen and Singapore. Framestore specializes in photorealistic creature work for streaming franchises, differentiating on technical craft rather than volume scale.
Animation, VFX & Game production encompasses the creation of moving imagery and interactive software through digital rendering, motion capture acquisition, and real-time engine processing, serving entertainment, education, and commercial visualization industries. Rendering Software and Game Engines form the technical backbone, with Unreal Engine and proprietary toolchains displacing legacy compositing workflows in high-budget productions. Film Production and Interactive Media represent the dominant application channels, though margin pools increasingly concentrate in live-service game ecosystems and episodic streaming content where recurring revenue models outperform theatrical release economics.
The Federal Communications Commission shapes content distribution standards for interactive media in the United States, while China's National Radio and Television Administration enforces approval protocols for imported game titles and animated series. Japan's Ministry of Economy, Trade and Industry promotes digital content exports through JIS-aligned production quality benchmarks. Stakeholders must monitor divergent regulatory trajectories for AI-generated assets, as fragmented compliance architectures across North America, Europe, and Asia-Pacific threaten to fragment cross-border content licensing and co-production financing structures.
Market Dynamics
Real-time rendering engines are compressing production timelines from months to weeks, forcing studios to restructure asset pipelines around live engine workflows rather than traditional offline compositing.
Growth Catalysts
- Cloud gaming infrastructure:Backward integration into distributed compute networks reduces latency for interactive streaming, expanding addressable audiences beyond console hardware limitations.
- EU AI Act:Content authentication mandates for generative tools create first-mover advantages for studios with compliant disclosure frameworks already operational.
- Live-service ecosystems:Episodic content models in interactive media generate recurring revenue pools that outperform theatrical release economics.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity constraints create input cost volatility for rendering hardware procurement.
- Technical debt in legacy pipelines:Proprietary toolchains built over decades resist migration to real-time engine architectures without complete workflow reconstruction.
- Cross-border licensing friction:Fragmented compliance architectures across North American, European, and Asian regulators threaten co-production financing structures.
Strategic Opportunities
- India's production services sector:Underpenetrated VFX labor pools in Mumbai and Hyderabad offer cost arbitrage for mid-budget streaming content.
- Spatial computing convergence:Unreal Engine and neural rendering pipelines merging for immersive headset deployments create new content format demand.
- Japan's digital content export incentives:METI-aligned production quality benchmarks subsidize localization costs for anime distribution into Southeast Asian markets.
Industry Challenges
- Real-time technical artist scarcity:Talent capable of bridging traditional cinematography with engine-native lighting workflows commands premium compensation that compresses project margins.
- Generative asset provenance:IP disputes over training data ownership for character animation models create legal exposure throughout distribution chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animation, VFX & Game Market |
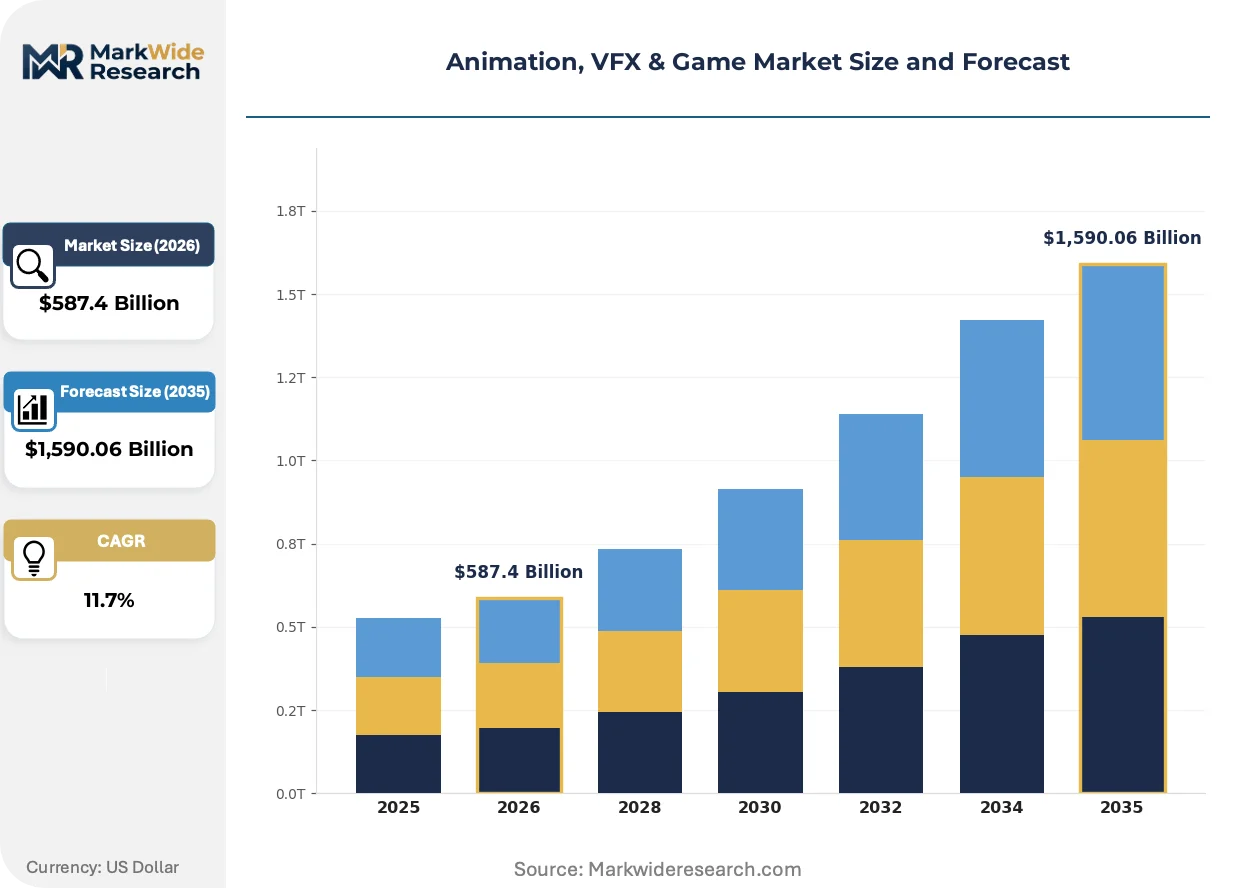
| Market Size in 2026 | $587.4 Billion |
| Market Size in 2035 | $1,590.06 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Animation, 3D Animation, Visual Effects, Game Development Technology: Rendering Software, Game Engines, Motion Capture, Compositing Tools Application: Film Production, Television, Advertising, Interactive Media End User: Studios, Independent Artists, Game Developers, Educational Institutions |
| Companies Covered | Tencent, Sony, Activision Blizzard, Microsoft, Nintendo, Netease, Walt Disney Animation Studios, Warner Bros, Framestore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animation, VFX & Game Market Trends and Innovations
Neural rendering and AI-assisted motion synthesis are collapsing traditional production hierarchies, redistributing creative control from post-production specialists to pre-visualization generalists.
Neural radiance fields (NeRF) and Gaussian splatting techniques are rewriting environmental capture economics. Indie studios and mid-tier streaming producers now achieve photorealistic location replication without physical set construction. The structural consequence compresses location scouting budgets into software licensing fees.
The EU AI Act's transparency obligations for synthetic media are restructuring disclosure protocols across European production houses. Studios must embed provenance metadata into generative character assets prior to distribution. Interactive media publishers with cross-border licensing operations face the steepest compliance reconstruction timelines.
Consumption patterns in interactive media are fragmenting around platform-exclusive content libraries. Gamers now maintain multiple subscription tiers rather than purchasing perpetual licenses. This behavioral shift concentrates most visibly in the United States, where California-based production clusters anchor the largest concentration of live-service development talent.
Animation, VFX & Game Market Segmentation
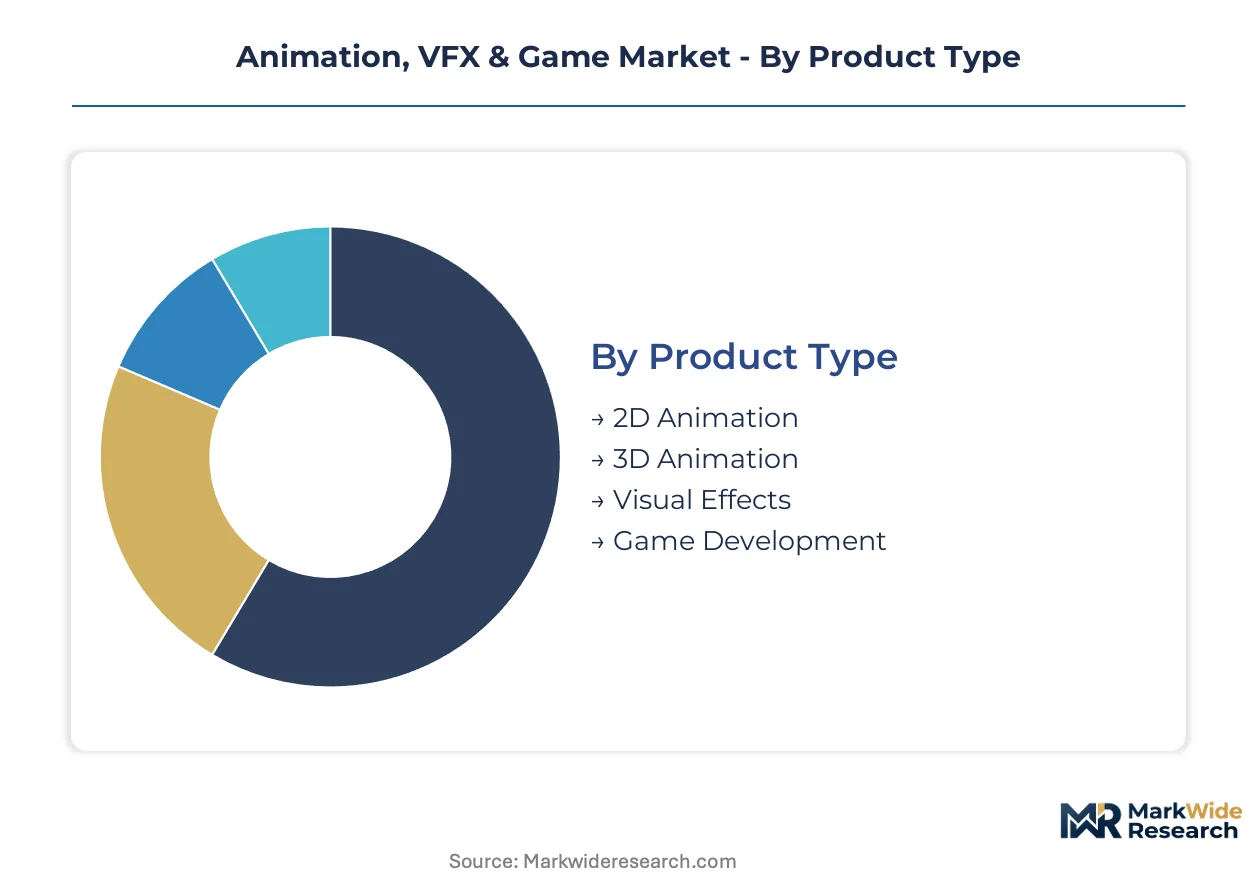
Production pipelines in animation, VFX, and interactive media fragment across multiple technical and commercial dimensions. Capital allocation decisions vary dramatically by segment, with real-time engine infrastructure demanding fundamentally different investment profiles than legacy compositing workflows.
Product Type:
Capital intensity concentrates in segments requiring dedicated render farms and proprietary toolchains, with 3D animation and game development commanding the largest upfront infrastructure commitments.
- 3D Animation:Character rigging, procedural simulation, and volumetric lighting pipelines require sustained compute investments. Major studios in California and Tokyo deploy petabyte-scale storage arrays for asset versioning. Real-time engine adoption is compressing traditional rendering timelines from weeks to days.
- Game Development:Live-service architectures demand continuous content delivery infrastructure with 24/7 operational support. Cloud gaming integration in Shenzhen and Singapore is expanding addressable audiences beyond console hardware constraints.
- 2D Animation:Vector-based workflows and limited animation techniques reduce hardware requirements. Japanese studios leverage METI export incentives for Southeast Asian distribution.
- Visual Effects:Photorealistic creature work and destruction simulation require specialized solver licenses. Framestore and similar houses differentiate on technical craft rather than volume scale.
Most installed capacity flows through 3D Animation. Expansion is steepest in Game Development.
Technology:
Procurement patterns reveal a structural shift from perpetual licenses toward subscription-based engine access and cloud-rendered compute cycles.
- Game Engines:Unreal Engine and proprietary real-time architectures displace offline compositing in high-budget productions. Unity and Epic licensing models now dominate pre-visualization through final pixel workflows across Culver City and London facilities.
- Rendering Software:GPU-accelerated path tracing and neural denoising reduce iteration cycles. Foundry Nuke and Autodesk Arnold maintain entrenched positions in feature film finishing pipelines despite engine-native competition.
- Motion Capture:Optical and inertial systems capture performance data for character animation. Sony operates dedicated stages in Tokyo and Los Angeles for premium content acquisition.
- Compositing Tools:Layer-based integration of CG elements with live-action plates remains essential for VFX finishing. Legacy node-based workflows resist migration to engine-native lighting without complete pipeline reconstruction.
Licensing revenue concentrates in Game Engines. Technical artist scarcity is most acute in Motion Capture integration.
Application:
Margin pools redistribute toward recurring revenue models, with episodic streaming and live-service ecosystems outperforming theatrical release economics.
- Interactive Media:Subscription-based access and in-game economies generate sustained revenue streams. California-based development clusters anchor the largest concentration of live-service talent for platform-exclusive content libraries.
- Film Production:Franchise tentpoles and streaming originals drive VFX volume. EU AI Act transparency obligations for synthetic media are restructuring disclosure protocols across European production houses.
- Television:Episodic schedules demand rapid turnaround pipelines. Mumbai and Hyderabad service providers offer cost arbitrage for mid-budget streaming content.
- Advertising:Commercial spots and branded content require accelerated delivery timelines. Real-time rendering enables same-day creative iteration for campaign launches.
Recurring revenue models dominate Interactive Media. Production volume is expanding most quickly in Television episodic content.
End User:
Customer sophistication spans from enterprise-scale facilities with captive render infrastructure to individual creators reliant on cloud-based subscription tiers.
- Studios:Integrated production houses maintain proprietary pipelines across animation, VFX, and interactive divisions. Tencent anchors dominance through backward integration into cloud gaming infrastructure spanning Shenzhen and Singapore.
- Game Developers:Specialized interactive media publishers range from AAA franchises to indie studios. Cross-border licensing operations face steepest compliance reconstruction timelines under fragmented regulatory architectures.
- Independent Artists:Freelance animators and VFX generalists access engine capabilities through affordable subscription tiers. Neural radiance field techniques now enable photorealistic environmental capture without physical set construction.
- Educational Institutions:University programs and vocational schools train emerging technical artists. Curriculum lag behind industry engine adoption creates persistent skills gaps in real-time pipeline expertise.
Capital deployment concentrates in Studios. Talent formation is climbing the fastest in Educational Institutions adapting curricula to engine-native workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hollywood's studio system established the foundational infrastructure for modern animation and visual effects production during the mid-20th century. Digital toolchains later migrated to specialized clusters across multiple continents. Contemporary production gravity now distributes across five dominant national markets with distinct regulatory and talent architectures.
United States
California-based production clusters anchor the largest concentration of VFX and live-service development talent worldwide. The Federal Communications Commission shapes content distribution standards for interactive media while state tax incentives sustain facility operations in Los Angeles and San Francisco. Sony operates dedicated motion capture stages in Culver City alongside Epic Games' engine development headquarters in North Carolina.
Japan
Tokyo and Osaka metropolitan areas host the world's most vertically integrated anime production ecosystems with century-old studio networks. The Ministry of Economy, Trade and Industry promotes digital content exports through JIS-aligned production quality benchmarks subsidizing localization costs. Nintendo and Sony maintain captive animation pipelines in Kyoto and Tokyo for franchise content.
China
Shenzhen and Beijing clusters drive cloud gaming infrastructure investment and mobile-first interactive media development. The National Radio and Television Administration enforces approval protocols for imported game titles and animated series entering domestic distribution. Tencent anchors backward integration into distributed compute networks spanning Shenzhen and Singapore data centers.
United Kingdom
London facilities specialize in photorealistic creature work and high-end streaming franchise VFX for international clients. The EU AI Act's transparency obligations for synthetic media restructure disclosure protocols across British production houses maintaining European licensing operations. Framestore and similar houses differentiate on technical craft from Soho-based facilities.
India
Mumbai and Hyderabad service providers offer cost arbitrage for mid-budget streaming content and episodic television VFX. The country's national media regulator oversees content classification while state-level IT policies incentivize animation park development. Educational institutions in Bangalore and Pune adapt curricula to engine-native workflows, expanding technical artist formation pipelines.
Animation, VFX & Game Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical craft differentiation and proprietary infrastructure ownership. The vendor base concentrates around integrated conglomerates with captive distribution platforms, mid-tier specialists with singular technical excellence, and emerging cloud-native developers with engine-first architectures. Competitive positioning hardens through backward integration into rendering infrastructure and exclusive IP licensing arrangements.
Among Asia-Pacific-based conglomerates, Tencent and Sony exemplify platform-integrated archetypes with captive cloud and hardware ecosystems. Framestore represents the specialist tier with concentrated technical craft in photorealistic creature work. These three occupy positions across the margin spectrum, with conglomerates capturing recurring revenue pools and specialists commanding premium project fees.
| Leading Market Players |
|---|
| Tencent |
| Sony |
| Activision Blizzard |
| Microsoft |
| Nintendo |
| Netease |
| Walt Disney Animation Studios |
| Warner Bros |
| Framestore |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists in European VFX services have consolidated fragmented production houses across London and Paris, tightening pricing discipline through captive talent pools while forcing independent studios toward project-based rate competition. This ownership concentration feeds directly into supply behavior, as consolidated entities negotiate volume discounts on render farm capacity and motion capture stage access that independents cannot match.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates production services, separating Framestore-tier photorealistic creature work from mid-budget streaming VFX and offshore episodic animation. Price differentiation hinges on technical artist certification depth and geographic delivery cost, with California-based commands exceeding Mumbai rates by substantial multiples. Cost compression in mid-tier episodic content is intensifying because streaming platforms consolidate vendor panels. Indie game developers exhibit highest price sensitivity, while AAA live-service publishers absorb premium engine licensing without margin hesitation.
Supply Chain Analysis
Technical artist scarcity across Taiwan, South Korea, and Japan constrains foundry capacity expansion for GPU-dependent rendering pipelines. Input dependencies center on TSMC-fabricated accelerators, proprietary motion capture sensor arrays, and cloud compute cycles from Shenzhen and Singapore data centers. Single-source vulnerability in Taiwan-based semiconductor manufacturing threatens hardware procurement timelines. Distribution runs through direct licensing from Epic Games and Unity Technologies, with enterprise support tiers commanding substantial premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Animation, VFX & Game Market reads as a late-cycle quality story, with demand shifting decisively toward premium specifications as streaming platforms and live-service publishers prioritize technical craft differentiation over volume scale.
For Market Incumbents: Lock in exclusive IP licensing arrangements with streaming platforms before generative tools commoditize mid-tier environmental design. Secure captive cloud rendering infrastructure through backward integration into distributed compute networks, insulating margin pressure from GPU supply volatility. The EU AI Act's provenance mandates threaten uncompliant competitors with reconstruction costs. For New Entrants and Emerging Players: Enter via India's underpenetrated technical artist formation pipeline, where Bangalore and Pune educational institutions produce engine-native talent faster than curriculum adaptation in Western markets. Target episodic television VFX for mid-budget streaming content, where Mumbai and Hyderabad service providers currently dominate but quality tier gaps persist. Pursue white-label neural rendering tool development for indie game studios seeking photorealistic environmental capture without physical production. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier specialists with singular technical excellence in creature work or real-time engine integration, as conglomerate premiums concentrate in platform-integrated players. Long-term viability favors studios with compliant disclosure frameworks already operational under EU AI Act transparency obligations. Watch for inflection in cross-border co-production financing structures, where fragmented regulatory architectures may force consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Engine Migration | Unreal Engine adoption compresses rendering timelines from weeks to days across Culver City facilities. |
| Cloud Gaming Infrastructure Buildout | Tencent's Shenzhen-Singapore data center network reduces latency for interactive streaming beyond console constraints. |
| AI Provenance Compliance Investment | EU AI Act disclosure frameworks create first-mover advantages for European production houses. |
| Technical Artist Formation Partnership | Educational institutions in Bangalore and Pune expand curriculum alignment with engine-native workflows. |
| Neural Rendering Capability Acquisition | NeRF and Gaussian splatting techniques enable photorealistic location replication without physical set construction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with VFX studio heads, game engine product managers, streaming platform content executives, and technical artist training directors with secondary validation from SEC filings of Epic Games and Unity Technologies, EMA regulatory guidance on synthetic media disclosure, and customs data on GPU import flows. Bottom-up project pipeline tracking and top-down platform revenue analysis were triangulated against regional production cluster surveys.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-acceleration demand patterns. The analytical framework modeled segmentation across product type, technology stack, application channel, and end-user sophistication, with CAGRs derived from rolling average growth rate calibration against capital deployment cycles in render infrastructure. Industry-specific inputs included live-service content release cadences and streaming platform VFX budget allocations.
The model holds under stable regulatory enforcement timelines and uninterrupted semiconductor supply; deviation in Taiwan foundry capacity constraints or EU AI Act implementation severity would shift growth trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Puzzle Video Game Market
Gaming
Gaming Peripheral Market
Gaming
Social Gaming Market
Gaming
North America Gaming Market
Gaming
Europe Gaming Peripherals Market
Gaming
LAMEA Gaming Posters Market
Gaming
Chinese Gaming Industry Market
Gaming
Gaming Hardware Market
Gaming
Flat Gaming Monitors Market
Gaming
VR Gaming Accessories Market
Gaming
Global Esports Market
Gaming
China in-Game Advertising Market
Gaming
Africa Gaming Market
Gaming
Global Tarot Cards Market
Gaming
AAA Games Market
Gaming
Virtual Sports Market