
 India Smart TV and OTT Market | 2026-2036
India Smart TV and OTT Market Size, Share, and Industry Trends Forecast 2026-2036
India Smart TV and OTT Market Foresight
The Telecom Regulatory Authority of India's evolving OTT consultation framework is rebalancing compliance burdens for streaming platforms entering the Indian market. Samsung anchors its position through in-house display manufacturing and retail channel density across metro corridors. Xiaomi competes on cost-engineered LED smart television portfolios priced for mass-market penetration. VU Technologies specializes in India-centric feature sets and localized assembly operations that sustain margin resilience against import-dependent rivals.
India Smart TV and OTT denotes internet-connected television hardware paired with over-the-top streaming services delivered via broadband without traditional broadcast infrastructure. Smart televisions integrate ARM-based processors, minimum 2GB RAM, and Android or proprietary operating systems enabling application ecosystems for video-on-demand consumption. LED product type holds volume leadership due to cost accessibility for first-time upgraders from conventional CRT and basic LCD sets. Subscription service type captures recurring revenue pools as Disney+ Hotstar, JioCinema, and Amazon Prime Video build annual plans. Ad-supported service type is expanding fastest among price-sensitive users in smaller cities where willingness to pay remains constrained.
BIS certification mandates for electronic goods ensure safety and electromagnetic compatibility standards for all smart televisions sold domestically. The Ministry of Information and Broadcasting's content code and TRAI's net neutrality provisions shape how OTT platforms structure data delivery and regional language obligations. Stakeholders must monitor how the proposed Digital India Act intersects with existing IT Rules to determine content moderation liability and platform licensing requirements.
Market Dynamics
TRAI's OTT consultation framework is compressing compliance timelines for streaming platforms while BIS certification mandates for smart television hardware reshape manufacturing footprints across domestic assembly operations.
Growth Catalysts
- PLI Scheme for Electronics Manufacturing:Production-linked incentives for large-scale electronics manufacturing are attracting component suppliers to set up display and semiconductor packaging facilities in India.
- Broadband Infrastructure Expansion:Fiber-to-the-home deployments by Reliance Jio and Bharti Airtel in tier-two cities are creating addressable bases for connected television ecosystems.
- Regional Content Investment:Streaming platforms are commissioning Tamil, Telugu, and Marathi original programming that drives hardware upgrades in Maharashtra, Karnataka, and Tamil Nadu.
Market Restraints
- Display Panel Import Dependency:Open-cell LED panels from China and Taiwan constitute the dominant input cost, exposing assemblers to currency volatility and shipping disruptions.
- Content Regulation Uncertainty:The proposed Digital India Act intersects with existing IT Rules to create overlapping compliance obligations for platform content moderation.
- Price Sensitivity Ceiling:Mass-market willingness to pay remains constrained below 25,000 rupees, compressing margin pools for feature-rich product tiers.
Strategic Opportunities
- Ad-Supported Service Expansion:AVOD models targeting price-sensitive users in smaller cities represent unmonetized inventory pools for regional advertisers.
- Local Assembly Scale-Up:VU Technologies and Dixon Technologies are expanding captive manufacturing to qualify for PLI incentives and reduce import duty exposure.
- Voice Interface Localization:Hindi and regional language voice search integration creates differentiation for India-centric feature sets against global platform defaults.
Industry Challenges
- Software-Hardware Integration Complexity:Android TV certification timelines and security patch obligations strain engineering resources of domestic assemblers.
- Retailer Margin Compression:E-commerce platform commissions and offline distributor markups fragment working capital across multi-channel fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Smart TV and OTT Market |
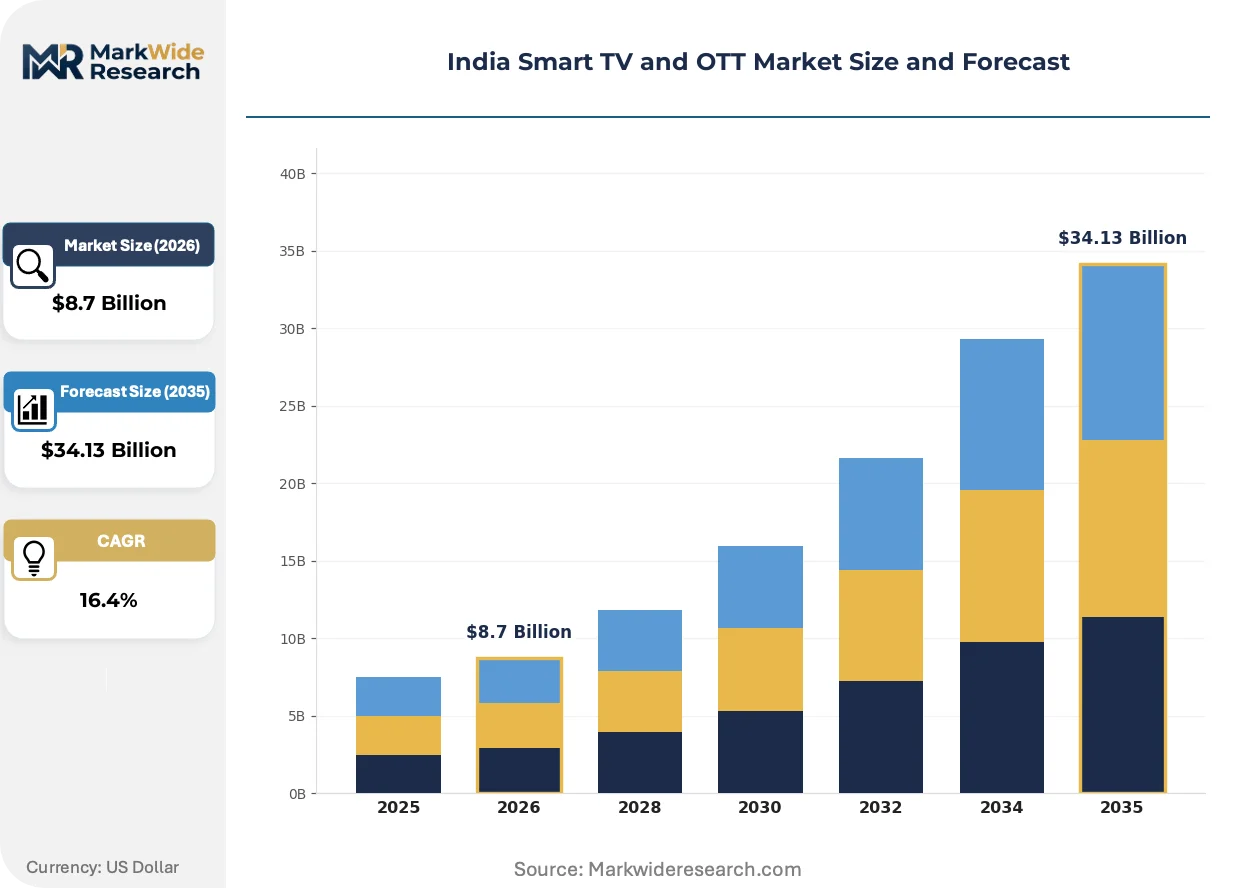
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, Smart Projectors Service Type: Subscription, Transactional, Ad-supported, Hybrid End User: Households, Educational Institutions, Hospitality, Enterprises Content Type: Movies, Series, Sports, Documentaries |
| Companies Covered | TCL Technology, VU Technologies, Samsung, Dixon, OnePlus, LG Electronics, Sony Corporation, Jio, Xiaomi Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Smart TV and OTT Market Shifts & Advancements
Artificial intelligence recommendation engines and voice-native interfaces are restructuring how viewers discover content, while regulatory pressure on data localization accelerates platform infrastructure investments.
AI-powered content discovery is automating programming decisions for streaming services. Disney+ Hotstar and JioCinema deploy machine learning models that surface regional language titles based on viewing history and time-of-day patterns. This capability is automating the editorial curation function that previously required large human programming teams, compressing content acquisition costs while improving engagement metrics for India-specific catalogs.
TRAI's evolving OTT consultation framework is mandating transparency in data usage disclosures and net neutrality compliance for video delivery. The regulation requires platforms to report peak-hour traffic management practices and maintain interconnection agreements with internet service providers. Streaming services are responding by expanding edge caching infrastructure within Indian data centers to reduce latency penalties and regulatory scrutiny on cross-border data flows.
Subscription fatigue among urban households is fragmenting wallet share across multiple platforms. Consumers in Mumbai, Delhi, and Bangalore are rotating monthly subscriptions rather than maintaining annual commitments, forcing platforms to unbundle sports and entertainment tiers. This behavior is most visible in cricket-heavy programming windows where JioCinema's IPL rights have disrupted Disney+ Hotstar's historical dominance in annual plan retention.
India Smart TV and OTT Market Segmentation
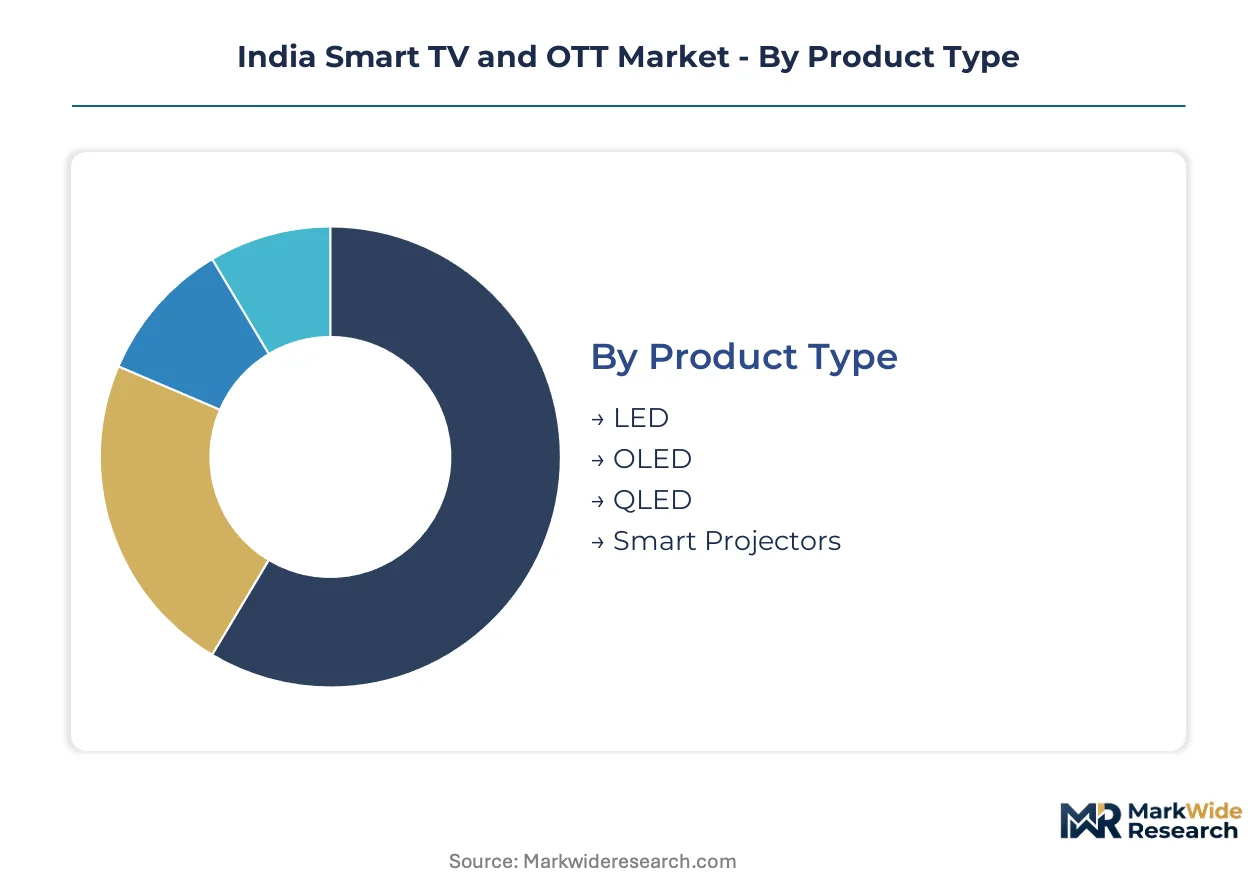
Segmentation in India's connected television ecosystem reveals how hardware specifications, monetization models, and viewing contexts fragment addressable demand. Understanding these divisions clarifies where BIS certification burdens, PLI incentive eligibility, and regional content investments concentrate commercial leverage.
Product Type:
Buyers in this category differentiate by display technology cost tiers and upgrade pathways from legacy CRT sets.
- LED:Open-cell panels assembled domestically under PLI schemes power volume leadership. Demand concentrates in tier-two Maharashtra and Karnataka cities where first-time smart TV buyers prioritize sub-25,000 rupee price bands and BIS-certified safety compliance over premium specifications.
- OLED:Self-illuminating pixel arrays deliver contrast ratios exceeding conventional backlit systems. Mumbai and Delhi high-income households drive adoption as secondary bedroom or gaming-dedicated screens, constrained by import duties on Korean-manufactured panels.
- QLED:Quantum dot-enhanced LED systems from Samsung and TCL bridge premium aspirations with localized assembly feasibility.
- Smart Projectors:Portable connected display devices target rental housing and temporary viewing setups in Bangalore's tech workforce corridors.
LED leads volumes today; smart projectors are gaining share fastest among urban millennials in transient housing arrangements.
Service Type:
Recurring revenue stability versus upfront monetization tolerance separates subscribers across India's payment infrastructure maturity gradient.
- Subscription:Annual and monthly plans from Disney+ Hotstar, JioCinema, and Amazon Prime Video lock in predictable ARPU. Annual commitment concentration runs deepest in Tamil Nadu and Karnataka where broadband penetration supports household-level account sharing rather than mobile-only consumption.
- Ad-supported:AVOD inventory pools monetize price-sensitive users unwilling to commit recurring payments. Tier-two city expansion in Uttar Pradesh and Rajasthan drives inventory growth as regional advertisers target vernacular content adjacencies.
- Transactional:Pay-per-view movie rentals capture occasional viewers seeking theatrical window releases without platform subscriptions.
- Hybrid:Freemium tiers combining limited ad-supported catalogs with premium upsell pathways balance reach and conversion in competitive acquisition markets.
Subscription models dominate revenue today; ad-supported services are expanding most quickly in smaller cities where UPI penetration outpaces credit card adoption.
End User:
Deployment scale and content curation control distinguish institutional procurement from household discretionary purchases.
- Households:Individual family units drive replacement cycles from basic LCD to connected ecosystems. Maharashtra, Karnataka, and Tamil Nadu account for disproportionate volume given fiber-to-the-home density and regional original programming investment by streaming platforms.
- Educational Institutions:Schools and universities deploy smart displays for hybrid learning infrastructure. Government procurement under Digital India education schemes concentrates demand in state capitals with established vendor empanelment processes.
- Hospitality:Hotels and serviced apartments integrate casting-enabled televisions as standard amenity offerings. Business travel recovery in Bangalore and Hyderabad corporate corridors sustains refresh demand.
- Enterprises:Corporate meeting rooms and retail signage applications require commercial-grade panel durability and centralized device management platforms.
Households lead volumes today; educational institutions are climbing the fastest amid post-pandemic hybrid learning standardization.
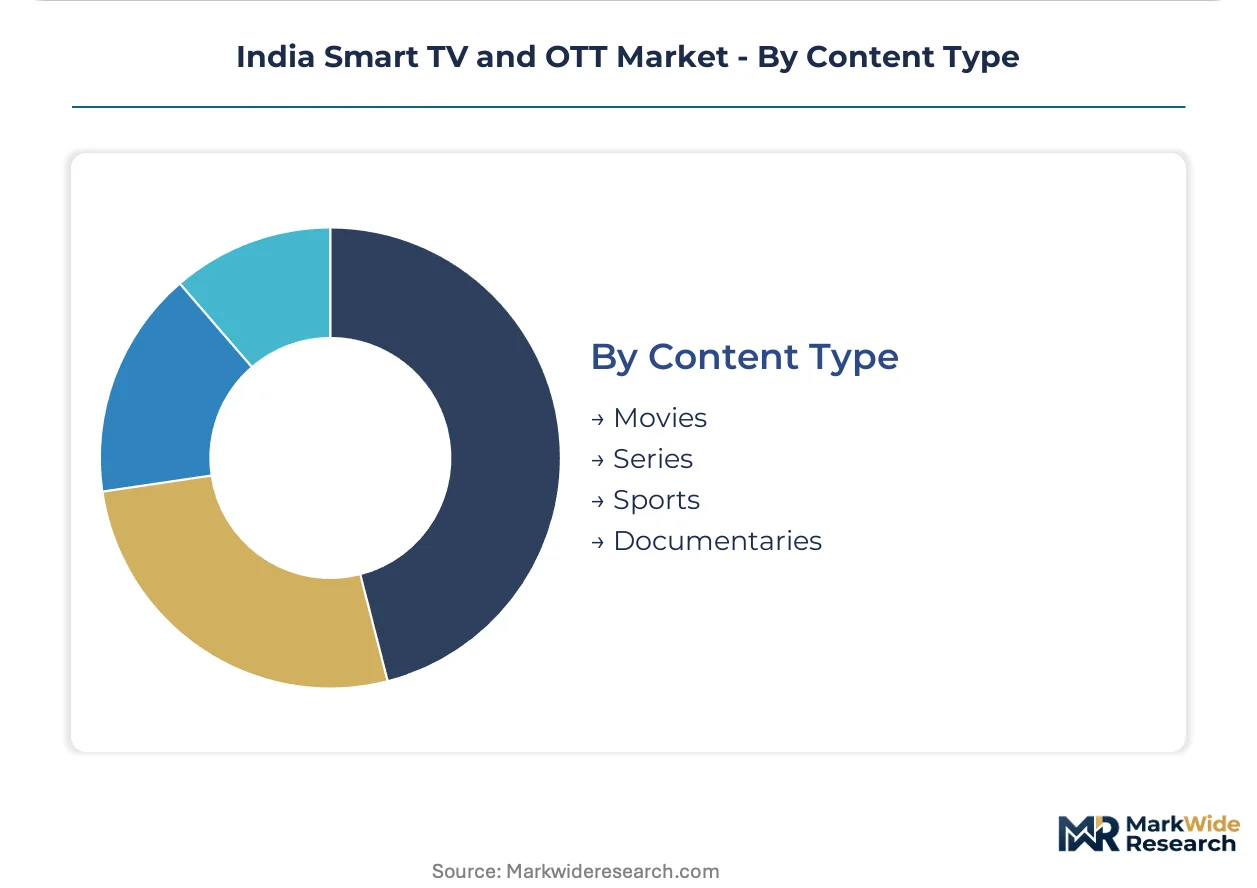
Content Type:
Production budget intensity and live event scheduling economics determine platform licensing strategies and hardware upgrade triggers.
- Sports:Cricket IPL and international tournament rights command premium subscription pricing and 4K upgrade incentives. JioCinema's IPL acquisition disrupted Disney+ Hotstar's historical dominance in annual plan retention across cricket-intensive markets.
- Series:Multi-episode regional language originals in Tamil, Telugu, and Marathi drive sustained engagement and reduce churn in Maharashtra and Karnataka. Machine learning recommendation engines now automate programming decisions that previously required large human curation teams.
- Movies:Theatrical window streaming releases balance pay-per-view transactional revenue against subscription catalog depth.
- Documentaries:Niche factual programming attracts educated urban demographics in Delhi and Mumbai with lower production cost thresholds.
Series leads consumption hours today; sports commands the steepest expansion trajectory in subscription pricing power and 4K hardware upgrade correlation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's connected television ecosystem concentrates where engineering talent pools, semiconductor packaging facilities, and streaming platform headquarters cluster together.
Maharashtra
Mumbai anchors India's streaming platform headquarters density with Disney+ Hotstar and JioCinema operations centers. The state's electronics manufacturing policy under the Maharashtra Industrial Development Corporation offers capital subsidies for display assembly facilities. Pune's automotive electronics corridor is repurposing precision manufacturing capabilities toward smart TV component fabrication.
Karnataka
Bangalore's software engineering base powers AI recommendation engine development for regional content platforms. The Karnataka Electronics System Design and Manufacturing policy provides reimbursement for BIS certification costs incurred by domestic assemblers. Whitefield and Electronic City host captive R&D centers where voice interface localization for Kannada and Tulu languages proceeds.
Tamil Nadu
Chennai's port infrastructure handles open-cell LED panel imports from Taiwan and Korea for final assembly operations. The state's Electronics Manufacturing Policy offers 25% capital subsidy for component manufacturing investments exceeding 100 crore rupees. Sriperumbudur's electronics hardware park hosts Dixon Technologies and Foxconn facilities producing smart televisions for pan-India distribution.
Telangana
Hyderabad's film industry infrastructure supports Telugu original content production driving hardware upgrades in Deccan markets. The Telangana State Industrial Project Approval and Self-Certification System accelerates environmental clearances for electronics manufacturing units. Genome Valley's adjacent logistics corridors enable just-in-time component delivery to assembly plants in Medchal and Patancheru.
Delhi-NCR
Gurgaon's consumer electronics retail density concentrates premium QLED and OLED demand from high-income households. The Delhi government's electric vehicle and electronics cluster policy offers land allotment preferences for display technology investments. Noida's manufacturing belt hosts VU Technologies assembly operations serving northern India distribution networks.
India Smart TV and OTT Market Competitive Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive display manufacturing capabilities. Samsung and LG Electronics anchor premium positioning through in-house panel production and retail channel density across metro corridors. Xiaomi and TCL Technology compete on cost-engineered portfolios priced for mass-market penetration. Two dominant competitive moves define current positioning: local assembly scale-up to qualify for PLI incentives, and voice interface localization for Hindi and regional language differentiation.
Among Korea-based electronics conglomerates, Samsung and LG Electronics exemplify the vertically integrated archetype with captive supply chains for display components. VU Technologies occupies a position within the India-centric specialist tier, leveraging localized assembly operations and regional feature customization. Xiaomi Corporation represents the cost-engineered volume play, competing through aggressive pricing in sub-25,000 rupee bands where mass-market willingness to pay concentrates.
| Leading Market Players |
|---|
| TCL Technology |
| VU Technologies |
| Samsung |
| Dixon |
| OnePlus |
| LG Electronics |
| Sony Corporation |
| Jio |
| Xiaomi Corporation |
| Others |
Supply & Pricing Matrix
Mass-market households in tier-two cities anchor India's smart TV demand, compressing pricing into sub-25,000 rupee bands where BIS-certified LED panels dominate procurement decisions. This buyer concentration forces assemblers to absorb currency volatility on imported open-cell displays while streaming platforms unbundle sports tiers to capture rotating subscriptions.
Pricing Analysis
Bundled annual subscriptions from Disney+ Hotstar and JioCinema compete against unbundled monthly rotations as consumers fragment wallet share across multiple platforms. Price differentiation rests on certification tier—BIS-mandated safety standards separate compliant domestic assemblers from grey-market imports—and regional language voice interface customization. Pricing pressure intensifies as Xiaomi and TCL compress hardware margins in entry-level LED segments. Mass-market buyers in Uttar Pradesh and Rajasthan exhibit highest price sensitivity, while Mumbai and Delhi high-income households tolerate premium QLED and OLED tiers.
Supply Chain Analysis
Workforce availability in Tamil Nadu's Sriperumbudur electronics corridor and Karnataka's Bangalore tech belt concentrates final assembly operations for pan-India distribution. Open-cell LED panels draw from China and Taiwan, semiconductor packaging rests on Korean and Japanese component flows, and ARM-based processors hinge on Taiwanese foundry output. Single-source vulnerability on display panel imports exposes assemblers to shipping disruptions and rupee depreciation. Distribution runs through Reliance Digital and Croma retail networks alongside Amazon and Flipkart e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
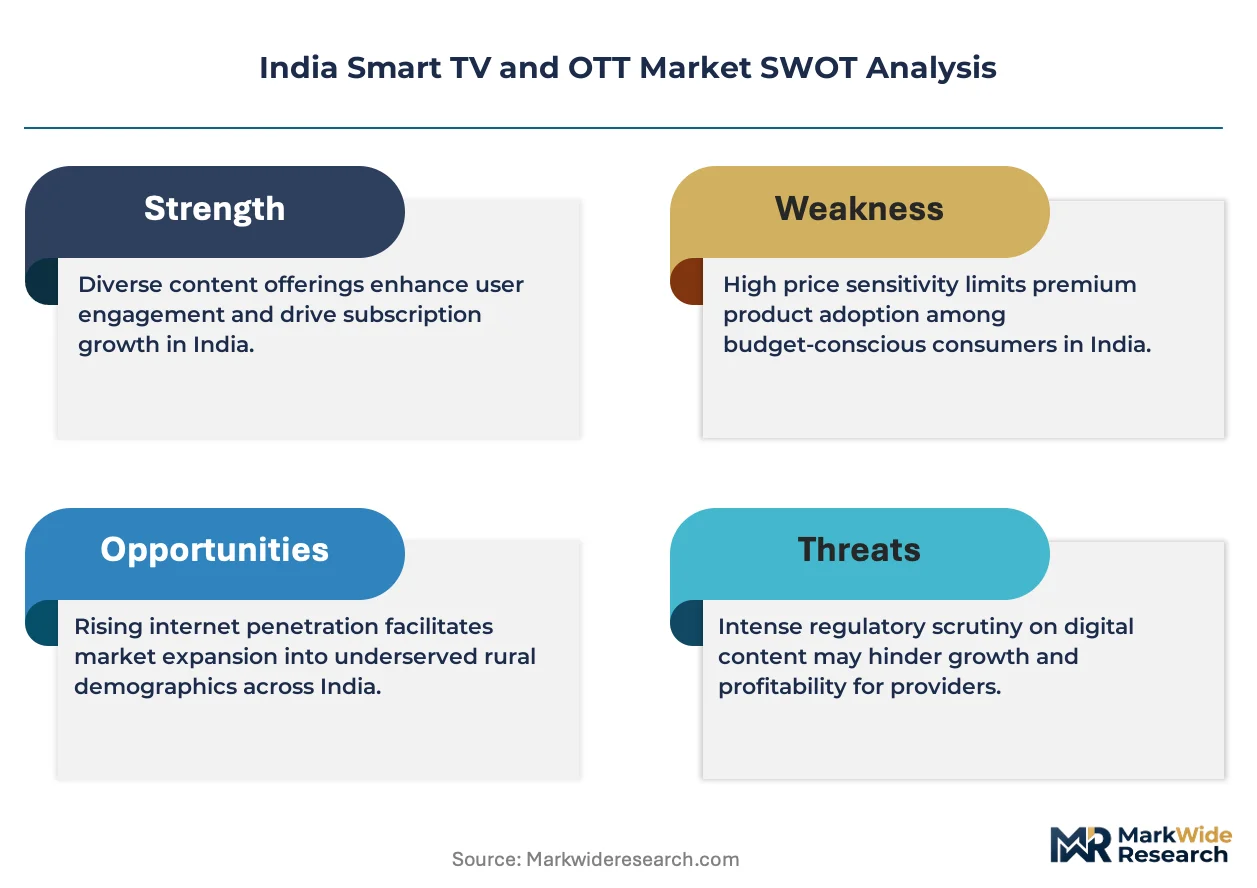
India's smart TV and OTT market functions as a stable compounder where broadband infrastructure expansion and regional content investment sustain replacement cycles across tier-two cities.
For Market Incumbents: Deploy PLI scheme qualification as a defensive moat by expanding captive assembly in Tamil Nadu and Uttar Pradesh to lock in component sourcing advantages against import-dependent rivals. Deepen voice interface localization for Marathi and Kannada to differentiate against global platform defaults. Monitor JioCinema's sports rights acquisitions as a churn threat to annual subscription retention. For New Entrants and Emerging Players: The 15,000-25,000 rupee price-point gap between premium Samsung QLED and economy Xiaomi LED offers white-space targeting for mid-tier regional assemblers. Focus initial penetration on Maharashtra's tier-two cities where fiber-to-the-home density supports connected ecosystem upgrades. Pursue co-branding partnerships with regional streaming platforms commissioning Marathi and Telugu originals. For Investors and Strategic Acquirers: Domestic electronics conglomerates with display assembly capabilities are the most active acquirers in this space, seeking voice-AI engineering teams and regional content catalogs. Long-term viability hinges on PLI incentive continuity and BIS certification enforcement. Watch TRAI's Digital India Act implementation as a regulatory inflection signal on content moderation liability and platform licensing costs.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Scale-Up | Captures PLI incentives and reduces import duty exposure for Dixon and VU Technologies. |
| Voice Interface Localization | Enables Hindi and Kannada differentiation against Android TV global defaults. |
| Regional Content Partnership | Locks in exclusive Marathi and Telugu programming for Maharashtra and Telangana penetration. |
| Edge Caching Infrastructure | Reduces latency penalties under TRAI's net neutrality disclosure requirements. |
| Ad-Supported Tier Expansion | Monetizes price-sensitive users in Uttar Pradesh where UPI penetration outpaces credit cards. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Tamil Nadu, and Telangana, with primary inputs from each state's electronics manufacturing clusters and streaming platform headquarters. The research combines interviews with smart TV product managers, OTT platform content acquisition leads, BIS certification consultants, and retail channel partners at Croma and Reliance Digital. Secondary validation draws from TRAI consultation papers, Ministry of Information and Broadcasting content codes, PLI scheme disclosures, and customs data on open-cell panel imports. Bottom-up assembly volume estimates triangulate against top-down broadband household penetration projections.
Granularity-level modeling disaggregates hardware by display technology tier, streaming service by monetization model, and geography by state-level fiber-to-the-home deployment. The analytical framework projects replacement cycles from basic LCD to connected ecosystems across the projection horizon. CAGRs derive from segment-level growth rate blending. Forecast inputs include Reliance Jio and Bharti Airtel capex disclosures on fiber expansion and streaming platform regional content commissioning announcements.
Caveats apply where TRAI's Digital India Act finalization, rupee volatility against the dollar, or display panel supply disruptions from Taiwan could materially shift the outlook. Forecasts reflect assumptions on PLI scheme continuity and BIS enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Video Servers Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Streaming Media Services Market