
 Streaming Spending Market | 2026-2036
Streaming Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Streaming Spending Market Insights
The shift from single-studio licensing to multi-source content aggregation is pivoting how platforms build libraries. Netflix sustains its lead through original production scale across multiple continents. Disney+ anchors family-oriented IP ecosystems that reduce churn in saturated markets. Amazon Prime Video leverages e-commerce bundling to subsidize streaming acquisition costs in price-sensitive regions.
Streaming spending encompasses consumer and enterprise expenditures on digital video content delivery, encompassing bandwidth allocation, cloud encoding infrastructure, and rights acquisition budgets measured in per-subscriber acquisition cost and average revenue per user. The primary commercial purpose centers on converting viewer attention into recurring revenue through retention-optimized content portfolios. Subscription Services command the largest revenue pool due to predictable cash flow and lower ad-tech overhead. Ad-Supported Services are expanding fastest among cost-conscious demographics, though Hybrid Models capture the highest lifetime value by blending both revenue streams.
The FCC enforces net neutrality principles that shape broadband pricing structures affecting streaming delivery economics, while the EU's GDPR imposes data governance costs on personalized recommendation engines. India's TRAI consultation on OTT regulation threatens to introduce licensing fees that would reshape platform pricing across South Asia. Stakeholders must monitor regulatory fragmentation between data-privacy regimes and content-localization mandates as the decisive variable for cross-border expansion economics.
Market Dynamics
Content aggregation economics are forcing platforms to abandon single-studio exclusivity in favor of multi-source licensing portfolios that dilute per-title acquisition costs while expanding catalog breadth.
Growth Catalysts
- India's TRAI OTT consultation:The proposed pricing transparency framework is accelerating subscriber onboarding by reducing friction in plan comparison across competing platforms.
- Cloud encoding infrastructure:Distributed processing nodes are collapsing transcoding timelines from hours to minutes, enabling same-day global release windows for original productions.
- Southeast Asia mobile-first consumption:Smartphone-dominant viewing patterns are concentrating platform investment in vertical video formats and low-bandwidth adaptive streaming protocols.
Market Restraints
- Bandwidth cost volatility:Peering agreement disputes between last-mile ISPs and content delivery networks are injecting unpredictability into streaming delivery economics.
- Content licensing concentration:Sports rights aggregation among a handful of legacy broadcasters is constraining platform access to live event inventory in key markets.
- GDPR compliance overhead:The EU's data governance requirements are imposing fixed costs on recommendation engine development that scale poorly for smaller platforms.
Strategic Opportunities
- Regional language originals in India:Young adult demographics are expanding paid subscriptions for Marathi, Tamil, and Malayalam content that commands lower production cost per hour than Hindi or English equivalents.
- Ad-tech convergence with e-commerce:Shoppable video integrations are opening direct-response revenue streams that bypass traditional subscription fatigue barriers.
- Hybrid monetization models:Tiered service structures blending subscription and advertising are capturing higher lifetime value than pure-play alternatives in price-sensitive segments.
Industry Challenges
- Localization talent scarcity:Subtitling and dubbing pipelines face bottlenecks in sourcing qualified linguists for less-common language pairs, delaying international release schedules.
- Legacy content management system integration:Platforms acquiring regional libraries must reconcile disparate metadata standards that fragment search and recommendation coherence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Streaming Spending Market |
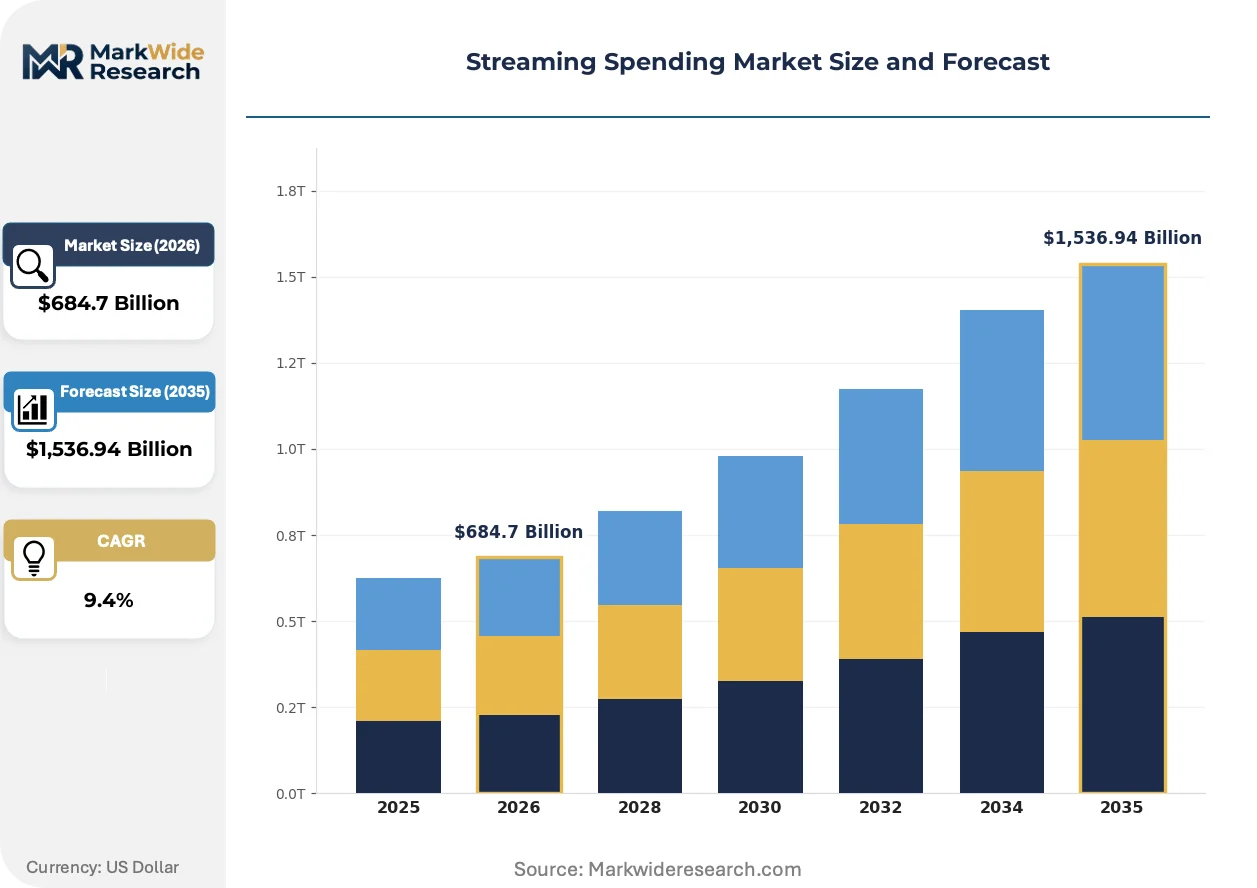
| Market Size in 2026 | $684.7 Billion |
| Market Size in 2035 | $1,536.94 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription Services, Ad-Supported Services, Hybrid Models, Pay-Per-View Content Genre: Drama, Comedy, Documentary, Action Device Type: Smart TVs, Mobile Devices, Laptops, Game Consoles Pricing Model: Freemium, Tiered Pricing, Single Purchase, Bundle Offers |
| Companies Covered | Netflix, Amazon Prime Video, Disney+, YouTube, Hulu, HBO Max, Paramount+, Apple TV+, Peacock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Streaming Spending Market Trends and Innovations
Edge computing architectures and federated content delivery are redistributing infrastructure control away from centralized hyperscalers toward geographically distributed processing nodes.
Federated learning for recommendation engines is decentralizing model training across device endpoints without centralizing raw viewing data. Platforms in Germany and France are piloting this approach to preempt GDPR scrutiny while preserving personalization quality. The structural consequence is a compression in cloud compute expenditure for inference-heavy workloads.
The EU's Digital Services Act is imposing algorithmic transparency mandates on content ranking systems. Platforms must now disclose parameters governing recommended video surfacing, forcing engineering teams to document decision logic previously treated as proprietary. French and German regulators are already requesting audits of trending content amplification mechanisms.
Subscription fatigue is driving ad-supported tier migration among cost-conscious households. Southeast Asian platforms are responding with six-second unskippable formats that preserve engagement metrics while delivering advertiser reach. India's young adult demographic shows the highest propensity for this switch, particularly in tier-two cities where disposable income constraints intersect with high mobile data consumption.
Streaming Spending Market Segmentation
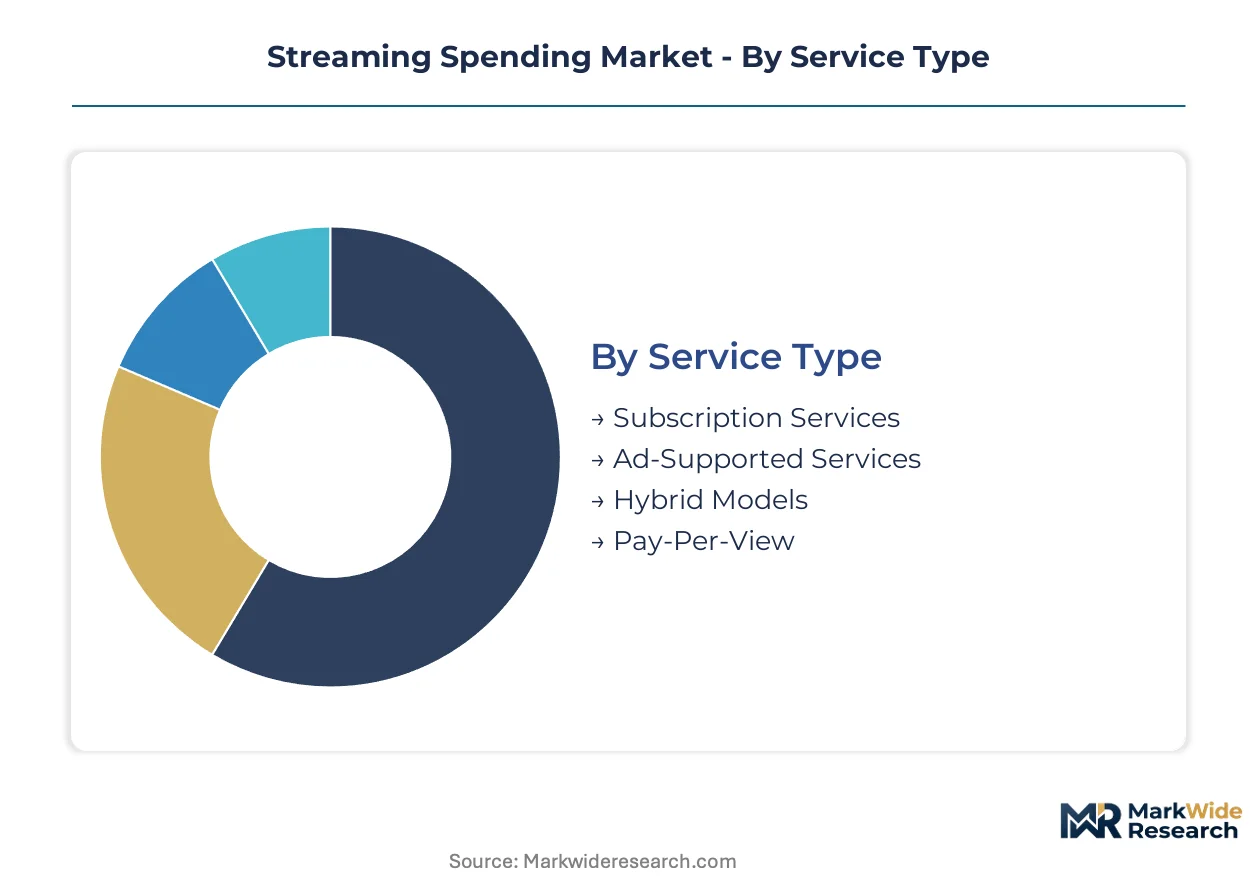
Streaming spending fragments across four distinct category systems that determine how platforms capture viewer attention and convert it into recurring revenue. Each segmentation axis reveals divergent cost structures, retention mechanics, and geographic concentration patterns that shape competitive strategy.
Service Type:
Standardization dominates at the infrastructure layer while customization proliferates at the monetization interface across this spectrum.
- Subscription Services:Predictable monthly billing structures anchor cash flow planning for platforms operating across multiple continents. India's young adult demographic in tier-two cities drives expansion here, though TRAI pricing transparency mandates are compressing plan differentiation.
- Ad-Supported Services:Six-second unskippable formats preserve engagement metrics while delivering advertiser reach in Southeast Asian mobile-first markets. Cost-conscious households in India's regional language belts migrate here fastest as disposable income constraints intensify.
- Hybrid Models:Tiered structures blending subscription base with advertising overlays capture highest lifetime value in price-sensitive segments.
- Pay-Per-View:Event-driven purchases concentrate around live sports rights held by legacy broadcasters in constrained inventory markets.
Leading the category by volume: Subscription Services. Growing fastest: Ad-Supported Services.
Content Genre:
Production cost tiers and localization requirements segment this category from premium scripted through lower-cost unscripted formats.
- Drama:Serialized narrative formats command highest per-hour production investment and drive subscriber acquisition in saturated North American and Western European markets. Netflix's multi-continental original slate anchors competitive positioning here.
- Comedy:Shorter episode runtimes and lower location costs enable faster production cycles for regional language adaptations. Indian platforms expand Marathi and Tamil comedy originals to reduce cost-per-hour versus Hindi or English equivalents.
- Documentary:Lower production overhead attracts ad-supported platforms seeking catalog breadth without subscription-level investment.
- Action:Visual effects requirements concentrate production in markets with established post-production infrastructure.
Highest production investment: Drama. Steepest expansion trajectory: Comedy.
Device Type:
Screen size and bandwidth requirements create divergent technical specifications and content formatting demands.
- Smart TVs:Large-format viewing preserves premium subscription tiers and family co-viewing sessions that reduce churn. North American and Western European households maintain this as primary consumption endpoint.
- Mobile Devices:Vertical video formats and low-bandwidth adaptive streaming protocols dominate Southeast Asian platform investment. Smartphone-dominant viewing patterns in Indonesia, Philippines, and Vietnam concentrate subscriber acquisition spending.
- Laptops:Intermediate screen size supports multi-tasking consumption patterns among younger demographics.
- Game Consoles:Hardware-integrated streaming apps capture gaming-adjacent households with existing entertainment expenditure patterns.
Dominant by viewing hours: Smart TVs. Gaining share fastest: Mobile Devices.
Pricing Model:
Revenue predictability and customer acquisition friction vary across commitment structures from zero-entry through long-term contracts.
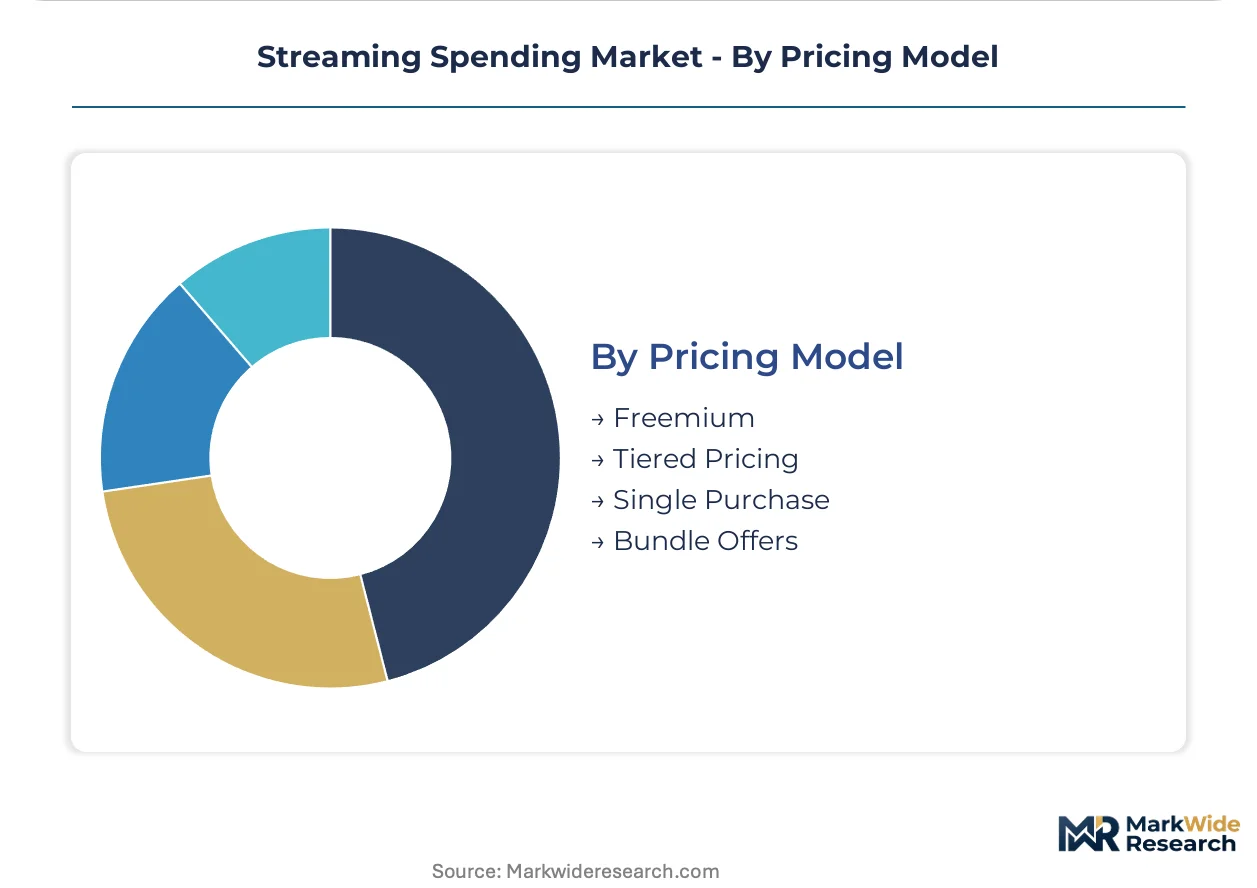
- Freemium:Zero-entry tiers convert to paid through content gating and feature restrictions. Southeast Asian platforms deploy this to overcome subscription fatigue in markets with high mobile data consumption but constrained disposable income.
- Tiered Pricing:Three-level structures separating premium, standard, and economy access enable price discrimination across income segments. India's TRAI consultation on pricing transparency accelerates plan comparison and reduces onboarding friction.
- Single Purchase:Transactional models concentrate around theatrical window content and live event access.
- Bundle Offers:E-commerce integration through Amazon Prime Video subsidizes streaming acquisition costs in price-sensitive regions.
Widest adoption: Tiered Pricing. Expanding most quickly: Freemium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Broadband infrastructure density and mobile data affordability anchor streaming spending concentration across distinct national markets. Regulatory frameworks governing content localization and pricing transparency reshape platform economics in each territory.
United States
Household broadband penetration and smart TV adoption sustain subscription service dominance. The FCC enforces net neutrality principles that shape peering agreements between ISPs and content delivery networks. Los Angeles and New York anchor original production clusters where Netflix and Disney+ operate soundstage facilities.
India
Young adult demographics in tier-two cities drive regional language original consumption for Marathi, Tamil, and Malayalam content. TRAI's OTT consultation framework imposes pricing transparency requirements that compress plan differentiation across competing platforms. Mumbai and Bengaluru concentrate post-production infrastructure and subtitling talent pipelines.
Germany
GDPR compliance costs burden personalized recommendation engine development for mid-sized platforms. The EU's Digital Services Act mandates algorithmic transparency for content ranking systems. Berlin hosts federated learning pilots that decentralize model training across device endpoints.
Brazil
Mobile-first viewing patterns concentrate subscriber acquisition investment in low-bandwidth adaptive streaming protocols. ANVISA regulates advertising standards for pharmaceutical and healthcare content in streaming environments. São Paulo anchors Portuguese-language original production facilities serving Latin American markets.
South Korea
High-speed fiber infrastructure supports 4K and 8K streaming adoption in urban households. The MFDS oversees content classification standards affecting platform catalog availability. Seoul's Gangnam district concentrates drama production studios that supply regional export demand.
Streaming Spending Market Competitive Landscape
Multi-source content aggregation dominates the current landscape as platforms abandon single-studio exclusivity. The vendor structure concentrates around three integrated conglomerates with diversified revenue streams, mid-sized regional specialists, and technology-anchored entrants leveraging existing customer bases. Strategic archetypes include IP-integrated entertainment conglomerates, e-commerce bundlers subsidizing streaming through retail economics, and hardware-ecosystem players converting device sales into service attachment. M&A activity and original production capacity expansion constitute the primary competitive moves reshaping market position.
Within the IP-integrated tier, Netflix and Disney+ exemplify divergent approaches to content portfolio construction. Netflix sustains multi-continental original production scale across drama, comedy, and documentary verticals. Disney+ anchors family-oriented intellectual property ecosystems that reduce churn in saturated North American and Western European markets. Amazon Prime Video occupies a distinct position leveraging e-commerce bundling to subsidize subscriber acquisition costs in price-sensitive regions including India and Southeast Asia.
| Leading Market Players |
|---|
| Netflix |
| Amazon Prime Video |
| Disney+ |
| YouTube |
| Hulu |
| HBO Max |
| Paramount+ |
| Apple TV+ |
| Peacock |
| Others |
Pricing and Supply Chain Analysis
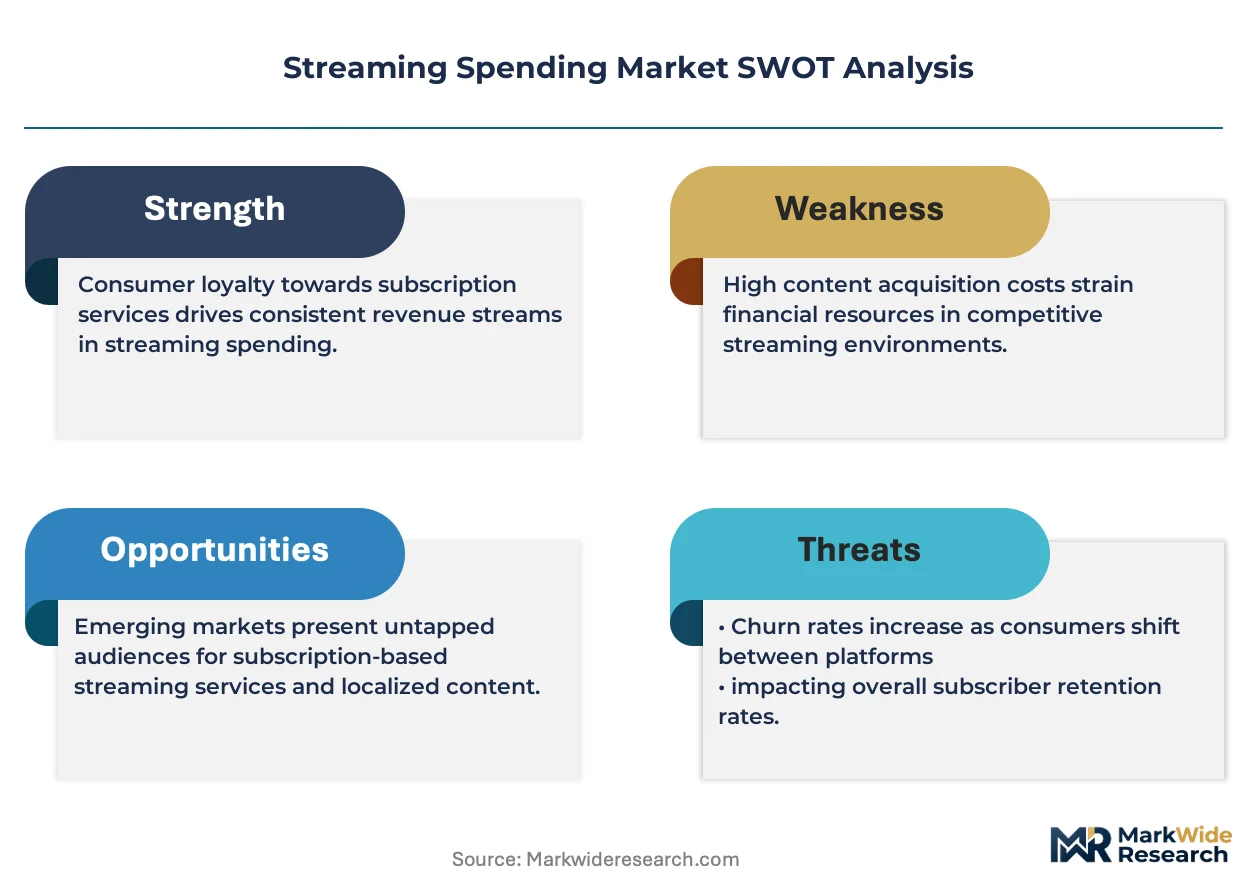
Subscription fatigue among cost-conscious households in Southeast Asia and India's tier-two cities is forcing platforms to unbundle premium features and compress plan tiers, which in turn accelerates investment in cloud encoding infrastructure to reduce per-stream delivery costs.
Pricing Analysis
Service-bundling configurations separate ad-supported tiers from premium subscription levels, with after-sales content access and offline download privileges as the primary unbundled differentiators. Price differentiation hinges on content resolution tiers and regional licensing breadth, with 4K streaming and multi-territory catalogs commanding premiums. Pricing pressure intensifies downward as India's TRAI transparency mandates compress plan differentiation across competing platforms. Ad-supported tiers attract the most price-sensitive segments in mobile-first Southeast Asian markets, while premium subscribers in North America and Western Europe show lowest sensitivity to incremental price increases.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud providers in the United States, Ireland, and Singapore for encoding and storage infrastructure. Raw material dependencies encompass bandwidth capacity from tier-1 ISPs, specialized GPU clusters for recommendation engine training, and licensed content libraries from consolidated studio aggregators. Supply chain risk centers on peering agreement disputes between last-mile providers and content delivery networks that inject unpredictability into delivery economics. Distribution runs through direct-to-consumer app stores and hardware-integrated preloads on smart TVs and mobile devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over original production capacity and proprietary IP catalogs determines pricing power and subscriber retention economics.
For Market Incumbents: Deploy exclusive original production pipelines across Marathi, Tamil, and Malayalam language markets to preempt regional specialist competition. Deepen backward integration into post-production infrastructure in Mumbai and Bengaluru to compress subtitling timelines and accelerate international release windows. Fortify against churn by anchoring family-oriented content ecosystems that reduce substitution elasticity in saturated North American and Western European households.
For New Entrants and Emerging Players: Capture underserved regional language comedy segments in India's tier-two cities where production cost-per-hour undercuts Hindi and English equivalents. Exploit white-space in shoppable video integrations that bypass subscription fatigue through direct-response e-commerce revenue streams. Pursue mobile-first go-to-market angles in Indonesia, Philippines, and Vietnam with vertical video formats and low-bandwidth adaptive streaming protocols.
For Investors and Strategic Acquirers: The window for entry favors platforms with federated learning capabilities that preempt GDPR scrutiny while preserving personalization quality. Long-term viability hinges on hybrid monetization architectures that blend subscription and advertising revenue streams. Monitor TRAI consultation outcomes as the decisive inflection signal for regulatory cost structures across South Asian expansion economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Original Production Scale-Up | Multi-continental soundstage investment secures content exclusivity against studio licensing concentration. |
| Regional Language Content Expansion | Marathi and Tamil originals reduce cost-per-hour while capturing underserved subscriber demographics in India. |
| Cloud Encoding Infrastructure Deployment | Distributed processing nodes collapse transcoding timelines from hours to minutes for same-day global releases. |
| Hybrid Monetization Tier Introduction | Blended subscription-advertising structures capture highest lifetime value in price-sensitive Southeast Asian segments. |
| Federated Learning Pilot Program | Decentralized recommendation training across German and French device endpoints preempts GDPR compliance scrutiny. |
Research Methodology
Document review covered SEC filings from streaming platforms, TRAI consultation papers, EU Digital Services Act implementation guidance, and hyperscaler capex disclosures, complemented by interviews with content acquisition executives, cloud infrastructure engineers, regional licensing directors, and mobile network operators. Primary fieldwork engaged platform strategy leads in Los Angeles, Mumbai, and Singapore alongside regulatory affairs specialists in Berlin and Brussels. Secondary validation drew from app store revenue estimates, broadband penetration databases, and content production cost surveys. Bottom-up subscriber projections and top-down advertising spend estimates were triangulated against infrastructure capacity expansion announcements.
Historical subscriber growth trajectories were cross-referenced against panel input from platform finance officers to calibrate acquisition cost assumptions across the projection horizon. The analytical framework modeled segmentation dimensions encompassing service type, content genre, device category, and regional regulatory cluster. CAGRs were derived from trend extrapolation moderated by saturation thresholds in mature markets and infrastructure buildout timelines in emerging territories. Forecast inputs incorporated mobile data affordability indices, smart TV adoption curves, and content localization pipeline capacity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to TRAI pricing mandate implementation, GDPR enforcement intensity, and peering agreement renegotiations between ISPs and content delivery networks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Media Streaming Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
Video Servers Market
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Indonesia OTT Market