
 Video Streaming Market | 2026-2036
Video Streaming Market Size, Share, and Industry Trends Forecast 2026-2036
Video Streaming Market Intelligence
Content distribution through exclusive licensing windows is fragmenting as studios reclaim intellectual property for proprietary platforms. Netflix leverages its global production infrastructure to sustain subscriber retention across multiple geographies. Amazon Prime Video anchors its streaming service within a broader Prime ecosystem, competing on bundled value rather than content volume alone.
Video streaming denotes the continuous transmission of compressed audiovisual data over internet protocol networks, typically employing adaptive bitrate algorithms ranging from 480p to 4K resolution to maintain playback quality across variable bandwidth conditions. The technology serves commercial entertainment delivery, enterprise communications, and educational content dissemination. Subscription models dominate revenue generation while ad-supported tiers capture price-sensitive demographics, and mobile phones have overtaken smart TVs as the primary consumption device in emerging markets where fixed broadband penetration remains limited.
The FCC in the United States enforces net neutrality principles that affect bandwidth prioritization for streaming services, while the EU's Digital Services Act imposes transparency requirements on recommendation algorithms and content moderation practices. India's TRAI mandates content certification and grievance redressal mechanisms for platforms operating within its jurisdiction. Stakeholders must monitor regulatory divergence across jurisdictions as compliance costs compound and data localization requirements reshape infrastructure deployment decisions.
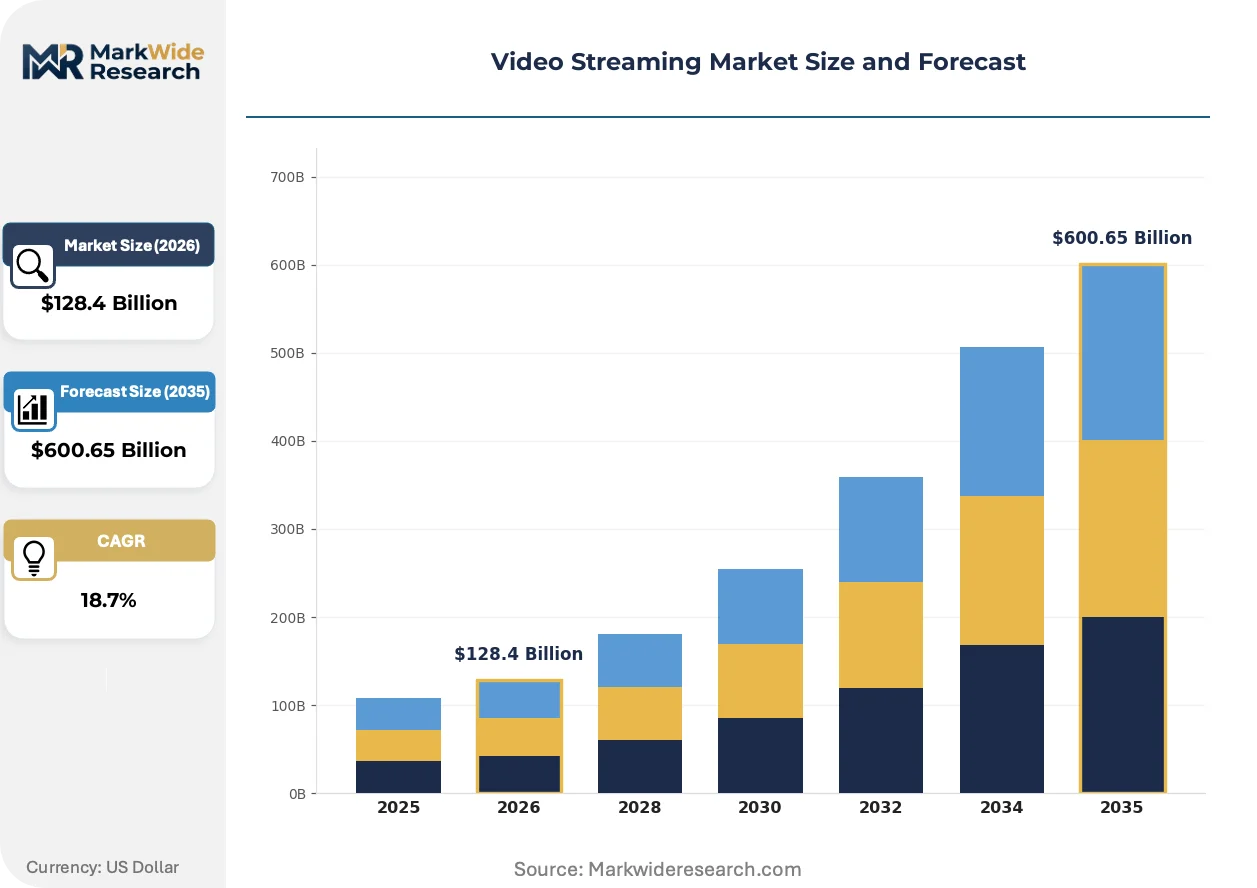
Market Dynamics
Studios are reclaiming intellectual property from licensing partners to populate proprietary direct-to-consumer platforms, compressing third-party content availability and forcing distributors toward original production investments.
Growth Catalysts
- Enterprise Learning Adoption:Corporate training departments in India are replacing classroom modules with on-demand video curricula, expanding addressable hours per subscriber.
- TRAI Content Certification:India's mandated grievance redressal mechanisms are accelerating platform localization investments that improve regional language catalog depth.
- Adaptive Bitrate Streaming:Compression algorithms now sustain 4K playback at 5 Mbps, enabling premium tier penetration in markets with constrained fixed broadband infrastructure.
Market Restraints
- Content Cost Inflation:Original production budgets for scripted drama series have tripled since 2019, compressing EBITDA margins for non-vertically integrated distributors.
- Net Neutrality Uncertainty:FCC bandwidth prioritization rules remain contested, exposing streaming services to potential throttling by last-mile internet service providers.
- Live Sports Fragmentation:Exclusive rights auctions are dispersing marquee events across dozens of platforms, diluting any single service's retention power.
Strategic Opportunities
- Brazil Urban Cord-Cutting:São Paulo and Rio de Janeiro middle-income households are abandoning pay-TV bundles faster than platforms can capture them with localized Portuguese originals.
- EU Algorithm Transparency:Digital Services Act disclosure requirements for recommendation engines create first-mover advantage for platforms investing in explainable AI systems.
- Mobile-First Emerging Markets:Smartphone penetration in Indonesia and Nigeria exceeds fixed broadband by 40 percentage points, favoring lightweight app experiences over smart TV apps.
Industry Challenges
- ML Engineer Scarcity:Personalized recommendation systems require scarce talent pools in computer vision and natural language processing, inflating compensation costs in Bangalore and Warsaw.
- Legacy System Integration:Established broadcasters migrating to streaming architectures face multi-year timelines to decouple from satellite transmission dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Streaming Market |
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $600.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Movies, TV Shows, Documentaries, Sports Delivery Model: Subscription, Ad-Supported, Pay-Per-View, Hybrid Device Type: Smart TVs, Mobile Phones, Tablets, Laptops Subscription Tier: Basic, Standard, Premium, Family |
| Companies Covered | Netflix, Amazon Prime Video, Disney+, YouTube, Apple TV+, Hulu, Max, Tencent Video, iQIYI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Streaming Market Strategic Shifts & Innovations
Cloud-native encoding pipelines and edge computing nodes are compressing content delivery latency, while regulatory pressure on algorithmic transparency is forcing investments in explainable recommendation architectures.
Serverless encoding architectures are virtualizing traditional hardware-bound transcoding farms into elastic cloud compute instances. Mid-tier platforms in Southeast Asia are adopting these systems to avoid capital-intensive on-premise infrastructure. This technology is virtualizing the cost structure of 4K HDR content preparation, enabling smaller catalogs to compete on technical quality.
The EU's Digital Services Act mandates public disclosure of content moderation criteria and recommendation system parameters. Platforms must now document how their algorithms rank and suggest audiovisual content to European users. French and German regulators are conducting the first compliance audits, forcing engineering teams to rebuild black-box ranking systems with auditable decision trails.
Subscription fatigue is compressing household willingness to maintain multiple concurrent streaming memberships. Brazilian and Mexican consumers are rotating between platforms monthly rather than stacking services, forcing distributors toward retention-focused content calendars rather than acquisition-driven premiere slates. This pattern is most visible in Latin American markets where credit card penetration supports frictionless cancellation workflows.
Video Streaming Market Segmentation
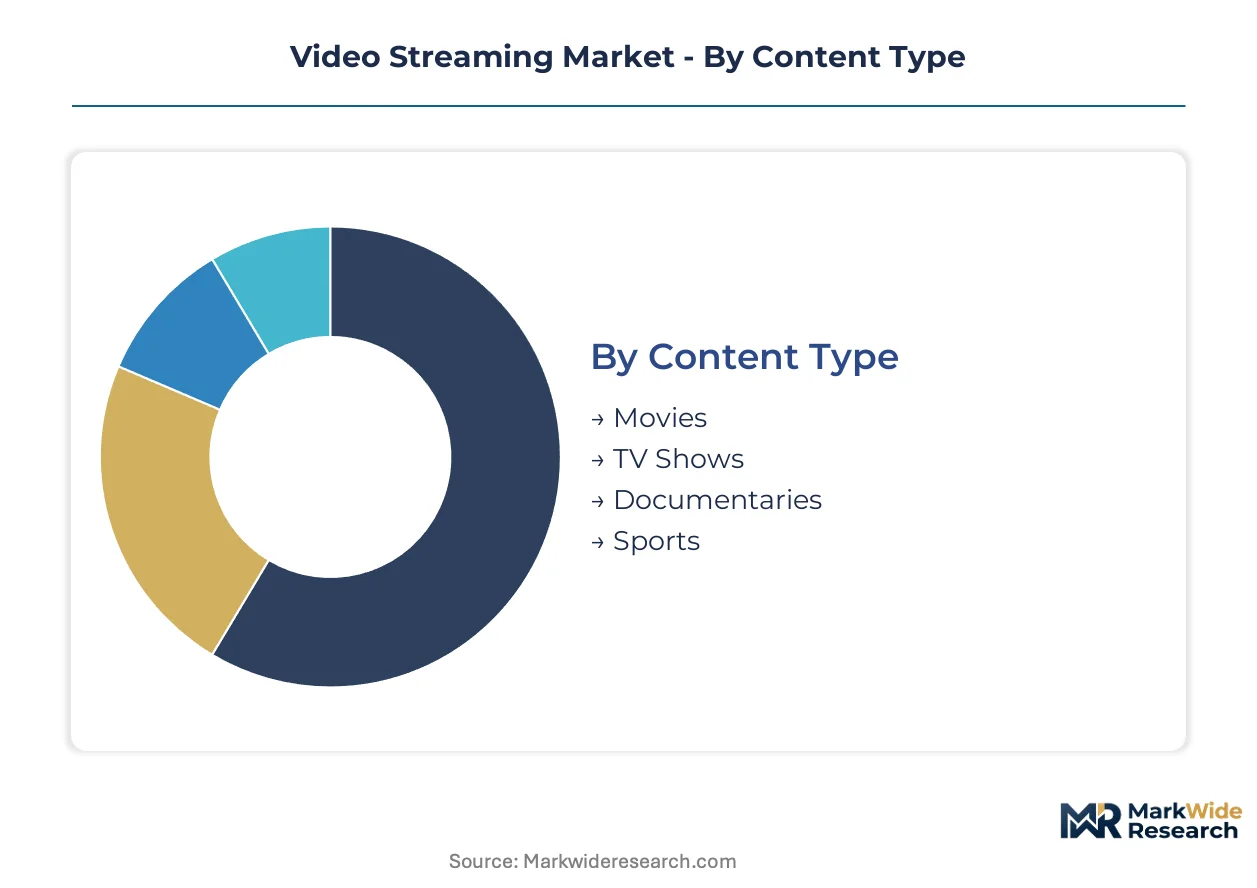
Video streaming platforms calibrate content libraries, monetization mechanics, and technical delivery around distinct consumption patterns. Segmentation reveals where infrastructure investments concentrate and which user cohorts drive marginal revenue per subscriber.
Content Type:
Mature formats dominate viewing hours while emerging categories reshape platform differentiation strategies.
- Movies:Theatrical window compression has collapsed from 90 days to 45 days, with studios releasing direct-to-streaming for mid-budget productions. India's multiplex-dense urban centers show strongest demand for day-and-date releases.
- TV Shows:Serialized drama series generate the highest completion rates and subscription retention, with binge-release models competing against weekly episode drops for sustained engagement. Brazil's São Paulo metropolitan area records above-average season completion rates.
- Documentaries:True crime and nature programming attracts older demographics with lower churn propensity.
- Sports:Live event rights command premium pricing and require specialized low-latency delivery infrastructure.
TV Shows handles the majority of throughput; Sports is the fastest mover on share.
Delivery Model:
Cost tier stratification separates subscription-dependent platforms from advertising-funded alternatives.
- Subscription:Recurring revenue models prioritize annual plans with 15-20% discounts, reducing monthly cancellation flexibility. India's TRAI-mandated grievance mechanisms have forced subscription platforms to improve refund processing speed.
- Ad-Supported:Lower price points capture price-sensitive households in Brazil's middle-income brackets, with ad load tolerance varying by content genre.
- Pay-Per-View:Event-based transactions concentrate around live sports and same-day theatrical releases.
- Hybrid:Tiered access combines ad-supported base tiers with premium upsells, maximizing addressable market coverage.
Subscription captures the largest revenue base; Ad-Supported is climbing the fastest as platforms pivot to capture churned subscribers.
Device Type:
Volume concentration shifts toward mobile-first consumption in bandwidth-constrained markets.
- Smart TVs:Large-screen viewing drives premium tier adoption and family account usage. Fixed broadband penetration in India's tier-1 cities enables 4K streaming on connected television sets.
- Mobile Phones:Smartphone penetration exceeds 80% in Indonesia and Nigeria, making handsets the primary consumption device where Wi-Fi infrastructure remains underdeveloped.
- Tablets:Commute and travel viewing favors portable screens with longer battery endurance.
- Laptops:Browser-based access serves enterprise learning deployments and shared household accounts.
Mobile Phones accounts for the greatest session volume; Smart TVs delivers the highest revenue per user.
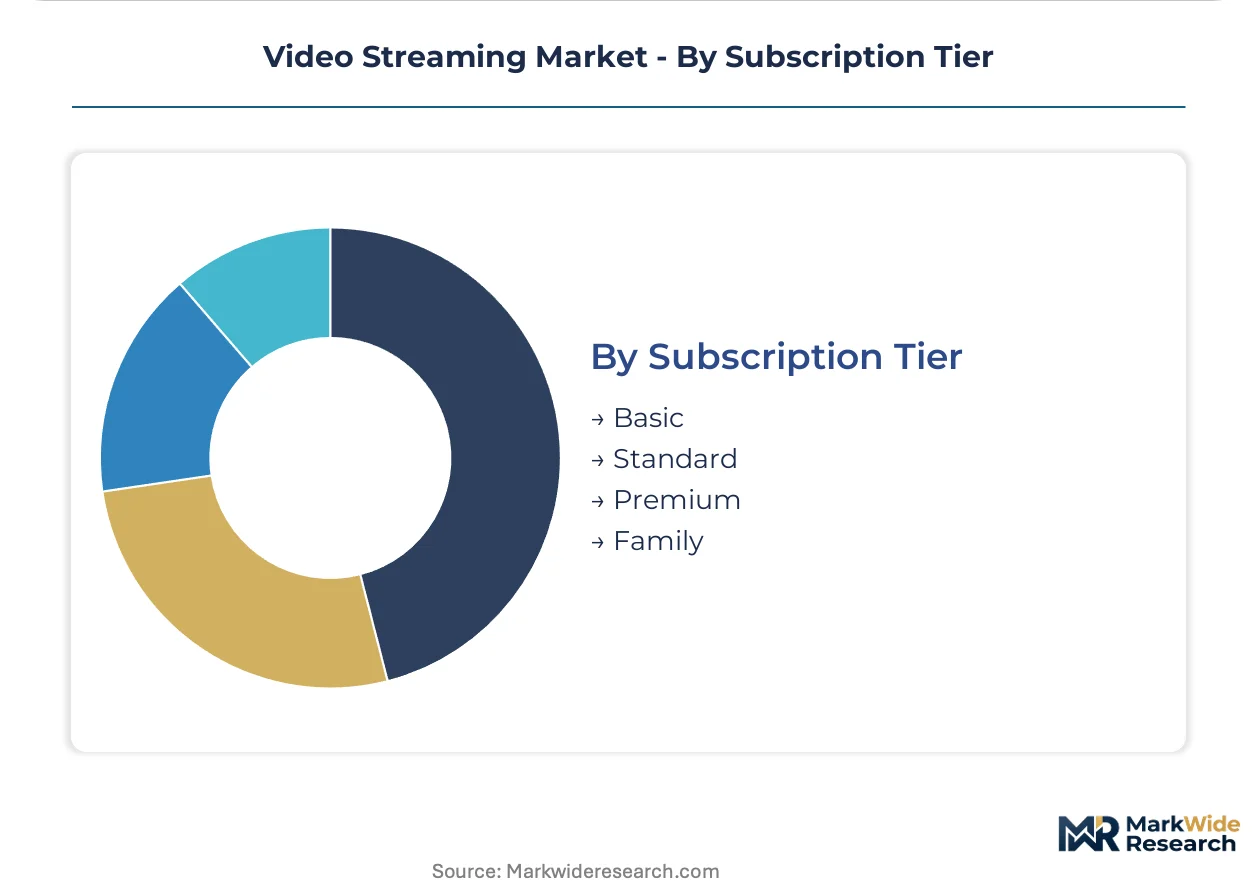
Subscription Tier:
Customer type differentiation separates individual subscribers from multi-user household plans.
- Basic:Single-screen, standard-definition plans target solo viewers with constrained budgets. Brazil's credit card-enabled cancellation workflows make this tier susceptible to monthly rotation behavior.
- Standard:HD streaming on two concurrent devices captures couple and small household configurations.
- Premium:4K HDR and four-screen access commands pricing multiples over basic tiers.
- Family:Expanded user profiles and parental controls address multi-generational household sharing patterns.
Standard tier maintains the largest installed base; Family plans are gaining share fastest as platforms crack down on password sharing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC governs bandwidth prioritization rules that directly shape streaming service delivery economics across the United States. Regulatory divergence between Washington, Brussels, and New Delhi forces platforms to maintain parallel compliance architectures. Infrastructure deployment decisions cluster around metropolitan density zones where fiber penetration enables 4K streaming at scale.
United States
Enterprise learning platforms and ad-supported tier expansion drive subscriber growth in secondary metro areas. The FCC's contested net neutrality framework exposes distributors to potential ISP throttling without guaranteed recourse. Atlanta and Austin host the fastest-growing data center clusters for edge-encoded content delivery.
India
Mobile-first consumption patterns dominate as smartphone penetration outpaces fixed broadband by substantial margins. TRAI mandates content certification and grievance redressal mechanisms that accelerate platform localization investments. Mumbai and Bangalore concentrate regional language production facilities serving tier-2 and tier-3 city demand.
Brazil
São Paulo and Rio de Janeiro middle-income households abandon pay-TV bundles faster than platforms capture them with Portuguese originals. ANVISA content classification requirements apply to health and wellness programming distributed through streaming channels. The southeastern corridor anchors subscription growth despite monthly rotation behavior enabled by frictionless credit card cancellation.
Germany
EU Digital Services Act transparency requirements for recommendation algorithms reshape engineering priorities for platforms operating across the single market. The KBA does not regulate streaming directly, but GDPR compliance costs compound with algorithmic audit obligations. Berlin and Munich host explainable AI development labs responding to regulatory pressure.
South Korea
5G network density enables ultra-low latency streaming that supports live sports and interactive content formats. The MFDS oversees health-related content classifications for wellness and medical programming distributed via OTT platforms. Seoul anchors original production investments targeting pan-Asian distribution rights.
Video Streaming Market Key Industry Players
Vertically integrated studios and technology-platform hybrids split the market into competing strategic camps. The vendor base concentrates around entities controlling both intellectual property libraries and distribution infrastructure. Three archetypes dominate: legacy studios reclaiming content for proprietary direct-to-consumer platforms, technology giants bundling streaming within broader ecosystem plays, and regional specialists optimizing for local language production. Competitive moves center on exclusive sports rights auctions and cloud-native encoding infrastructure deployment.
Within the technology-platform tier, Netflix and Amazon Prime Video occupy positions defined by global production infrastructure and bundled ecosystem value respectively. Disney+ exemplifies the studio-reclamation archetype through intellectual property consolidation for proprietary distribution. Tencent Video anchors the regional specialist model with concentration in Mandarin-language content and adjacent market expansion.
| Leading Market Players |
|---|
| Netflix |
| Amazon Prime Video |
| Disney+ |
| YouTube |
| Apple TV+ |
| Hulu |
| Max |
| Tencent Video |
| iQIYI |
| Others |
Cost & Logistics Intelligence
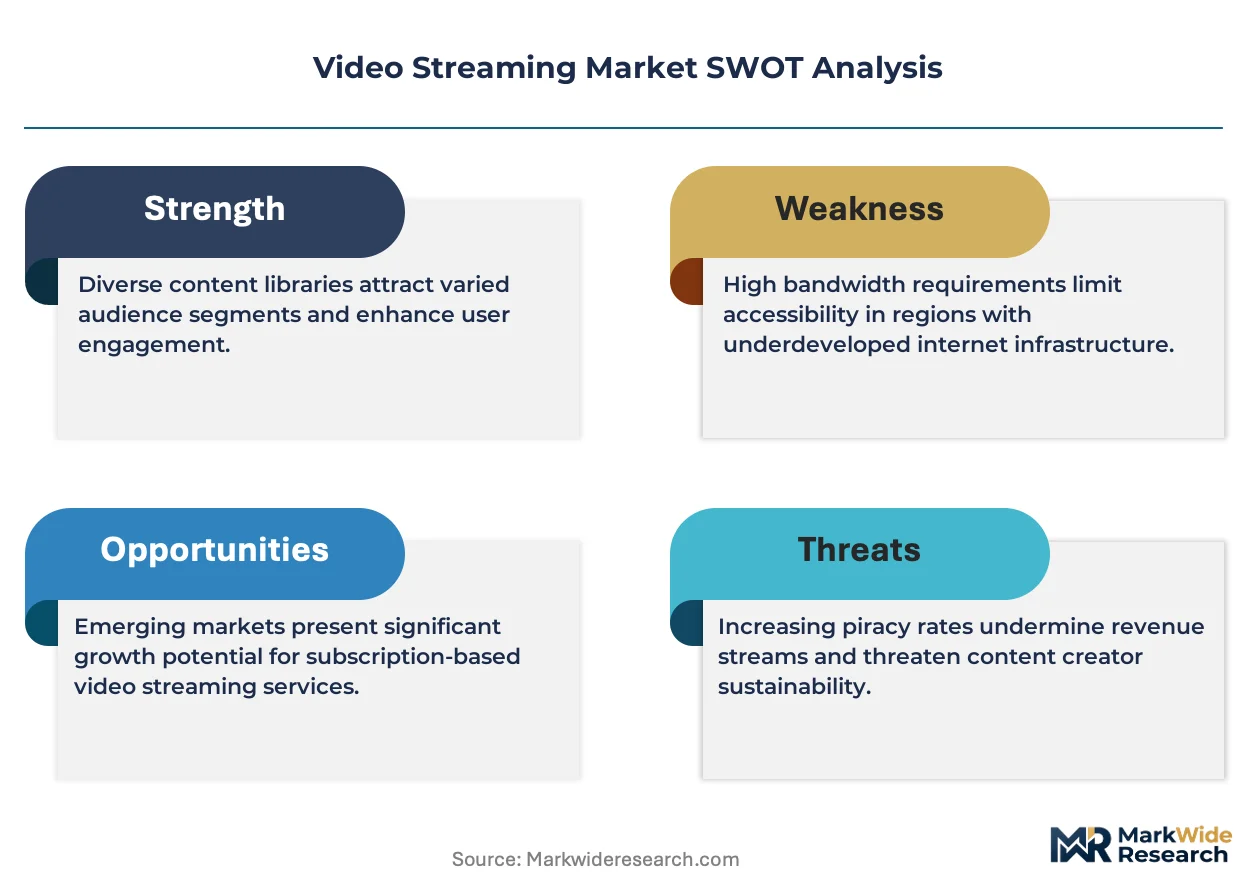
Regulatory fragmentation across India's TRAI certification, the EU's Digital Services Act, and the FCC's contested net neutrality framework compresses pricing tier spreads while forcing parallel supply chain architectures. Platforms must maintain separate compliance infrastructure for each jurisdiction, inflating fixed costs that concentrate in premium subscription tiers while ad-supported models absorb margin pressure.
Pricing Analysis
The customization-premium spread separates bespoke enterprise learning deployments from standardized consumer subscriptions. Three-tier pricing structure across premium, standard, and economy levels captures individual, household, and institutional buyer archetypes. Price differentiation hinges on content resolution tier and regional language catalog depth. Cost compression in basic tiers is intensifying because Brazilian and Mexican consumers rotate monthly between platforms. Enterprise learning departments in India show least price sensitivity due to training budget allocations.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers now stretch to 90 days for mid-tier platforms negotiating elastic compute capacity. Encoding and transcoding capacity concentrates in the United States, India, and Germany where hyperscaler data clusters anchor edge delivery nodes. Raw material dependencies span server-grade silicon, submarine cable bandwidth, and renewable energy contracts for carbon-neutral operations. Single-source vulnerability sits with AWS, Azure, and Google Cloud controlling global encoding infrastructure. Distribution runs through direct-to-consumer app stores and telco-bundled partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from user-generated content platforms and interactive entertainment formats that capture younger demographics. Defense requires building structural barriers against churn and content fragmentation.
For Market Incumbents: Build exclusive sports rights moats through multi-year live event contracts that lock marquee tournaments away from competitors. Anchor retention with serialized drama production pipelines that sustain weekly engagement calendars. Vertical integration into regional language studios in Mumbai and São Paulo secures catalog differentiation against pure-technology entrants. For New Entrants and Emerging Players: Establish a beachhead in Indonesia and Nigeria's mobile-first segments where smartphone penetration exceeds fixed broadband by 40 percentage points. Target enterprise learning deployments in India's corporate training departments replacing classroom modules. Go-to-market leverage rests on lightweight app architectures optimized for 5 Mbps adaptive bitrate streaming. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms controlling both intellectual property libraries and proprietary distribution infrastructure. Five-to-ten year viability centers on original production capability and regional localization depth. Acquisition targets should demonstrate explainable AI engineering teams responding to EU Digital Services Act audit requirements. Watch for inflection where monthly rotation behavior in Latin American markets stabilizes into annual subscription commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Original Content Production Scale-Up | Netflix's global production infrastructure sustains subscriber retention across multiple geographies. |
| Regional Language Localization Investment | TRAI-mandated grievance mechanisms accelerate platform localization for India's tier-2 and tier-3 cities. |
| Cloud-Native Encoding Infrastructure | Serverless architectures virtualize transcoding costs for mid-tier platforms in Southeast Asia. |
| Explainable AI System Development | EU Digital Services Act disclosure requirements force auditable recommendation engine rebuilds. |
| Live Sports Rights Acquisition | Exclusive marquee event contracts anchor retention against monthly rotation behavior in Brazil. |
Research Approach
Operator-level perspectives from platform engineering directors, content licensing executives, telco partnership managers, and enterprise learning procurement officers anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, TRAI regulatory notices, EU Digital Services Act implementation guidance, and hyperscaler capex disclosures. Bottom-up subscriber modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing framed optimistic, baseline, and pessimistic trajectories across the projection horizon. Segmentation dimensions modeled include content type, delivery model, device category, and subscription tier alongside regional regulatory cluster. CAGRs derived from historical growth pattern analysis and elasticity-adjusted adoption curves. Industry-specific inputs incorporated bandwidth infrastructure buildout timelines and content production budget inflation indices.
Stress conditions across FCC net neutrality rule changes, TRAI certification timeline extensions, and live sports rights auction volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substitution threat intensity and infrastructure deployment pace. Macroeconomic contraction, regulatory divergence acceleration, or interactive format disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Streaming Services Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Global Live Streaming Video Platform Market