
 United States Online Video Platform Market | 2026-2036
United States Online Video Platform Market Size, Share, and Industry Trends Forecast 2026-2036
United States Online Video Platform Market Intelligence
The United States online video platform landscape is restructuring around a sharp split between premium subscription stacks and ad-supported commodity infrastructure. Brightcove Inc. anchors the enterprise tier with specialized video hosting and monetization tools for broadcasters. Google LLC dominates the consumer-facing layer through YouTube's dual revenue engine, while Amazon Web Services Inc. competes on cloud delivery economics that undercut self-hosted alternatives.
Online video platforms are software systems that ingest, transcode, store, and distribute video content across IP networks, typically supporting adaptive bitrate streaming protocols such as HLS and DASH to maintain playback quality across variable bandwidth conditions. Their primary commercial purpose is to reduce the technical and capital barriers for content owners to reach audiences at scale without building proprietary CDN infrastructure. The subscription service type captures the highest revenue per user, though ad-supported models now attract the largest viewer bases and command the bulk of advertising technology investment. Cloud-based deployment leads in new implementations, while hybrid architectures persist among enterprises with legacy compliance requirements that mandate on-premises data residency.
The FCC governs broadband classification and peering agreements that shape last-mile delivery costs for streaming services, while the FTC scrutinizes platform consolidation and data practices under consumer protection authority. The SEC additionally imposes disclosure requirements on publicly traded platform operators regarding content licensing obligations and subscriber metric definitions. Stakeholders must monitor how regulatory pressure on algorithmic recommendation systems and child safety standards reshapes product development priorities and content moderation investments.
Market Dynamics
The United States online video platform market is restructuring around bandwidth allocation rules and cloud infrastructure economics, with FCC net neutrality proceedings determining streaming quality thresholds and enterprise training departments driving replacement cycles for legacy learning management systems.
Growth Catalysts
- Enterprise Training Migration:Organizations are replacing legacy learning management systems with integrated video delivery, creating sustained procurement cycles from Fortune 500 training departments and federal agency workforce development programs.
- FCC Bandwidth Rules:Ongoing net neutrality proceedings establish predictable peering cost structures that reduce last-mile delivery uncertainty for platform operators investing in adaptive bitrate streaming infrastructure.
- Silicon Valley Density:California's content creator concentration overlapping with hyperscale cloud infrastructure in the San Jose-to-Los Angeles corridor generates network effects that lower customer acquisition costs for platform vendors.
Market Restraints
- CDN Concentration Risk:Three hyperscale cloud providers control over 70 percent of edge server capacity, creating single-point-of-failure exposure and limiting price negotiation leverage for mid-tier platform operators.
- Transcoding Energy Costs:Real-time video processing at 4K resolution requires specialized GPU clusters whose electricity consumption and cooling demands strain facility budgets in markets with high utility rates.
- Interconnection Fee Volatility:Peering agreement disputes between last-mile ISPs and content networks periodically disrupt streaming quality, forcing platforms to absorb transit cost spikes or degrade user experience.
Strategic Opportunities
- Texas Enterprise Corridor:Austin and Dallas-Fort Worth metro areas host expanding corporate headquarters with underpenetrated training technology budgets, offering first-mover advantages for platform vendors establishing regional data centers.
- AI-Generated Content Pipelines:Convergence of generative video models with automated metadata tagging enables platforms to offer synthetic content creation tools that reduce production timelines for mid-market creators.
- State Privacy Legislation:California Consumer Privacy Act amendments and emerging Texas and Florida data residency requirements create compliance service revenue streams for platforms offering localized data storage and audit-ready analytics.
Industry Challenges
- Codec Patent Licensing:AV1, HEVC, and VVC royalty pool complexity creates legal exposure for platforms supporting multiple formats, with MPEG-LA and Access Advance patent claims requiring dedicated IP counsel and escrow reserves.
- Live Event Scaling:Unpredictable concurrent viewer spikes during sports and entertainment broadcasts strain auto-scaling infrastructure, demanding redundant capacity that sits idle during normal operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Online Video Platform Market |
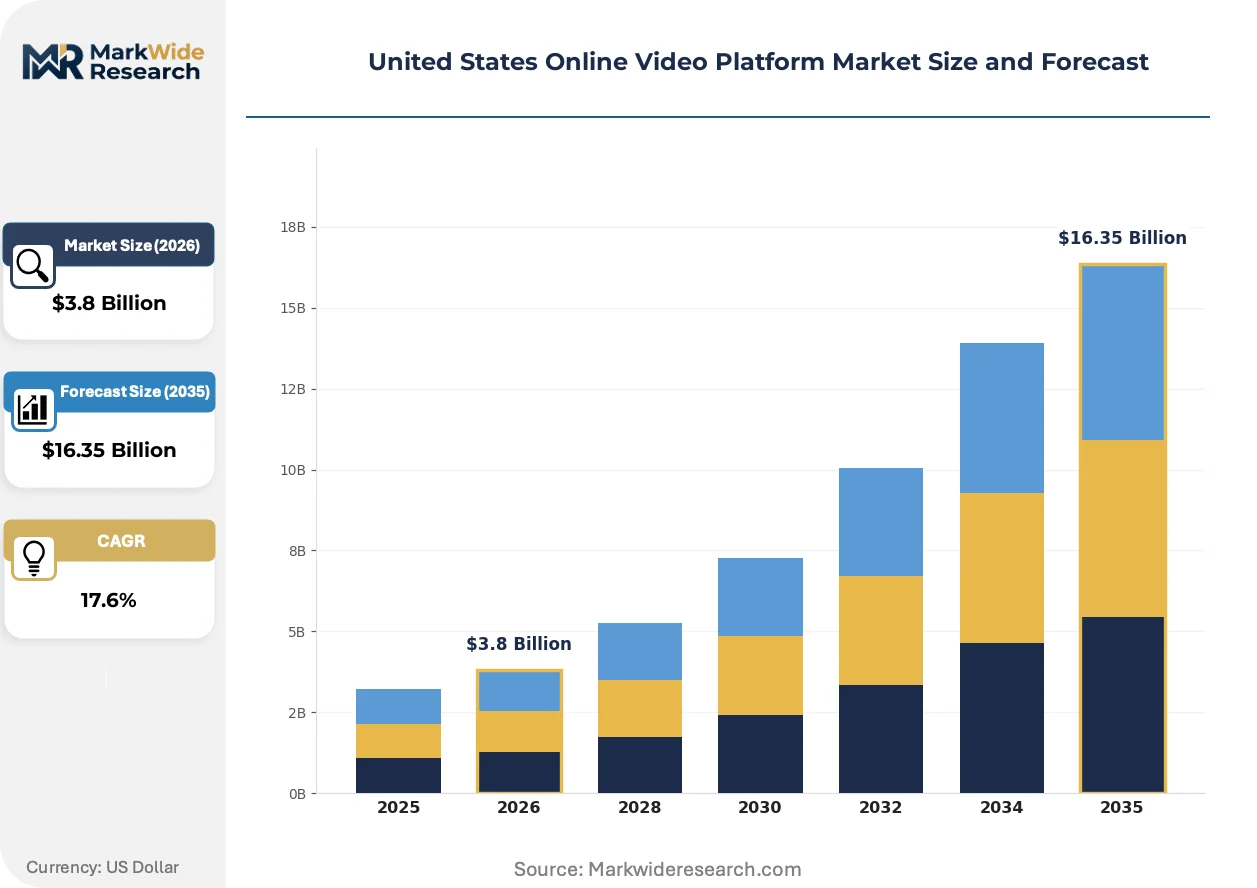
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, Ad-supported, Transactional Video on Demand, Live Streaming End User: Households, Educational Institutions, Enterprises, Content Creators Deployment: Cloud-based, On-premises, Hybrid, Mobile Content Type: Movies, TV Shows, Web Series, User-generated Content |
| Companies Covered | Brightcove Inc., Kaltura Inc., Akamai Technologies, Netflix Inc., Google LLC, Amazon Web Services Inc., Apple Inc., Wistia Inc., IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Online Video Platform Market Strategic Shifts & Innovations
Edge computing architectures and algorithmic content moderation are compressing latency thresholds and reshaping trust-and-safety investments across the United States online video platform landscape.
Serverless edge functions for real-time personalization are modularizing how platforms deploy recommendation engines, allowing enterprise customers to swap algorithm modules without re-architecting core infrastructure. Media companies and educational institutions are adopting this approach fastest, with deployment cycles compressing from eighteen months to six weeks. The structural consequence is modularizing the competitive moat away from proprietary algorithms toward data pipeline interoperability and customer data portability.
The FCC's ongoing broadband reclassification proceedings are creating regulatory uncertainty around common-carrier obligations for streaming traffic, with proposed rules threatening to impose quality-of-service mandates on platform operators. This friction is elevating compliance costs for mid-tier vendors while reinforcing the advantage of hyperscale operators with dedicated government affairs teams. Live sports broadcasters and political content distributors face the most acute exposure, with several platforms pre-emptively expanding Washington DC policy staff.
Subscription fatigue among consumer households is fragmenting video budgets across eight to twelve niche services, compressing average revenue per user for general-interest platforms while elevating willingness-to-pay for specialized vertical content. Enterprise procurement teams are mirroring this pattern, unbundling monolithic learning management contracts to procure point-solution video tools. This behavioral shift is most visible in healthcare and financial services verticals, where compliance-specific training content commands premium pricing independent of platform scale.
United States Online Video Platform Market Segmentation
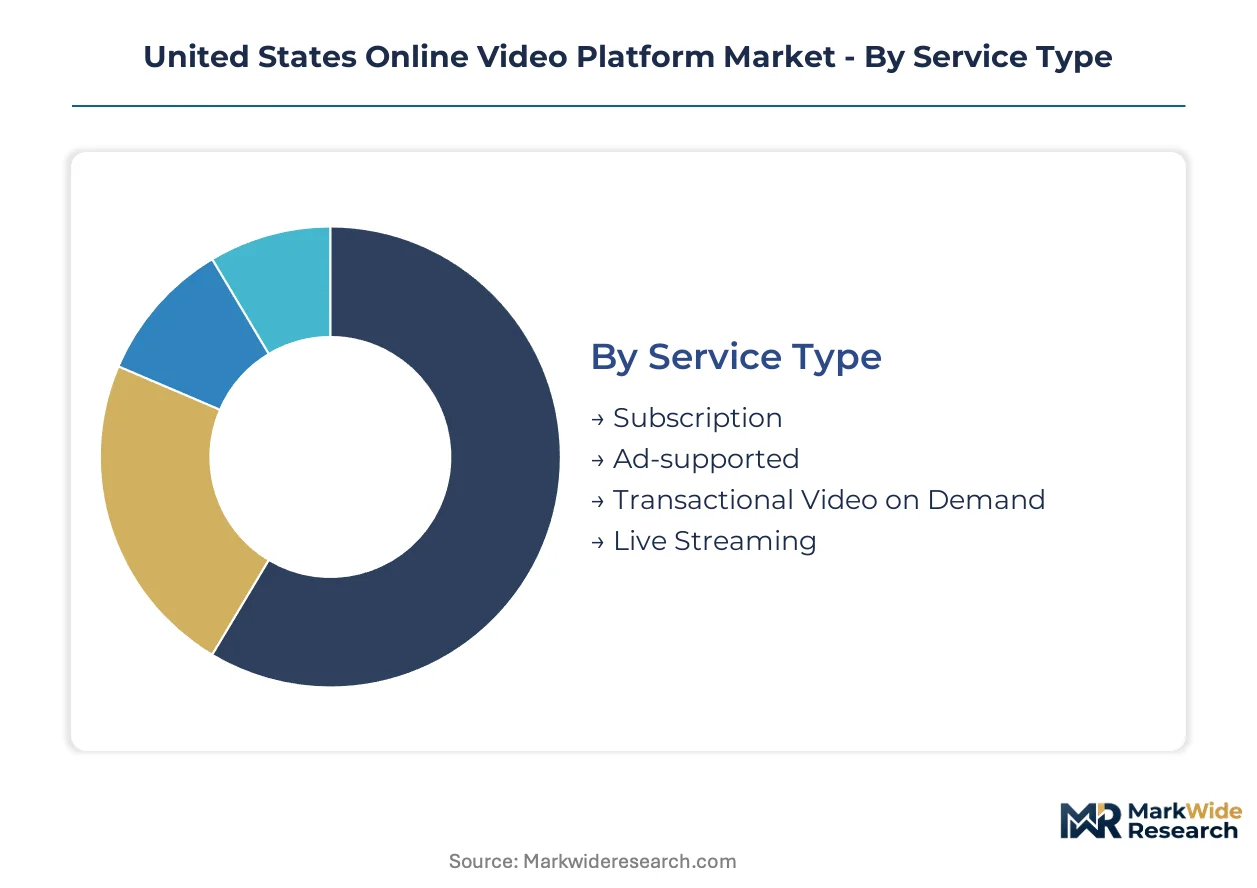
Platform operators in the United States online video platform market configure pricing, infrastructure, and compliance architectures around four distinct segmentation axes. Each axis carries divergent capital requirements, margin profiles, and regulatory exposure that reshape vendor competitive positioning.
Service Type:
Capital intensity varies sharply across service models, with live streaming infrastructure demanding the heaviest upfront investment in edge server networks and redundant transcoding capacity.
- Subscription:Recurring revenue models require substantial customer acquisition technology and churn prediction systems. Demand concentrates among households in California and New York metro areas where disposable income supports multiple platform commitments, though enterprise training departments are displacing consumer segments as the fastest-expanding procurement base.
- Ad-supported:Programmatic advertising stacks and viewer data management platforms drive fixed costs. Inventory monetization depends on FCC bandwidth allocation stability for maintaining ad insertion precision at scale.
- Transactional Video on Demand:Rights management infrastructure and studio licensing compliance create moderate capital barriers. Studios in Los Angeles corridor dominate supply relationships.
- Live Streaming:Unpredictable concurrent viewer spikes necessitate idle redundant capacity. Sports broadcasters and political content distributors absorb the highest infrastructure risk.
Most installed capacity flows through Ad-supported. Expansion is steepest in Subscription.
End User:
Procurement sophistication separates segments, with enterprise buyers demanding SLA guarantees and audit trails that consumer-facing deployments rarely match.
- Enterprises:Fortune 500 training departments and federal agencies mandate SOC 2 compliance and learning management system integration. Texas and Florida corporate relocations are opening underpenetrated procurement budgets outside traditional coastal markets.
- Educational Institutions:K-12 districts and universities require FERPA-aligned data residency. State-level privacy legislation in California and emerging Texas rules are fragmenting vendor qualification requirements.
- Content Creators:Individual and studio producers prioritize monetization tool depth over infrastructure control. Los Angeles and Silicon Valley density generates network effects lowering platform acquisition costs.
- Households:Subscription fatigue is fragmenting budgets across eight to twelve niche services, compressing average revenue per user for general-interest platforms.
Enterprise procurement volumes now match household spending. Educational institutions are climbing the fastest.
Deployment:
Compliance mandates and latency requirements are pulling implementations toward opposite infrastructure poles.
- Cloud-based:Hyperscale provider economics dominate new implementations. AWS, Google Cloud, and Azure control over seventy percent of edge capacity, creating concentration risk for mid-tier operators.
- Hybrid:Enterprises with legacy compliance requirements maintain on-premises data residency for sensitive content while bursting to cloud for distribution. Financial services and healthcare verticals show strongest attachment.
- On-premises:Federal agencies and defense contractors mandate air-gapped storage for classified training materials. Capital intensity limits viable vendor pool.
- Mobile:5G network slicing and carrier-edge partnerships are reducing last-mile latency for field workforce training. First responder and logistics applications drive specification requirements.
Cloud-based hosts the majority of new implementations. Mobile is expanding most quickly.
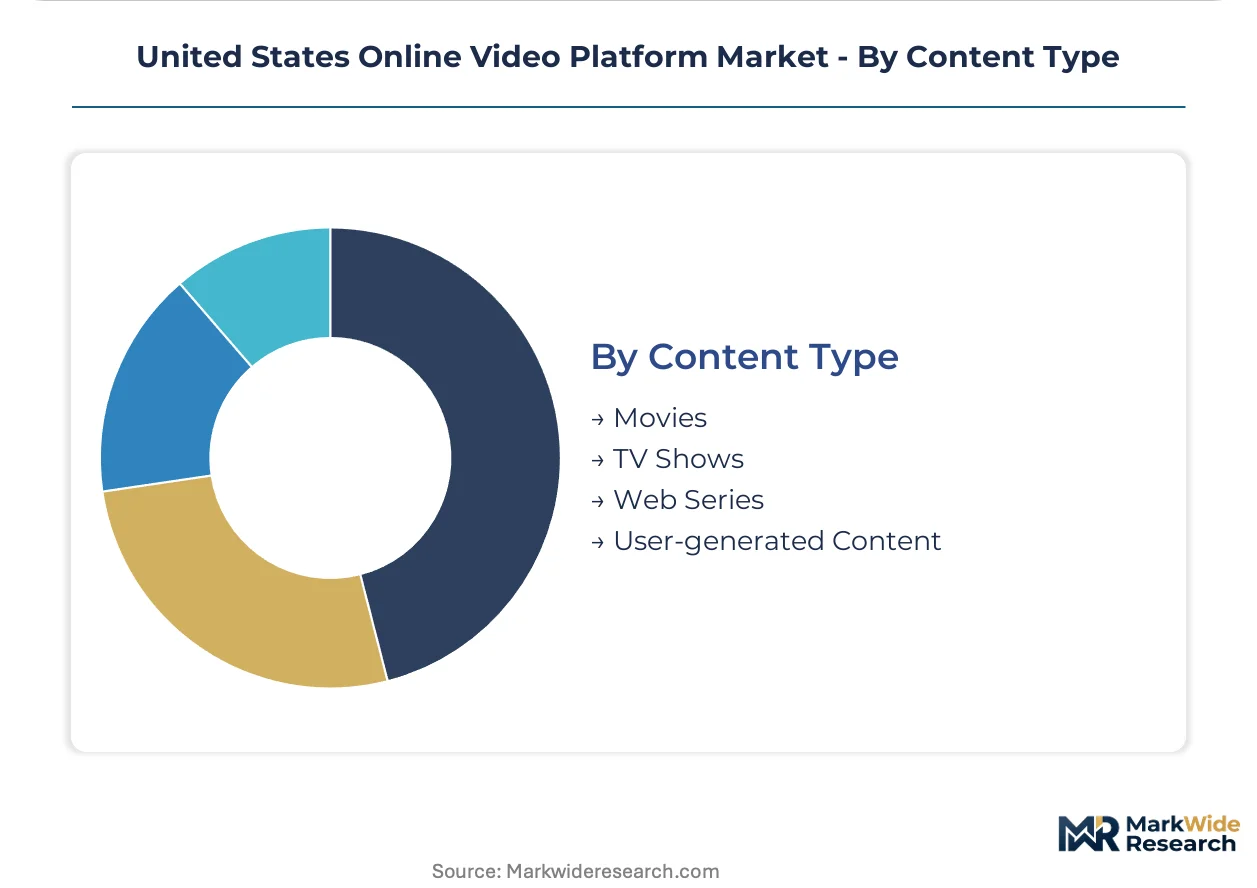
Content Type:
Production cost structures and rights complexity determine platform margin sustainability across content categories.
- Movies:Studio licensing windows and theatrical holdback rules create inventory fragmentation. Major studio concentration in Los Angeles corridor shapes supply negotiation dynamics.
- TV Shows:Seasonal release patterns generate predictable traffic spikes requiring elastic infrastructure. Broadcast network partnerships remain concentrated among legacy platform operators.
- Web Series:Lower production thresholds enable mid-market creator entry. AI-generated content pipelines are compressing production timelines and metadata tagging costs.
- User-generated Content:Algorithmic recommendation systems and trust-and-safety moderation dominate operational expense. FCC proceedings on algorithmic transparency are elevating compliance investment.
User-generated Content carries the largest viewer base. Web Series is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content creator density in California's Silicon Valley-to-Los Angeles corridor anchors United States online video platform demand, while enterprise training procurement clusters in Texas and federal compliance mandates concentrate in the Washington DC metro area.
California
Hollywood studio licensing partnerships and Silicon Valley cloud infrastructure overlap generate network effects that lower customer acquisition costs for platform vendors. The California Consumer Privacy Act mandates localized data storage and audit-ready analytics capabilities. Los Angeles content creator density and San Jose hyperscale data center proximity sustain the highest platform vendor concentration nationwide.
Texas
Austin and Dallas-Fort Worth corporate headquarters relocations are opening underpenetrated training technology budgets outside traditional coastal markets. Emerging Texas data residency requirements create compliance service revenue opportunities for platforms offering regional data centers. The state enterprise corridor attracts first-mover platform vendors establishing localized infrastructure.
New York Metro
Financial services and media company headquarters demand SOC 2-compliant video delivery with learning management system integration. New York State privacy legislation fragments vendor qualification requirements alongside federal SEC disclosure mandates. Manhattan and Brooklyn content production studios sustain mid-market creator platform adoption.
Washington DC Metro
Federal agency workforce development programs mandate air-gapped storage for classified training materials and FERPA-aligned data residency. FCC net neutrality proceedings headquartered in the district directly influence bandwidth allocation rules determining streaming quality thresholds. Virginia and Maryland defense contractors anchor on-premises deployment demand.
Illinois and Midwest
Manufacturing and logistics enterprise training departments in Chicago and Detroit metro areas drive mobile-first video delivery specifications for field workforce applications. State-level procurement regulations favor vendors with demonstrated learning management system interoperability. The region's industrial base sustains steady mid-tier platform adoption outside coastal technology clusters.
United States Online Video Platform Market Key Industry Players
Top-tier vendors anchor the hyperscale cloud delivery tier, while specialized enterprise hosting providers occupy the mid-market segment. The United States online video platform market structures around three distinct competitive layers: broadcast-grade enterprise suites, consumer-facing advertising engines, and infrastructure-as-a-service delivery networks. Strategic archetypes include vertically integrated content-to-cloud operators, pure-play video software specialists, and hyperscale cloud providers leveraging network effects. Dominant competitive moves center on learning management system integration partnerships and regional data center expansion to satisfy state privacy mandates.
Within the enterprise video hosting tier, Brightcove Inc. and Kaltura Inc. represent specialized vendors delivering broadcast-grade monetization tools and compliance architectures for Fortune 500 training departments. Google LLC and Amazon Web Services Inc. exemplify the hyperscale infrastructure archetype, leveraging cloud delivery economics and edge server networks to undercut self-hosted alternatives. Netflix Inc. occupies a distinct position bridging consumer subscription mechanics with proprietary content production pipelines.
| Leading Market Players |
|---|
| Brightcove Inc. |
| Kaltura Inc. |
| Akamai Technologies |
| Netflix Inc. |
| Google LLC |
| Amazon Web Services Inc. |
| Apple Inc. |
| Wistia Inc. |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up video infrastructure specialists have consolidated CDN and transcoding assets across California and Texas, tightening pricing discipline while feeding supply chain concentration into enterprise procurement leverage.
Pricing Analysis
Bundled enterprise suites versus unbundled point-solution subscriptions split the pricing architecture. Subscription tiers stratify across premium broadcast-grade, standard SaaS, and economy self-serve levels, with differentiation hinging on SLA guarantees and SOC 2 certification depth. Cost compression in the ad-supported tier intensifies as hyperscale cloud providers undercut specialist margins. Enterprise training departments show lowest price sensitivity due to compliance mandates, while individual content creators absorb the highest budget pressure.
Supply Chain Analysis
Freight and interconnection costs for edge server deployment concentrate supply chain risk in the California-to-Virginia corridor. Hyperscale cloud infrastructure draws from Taiwan, South Korea, and domestic US fabrication for GPU clusters, while specialized transcoding hardware sources from Japan and Germany. Single-source vulnerability in ASIC supply threatens redundant capacity planning. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales channels with regional data center presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas enterprise corridor expansion against California's CCPA compliance costs frames a geographic-arbitrage play for platform vendors seeking margin relief from coastal regulatory density.
For Market Incumbents: Extend hybrid deployment architectures into Austin and Dallas-Fort Worth to capture corporate relocation budgets before compliance fragmentation hardens. Fortify SOC 2 certification depth against emerging state privacy mandates in Florida and Texas. Vertical integration into regional edge capacity insulates against hyperscale cloud pricing power. For New Entrants and Emerging Players: Launch via API-first integration partnerships targeting mid-market healthcare training departments with FERPA-aligned data residency offerings. Penetration runs deepest among K-12 districts in Illinois and Michigan seeking learning management system interoperability without enterprise-grade procurement friction. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid-deployment specialists with federal contracting credentials and air-gapped storage capabilities. Long-term viability hinges on AI-generated content pipeline integration. The signal to watch is FCC net neutrality ruling clarity as bandwidth allocation certainty resets infrastructure investment thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Data Center Expansion | Texas and Florida data residency requirements create first-mover compliance advantages against coastal competitors. |
| Learning Management System Integration | Fortune 500 training departments mandate seamless LMS interoperability for procurement qualification. |
| AI-Generated Content Pipeline | Automated metadata tagging and synthetic video creation compress production timelines for mid-market creators. |
| Hybrid Deployment Architecture | Financial services and healthcare verticals require on-premises data residency with cloud bursting flexibility. |
| FCC Policy Affairs Investment | Net neutrality proceedings in Washington DC directly determine streaming quality threshold economics. |
Research Approach
Bottom-up enterprise training procurement modeling reconciled against top-down hyperscale cloud capacity tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, platform engineers, and federal agency training directors combine with secondary validation from SEC filings, hyperscaler capex disclosures, FCC proceeding dockets, and state privacy legislation databases. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of subscription and ad-supported revenue trajectories informs projection mechanics across the modeling period. Segmentation dimensions include service type, end-user vertical, deployment architecture, and content category, with CAGRs derived from elasticity-adjusted adoption curves. Forecast inputs incorporate FCC bandwidth rule scenarios and enterprise LMS replacement cycle timing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under net neutrality reversal or state privacy legislation fragmentation. Model assumptions reflect current regulatory trajectories and hyperscale cloud pricing stability. A model refresh is warranted upon material change in FCC broadband classification proceedings or Texas data residency enforcement timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
United States OTT Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Live Streaming Market