
 Indonesia OTT Market | 2026-2036
Indonesia OTT Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia OTT Market Insights
TRIAS Digital Platform certification is redrawing competitive access for foreign OTT providers entering Indonesia. Netflix Indonesia leverages its original content pipeline to sustain subscriber stickiness against localized rivals. Telkomsel anchors distribution through bundled mobile data plans that reduce customer acquisition costs. MNC Media competes via Vidio's freemium sports rights, particularly Liga 1 football streaming that dominates national viewership.
Indonesia over-the-top services deliver audio, video, and interactive content directly to end-users via internet protocol, bypassing traditional broadcast or cable infrastructure, with adaptive bitrate streaming typically ranging from 480p to 4K resolution depending on bandwidth availability. The primary commercial purpose centers on monetizing attention through subscription, advertising, or transaction-based revenue models across a fragmented archipelago where terrestrial infrastructure remains uneven. Video Streaming leads service type revenue as SVOD and AVOD models mature, while Live Broadcasting represents the fastest-growing segment driven by sports rights and real-time entertainment. Smartphone dominance in device type reflects Indonesia's mobile-first internet penetration, though Smart TVs are gaining traction in middle-class Jakarta households.
Ministry of Communication and Informatics licensing requirements and content takedown protocols shape platform operating costs, while the Indonesian Broadcasting Commission oversees domestic content quotas that force foreign services to commission local productions. The Financial Services Authority monitors payment gateway partnerships critical to recurring subscription billing. Stakeholders must track regulatory enforcement intensity around data localization mandates and youth content safeguards as compliance investment becomes a structural cost of market participation.
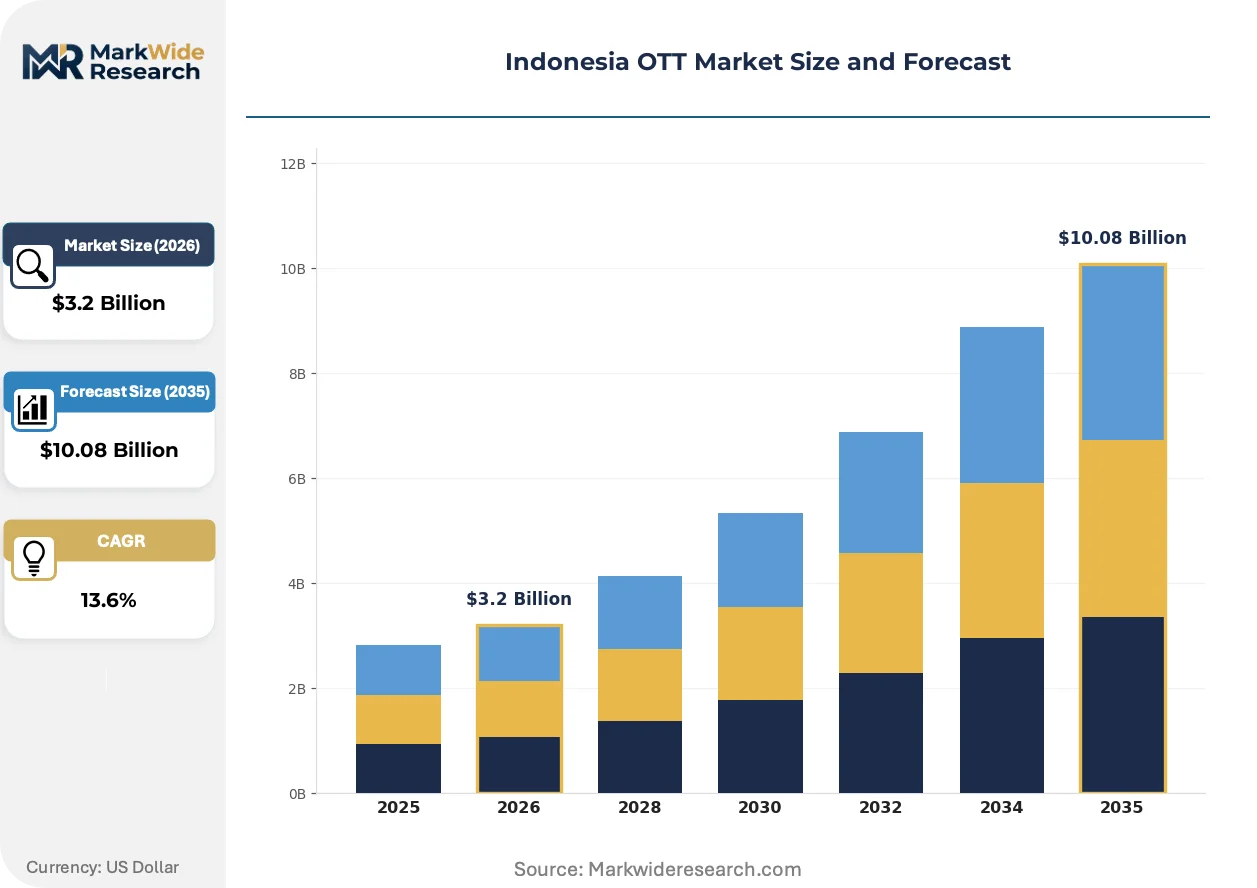
Market Dynamics
TRIAS Digital Platform certification is forcing foreign OTT providers to rebuild their Indonesia entry architecture around local infrastructure mandates. This regulatory pivot compresses deployment timelines while elevating compliance costs as a structural barrier to market access.
Growth Catalysts
- 4G/5G network expansion:Telkomsel and Indosat Ooredoo Hutchison are densifying base station coverage across Java and Sumatra. Reduced buffering friction accelerates SVOD adoption in Surabaya and Bandung metropolitan clusters.
- Ministry of Communication and Informatics content localization rules:Domestic production quotas pressure foreign platforms to commission Indonesian-language originals. Local commissioning spend creates downstream employment in Jakarta production houses.
- Smartphone penetration depth:Samsung and Xiaomi device saturation in middle-income households enables mobile-first streaming consumption. Adaptive bitrate technology optimizes experience across variable network conditions.
Market Restraints
- Data center localization costs:TRIAS certification requires domestic server deployment for content caching and user data storage. Capex intensity for AWS, Google Cloud, and Azure regions limits provider profitability in early years.
- Content licensing fragmentation:Sports rights—particularly Liga 1 football—are locked in exclusive windows by MNC Media and Emtek. Foreign platforms face supply concentration risk for high-engagement programming.
- Payment infrastructure gaps:Credit card penetration remains below regional peers; recurring billing depends on e-wallet partnerships with OVO, GoPay, and Dana. Transaction failure rates elevate churn risk.
Strategic Opportunities
- Eastern Indonesia archipelago penetration:Sulawesi, Maluku, and Papua present underpenetrated addressable markets where terrestrial broadcast infrastructure remains sparse. Satellite backhaul and improved maritime fiber create enabling conditions.
- Interactive live commerce integration:Shopee and Tokopedia have conditioned users to real-time purchasing during video sessions. OTT platforms can embed transaction layers without redirecting to external apps.
- Financial Services Authority fintech licensing:Payment gateway direct licensing reduces reliance on third-party aggregators. Platforms can capture interchange revenue and reduce billing friction.
Industry Challenges
- Content moderation workforce scaling:Ministry of Communication and Informatics takedown protocols require 24-hour response windows for user-generated live streams. Hiring Indonesian-speaking trust and safety analysts strains HR pipelines.
- Legacy broadcast integration:MNC Media and SCTV maintain linear audience habits that resist full digital migration. Hybrid viewers expect seamless cross-platform content discovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia OTT Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $10.08 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Streaming, Music Streaming, Gaming, Live Broadcasting Device Type: Smartphones, Smart TVs, Laptops, Tablets Content Genre: Drama, Comedy, Documentary, Sports Subscription Model: SVOD, AVOD, Freemium, Transactional |
| Companies Covered | Amazon Prime Video, PT Telekomunikasi Selular (Telkomsel), Netflix Indonesia, CatchPlay, PT Media Nusantara Citra Tbk (MNC Media), Vidio, PT Telekomunikasi Indonesia Tbk (Telkom Indonesia), Iflix, Viu, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia OTT Market Trends and Innovations
Streaming technology stacks are fragmenting around divergent performance tiers as infrastructure inequality across the archipelago forces architectural compromise. Platform engineering teams now optimize for three distinct network environments rather than uniform delivery.
Adaptive bitrate streaming is bifurcating platform technical roadmaps. Netflix Indonesia and Disney+ Hotstar maintain separate encoding ladders for Java-based 4K-capable households versus Eastern Indonesia 480p-optimized streams. Telkomsel's network analytics inform real-time resolution downshifting. This technical segmentation is bifurcating content acquisition strategy—prestige originals target Jakarta smart TVs while mobile-optimized formats dominate regional expansion.
Indonesian Broadcasting Commission domestic content quotas are tightening enforcement timelines. Foreign platforms must now commission 20% local production within 24 months of licensing. Production houses in South Jakarta and Cikarang are absorbing this demand surge. Scripted drama and religious programming categories face the steepest compliance pressure.
Subscription bundling through mobile carriers is displacing direct-to-consumer acquisition. Telkomsel's MaxStream packages reduce customer acquisition costs by 60% versus standalone marketing. Prepaid subscribers convert to monthly SVOD through pulsa balance deductions. This channel shift concentrates distribution power with two national carriers.
Indonesia OTT Market Segmentation
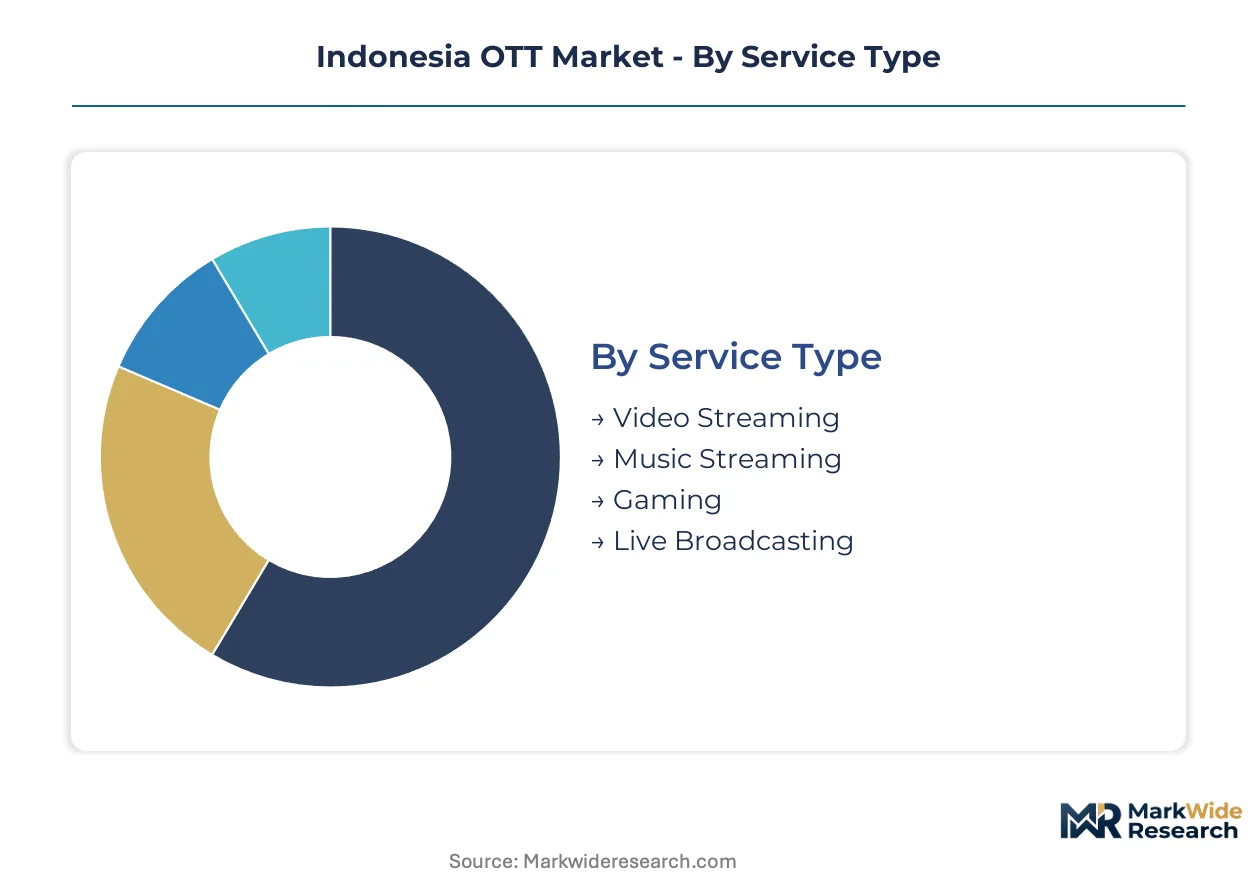
Segmentation in Indonesia's OTT landscape reveals how infrastructure inequality and regulatory pressure fragment platform strategies. Each dimension exposes distinct margin pools and competitive chokepoints that determine which providers capture Jakarta's premium households versus Eastern Indonesia's mobile-first users.
Service Type:
Video Streaming commands the dominant revenue share, though margin concentration varies sharply by content cost structure and subscriber lifetime value.
- Video Streaming:SVOD and AVOD models monetize through adaptive bitrate delivery ranging from 480p to 4K. Demand clusters in Java metropolitan areas where Telkomsel's network densification enables premium tier uptake.
- Music Streaming:Audio-first consumption dominates commute contexts across Surabaya and Bandung. Lower data requirements expand addressable markets beyond video-capable infrastructure zones.
- Gaming:Cloud gaming services face latency constraints that limit deployment to 5G-enabled Jakarta corridors. Interactive live commerce integration presents alternative monetization pathways.
- Live Broadcasting:Sports rights—particularly Liga 1 football—drive the steepest engagement spikes. Real-time delivery demands edge caching infrastructure that elevates operational costs.
Video Streaming holds installed capacity. Live Broadcasting is rotating up the share rankings.
Device Type:
Smartphone penetration depth across the archipelago creates volume leadership, though Smart TV households in Jakarta generate disproportionate ARPU.
- Smartphones:Samsung and Xiaomi device saturation enables mobile-first consumption. Adaptive bitrate technology optimizes experience across variable network conditions in Eastern Indonesia.
- Smart TVs:Middle-class Jakarta households drive 4K original commissioning decisions. Netflix Indonesia and Disney+ Hotstar maintain separate encoding ladders for this premium tier.
- Laptops:Work-from-home normalization sustains steady demand for long-form content consumption. Screen size supports multi-tasking behaviors that reduce completion rates.
- Tablets:Shared household devices concentrate in family contexts. Religious programming and children's content categories face compliance pressure here.
Smartphones capture volume leadership. Smart TVs are climbing the fastest on revenue per user metrics.
Content Genre:
Domestic production quotas under Indonesian Broadcasting Commission enforcement reshape where platforms allocate commissioning spend across genre categories.
- Drama:Scripted Indonesian-language originals satisfy localization mandates. Production houses in South Jakarta and Cikarang absorb surge demand from foreign platform commissioning.
- Comedy:Regional humor variants require hyper-local production partnerships. Stand-up and sketch formats gain traction on short-form platforms.
- Documentary:Religious and cultural programming categories face steepest compliance pressure. Lower production costs attract AVOD platform investment.
- Sports:Exclusive Liga 1 windows locked by MNC Media and Emtek create supply concentration risk. Foreign platforms face exclusion from highest-engagement programming.
Drama holds installed capacity. Sports is expanding most quickly on engagement intensity.
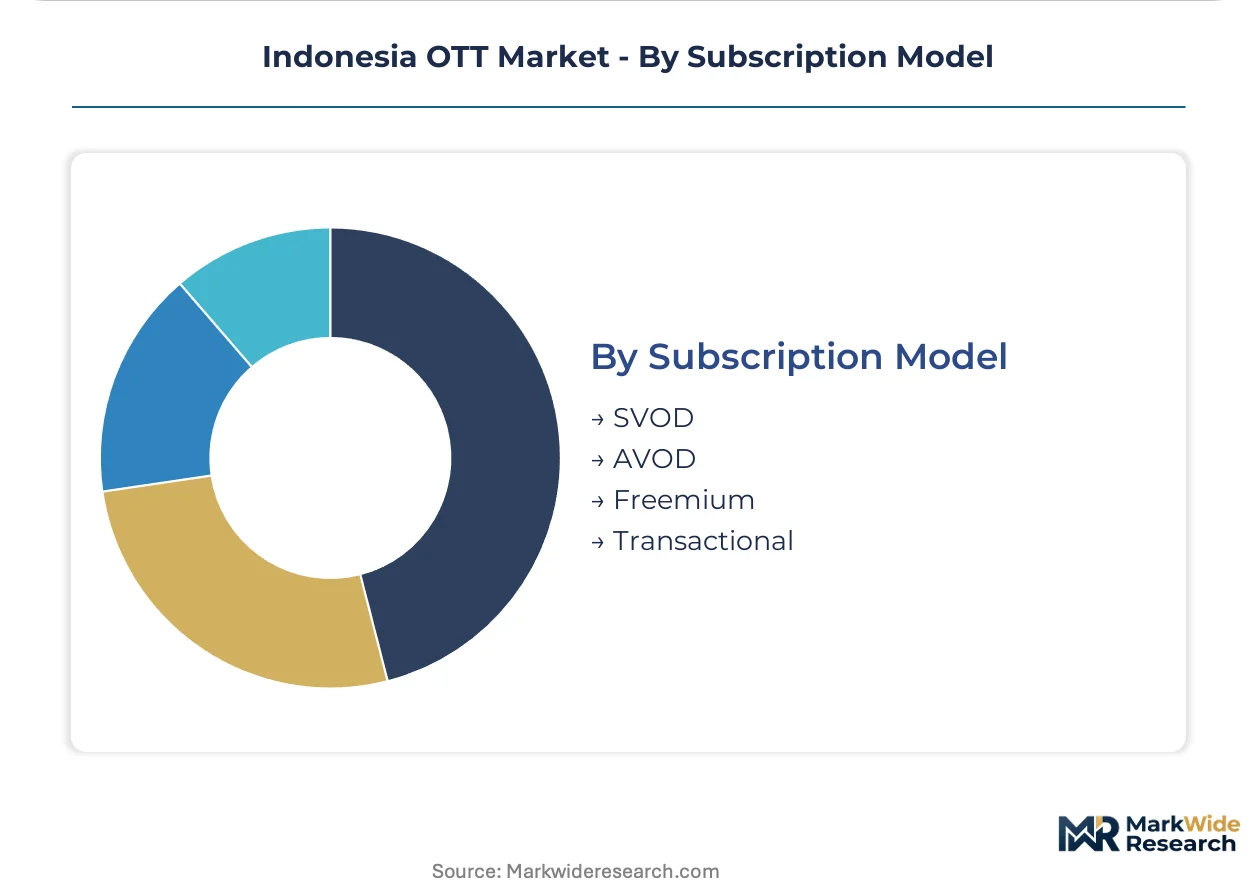
Subscription Model:
Telkomsel's bundling power concentrates distribution economics around carrier-integrated acquisition channels.
- SVOD:Recurring revenue depends on e-wallet partnerships with OVO, GoPay, and Dana. Transaction failure rates elevate churn risk where credit card penetration lags.
- AVOD:Advertising load tolerance varies by income tier. Jakarta households accept higher ad frequency than Eastern Indonesia users.
- Freemium:Vidio's sports rights strategy converts Liga 1 viewers through tiered access. Pulsa balance deductions reduce payment friction for prepaid subscribers.
- Transactional:Day-and-date film releases target theatrical bypass in secondary cities. Limited catalog depth constrains repeat purchase frequency.
SVOD holds installed capacity. Freemium is gaining share fastest on sports-driven conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
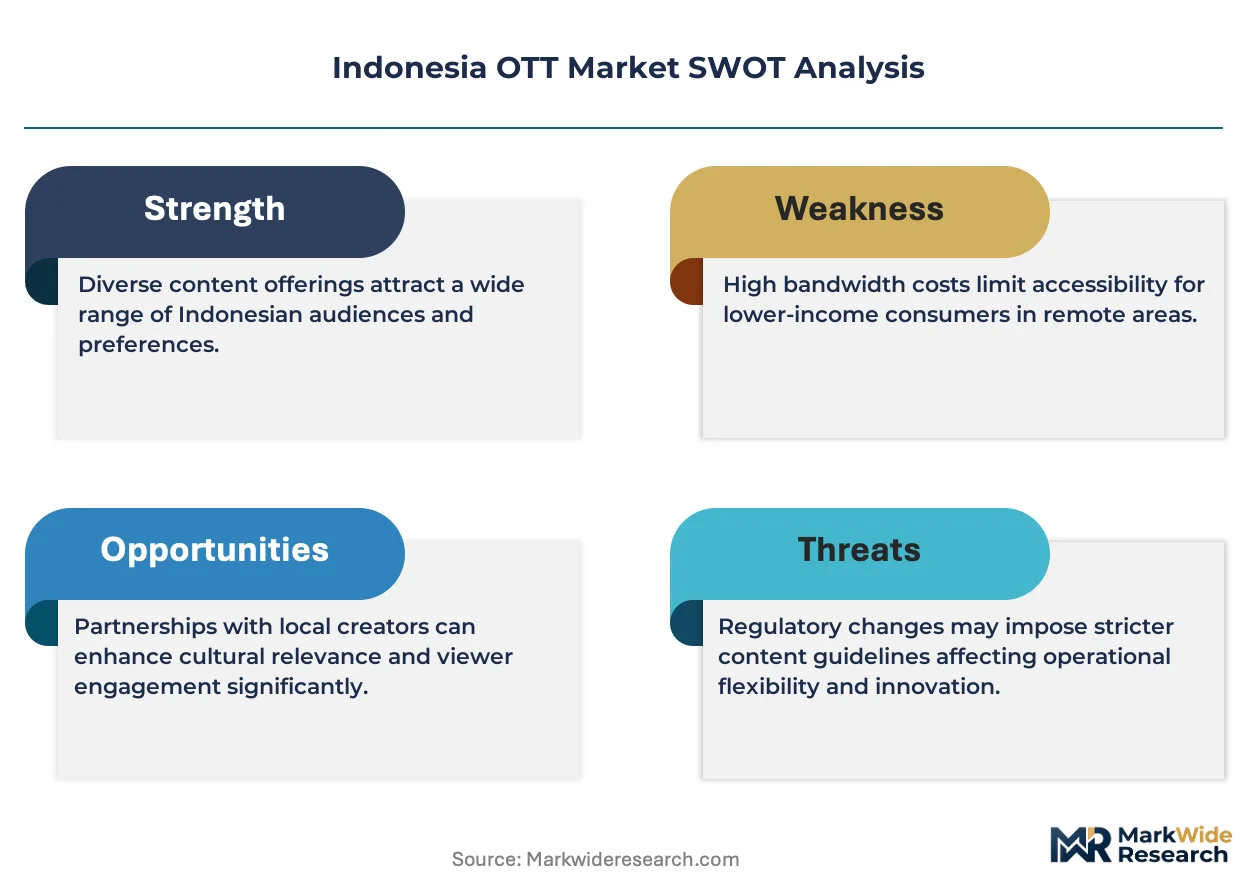
Ministry of Communication and Informatics licensing requirements are redrawing competitive access across Indonesia's archipelago. TRIAS Digital Platform certification mandates domestic server deployment, elevating compliance costs as a structural barrier to market entry.
Java
Jakarta and Surabaya metropolitan clusters concentrate SVOD uptake among young urban professionals. Telkomsel's 4G/5G network densification reduces buffering friction in Bandung and Yogyakarta. Production houses in South Jakarta absorb surge demand from foreign platform commissioning under domestic content quotas.
Sumatra
Medan and Palembang drive smartphone-first streaming consumption through Samsung and Xiaomi device saturation. Indonesian Broadcasting Commission enforcement timelines pressure platforms to commission local productions within 24 months. Adaptive bitrate technology optimizes 480p streams across variable network conditions in secondary cities.
Sulawesi
Makassar anchors Eastern Indonesia penetration where terrestrial broadcast infrastructure remains sparse. Satellite backhaul and improved maritime fiber create enabling conditions for mobile-first OTT adoption. Pulsa balance deductions through Telkomsel bundles reduce payment friction for prepaid subscribers.
Bali and Nusa Tenggara
Denpasar tourism corridors sustain steady demand for long-form content consumption on shared household tablets. Religious programming and children's content categories face compliance pressure from content rating enforcement. E-wallet partnerships with OVO and GoPay sustain recurring billing where credit card penetration lags.
Papua
Jayapura presents underpenetrated addressable markets with sparse terrestrial infrastructure. Network analytics inform real-time resolution downshifting for 480p-optimized streams. Local commissioning spend creates downstream employment in regional content moderation workforce scaling.
Indonesia OTT Market Competitive Landscape
Player mix skews toward carrier-integrated platforms and foreign streaming services with localized infrastructure. Market structure concentrates around bundled mobile data distribution and exclusive sports rights windows. Strategic archetypes include telecommunications carriers with content platforms, global streaming services with original content pipelines, and domestic media conglomerates with linear broadcast integration. Dominant competitive moves encompass carrier partnership negotiations and local production commissioning to satisfy regulatory quotas.
Among global streaming services, Netflix Indonesia and Amazon Prime Video exemplify foreign platforms rebuilding entry architecture around TRIAS certification mandates. PT Telekomunikasi Selular anchors distribution through bundled mobile data plans that reduce customer acquisition costs. PT Media Nusantara Citra Tbk occupies a position within the domestic media tier, competing via exclusive sports rights concentration.
| Leading Market Players |
|---|
| Amazon Prime Video |
| PT Telekomunikasi Selular (Telkomsel) |
| Netflix Indonesia |
| CatchPlay |
| PT Media Nusantara Citra Tbk (MNC Media) |
| Vidio |
| PT Telekomunikasi Indonesia Tbk (Telkom Indonesia) |
| Iflix |
| Viu |
| Others |
Pricing and Supply Chain Analysis
Long-term sports rights offtake agreements with Liga 1 broadcasters lock in both content access and subscriber pricing visibility for Indonesian OTT platforms, compressing margin flexibility as domestic production quotas under Indonesian Broadcasting Commission enforcement add parallel cost layers.
Pricing Analysis
Cost-plus content licensing with CPI indexation anchors SVOD tariff structures against rising local commissioning spend. Three-tier pricing structure across premium, standard, and economy levels separates 4K smart TV households in Jakarta from 480p mobile users in Eastern Indonesia. Cost compression in the standard tier is intensifying because carrier bundling through Telkomsel's MaxStream packages concentrates buyer power. Prepaid subscribers in Sulawesi and Papua exhibit highest price sensitivity; Jakarta smart TV households show lowest.
Supply Chain Analysis
Port congestion at Tanjung Priok and container availability constraints on the Singapore-Jakarta trade lane elevate inbound logistics costs for server hardware and networking equipment. Manufacturing concentration in China, Taiwan, and South Korea feeds cloud infrastructure deployment. Content delivery networks draw from submarine cable landings and domestic data center builds under TRIAS certification. Single-source vulnerability sits with AWS, Google Cloud, and Azure regional availability. Distribution runs through Telkomsel and Indosat Ooredoo Hutchison mobile carrier partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesian OTT market returns flow to platforms that control scarce sports rights and localized production capabilities, with skill gaps in Indonesian-language content commissioning and edge caching infrastructure deployment creating asymmetric advantage for early movers.
For Market Incumbents: Secure exclusive Liga 1 windows through multi-year extensions before Emtek and MNC Media consolidate remaining inventory. Deepen vertical integration into Jakarta production houses to satisfy Indonesian Broadcasting Commission quotas without margin erosion from third-party markups. For New Entrants and Emerging Players: Anchor in Eastern Indonesia's Sulawesi, Maluku, and Papua corridors where terrestrial broadcast infrastructure remains sparse and carrier bundling has not locked subscriber relationships. Target prepaid mobile users through pulsa-deducted freemium conversion, leveraging satellite backhaul and maritime fiber improvements as enabling infrastructure. For Investors and Strategic Acquirers: Domestic production houses with Indonesian Broadcasting Commission compliance track records and established talent pipelines in South Jakarta and Cikarang represent the highest-conviction acquisition archetype. Long-term viability hinges on 5-10 year regulatory enforcement continuity around domestic content quotas. The signal to watch is Ministry of Communication and Informatics takedown protocol staffing levels, which indicate enforcement intensity and compliance cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Local Production Commissioning | Satisfies Indonesian Broadcasting Commission quotas while building subscriber stickiness through Indonesian-language originals. |
| Carrier Partnership Expansion | Telkomsel and Indosat bundling reduces customer acquisition costs by embedding SVOD into existing mobile relationships. |
| Edge Caching Infrastructure | TRIAS-mandated domestic server deployment improves streaming quality for Java metropolitan 4K households. |
| Sports Rights Acquisition | Exclusive Liga 1 windows lock highest-engagement programming away from rival platforms. |
| Interactive Live Commerce Integration | Shopee-conditioned users enable transaction-layer embedding without external app redirection. |
Research Methodology
The analysis maps SVOD, AVOD, live broadcasting, and music streaming sub-sectors, each validated through platform strategy executives, carrier partnership managers, Jakarta production house operators, and Indonesian Broadcasting Commission liaison officers. Primary interviews combined with secondary validation from Ministry of Communication and Informatics licensing disclosures, Telkomsel network densification reports, and hyperscaler regional capex announcements. Bottom-up subscriber modeling and top-down addressable market sizing provided cross-check triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, device tier, content genre, and subscription model, with regional infrastructure quality as an industry-specific overlay. CAGRs derived from subscriber growth curves, ARPU progression by tier, and content cost inflation assumptions. Forecast inputs incorporated 4G/5G rollout pace, domestic production quota enforcement timelines, and e-wallet penetration rates.
Material uncertainties — regulatory enforcement intensity shifts, sports rights renewal outcomes, and maritime fiber deployment delays — sit outside the modeled envelope. Forecasts reflect assumptions around TRIAS certification continuity and carrier bundling persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
Global Cloud Video Streaming Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
United States Online Video Platform Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Enterprise Streaming Media Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Global Svod Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Streaming Spending Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market