
 India Loyalty Program Market | 2026-2036
India Loyalty Program Market Size, Share, and Industry Trends Forecast 2026-2036
India Loyalty Program Market Outlook
Asset-light SaaS licensing and revenue-sharing partnerships with retailers is tilting competitive dynamics toward technology platforms with scalable cloud infrastructure. Capillary Technologies leverages its enterprise-grade analytics stack to anchor multi-brand coalition programs for large retail conglomerates. Loyaltyxpert competes through modular white-label deployments that reduce upfront capital burdens for mid-market hospitality chains. IMAST Operations Private Limited sustains its position through specialized program management services tied to manufacturing and building-materials distributors.
Loyalty programs constitute structured customer-retention mechanisms that deploy data-driven reward architectures to influence repeat purchase behavior and lifetime value. These systems integrate CRM databases, transaction processing engines, and redemption marketplaces to deliver personalized incentives across digital and physical touchpoints. Points-based programs dominate transaction volumes in Indian retail due to their flexibility across diverse merchant networks, while tiered loyalty programs capture disproportionate margin pools in hospitality and premium travel verticals. Cashback programs are expanding fastest among price-sensitive e-commerce segments where immediate gratification drives conversion.
RBI oversight of prepaid wallets and loyalty point monetization, combined with SEBI disclosure requirements for listed retailers running material customer-incentive programs, shapes how operators architect fund flows and redemption reserves. BIS data-security standards and the Digital Personal Data Protection Act impose encryption and consent-management obligations on program databases. Stakeholders must monitor evolving central-bank guidance on loyalty-credit interoperability and state-level consumer-protection enforcement to anticipate compliance-driven platform redesigns.
Market Dynamics
RBI's prepaid wallet guidelines and the Digital Personal Data Protection Act are forcing loyalty operators to re-architect fund flows and consent-management systems, compressing margins for non-compliant legacy platforms while favoring cloud-native infrastructure providers.
Growth Catalysts
- Coalition Network Expansion:Quick-service restaurants and retail chains in Maharashtra and Karnataka are building multi-brand redemption ecosystems that pool customer data across merchants.
- PLI Scheme Tailwinds:India's production-linked incentive schemes for electronics manufacturing are embedding loyalty modules into OEM supply chains to capture aftermarket parts demand.
- Tier-II Urbanization:Organized retail penetration in Indore and Coimbatore is creating concentrated demand centers where loyalty programs drive footfall conversion.
Market Restraints
- Data Localization Costs:The Digital Personal Data Protection Act mandates domestic server infrastructure, raising capex for foreign platform operators entering India.
- Prepaid Reserve Requirements:RBI rules force loyalty operators to maintain liquid reserves against outstanding point liabilities, compressing working capital flexibility.
- Merchant Concentration Risk:Coalition programs depend on anchor retailers in Mumbai and Bengaluru, creating geographic dependency in network effects.
Strategic Opportunities
- Manufacturing Vertical Penetration:Building-materials and automotive parts distributors in Gujarat and Tamil Nadu remain underserved by structured retention programs.
- Voice-Enabled Redemption:Integration of vernacular voice interfaces with UPI rails is hybridizing access for semi-urban demographics.
- SEBI Disclosure Alignment:Listed retailers running material incentive programs must enhance transparency, creating demand for audit-ready loyalty management platforms.
Industry Challenges
- Consent-Architecture Talent Scarcity:Shortage of engineers versed in BIS data-security standards and RBI compliance protocols delays platform deployments.
- Legacy CRM Integration Friction:Mid-market hospitality chains struggle to merge siloed transaction databases with real-time points engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Loyalty Program Market |
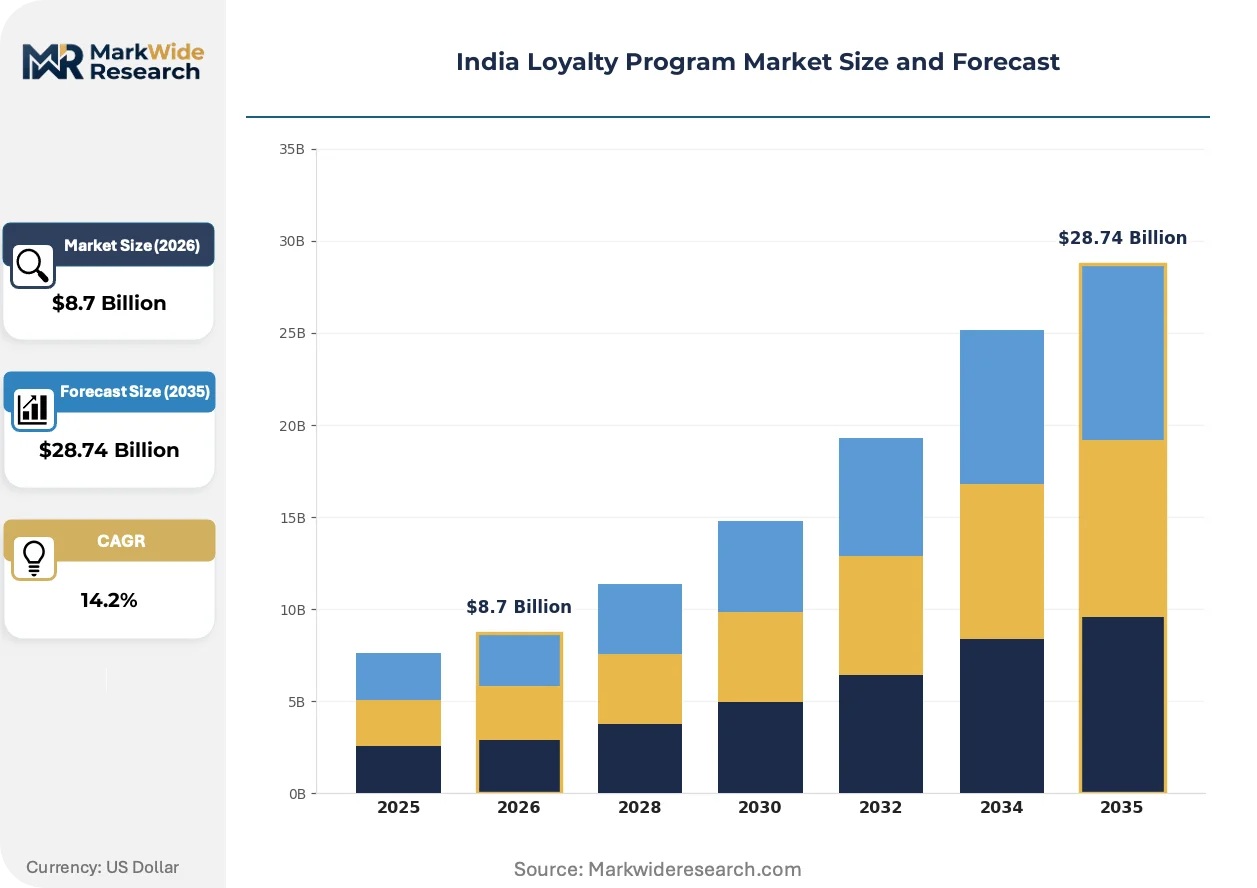
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Discount Programs, Cashback Programs, Points-Based Programs, Tiered Loyalty Programs Industry Vertical: Retail, Hospitality, E-commerce, Travel Customer Type: B2C, B2B, Millennials, Seniors Reward Structure: Monetary Rewards, Non-Monetary Rewards, Experiential Rewards, Exclusive Access |
| Companies Covered | Prince Pipes, Digisol Systems, Capillary Technologies, Havells India, Berger Paints, IMAST Operations Private Limited, CenturyPly, Goldbck, Loyaltyxpert, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Loyalty Program Market Strategic Shifts
Artificial intelligence and vernacular interfaces are reconfiguring how Indian loyalty platforms engage price-sensitive consumers across tiered urban markets.
Machine learning engines for predictive redemption modeling are hybridizing rule-based points allocation with dynamic offer personalization. Large retail conglomerates in Delhi and Hyderabad are deploying these systems to reduce breakage rates. The technology is compressing the gap between transaction data capture and incentive delivery from days to milliseconds.
The Digital Personal Data Protection Act's consent-layer mandates are forcing platform operators to rebuild customer databases with granular opt-in architectures. This regulatory pressure is accelerating partnerships between loyalty SaaS providers and domestic cloud infrastructure vendors. Tier-II city deployments face the steepest compliance timelines due to limited local legal-tech expertise.
Consumer preference for immediate gratification is displacing deferred-reward psychology in e-commerce segments. Cashback programs with instant UPI settlement are capturing transaction volumes previously directed at points-based accumulation models. This behavioral pivot is most visible in price-sensitive apparel and grocery verticals across Bengaluru and Pune.
India Loyalty Program Market Segmentation
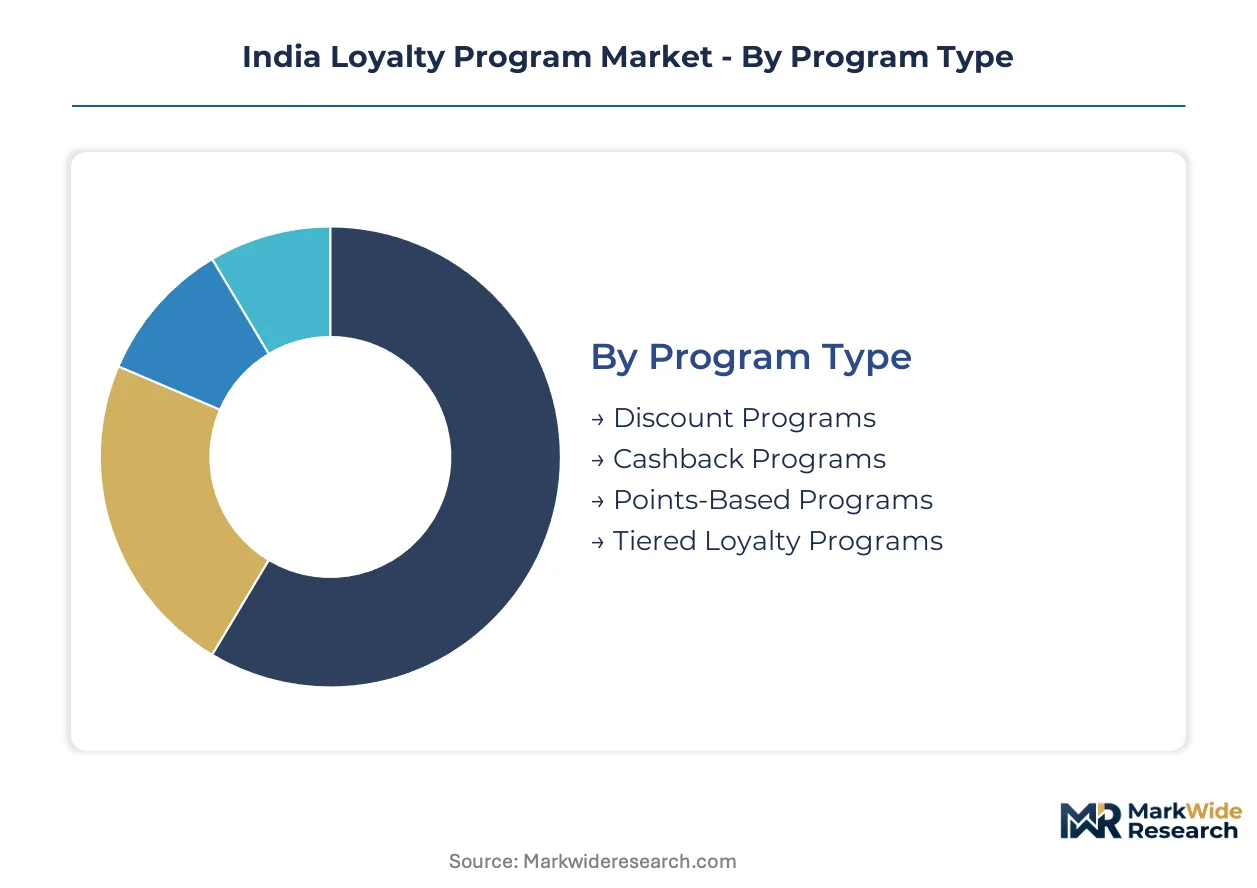
Loyalty program architectures in India diverge sharply across reward psychology and operational complexity. Program operators must align infrastructure investments with distinct engagement patterns across consumer demographics and merchant categories.
Program Type:
Use-case spectrum spans immediate gratification mechanisms to deferred status accumulation, each demanding different technology stacks and merchant network configurations.
- Points-Based Programs:Modular credit systems accumulate value across heterogeneous merchant networks through standardized redemption ratios. Maharashtra and Karnataka retail chains deploy these for cross-brand data pooling, though RBI prepaid reserve requirements compress float yields on outstanding liabilities.
- Cashback Programs:Instant UPI settlement mechanisms eliminate breakage risk while satisfying price-sensitive e-commerce demand in Bengaluru and Pune. Immediate gratification psychology displaces deferred-reward models in grocery and apparel verticals.
- Tiered Loyalty Programs:Status hierarchies with escalating privileges dominate hospitality and premium travel.
- Discount Programs:Upfront price reductions at point-of-sale require minimal backend infrastructure.
Established volume favors Points-Based Programs; emerging adoption favors Cashback Programs.
Industry Vertical:
Margin structure and purchase frequency determine program economics across sectors.
- Retail:High-frequency, low-margin transactions demand coalition networks to amortize customer acquisition costs. Quick-service restaurants in Mumbai anchor multi-brand redemption ecosystems.
- E-commerce:Digital-native transaction data enables real-time personalization engines. Cashback mechanisms with instant settlement capture volumes from deferred-reward competitors.
- Hospitality:Discretionary spend and experience differentiation support tiered status programs with asymmetric reward distribution.
- Travel:High-ticket, episodic purchases require breakage-optimized point architectures and partner airline integrations.
Coalition density concentrates in Retail; E-commerce exhibits steepest expansion trajectory.
Customer Type:
Demographic engagement patterns dictate interface design and reward preference.
- Millennials:Digital-native cohorts favor mobile-first redemption with social sharing features. Voice-enabled vernacular interfaces in Tier-II cities address semi-urban access barriers.
- B2C:Individual consumer programs dominate transaction volumes across retail networks.
- B2B:Corporate procurement incentives require invoice-linked accrual and bulk redemption mechanisms.
- Seniors:Assisted onboarding and simplified redemption paths address technology adoption friction.
Platform investment prioritizes Millennials; B2B remains structurally underserved.
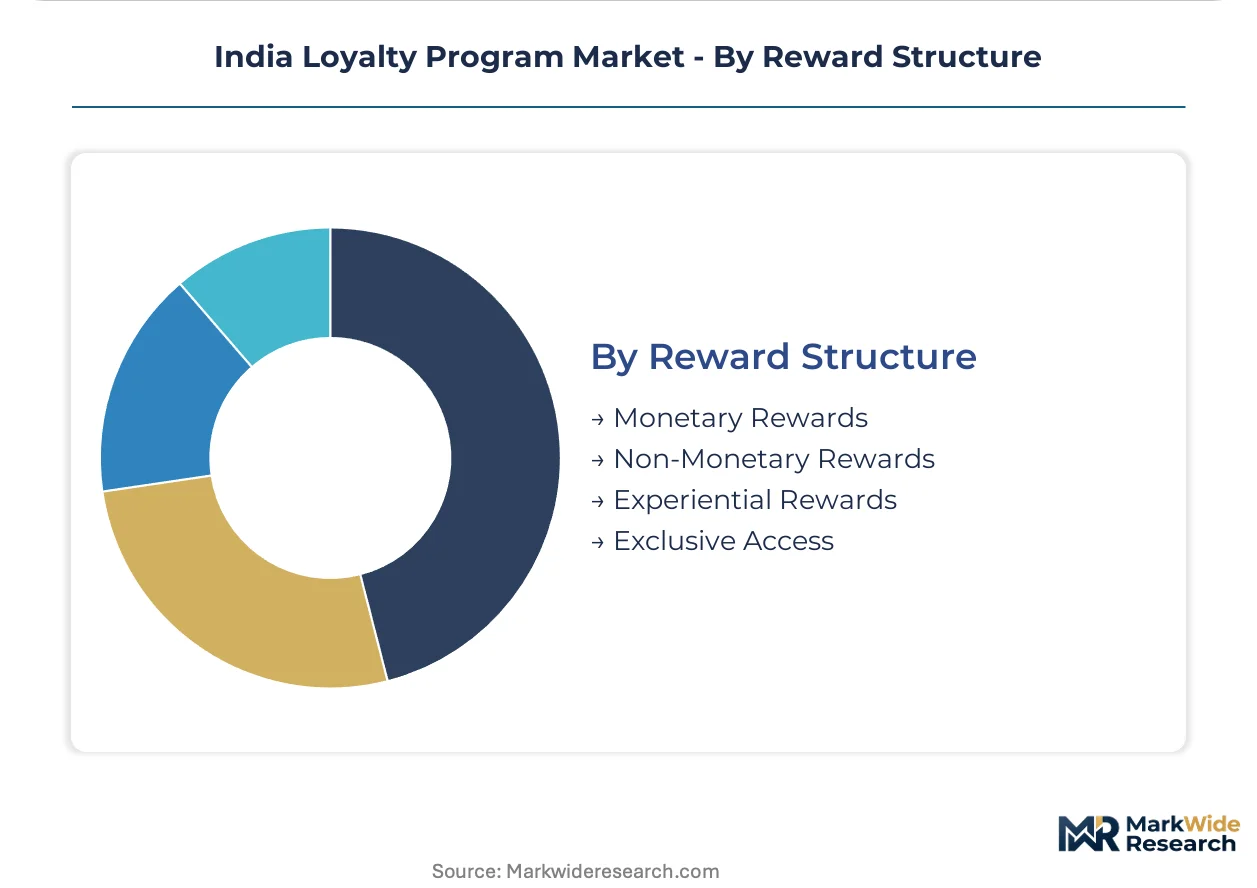
Reward Structure:
Value delivery mechanisms range from fungible currency to irreplaceable experiences.
- Monetary Rewards:Direct cash equivalence maximizes perceived value transparency. UPI settlement rails enable instant gratification without merchant-specific constraints.
- Experiential Rewards:Curated access and events command premium positioning in hospitality verticals.
- Non-Monetary Rewards:Merchandise and service credits reduce cash outflows for program operators.
- Exclusive Access:Priority service and limited availability drive status differentiation in tiered programs.
Monetary Rewards anchor mass-market penetration; Experiential Rewards secure premium margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's loyalty program infrastructure operates as a predominantly domestic service economy with limited cross-border point redemption flows. The market's regional architecture clusters around state-level retail penetration patterns and compliance jurisdiction boundaries.
Maharashtra
Mumbai anchors India's densest coalition loyalty networks, with quick-service restaurants and retail chains pooling customer data across multi-brand redemption ecosystems. RBI prepaid wallet guidelines force operators here to maintain liquid reserves against outstanding point liabilities. The Mumbai-Pune corridor concentrates enterprise-grade analytics deployments for large retail conglomerates.
Karnataka
Bengaluru's e-commerce density drives fastest adoption of cashback programs with instant UPI settlement, displacing deferred-reward models in grocery and apparel verticals. The state's technology workforce supplies engineers for consent-architecture platforms under Digital Personal Data Protection Act mandates. Tier-II satellite cities face steeper compliance timelines due to limited local legal-tech expertise.
Gujarat
Surat and Ahmedabad host underserved manufacturing verticals where building-materials and automotive parts distributors lack structured retention programs. PLI scheme tailwinds for electronics manufacturing embed loyalty modules into OEM supply chains. The state's merchant concentration remains below coalition network viability thresholds.
Tamil Nadu
Coimbatore emerges as a concentrated demand center where organized retail penetration deepens loyalty-driven footfall conversion. Chennai's hospitality sector deploys tiered status programs with asymmetric reward distribution. State-level consumer protection enforcement creates additional compliance layers for program operators.
Delhi-NCR
The National Capital Region concentrates SEBI-listed retailers running material customer-incentive programs requiring enhanced disclosure transparency. Noida and Gurugram house cloud-native infrastructure providers serving multi-brand deployments. Data localization norms under the Digital Personal Data Protection Act accelerate partnerships with domestic cloud vendors.
India Loyalty Program Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in analytics engines and consent-management modules. Market structure tilts toward technology platforms with scalable cloud infrastructure as asset-light SaaS licensing displaces capital-heavy proprietary deployments. Three archetypes dominate: enterprise-grade analytics providers anchoring multi-brand coalitions, modular white-label vendors reducing upfront burdens for mid-market chains, and specialized program managers tied to vertical distributors. Competitive moves concentrate on revenue-sharing partnerships with retailers and compliance-driven platform redesigns.
Within the enterprise analytics tier, Capillary Technologies occupies a position representing cloud-native infrastructure integration for large retail conglomerates. Loyaltyxpert exemplifies the modular deployment archetype serving hospitality chains with reduced capital barriers. IMAST Operations Private Limited anchors the specialized vertical segment through program management services tied to manufacturing and building-materials distribution networks.
| Leading Market Players |
|---|
| Prince Pipes |
| Digisol Systems |
| Capillary Technologies |
| Havells India |
| Berger Paints |
| IMAST Operations Private Limited |
| CenturyPly |
| Goldbck |
| Loyaltyxpert |
| Others |
Value Chain & Pricing Dynamics
Mumbai's concentration of cloud-native loyalty infrastructure providers shapes downstream pricing power for SaaS deployments across Indian retail conglomerates. RBI reserve requirements against outstanding point liabilities compress float yields, forcing operators to recoup costs through tiered subscription structures rather than transactional spreads.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium analytics stacks, standard coalition modules, and economy white-label deployments. Price differentiation rests on certification depth under BIS data-security standards and customization granularity for consent-architecture workflows. Cost compression in the mid-market tier is intensifying because foreign platform operators face domestic server capex burdens under data localization mandates. Price-sensitive mid-market hospitality chains gravitate toward modular deployments, while large retail conglomerates absorb premium tiers for enterprise-grade predictive redemption engines.
Supply Chain Analysis
Extended payment terms from domestic cloud infrastructure vendors are restructuring working capital dynamics for loyalty SaaS providers building RBI-compliant deployments. Technology sourcing concentrates on India, Singapore, and the United States for analytics engines, consent-management modules, and UPI settlement rails. Raw material dependencies span domestic server capacity, encryption hardware certified under BIS standards, and vernacular natural-language processing datasets. Single-source vulnerability concentrates in Mumbai and Bengaluru data center clusters. Distribution runs through direct enterprise sales teams for large retail conglomerates and channel partners for mid-market hospitality chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers versed in RBI compliance protocols and BIS data-security standards remain scarce, constraining platform deployment velocity and inflating talent acquisition costs for operators racing to meet Digital Personal Data Protection Act timelines.
For Market Incumbents: Harden consent-architecture capabilities through targeted acquisition of domestic legal-tech specialists, insulating against emerging entrants exploiting compliance delays in Tier-II city deployments. Fortify coalition network density in Maharashtra and Karnataka to lock in anchor retailer data pools before PLI scheme tailwinds attract manufacturing-focused competitors. For New Entrants and Emerging Players: Establish a beachhead in Gujarat and Tamil Nadu building-materials distribution networks, where structured retention programs remain underpenetrated despite organized retail expansion. Pursue voice-enabled vernacular interfaces as a differentiated go-to-market angle for semi-urban demographics underserved by English-first incumbent platforms. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because compliance-driven platform redesigns will consolidate market share toward cloud-native infrastructure providers with scalable domestic server footprints. Target acquisition candidates with proven RBI audit-ready architectures and existing revenue-sharing partnerships with Tier-II retail chains. Monitor central-bank guidance on loyalty-credit interoperability as the critical inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Consent-Architecture Talent Acquisition | Secures scarce engineers versed in RBI protocols and BIS encryption standards ahead of Tier-II deployment deadlines. |
| Domestic Cloud Infrastructure Partnership | Accelerates compliance with Digital Personal Data Protection Act localization mandates while reducing foreign operator capex burdens. |
| Coalition Network Expansion in Tier-II Cities | Captures concentrated demand centers in Indore and Coimbatore as organized retail penetration deepens loyalty-driven footfall conversion. |
| Vernacular Voice Interface Integration | Hybridizes UPI redemption access for semi-urban demographics lacking English-language digital fluency. |
| SEBI Disclosure Alignment Investment | Positions audit-ready platforms to capture listed retailer demand for transparent customer-incentive program management. |
Study Parameters
A standing panel of loyalty program operators, retail chain CTOs, RBI compliance officers, and domestic cloud infrastructure vendors provided ongoing calibration across primary interviews and secondary validation. Secondary sources encompassed SEBI disclosure filings, RBI circulars on prepaid payment instruments, BIS data-security standards documentation, and organized retail penetration databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing framed projections across program type, industry vertical, customer demographic, and reward structure dimensions throughout the forecast period. CAGRs derived from elasticity modeling against retail transaction velocity, coalition network density trajectories, and regulatory implementation timelines. Forecast inputs incorporated PLI scheme electronics manufacturing incentives and Digital Personal Data Protection Act compliance cost curves.
Stress conditions across RBI reserve requirement adjustments, data localization enforcement intensity, and Tier-II urbanization velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation cadence and merchant adoption curves. Macroeconomic contraction, accelerated central-bank interoperability mandates, or breakthroughs in legacy CRM integration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Digital Onboarding Software Market
Digital Solutions
Global Data Historian Market
Digital Solutions
Consent Management Market
Digital Solutions
Global Online Classifieds Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Global Product Lifecycle Management Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Cloud Logistics Software Market
Digital Solutions
Data Integration Market