
 Global Service Integration and Management Market | 2026-2036
Global Service Integration and Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Service Integration and Management Market Outlook
API orchestration layers are decoupling legacy middleware economics from enterprise IT budgets. IBM Corporation leverages its Red Hat integration stack to anchor hybrid cloud SIAM deployments across regulated industries. HCL Technologies Limited sustains competitive positioning through deep vertical specialization in manufacturing and telecom service towers. Accenture PLC differentiates via outcome-based contracting models that tie SIAM fees to measurable service-level improvements.
Service Integration and Management (SIAM) denotes a management methodology that coordinates multiple service providers through a single integrator layer, typically governed by ITIL-aligned processes with defined service level agreements, key performance indicators, and governance boards. Its primary purpose is to eliminate vendor silos, standardize reporting, and ensure end-to-end accountability in multi-sourced IT environments. Managed Services commands the largest revenue pool due to long-term operational contracts, while Cloud deployment models represent the fastest-expanding segment as enterprises exit owned data centers. API-based integration approaches capture disproportionate margin pools because they enable real-time interoperability without custom code maintenance.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that reshape how SIAM providers architect cross-border service flows. NIST cybersecurity frameworks in the United States and Japan's METI data governance guidelines further tighten vendor certification and audit protocols. India's Digital Personal Data Protection Act introduces localization mandates that SIAM integrators must embed into multi-country delivery models. Stakeholders should evaluate whether their current governance frameworks can absorb emerging sector-specific compliance layers without fragmenting service accountability.
Market Dynamics
API orchestration layers are decoupling legacy middleware economics from enterprise IT budgets, forcing integrators to rebuild pricing models around real-time interoperability rather than perpetual license maintenance.
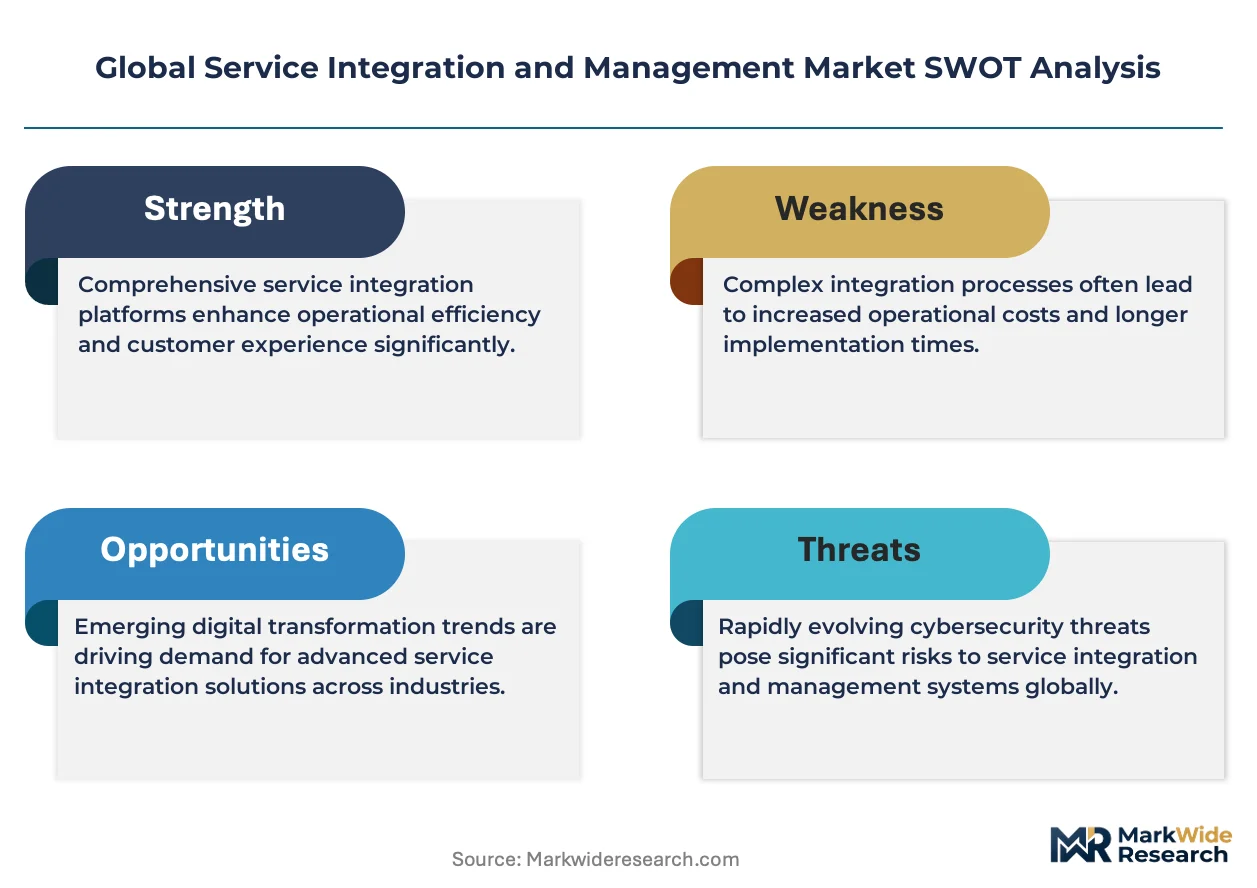
Growth Catalysts
- EU Digital Sovereignty Mandates:Cloud migration requirements under EU data residency frameworks are accelerating hybrid deployment adoption across financial services and automotive supply chains.
- Automotive Supplier Architectures:German industrial conglomerates operate complex multi-tier supplier-integrated service models that demand unified SIAM governance to coordinate Tier-1 through Tier-3 IT operations.
- ITIL Process Maturation:Standardized service level agreement frameworks and key performance indicator dashboards are eliminating vendor silos in multi-sourced enterprise environments.
Market Restraints
- Certification Timeline Compression:NIST cybersecurity frameworks and Japan's METI data governance guidelines tighten vendor audit protocols, extending qualification cycles for cross-border delivery models.
- Input Cost Concentration:Specialized SIAM talent pools concentrate in Bangalore and Frankfurt, creating wage inflation pressure for managed services contracts.
- Technical Debt Accumulation:Legacy middleware dependencies in European banking infrastructure resist API-first migration without custom bridge development.
Strategic Opportunities
- India Localization Mandates:The Digital Personal Data Protection Act creates captive delivery requirements that favor integrators with Mumbai and Hyderabad operational hubs.
- AI Governance Convergence:The EU AI Act's algorithmic transparency rules intersect with GDPR data residency requirements, opening compliance-as-a-service revenue streams.
- Manufacturing IoT Integration:Industrial sensor networks and edge computing platforms converge to demand real-time service orchestration across predictive maintenance ecosystems.
Industry Challenges
- Multi-Framework Talent Scarcity:Practitioners fluent in both ITIL v4 and DevSecOps pipelines command premium compensation, constraining margin expansion for managed services providers.
- Cross-Border Data Flow Friction:India's localization mandates fragment service accountability across multi-country delivery architectures, complicating end-to-end liability structures.
- Legacy System Integration Complexity:Mainframe-dependent financial institutions in Frankfurt and London require custom API gateways that extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Service Integration and Management Market |
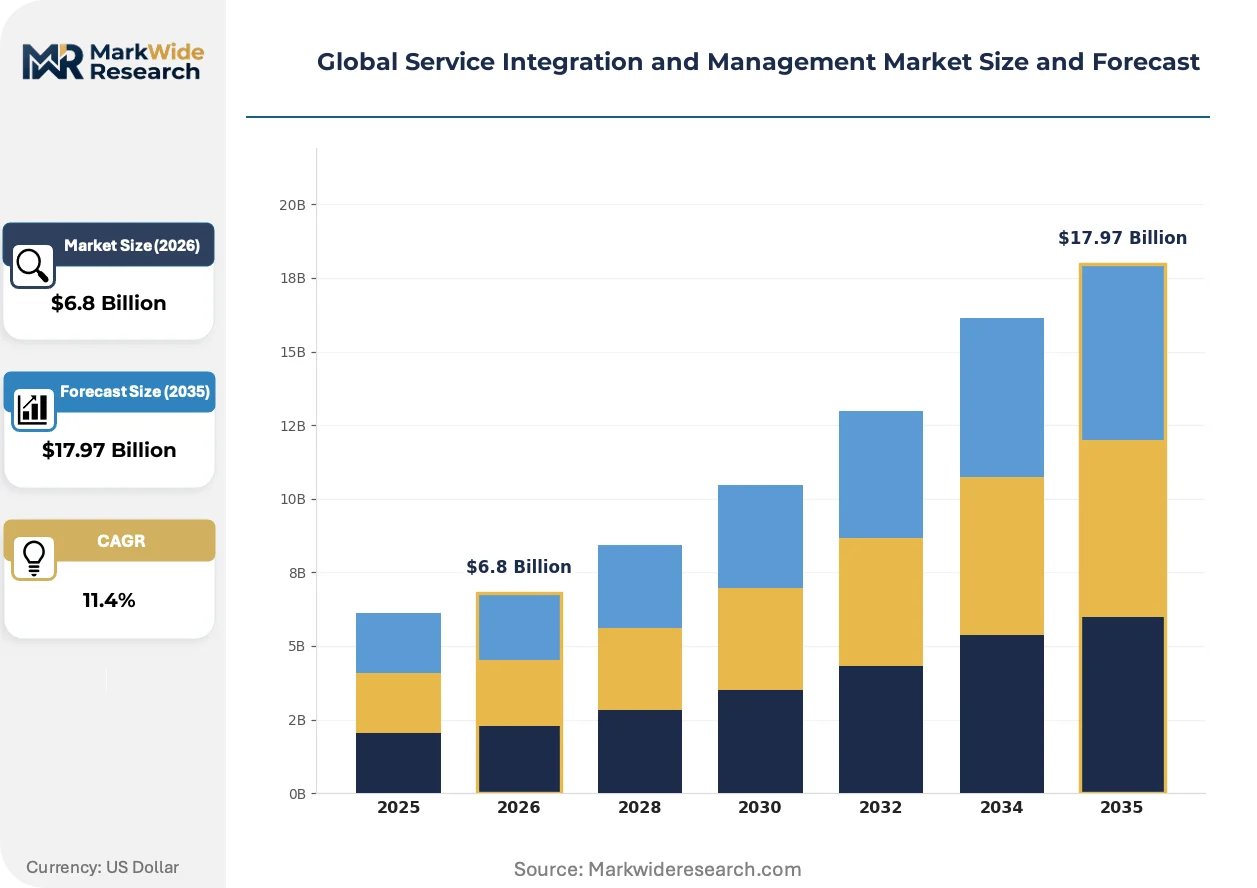
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Professional Services, Consulting Services, Support Services Industry Vertical: Healthcare, BFSI, Retail, Telecommunications Deployment Model: On-Premises, Cloud, Hybrid, Dedicated Integration Approach: API-based, Event-driven, User Interface, Others |
| Companies Covered | IBM Corporation, HCL Technologies Limited, Accenture PLC, Fujitsu, TATA Consultancy Services Limited, DXC Technology Company, CGI Inc, Atos SE, Infosys Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Service Integration and Management Market Strategic Shifts
Real-time interoperability demands are compressing the value capture window for traditional integration middleware, redirecting investment toward event-driven architecture and low-code orchestration platforms.
Event-driven API mesh architectures are absorbing the integration workload previously handled by enterprise service buses. Automotive manufacturers in Stuttgart and Wolfsburg are deploying these meshes to synchronize supplier production schedules with assembly line telemetry. The technology is absorbing margin pools from legacy middleware vendors by eliminating custom code maintenance requirements.
The EU AI Act imposes algorithmic transparency and human-in-the-loop documentation requirements on automated service orchestration tools. Financial services institutions must now maintain audit trails for AI-driven incident routing decisions. German banking regulators are demanding explainability layers that SIAM providers must embed into multi-vendor governance dashboards.
Buyers are unbundling long-term managed services contracts into modular, outcome-based engagements with shorter renewal cycles. Automotive OEMs in Munich now negotiate SIAM fees tied to measurable mean-time-to-resolution improvements rather than headcount-based rates. This pattern is most visible in German-speaking industrial corridors where procurement functions have consolidated vendor management authority.
Global Service Integration and Management Market Segmentation
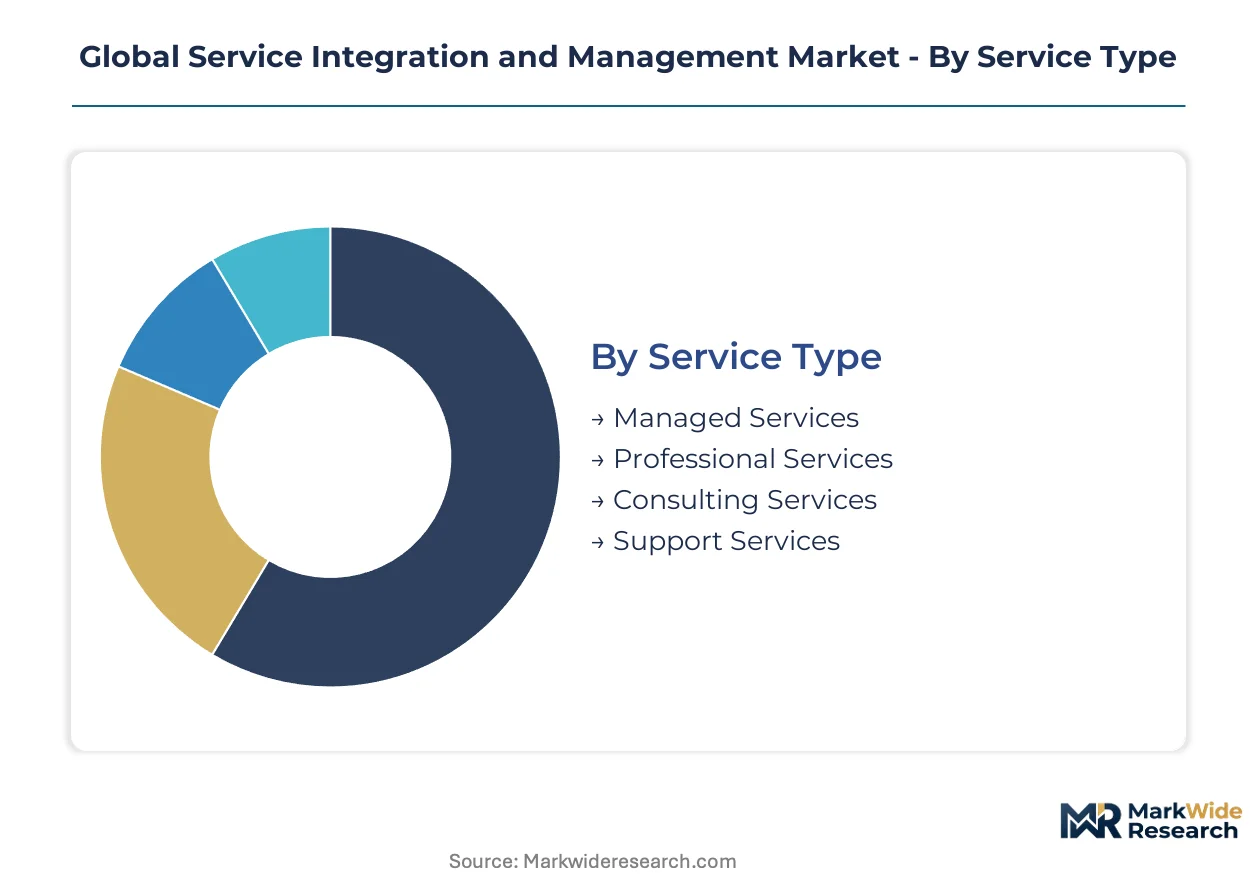
SIAM procurement patterns fragment across four structural dimensions that determine vendor selection criteria and contract economics. Each segmentation layer captures distinct buyer priorities, from operational control preferences to compliance architectures governing multi-vendor coordination.
Service Type:
Supply concentration in managed services contracts anchors revenue stability for integrators, while professional services margins fluctuate with project pipeline volatility.
- Managed Services:Long-term operational contracts embed ITIL-aligned governance boards and SLA dashboards into recurring revenue streams. German automotive conglomerates in Stuttgart and Wolfsburg favor these structures for Tier-1 through Tier-3 supplier coordination. The segment commands the largest revenue pool due to multi-year contract tenures and embedded escalation clauses.
- Professional Services:Project-based engagements deliver SIAM architecture design, vendor onboarding, and process reengineering. Demand concentrates in financial services institutions across Frankfurt and London modernizing legacy middleware stacks. Margin pressure intensifies as buyers unbundle implementations into modular, outcome-scoped statements of work.
- Consulting Services:Advisory engagements assess multi-vendor governance maturity and design integration operating models.
- Support Services:Break-fix and maintenance tiers address incident resolution across heterogeneous supplier environments.
Today's leader: Managed Services. Tomorrow's challenger: Professional Services.
Industry Vertical:
Application-specific compliance burdens reshape integration architecture requirements, with BFSI and healthcare demanding distinct audit trail capabilities.
- BFSI:Banking and insurance institutions operate under GDPR, EU AI Act, and NIST cybersecurity frameworks that mandate algorithmic transparency in automated service orchestration. Frankfurt-based regulators require explainability layers embedded in multi-vendor governance dashboards. The vertical generates concentrated demand for hybrid deployment models that satisfy data residency requirements.
- Healthcare:HIPAA in the United States and EMA data governance guidelines impose patient data protection standards on cross-border service flows. Medical device manufacturers in Switzerland and Germany require SIAM architectures that segregate clinical systems from administrative IT.
- Retail:Omnichannel fulfillment networks demand real-time inventory synchronization across distributed supplier ecosystems.
- Telecommunications:5G network slicing and edge computing deployments require low-latency service orchestration across infrastructure partners.
BFSI anchors current procurement volume. Healthcare is climbing the fastest as digital health platforms expand.
Deployment Model:
Margin structures diverge sharply between capital-intensive on-premises installations and consumption-based cloud economics.
- Cloud:Consumption-based pricing eliminates perpetual license maintenance and accelerates exit from owned data centers. EU digital sovereignty mandates under GDPR and the EU AI Act are accelerating adoption across financial services and automotive supply chains. The model captures the steepest expansion trajectory as enterprises prioritize operational expenditure flexibility.
- Hybrid:Architectures partition sensitive workloads to on-premises infrastructure while bursting transactional loads to public cloud. German industrial conglomerates favor this model for supplier-integrated service architectures that must satisfy both operational technology isolation and scalability requirements.
- On-Premises:Legacy installations persist in Frankfurt and London banking infrastructure resistant to API-first migration without custom bridge development.
- Dedicated:Single-tenant environments address sovereign cloud requirements in India under the Digital Personal Data Protection Act.
Hybrid dominates contract value today. Cloud is gaining share fastest as exit timelines compress.
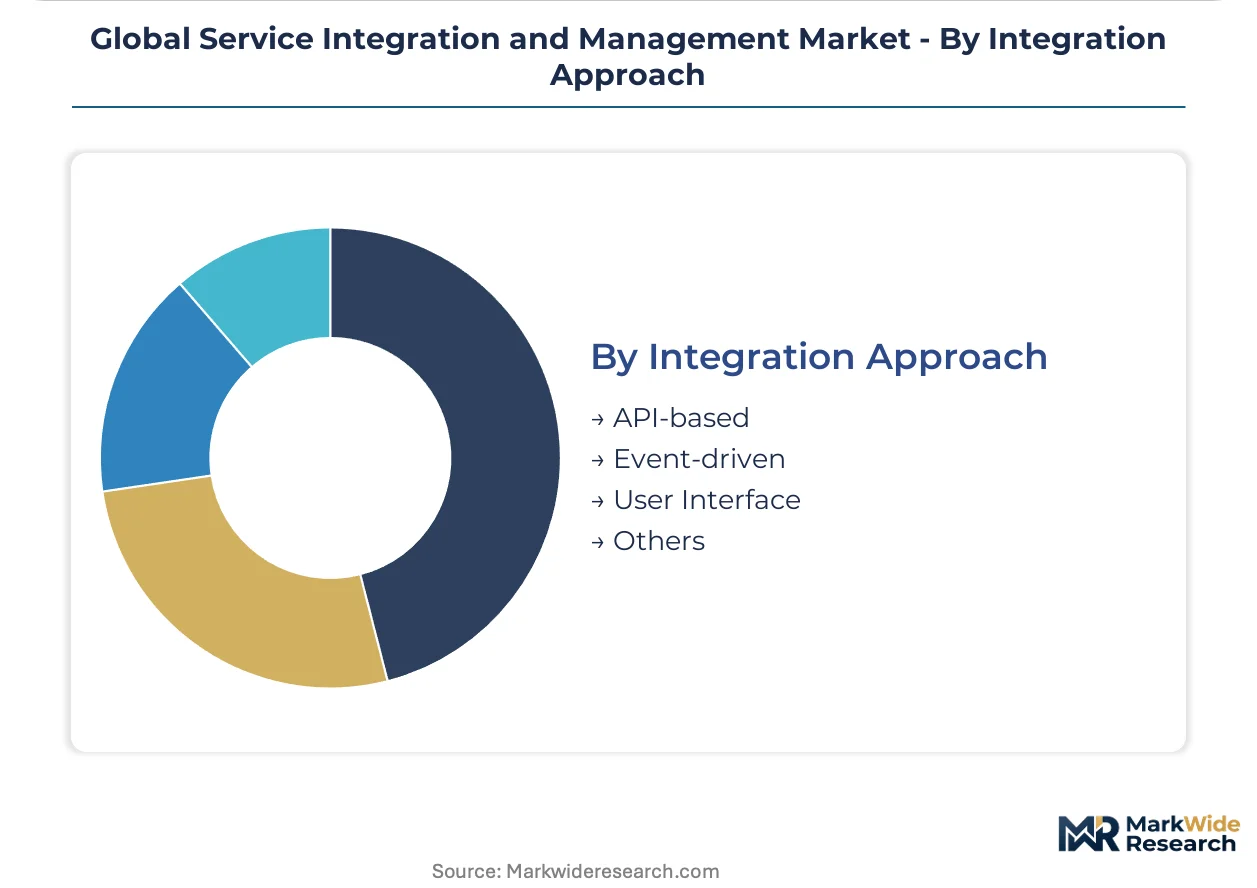
Integration Approach:
Technical debt accumulation in legacy middleware is forcing architectural pivots toward real-time interoperability mechanisms.
- API-based:REST and GraphQL interfaces enable real-time data exchange without custom code maintenance, capturing disproportionate margin pools. Automotive manufacturers in Stuttgart deploy API meshes to synchronize supplier production schedules with assembly line telemetry. The approach absorbs integration workloads previously handled by enterprise service buses.
- Event-driven:Asynchronous messaging architectures process high-velocity telemetry from industrial sensor networks and edge computing platforms. Manufacturing IoT integration in German industrial corridors demands this capability for predictive maintenance ecosystems.
- User Interface:Screen-scraping and robotic process automation bridge legacy systems lacking programmatic interfaces.
- Others:File-based batch transfers and message queue intermediaries persist in mainframe-dependent environments.
API-based approaches command premium positioning now. Event-driven architectures are expanding most quickly as IoT sensor density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and industrial conglomerates in Stuttgart and Wolfsburg anchor demand for multi-tier supplier-integrated service architectures. Cloud migration mandates under GDPR and the EU AI Act reshape procurement patterns across financial services and manufacturing clusters. Regulatory fragmentation across data residency regimes complicates cross-border delivery models for managed services integrators.
United States
Financial services institutions in New York and Chicago drive hybrid SIAM adoption for multi-vendor IT ecosystem unification. NIST cybersecurity frameworks tighten vendor audit protocols and extend qualification cycles for cross-border delivery architectures. Healthcare providers in Boston and Minneapolis require HIPAA-compliant service orchestration for clinical system segregation.
Germany
Automotive OEMs in Munich and Stuttgart operate complex Tier-1 through Tier-3 supplier-integrated service models demanding unified governance. The EU AI Act imposes algorithmic transparency requirements on automated incident routing decisions. Industrial conglomerates in Wolfsburg deploy API mesh architectures to synchronize supplier production schedules with assembly line telemetry.
India
The Digital Personal Data Protection Act creates captive delivery requirements favoring integrators with Mumbai and Hyderabad operational hubs. RBI and SEBI guidelines impose data localization mandates on financial services SIAM architectures. IT services clusters in Bangalore concentrate specialized talent pools, creating wage inflation pressure for managed services contracts.
United Kingdom
Financial institutions in London modernize legacy middleware stacks through professional services engagements with outcome-based contracting models. GDPR and emerging UK data protection frameworks reshape cross-border service flow architectures. Mainframe-dependent banking infrastructure in the City requires custom API gateways extending implementation timelines.
Japan
Manufacturing conglomerates in Toyota City and Osaka demand real-time service orchestration across predictive maintenance ecosystems. METI data governance guidelines tighten vendor certification protocols for industrial IoT integration. Edge computing deployments in Nagoya industrial corridors require low-latency service orchestration across infrastructure partners.
Global Service Integration and Management Market Competitive Environment
Strategic partnerships dominate the current landscape as integrators rebuild pricing models around real-time interoperability. The vendor base organizes into three tiers: global consultancies with outcome-based contracting capabilities, IT services specialists with deep vertical expertise, and technology vendors anchoring hybrid cloud deployments. Two strategic archetypes prevail: ITIL-process-heavy managed services providers and API-first integration specialists. Competitive moves concentrate on portfolio diversification into AI governance compliance services and geographic expansion into India captive delivery hubs.
Within the technology-anchored tier, IBM Corporation exemplifies hybrid cloud SIAM deployment capabilities across regulated industries. HCL Technologies Limited and Accenture PLC occupy positions on the vertical specialization and outcome-based contracting vectors respectively. These three entities represent distinct competitive positioning strategies: technology stack leverage, deep manufacturing and telecom expertise, and performance-tied fee structures. Each archetype captures margin pools through differentiated governance models rather than commodity service delivery.
| Leading Market Players |
|---|
| IBM Corporation |
| HCL Technologies Limited |
| Accenture PLC |
| Fujitsu |
| TATA Consultancy Services Limited |
| DXC Technology Company |
| CGI Inc |
| Atos SE |
| Infosys Limited |
| Others |
Value Chain & Pricing Dynamics
Specialized SIAM talent concentration in Bangalore and Frankfurt feeds directly into three-tier pricing structures across premium, standard, and economy service levels, with wage inflation pressure compressing margins at the mid-tier while premium integrators capture algorithmic transparency premiums under EU AI Act mandates.
Pricing Analysis
Input-cost pass-through from specialized practitioner wages in Indian IT clusters and German industrial corridors intensifies pricing pressure at the standard tier, where managed services contracts face margin compression. Price differentiation hinges on ITIL v4 certification density and DevSecOps pipeline integration depth, with outcome-based contracting commanding premiums in Stuttgart automotive procurement. Cost compression in professional services is intensifying because buyers unbundle implementations into modular statements of work. Mid-market financial institutions in Frankfurt exhibit highest price sensitivity, while German automotive OEMs in Munich demonstrate lowest sensitivity when fees tie to measurable mean-time-to-resolution improvements.
Supply Chain Analysis
Logistics and freight cost elevation for cross-border service delivery complicates multi-country architectures under India's Digital Personal Data Protection Act localization mandates. Supply concentrates in India, Germany, and the United States, drawing from specialized talent pools, proprietary integration platforms, and regulatory compliance frameworks. Raw material dependencies rest on API gateway infrastructure, event-driven middleware licenses, and cloud compute capacity. Single-source vulnerability concentrates in Bangalore for ITIL-certified practitioners. Distribution runs through direct enterprise sales, systems integrator partnerships, and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as EU digital sovereignty mandates institutionalize hybrid cloud governance across financial services and automotive supply chains, embedding recurring revenue streams.
For Market Incumbents: Anticipate margin erosion from API-first specialists by embedding explainability layers into multi-vendor governance dashboards ahead of EU AI Act enforcement. Fortify position through backward integration into Red Hat-aligned hybrid cloud stacks and captive talent acquisition in Hyderabad operational hubs. For New Entrants and Emerging Players: Launch via outcome-based contracting models targeting mid-tier BFSI institutions in London modernizing legacy middleware stacks. White-space concentrates in AI governance compliance-as-a-service and manufacturing IoT integration for predictive maintenance ecosystems. Go-to-market angle: modular, short-cycle engagements unbundled from long-term managed services contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where vertical specialization in manufacturing and telecom service towers intersects with captive delivery capabilities under Indian localization mandates. Long-term viability favors integrators with ITIL-process-heavy managed services revenue anchored in German automotive procurement. Acquisition target archetype: API-first integration specialists with event-driven architecture expertise. Signal to watch: Tier-1 automotive OEM procurement consolidation of vendor management authority in German-speaking industrial corridors.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Compliance Service Launch | EU AI Act algorithmic transparency rules intersect with GDPR data residency requirements in Frankfurt banking. |
| India Captive Delivery Hub Expansion | Digital Personal Data Protection Act mandates favor integrators with Mumbai and Hyderabad operational presence. |
| Event-Driven Architecture Platform Integration | Automotive manufacturers in Stuttgart deploy API meshes to synchronize supplier production schedules. |
| Outcome-Based Contracting Model Adoption | Munich automotive OEMs negotiate SIAM fees tied to measurable mean-time-to-resolution improvements. |
| Manufacturing IoT Integration Partnership | Industrial sensor networks in Wolfsburg demand real-time service orchestration across predictive maintenance ecosystems. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with SIAM practice leads, IT procurement officers at automotive OEMs, regulatory compliance directors, and cloud platform engineers with secondary validation through SEC filings, EU regulatory submissions, hyperscaler capex disclosures, and IT services contract databases. Bottom-up and top-down triangulation cross-checks vendor revenue disclosures against enterprise spend patterns.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window, modeling deployment model shifts, integration approach transitions, and vertical migration patterns. Segmentation dimensions include service type, industry vertical, deployment architecture, and geographic regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for policy inflection points, with EU AI Act implementation timelines and India localization mandate phase-ins as specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated cloud exit timelines or prolonged certification delays from NIST cybersecurity framework tightening. Forecasts reflect documented assumptions about regulatory enforcement intensity and talent pool elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Virtual Hiring Tools Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
APAC Digital Signage Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Container Orchestration Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Change Management Software Market
Digital Solutions
Digital String Encoder Market