
 Electronic Data Interchange [EDI] Solution Market | 2026-2036
Electronic Data Interchange [EDI] Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Data Interchange [EDI] Solution Market Foresight
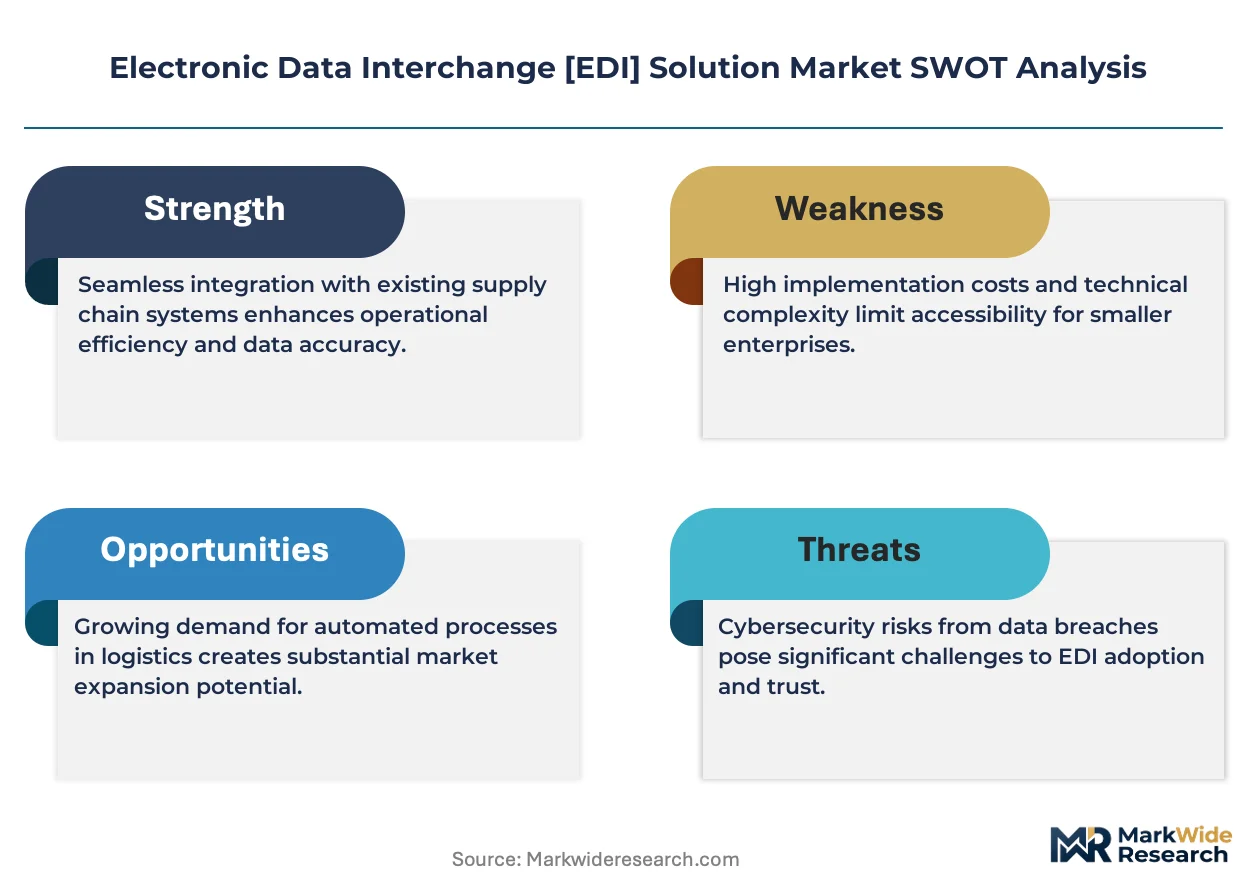
API-first architecture is tilting EDI delivery away from legacy point-to-point connections toward composable integration platforms. SPS Commerce leverages cloud-native infrastructure to dominate retail supply chain onboarding. TrueCommerce anchors its position through multi-enterprise connectivity spanning suppliers, logistics providers, and marketplaces. Cleo specializes in hybrid integration that bridges traditional EDI with modern application programming interfaces.
Electronic Data Interchange [EDI] solutions are standardized software systems that translate business documents into structured formats such as ANSI X12 or EDIFACT for automated computer-to-computer exchange between trading partners, operating through value-added networks or direct AS2 protocols to eliminate manual data re-entry. Their primary commercial purpose is to accelerate order-to-cash and procure-to-pay cycles while reducing transcription errors in high-volume B2B transactions. Cloud-based deployment represents the fastest-expanding solution type as enterprises retire on-premises translation engines and embrace consumption-based pricing models. Within industry verticals, healthcare claims processing and automotive supplier networks generate the deepest margin pools due to compliance complexity and stringent SLA requirements.
FDA 21 CFR Part 11 requirements for electronic records in pharmaceutical supply chains, HIPAA transaction standards for healthcare administrative simplification, and the EU GDPR framework for cross-border data flows all shape product design and market access for EDI vendors serving regulated industries. The SEC's mandate for inline XBRL financial reporting further extends structured data exchange requirements into capital markets. Stakeholders must evaluate whether their integration architecture can absorb emerging real-time payment rails and sustainability disclosure standards without fragmenting existing trading partner connectivity.
Market Dynamics
API-first integration architectures are compressing traditional value-added network margins while fragmenting vendor control over trading partner onboarding workflows.
Growth Catalysts
- HIPAA Transaction Mandates:Healthcare administrative simplification requirements in the United States are forcing claims processors to retire paper-based workflows. Payers and providers must achieve electronic eligibility verification and remittance advice exchange.
- Real-Time Payment Rails:The Federal Reserve's FedNow Service and comparable instant settlement infrastructure are creating technical imperatives for synchronous data exchange. Financial institutions require sub-second transaction confirmation.
- Automotive Supplier Networks:OEM just-in-sequence manufacturing protocols in Germany and Japan demand millisecond-accurate shipment notifications. Tier-1 suppliers face contractual penalties for ASN transmission delays.
Market Restraints
- Legacy AS2 Protocol Lock-In:Established direct-connect infrastructure carries substantial sunk costs and contractual minimums. Trading partners resist migration to modern alternatives despite superior functionality.
- Translation Engine Talent Scarcity:Specialized expertise in ANSI X12 and EDIFACT mapping conventions commands premium compensation. Vendor implementation timelines extend due to qualified engineer shortages.
- Cloud Concentration Risk:Hyperscaler infrastructure dependencies create single-point-of-failure exposure for multi-tenant EDI platforms. Downtime incidents cascade across thousands of simultaneous trading relationships.
Strategic Opportunities
- Carbon Disclosure Integration:The EU CSRD mandates granular supply chain emissions reporting. EDI platforms can embed Scope 3 data fields within existing purchase order and invoice transactions.
- Small-Business Onboarding:Mid-market retailers in India lack technical resources for traditional EDI implementation. Self-service API portals with pre-built connector libraries address this accessibility gap.
- Blockchain-EDI Convergence:Distributed ledger technology offers immutable audit trails for pharmaceutical pedigree verification. FDA DSCSA compliance deadlines create immediate addressable demand.
Industry Challenges
- Map Version Synchronization:Trading partners operate incompatible document revision levels. Version drift produces validation failures requiring manual intervention.
- Hybrid Integration Complexity:Enterprises maintain simultaneous requirements for traditional EDI, modern APIs, and flat-file exchange. Unified monitoring across protocol stacks demands specialized tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Data Interchange [EDI] Solution Market |
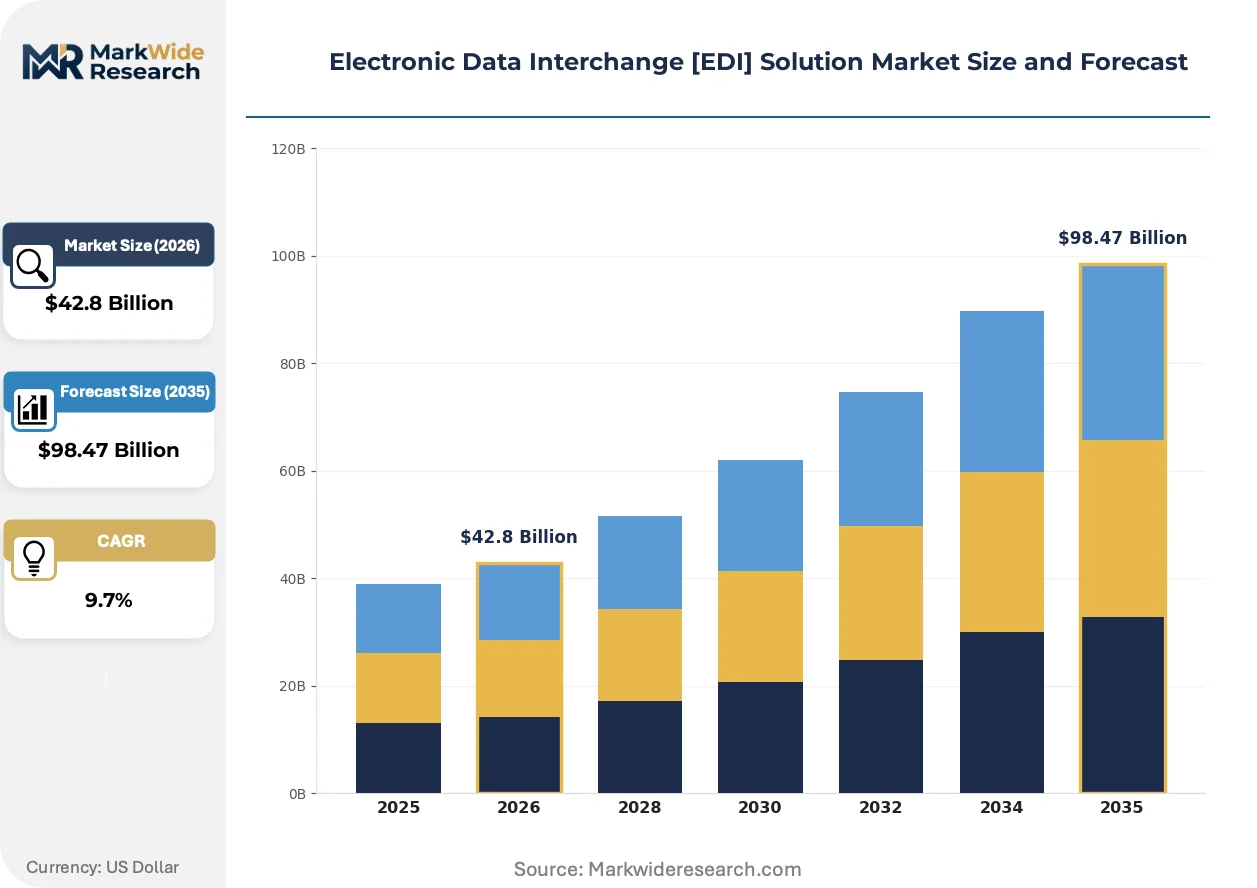
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $98.47 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-based, On-premises, Hybrid, Managed Services Industry Vertical: Retail, Automotive, Healthcare, Manufacturing Deployment Model: Public Cloud, Private Cloud, Dedicated Server, Multi-tenant Integration Level: Full Integration, Partial Integration, Standalone, API-based |
| Companies Covered | SPS Commerce, TrueCommerce, Cleo, Boomi, OpenText, Software AG, MuleSoft, EDICOM, Jitterbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Data Interchange [EDI] Solution Market Shifts & Advancements
Composable integration platforms are displacing monolithic translation engines. Vendors now compete on ecosystem connectivity density rather than protocol support breadth alone.
Embedded AI-powered data validation is digitizing exception handling workflows. Machine learning models trained on historical transaction patterns identify anomalies in purchase order acknowledgments before downstream propagation. Retailers with high SKU velocity are deploying these capabilities to compress order-to-ship cycle times.
The FDA's DSCSA implementation timeline is mandating serialized product identifiers across pharmaceutical supply chains. Wholesale distributors must verify saleable returns through interoperable data exchange. Manufacturers are accelerating EDI infrastructure upgrades to accommodate verification router requirements before enforcement deadlines.
Subscription-based pricing models are displacing per-transaction fee structures. Enterprise procurement teams prefer predictable operational expenditure over variable costs tied to seasonal volume spikes. This shift concentrates vendor revenue in annual recurring contracts rather than usage-based billing.
Electronic Data Interchange [EDI] Solution Market Segmentation
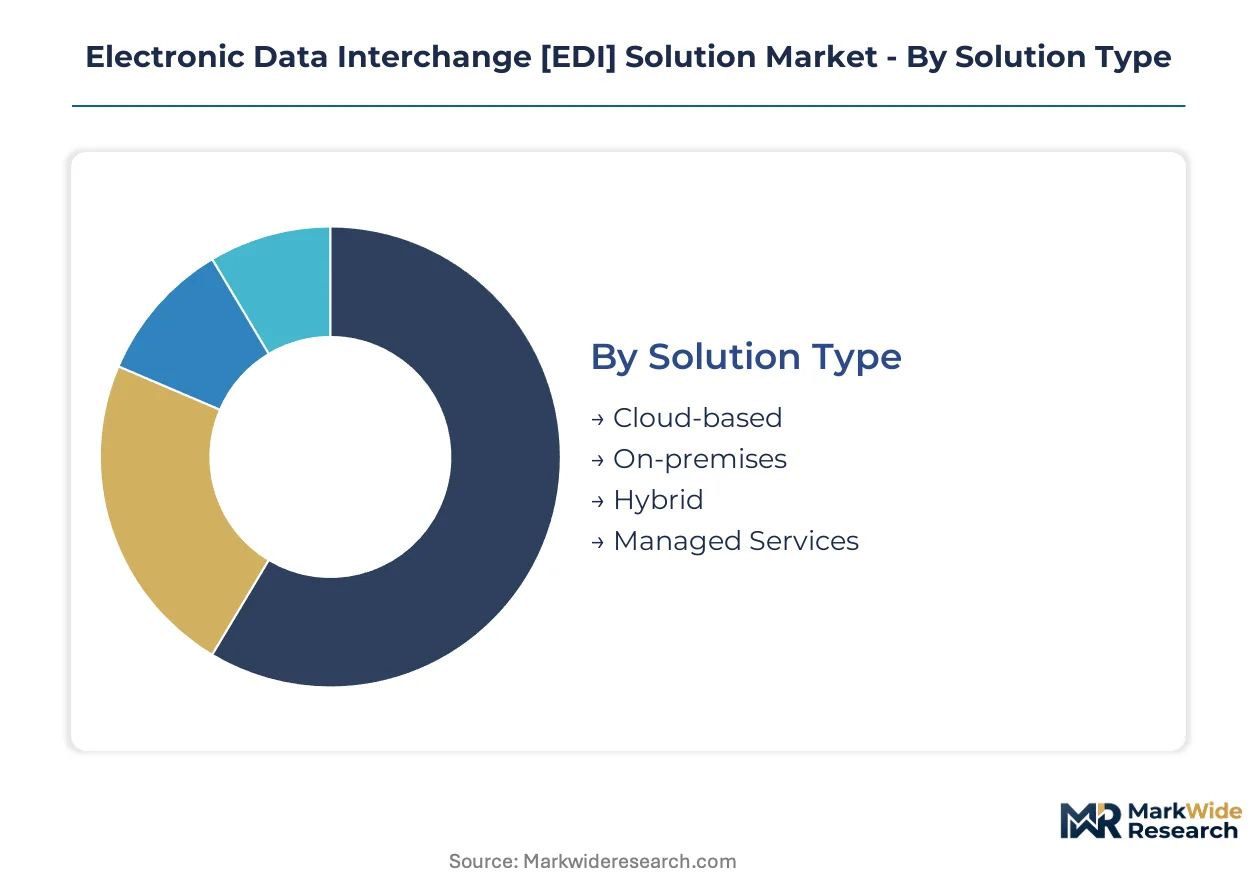
EDI solution segmentation reveals how deployment architecture, industry compliance requirements, and integration maturity determine vendor selection criteria. Trading partners prioritize protocol compatibility and data sovereignty controls when evaluating solution categories.
Solution Type:
Cloud-native architectures now span the full spectrum from fully managed SaaS to retained on-premises control for regulated environments.
- Cloud-based:Multi-tenant platforms with consumption-based pricing eliminate capital expenditure for translation engines. Healthcare payers in the United States favor this model for HIPAA-compliant claims processing scalability without infrastructure ownership.
- On-premises:Dedicated hardware deployments retain data within corporate firewalls for pharmaceutical manufacturers facing FDA 21 CFR Part 11 audit requirements. German automotive OEMs mandate this architecture for just-in-sequence production data sovereignty.
- Hybrid:Split processing routes sensitive transactions through private infrastructure while leveraging cloud burst capacity for seasonal volume spikes. Retailers deploy this configuration to balance PCI-DSS compliance with Black Friday transaction surges.
- Managed Services:Outsourced EDI operations transfer map development, partner onboarding, and 24/7 monitoring to specialized providers. Mid-market suppliers lacking ANSI X12 expertise contract these services to avoid talent scarcity penalties.
The dominant share belongs to Cloud-based solutions, while Hybrid deployments are closing the gap fastest as enterprises navigate data residency fragmentation.
Industry Vertical:
Regulatory intensity and transaction velocity create divergent technical requirements across buyer industries.
- Retail:High-SKU environments demand real-time inventory synchronization across marketplace endpoints. Walmart and Amazon supplier mandates drive adoption of API-capable EDI for drop-ship fulfillment automation.
- Automotive:OEM just-in-sequence protocols require millisecond-accurate ASN transmission with EDIINT AS2 delivery confirmation. Tier-1 suppliers face contractual penalties for transmission delays disrupting production lines.
- Healthcare:HIPAA transaction standards mandate electronic eligibility verification and remittance advice exchange. Claims processors achieve administrative simplification through X12 5010 compliance automation.
- Manufacturing:Discrete and process manufacturers leverage EDI for supplier collaboration and customer order fulfillment. Complex BOM structures necessitate hierarchical document mapping for component-level visibility.
Retail commands the largest revenue pool, though Healthcare is expanding most quickly under federal mandate pressure.
Deployment Model:
Infrastructure tenancy decisions hinge on data sovereignty, latency requirements, and shared-resource risk tolerance.
- Public Cloud:Shared hyperscaler infrastructure delivers elastic compute for variable transaction volumes. Cost optimization attracts price-sensitive mid-market buyers despite concentration risk exposure.
- Private Cloud:Single-tenant virtualized environments isolate processing resources for enhanced security posture. Financial institutions select this model for FedNow real-time payment rail integration.
- Dedicated Server:Physical hardware assignments guarantee resource availability for SLA-critical operations. Japanese automotive networks specify dedicated infrastructure for METI-compliant supply chain continuity.
- Multi-tenant:Logical separation within shared platforms maximizes vendor operational efficiency. Economies of scale enable competitive pricing for small-business supplier onboarding programs.
Public Cloud holds majority adoption, yet Private Cloud is gaining share fastest among regulated industries.
Integration Level:
Connectivity depth determines whether EDI functions as standalone translation or embedded within broader enterprise architecture.
- Full Integration:Native ERP connectors synchronize EDI transactions directly into financial and inventory systems. SAP and Oracle environments demand pre-certified adapters for procure-to-pay automation.
- Partial Integration:Selective data flows bridge EDI with core systems while maintaining manual touchpoints for exception handling. This approach suits enterprises with legacy mainframe dependencies.
- Standalone:Self-contained translation engines operate independently of back-office systems. Small trading partners deploy these for basic AS2 connectivity without ERP upgrade requirements.
- API-based:REST and GraphQL interfaces enable real-time data exchange alongside traditional batch EDI. Composable integration platforms favor this architecture for cloud-native trading partner ecosystems.
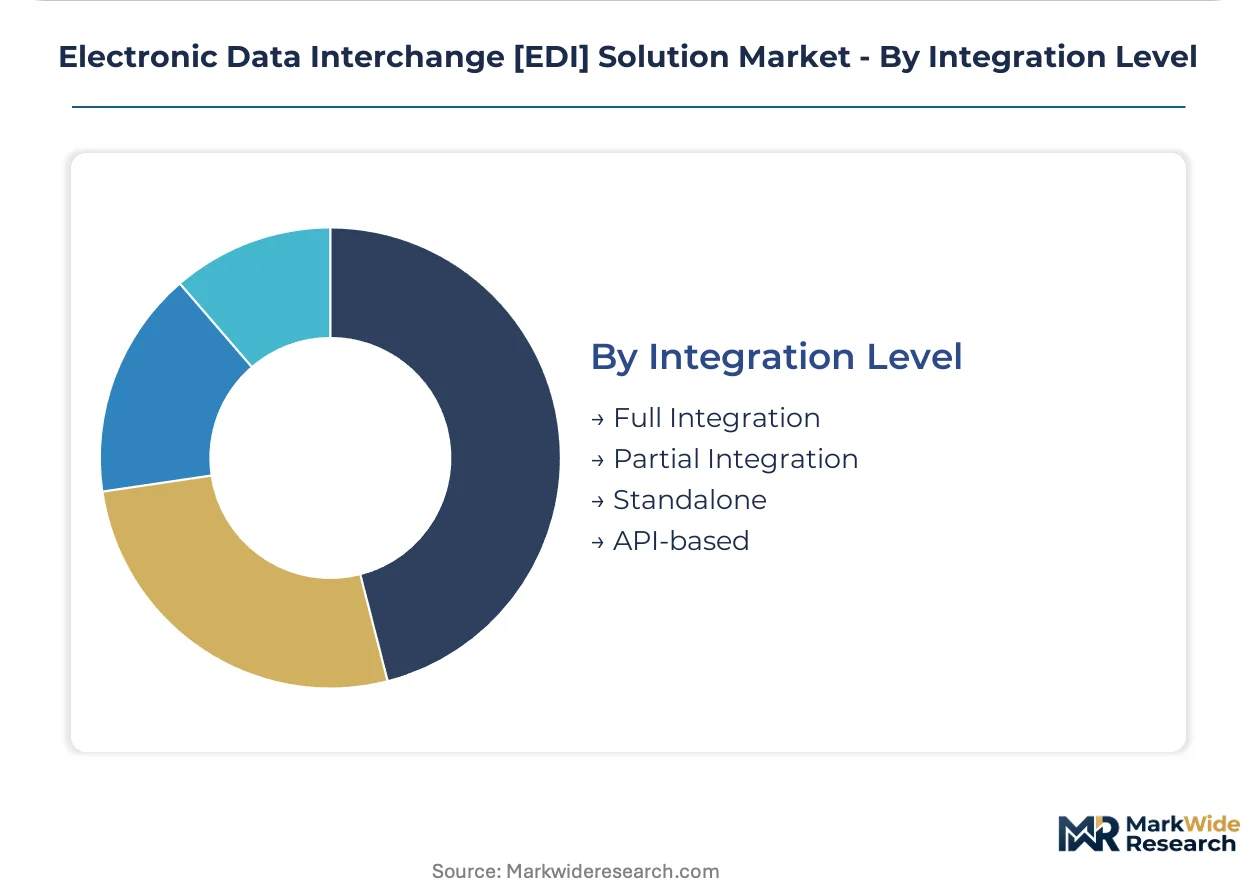
Full Integration retains the largest installed base, while API-based connectivity is climbing the fastest as enterprises modernize integration stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision automotive EDI infrastructure to Japanese OEM supply chains, while US healthcare technology flows into Canadian provincial health networks. These bilateral corridors concentrate solution deployment density and shape vendor localization priorities.
United States
FedNow real-time payment rails and HIPAA transaction mandates drive healthcare payer modernization. The SEC mandates inline XBRL financial reporting for capital markets disclosure automation. Healthcare technology clusters in Boston and Nashville process claims through cloud-native EDI platforms at scale.
Germany
Automotive OEM just-in-sequence manufacturing protocols demand millisecond-accurate ASN transmission. METI-aligned supply chain continuity requirements influence data sovereignty specifications. The Baden-Württemberg automotive belt hosts Tier-1 supplier networks with stringent EDI SLA enforcement.
Japan
Pharmaceutical wholesale distributors face FDA DSCSA-equivalent serialization deadlines for product verification. METI governs supply chain data exchange standards for manufacturing continuity. The Chubu region around Nagoya anchors precision supplier networks with embedded EDI compliance.
India
Mid-market retailers lack technical resources for traditional EDI implementation, creating self-service API demand. RBI payment system modernization drives synchronous data exchange requirements. Mumbai and Bangalore logistics hubs deploy cloud-based supplier onboarding platforms for export compliance.
United Kingdom
Post-Brexit customs documentation complexity accelerates trade facilitation EDI adoption. GDPR cross-border data flow frameworks shape platform architecture decisions. London financial services clusters integrate real-time payment messaging with legacy SWIFT infrastructure.
Electronic Data Interchange [EDI] Solution Market Competitive Landscape
On the supply side, the industry is consolidating around cloud-native integration platforms while fragmenting at the specialized protocol translation tier. Tier-one vendors compete on ecosystem connectivity density rather than protocol breadth alone. Two strategic archetypes dominate: retail supply chain specialists with pre-built supplier networks, and hybrid integration generalists bridging legacy EDI with modern APIs. M&A activity concentrates on API management capabilities, while geographic expansion targets mid-market supplier onboarding in emerging economies.
Within the retail-specialist tier, SPS Commerce exemplifies cloud-native infrastructure dominance through consumption-based pricing models. TrueCommerce occupies a multi-enterprise connectivity position spanning suppliers, logistics providers, and marketplace endpoints. Cleo represents the hybrid integration archetype, bridging traditional ANSI X12 translation with REST API modernization for enterprises navigating protocol migration complexity.
| Leading Market Players |
|---|
| SPS Commerce |
| TrueCommerce |
| Cleo |
| Boomi |
| OpenText |
| Software AG |
| MuleSoft |
| EDICOM |
| Jitterbit |
| Others |
Supply & Pricing Matrix
The Dallas-Fort Worth technology corridor concentrates cloud-native EDI platform development, where hyperscaler infrastructure investments compress marginal delivery costs and transfer pricing power downstream to enterprise procurement teams. This geographic capacity expansion enables consumption-based SaaS models that undercut legacy on-premises licensing structures.
Pricing Analysis
Legacy on-premises translation engines command 40-60% subscription premiums over cloud-native alternatives due to sunk-cost amortization and specialized ANSI X12 engineering talent scarcity. Pricing stratifies across enterprise-grade managed services, mid-market self-service portals, and basic AS2 connectivity tiers. Cost compression in the mid-market segment is intensifying because API-first platforms eliminate per-transaction minimums. Small-business suppliers exhibit highest price sensitivity, while pharmaceutical manufacturers facing FDA 21 CFR Part 11 audits demonstrate lowest elasticity due to compliance-driven procurement mandates.
Supply Chain Analysis
Extended payment terms from hyperscale cloud providers—Amazon Web Services, Microsoft Azure, Google Cloud Platform—enable multi-tenant EDI vendors to defer infrastructure costs while scaling customer acquisition. Software development draws from India, Poland, and Vietnam engineering centers. Single-source vulnerability concentrates in hyperscaler infrastructure dependencies. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and self-service API marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EDI solution market exhibits cyclical recovery characteristics as enterprises accelerate legacy modernization following pandemic-delayed infrastructure investments. HIPAA transaction mandate enforcement and FedNow real-time payment rail deployment constitute the primary cyclical demand drivers.
For Market Incumbents: Harden cloud-native platform resilience against concentration risk exposure through multi-region failover architecture and private cloud alternatives for regulated healthcare payers. Deepen vertical integration into API management capabilities via targeted acquisition of middleware specialists. Defensive consolidation around ecosystem connectivity density—pre-built supplier networks, marketplace endpoints, logistics provider integrations—raises switching costs against API-first challengers. For New Entrants and Emerging Players: Establish a beachhead in mid-market retail supplier onboarding across India and Southeast Asia, where technical resource constraints block traditional EDI implementation. Carbon disclosure integration for EU CSRD compliance represents immediate white-space opportunity with pre-built Scope 3 data field templates. Self-service API portals with localized language support and pre-certified connector libraries constitute the optimal go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid integration generalists bridging legacy ANSI X12 translation with modern REST API architectures, as enterprises navigate decade-long protocol migration complexity. Long-term viability rests on annual recurring revenue concentration and trading partner network effects rather than transactional volume exposure. Watch for FDA DSCSA enforcement deadline acceleration as inflection indicator for pharmaceutical supply chain infrastructure upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Migration | Enables real-time FedNow payment rail integration for financial institutions. |
| Carbon Disclosure Field Embedding | Addresses EU CSRD Scope 3 reporting mandates within existing transaction flows. |
| Multi-Region Hyperscaler Diversification | Mitigates single-point-of-failure exposure for HIPAA-critical healthcare operations. |
| Self-Service Supplier Onboarding Portal | Captures mid-market retail demand in India lacking ANSI X12 technical resources. |
| Blockchain Verification Router Integration | Satisfies FDA DSCSA serialized product identifier requirements for pharmaceutical distributors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K infrastructure disclosures, hyperscaler capex reports, and HIPAA transaction standard implementation documentation. Conversations with EDI platform CTOs, healthcare payer IT procurement officers, retail supply chain directors, and systems integrator partners informed demand-side validation. Bottom-up segment sizing triangulates against top-down market aggregation across deployment architecture, industry vertical, and integration maturity dimensions.
Forecast inputs include cloud adoption curves, regulatory mandate timelines, and trading partner onboarding velocity across the projection horizon. Segmentation models capture solution type, industry vertical, deployment model, and integration level. CAGRs derive from installed base migration rates and new customer acquisition patterns. API transaction volume growth and legacy AS2 protocol retirement schedules constitute industry-specific forecast sensitivity parameters.
Stress conditions across hyperscaler pricing volatility, HIPAA enforcement intensity, and real-time payment rail adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding enterprise cloud migration willingness and trading partner interoperability standards. Macroeconomic contraction, regulatory enforcement delay, or generative AI-driven document automation disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Service Integration and Management Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
Digital Onboarding Software Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Game Engines Market
Digital Solutions
Conference Room Solutions Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
E-Ink E-Reader Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Global Data Historian Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Trade Management Software Market
Digital Solutions
Digital Library Software Market