
 Smart Card Reader Market | 2026-2036
Smart Card Reader Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Card Reader Market Outlook
Banking sector procurement is recalibrating terminal deployment priorities as contactless payment mandates expand across merchant networks. Thales leverages its aerospace and defense credentialing heritage to dominate high-assurance government identity projects. HID Global anchors enterprise access control integration through its embedded reader module ecosystem. Identiv specializes in NFC-enabled healthcare credentialing for hospital network access management.
A smart card reader is an electronic device that interfaces with integrated circuit cards through physical contact or proximity RF fields, typically operating at 13.56 MHz for NFC protocols or ISO 7816 standards for contact interfaces, to authenticate identity or authorize transactions in secure access and payment systems. Contactless readers lead volume deployment in retail environments where transaction speed governs checkout throughput, while biometric readers command premium positioning in government and defense segments where multi-factor authentication is non-negotiable. USB-connected desktop units retain manufacturing scale advantages for enterprise fleet rollouts despite Bluetooth mobility gains in field service applications.
FCC certification requirements govern RF emissions for contactless readers sold in the United States, while ETSI standards and CE marking regulate European market access for NFC-enabled terminals. PCI DSS compliance mandates from the payment card industry reshape hardware security module integration requirements across all reader categories. Stakeholders must monitor evolving quantum-resistant cryptography standards from NIST and their impending impact on secure element architectures.
Market Dynamics
EMV compliance deadlines and contactless payment mandates are compressing terminal replacement cycles across merchant acquirer networks, forcing simultaneous hardware refresh and security certification investments.
Growth Catalysts
- RBI Tokenization Guidelines:India's central bank mandates for payment tokenization are accelerating domestic manufacturing scale-up for contactless readers across merchant networks.
- PCI DSS Certification Requirements:Payment card industry security standards are mandating hardware security module integration, driving replacement demand across legacy terminal estates.
- NFC Technology Migration:Retail checkout throughput requirements are displacing magnetic stripe infrastructure with 13.56 MHz contactless interfaces at point-of-sale terminals.
Market Restraints
- Semiconductor Supply Concentration:Secure element chip fabrication concentrates in Taiwan and South Korea, creating single-source vulnerability for reader manufacturers.
- ETSI RF Certification Complexity:European harmonized standards for NFC emissions require multi-country testing protocols, extending time-to-market for new reader models.
- Biometric Sensor Cost Structure:Fingerprint and iris modules command 40-60% hardware cost premiums, limiting deployment to high-assurance government identity projects.
Strategic Opportunities
- Healthcare Credential Convergence:Hospital network access management systems are integrating NFC-enabled staff badges with patient record authentication, opening new vertical demand.
- PLI Scheme Manufacturing Incentives:India's production-linked incentive scheme for electronics manufacturing is attracting component localization investments for reader assembly.
- Quantum-Resistant Cryptography Standards:NIST post-quantum cryptographic guidelines will mandate secure element architecture redesigns, creating upgrade cycles for installed base.
Industry Challenges
- FCC and CE Dual Certification Timelines:Simultaneous RF emissions compliance for US and European markets requires parallel testing tracks, compressing product launch windows.
- Legacy ISO 7816 Integration Complexity:Contact interface readers must maintain backward compatibility with decades-old smart card formats while adding NFC functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Card Reader Market |
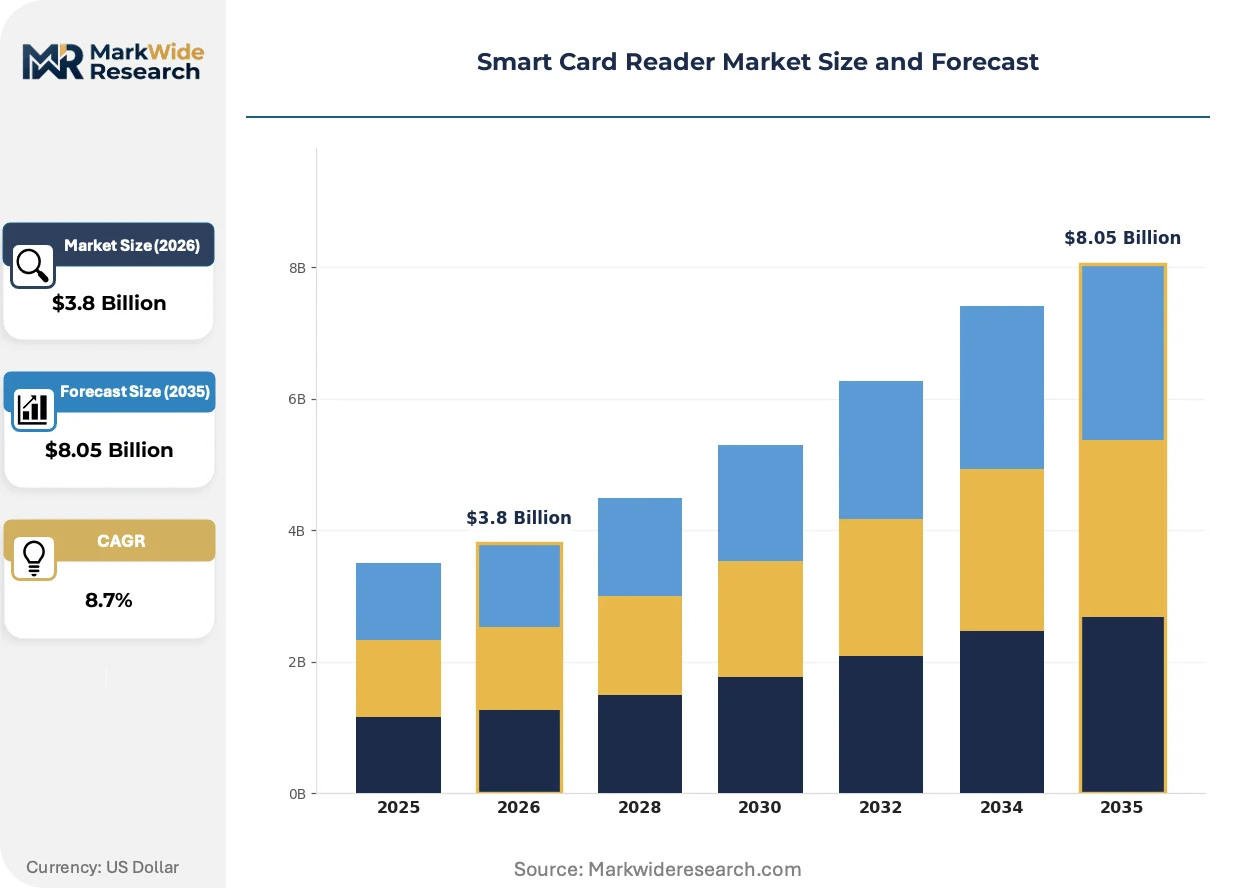
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Stripe Reader, Contactless Reader, EMV Chip Reader, Biometric Reader Technology: RFID, NFC, Bluetooth, USB Application: Payment Processing, Access Control, Identification, Loyalty Programs End User: Retail, Banking, Healthcare, Government |
| Companies Covered | Allegion plc, Thales, Advanced Card Systems Ltd., HID Global, IDEMIA, ASSA ABLOY AB, Identiv, Inc., NXP Semiconductors, dormakaba Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Card Reader Market Strategic Shifts
Secure credential authentication is fragmenting across distributed verification architectures, moving trust boundaries from centralized servers to edge devices and mobile handsets.
Embedded secure elements within smartphone handsets are decentralizing physical reader dependency for low-value transactions. Transit authorities in London and Tokyo now accept direct NFC handset tap without dedicated terminal infrastructure. This displacement is compressing unit demand for standalone readers in transportation and quick-service retail segments.
ETSI standards for NFC reader RF emissions are tightening field strength tolerances across European member states. Terminal manufacturers must redesign antenna matching circuits to comply with revised harmonized spectrum masks. Germany and France are enforcing pre-market conformity assessment procedures that add 8-12 weeks to certification timelines.
Merchant acquirers are unbundling terminal hardware from payment processing contracts, shifting procurement toward direct OEM relationships. Large retail chains in India and Brazil now negotiate reader purchases separate from merchant service agreements. This disintermediation is pressuring traditional distributor margins while rewarding manufacturers with direct certification capabilities and in-country service networks.
Smart Card Reader Market Segmentation
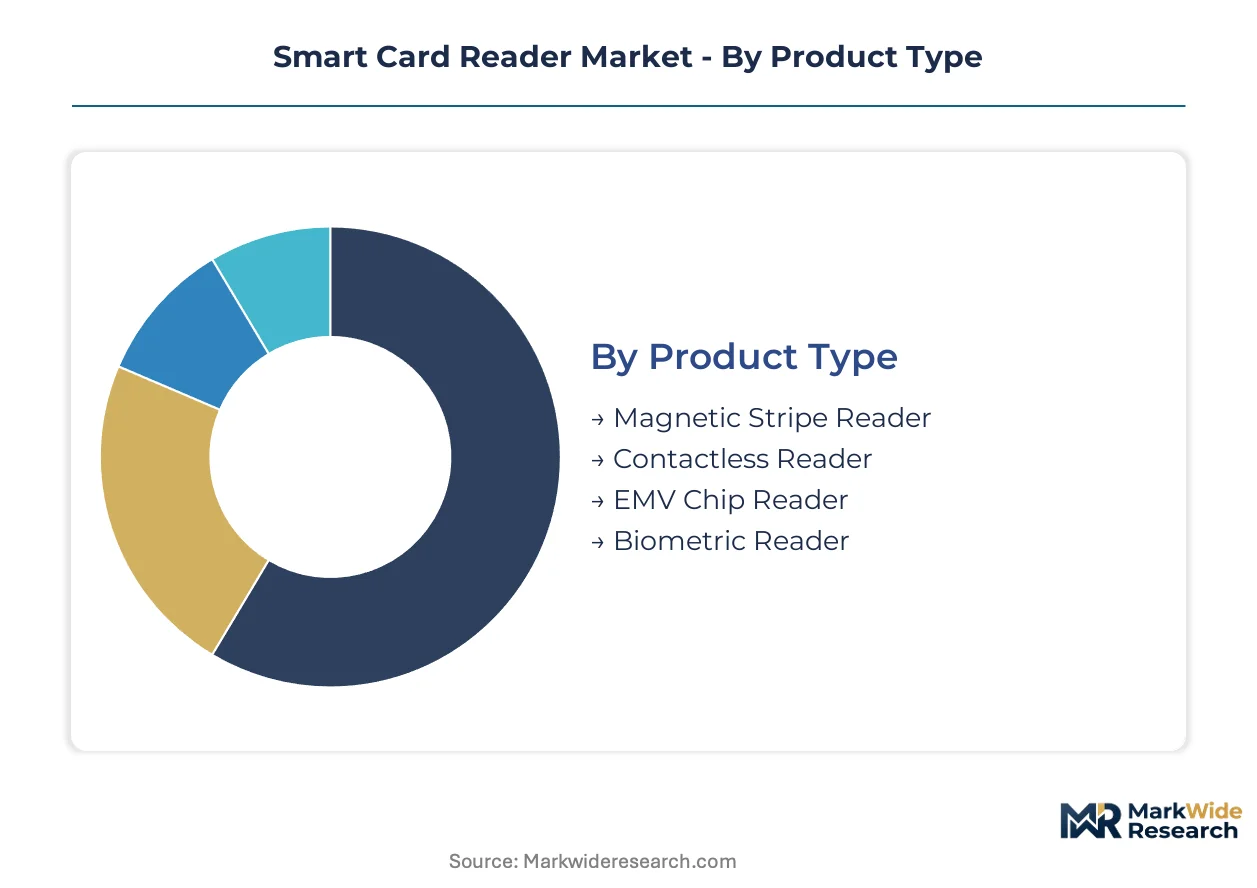
Smart card reader procurement decisions diverge sharply across deployment contexts, with payment networks prioritizing transaction velocity while defense agencies demand biometric multi-factor assurance. Component sourcing strategies and certification requirements vary dramatically by segment, reshaping manufacturer competitive positioning.
Product Type:
Secure element chip fabrication concentrates in Taiwan and South Korea, creating divergent supply risk profiles across reader categories with varying silicon intensity.
- Contactless Reader:These 13.56 MHz NFC terminals dominate retail point-of-sale deployments where checkout throughput governs merchant acquirer procurement. India's Reserve Bank tokenization mandates are accelerating domestic manufacturing scale-up for contactless infrastructure across merchant networks.
- Biometric Reader:Fingerprint and iris authentication modules integrate capacitive sensors with ISO 7816-compliant secure elements for high-assurance identity verification. Government identity projects in India and defense credentialing programs absorb 40-60% hardware cost premiums for multi-factor authentication capability.
- Magnetic Stripe Reader:Legacy swipe interfaces retain installed base in budget-constrained merchant segments requiring backward compatibility with decades-old card formats.
- EMV Chip Reader:Contact-based ISO 7816 terminals serve banking networks where EMV compliance deadlines force simultaneous hardware refresh and PCI DSS certification investments.
Today's leader: Contactless Reader. Tomorrow's challenger: Biometric Reader.
Technology:
RF front-end design complexity and antenna matching requirements create tiered cost structures across interface protocols.
- NFC:Operating at 13.56 MHz with standardized modulation schemes, this protocol enables tap-to-pay transactions with sub-400 millisecond latency requirements. Transit authorities in London and Tokyo now accept direct handset tap, compressing standalone reader demand in transportation segments.
- RFID:Ultra-high frequency and low-frequency variants serve access control and asset tracking applications where read range exceeds NFC proximity constraints. Manufacturing concentration in Shenzhen and Dongguan clusters creates procurement leverage for enterprise fleet buyers.
- Bluetooth:Wireless personal area connectivity enables mobile point-of-sale flexibility for field service and pop-up retail applications.
- USB:Wired desktop interfaces retain manufacturing scale advantages for enterprise fleet rollouts despite mobility limitations.
NFC commands current volume leadership. Bluetooth is gaining share fastest among micro-merchant segments.
Application:
Security certification intensity and transaction value thresholds segment procurement behavior across use cases.
- Payment Processing:PCI DSS compliance mandates hardware security module integration across all terminal categories, with merchant acquirers unbundling hardware from processing contracts to negotiate direct OEM relationships.
- Access Control:Enterprise physical security systems integrate NFC-enabled credentials with building management platforms, with HID Global's embedded module ecosystem anchoring hospital network deployments.
- Identification:Government credentialing programs demand FIPS 140-2 Level 3+ secure elements with tamper-evident packaging.
- Loyalty Programs:Low-value transaction authentication accepts smartphone-based credential verification without dedicated terminal infrastructure.
Payment Processing dominates revenue concentration. Access Control offers the steepest expansion trajectory through healthcare credential convergence.
End User:
Procurement authority centralization and compliance deadline pressure create divergent sales cycle dynamics across verticals.
- Banking:EMV compliance deadlines and contactless payment mandates compress terminal replacement cycles across merchant acquirer networks, forcing simultaneous hardware refresh and security certification investments.
- Retail:Large chains in India and Brazil negotiate reader purchases separate from merchant service agreements, disintermediating traditional distributors.
- Government:FICAM-compliant identity credentialing programs demand Thales-level assurance with aerospace and defense heritage certification.
- Healthcare:Hospital network access management systems integrate NFC-enabled staff badges with patient record authentication, opening vertical-specific demand for Identiv-specialized credentialing solutions.
Banking anchors near-term procurement volume. Healthcare represents the fastest-climbing opportunity through credential convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling smart card reader assembly toward jurisdictions where FCC and CE dual certification costs compress margins least aggressively. India's PLI scheme and Brazil's local content mandates are redirecting investment flows that previously concentrated in Shenzhen and Taipei.
United States
Merchant acquirers face compressed terminal replacement cycles as PCI DSS mandates force hardware security module integration. FCC certification governs 13.56 MHz RF emissions for contactless readers, with pre-market testing timelines extending 8-12 weeks for antenna redesigns. Dallas and Austin clusters host terminal engineering operations serving North American payment networks.
Germany
ETSI harmonized standards for NFC field strength tolerances are forcing antenna matching circuit redesigns across terminal portfolios. The country's national cybersecurity regulator enforces pre-market conformity assessments that add certification burden. Munich and Stuttgart industrial zones concentrate secure element integration facilities for European banking networks.
India
RBI tokenization guidelines and Payments Council of India interoperability standards are accelerating domestic manufacturing scale-up. The PLI scheme for electronics manufacturing attracts component localization investments for reader assembly. Bengaluru and Hyderabad clusters host merchant acquirer procurement operations negotiating direct OEM relationships outside traditional distributor channels.
Brazil
Large retail chains negotiate reader purchases separate from merchant service agreements, disintermediating traditional payment processing distributors. The country's central bank mandates contactless payment infrastructure expansion across merchant networks. São Paulo industrial districts concentrate terminal assembly operations serving Latin American acquirer networks.
China
Shenzhen and Dongguan manufacturing clusters retain procurement leverage for enterprise fleet buyers despite certification-driven cost pressures. GB standards for RF emissions create parallel testing tracks for domestic versus export-bound production lines. Shanghai and Beijing host payment processor engineering centers specifying reader requirements for Asia-Pacific deployment.
Smart Card Reader Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers add domestic assembly lines to satisfy India's PLI scheme and Brazil's local content thresholds. The vendor base stratifies across three tiers: diversified security conglomerates with aerospace heritage, specialized access control module suppliers, and contract manufacturers serving merchant acquirer direct procurement. Two competitive vectors shape positioning: M&A activity consolidating payment terminal engineering capabilities, and strategic partnerships disintermediating traditional distributor networks in favor of direct OEM relationships with large retail chains.
Within the diversified security tier, Thales and HID Global occupy positions shaped by credentialing heritage and embedded module ecosystems respectively. Identiv represents the specialized healthcare credentialing archetype, anchoring hospital network access management deployments. These three companies exemplify how competitive positioning fragments across payment velocity, government assurance, and healthcare convergence vectors rather than consolidating around uniform technology platforms.
| Leading Market Players |
|---|
| Allegion plc |
| Thales |
| Advanced Card Systems Ltd. |
| HID Global |
| IDEMIA |
| ASSA ABLOY AB |
| Identiv, Inc. |
| NXP Semiconductors |
| dormakaba Holding AG |
| Others |
Value Chain & Pricing Dynamics
RF antenna engineering talent concentrated in Shenzhen and Taipei drives labor-cost differentials that separate premium-certified terminals from economy-grade merchant hardware. These regional wage spreads translate directly into three-tier pricing structures where FCC and CE dual-certified units command substantial premiums over single-market alternatives.
Pricing Analysis
Distributor margins are compressing as large retail chains in India and Brazil negotiate direct OEM relationships outside traditional payment processor channels. Three-tier pricing structure across premium, standard, and economy levels separates biometric-enabled government terminals from contactless retail units and legacy magnetic stripe hardware. Cost compression in the standard tier is intensifying because merchant acquirers unbundle hardware from processing contracts. Small merchants and micro-merchants exhibit highest price sensitivity, while defense agencies and national identity programs demonstrate lowest sensitivity due to FIPS 140-2 certification requirements.
Supply Chain Analysis
Refurbishment flows for enterprise fleet rollouts create secondary supply channels that compete with new unit sales in budget-constrained segments. Secure element chip fabrication concentrates in Taiwan and South Korea, while final assembly clusters in Shenzhen, Dongguan, and Bengaluru. Component sourcing draws from NXP Semiconductors for NFC controllers, specialized antenna substrate suppliers, and PCI DSS-certified hardware security module vendors. Single-source vulnerability in secure element fabrication represents the dominant structural risk. Distribution runs through merchant acquirer networks, direct OEM procurement teams, and government contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart card reader market represents a late-cycle quality story where procurement is shifting toward premium specifications. Banking sector EMV compliance deadlines and contactless payment mandates favor manufacturers with dual-certification capabilities and established in-country service networks.
For Market Incumbents: Cement market position by deepening backward integration into secure element sourcing and expanding domestic assembly capacity under India's PLI scheme. The threat of embedded smartphone NFC displacing standalone terminals in transportation segments demands counter-positioning through healthcare credential convergence and government identity projects. Certification investment in quantum-resistant cryptography standards serves as the critical defensive lever.
For New Entrants and Emerging Players: Begin with hospital network access management deployments where Identiv has established credentialing templates but capacity constraints limit rapid scaling. Healthcare credential convergence offers the most penetrable vertical, with NFC-enabled staff badges integrating patient record authentication. A direct OEM relationship strategy with mid-size retail chains in Brazil bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Diversified security conglomerates with aerospace and defense heritage are the most active acquirers in this space, seeking payment terminal engineering capabilities to complement existing credentialing portfolios. Long-term viability hinges on quantum-resistant secure element architecture leadership. Acquisition targets should display embedded module ecosystem integration and direct certification capabilities. Monitor NIST post-quantum cryptographic standard finalization as the inflection signal for upgrade cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | India's PLI scheme attracts component localization investments for reader assembly under RBI tokenization guidelines. |
| Dual Certification Capability Expansion | Parallel FCC and CE testing tracks compress product launch windows for North American and European payment networks. |
| Healthcare Credential Convergence | Hospital network access management systems integrate NFC-enabled staff badges with patient record authentication platforms. |
| Quantum-Resistant Architecture Redesign | NIST post-quantum cryptographic guidelines mandate secure element upgrades across installed terminal estates. |
| Direct OEM Relationship Development | Large retail chains in India and Brazil negotiate reader purchases separate from merchant service agreements. |
Study Parameters
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Merchant acquirer procurement directors, terminal OEM engineering leads, secure element chip designers, PCI DSS certification auditors, and healthcare IT security officers provided qualitative intelligence. Secondary sources include FCC equipment authorization databases, ETSI harmonized standards filings, RBI circulars on tokenization, SEC 10-K disclosures from listed terminal manufacturers, and customs trade data for reader component flows. Bottom-up unit shipment estimates triangulate against top-down payment network terminal deployment disclosures.
Rate-of-change decomposition separates volume growth from average selling price evolution across the projection horizon. Segmentation dimensions modeled include product type, interface technology, application use case, and end-user vertical, with additional granularity on certification tier and geographic regulatory cluster. CAGRs derive from regression analysis of historical terminal replacement cycles, overlaying regulatory deadline impacts and technology migration curves. Forecast inputs incorporate EMV compliance timeline assumptions, NFC penetration rates in retail checkout environments, and biometric module cost reduction trajectories.
Several conditions sit outside the modeled scope, including sovereign tariff regime changes, semiconductor fabrication capacity disruptions from geopolitical events, and abrupt shifts in mobile wallet adoption displacing physical terminal demand. Forecasts reflect documented assumptions about regulatory deadline adherence and technology migration pacing. Practitioners should monitor NIST post-quantum cryptography standard publication, RBI tokenization guideline enforcement intensity, and merchant acquirer unbundling trends for early signals of forecast revision needs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Big Data Technology Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
Global E-Filing Platforms Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Infrastructure As Code (Iac) Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Latin America IT Market
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Returnless Refund Fraud Detection Market