

Anticipatory Commerce Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Anticipatory Commerce Infrastructure Market Insights
The capital-intensity divergence between robotic fulfillment specialists and software-only vendors is redrawing competitive boundaries in anticipatory commerce. Ocado Group sustains heavy capex in proprietary grid robotics for automated grocery picking. Symbotic specializes in AI-driven warehouse orchestration for big-box retail clients. Manhattan Associates leverages cloud-native order management to compete without owning physical automation assets.
Anticipatory commerce infrastructure comprises the integrated hardware, software, and data systems that enable supply chains to predict consumer demand before explicit orders are placed, typically processing terabyte-scale transaction streams through sub-100-millisecond latency pipelines to trigger preemptive inventory positioning. Predictive analytics and real-time data processing together form the highest-margin solution layer, while machine learning models are gaining share as retailers demand self-improving forecast engines. Cloud-based deployment dominates new implementations, though edge computing is accelerating in grocery micro-fulfillment centers where latency constraints override pure cloud economics.
The EU AI Act and GDPR jointly constrain how customer behavior tracking systems ingest and process personal data for demand prediction, forcing vendors to engineer privacy-preserving federated learning architectures. The US FDA and FTC are scrutinizing health-adjacent anticipatory commerce applications, particularly for predictive replenishment of pharmaceuticals and wellness products. Stakeholders must decide whether to build compliant-by-design data pipelines or retrofit existing platforms under escalating regulatory enforcement.
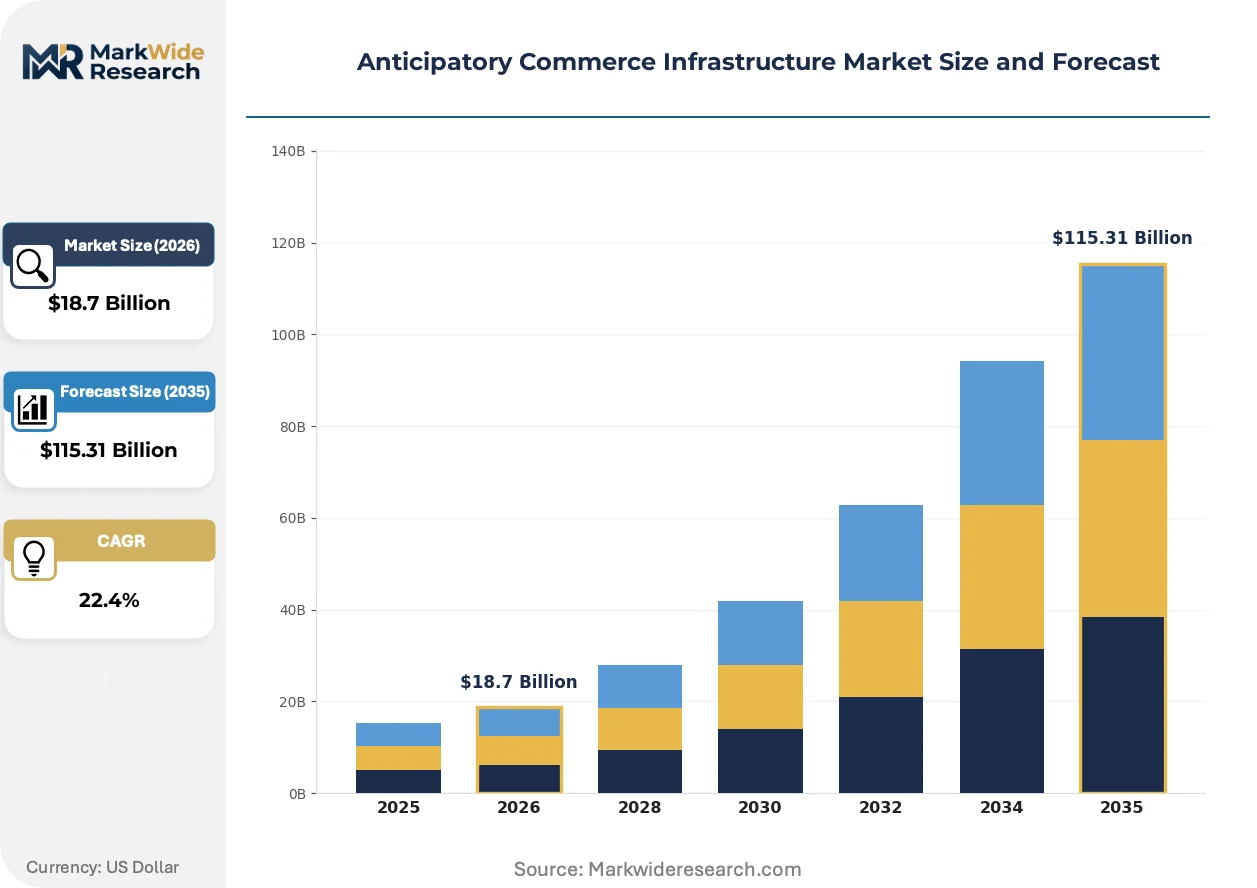
Market Dynamics
Capital-intensity divergence between robotic fulfillment specialists and cloud-native software vendors is fragmenting competitive boundaries. The EU AI Act's algorithmic transparency mandates are forcing anticipatory commerce platforms to reengineer data pipelines before enforcement deadlines.
Growth Catalysts
- EU AI Act compliance deadlines:Retailers are accelerating procurement of explainable demand-forecasting engines to meet 2025 transparency requirements for automated decision systems.
- Grocery micro-fulfillment expansion:German supermarket chains are retrofitting urban distribution centers with anticipatory robotics to compress last-mile latency below 100 milliseconds.
- Edge computing penetration:Latency-sensitive inventory positioning systems are migrating processing from cloud to local nodes in high-frequency trading zones.
Market Restraints
- Semiconductor supply concentration:Specialized AI inference chips for warehouse robotics face single-source dependency on Taiwan-based foundry capacity.
- GDPR data friction:Cross-border customer behavior tracking for demand prediction requires federated learning architectures that degrade model accuracy.
- Capital intensity barrier:Proprietary grid robotics systems demand $50-150 million per fulfillment center deployment, excluding mid-market retailers.
Strategic Opportunities
- India's PLI scheme for warehousing automation:Domestic manufacturers can capture 15-20% cost advantages through localized robotic component production.
- Pharmaceutical predictive replenishment:FDA scrutiny of health-adjacent anticipatory commerce is creating compliant-first vendor selection criteria.
- Digital twin convergence:Integration of physics-based simulation with real-time demand signals enables virtual commissioning of fulfillment networks.
Industry Challenges
- Legacy WMS integration complexity:Anticipatory engines must interface with 1990s-era warehouse management systems through brittle API layers.
- Millisecond-latency engineering talent scarcity:Pipeline optimization specialists with sub-100-millisecond system design experience command 40% compensation premiums.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anticipatory Commerce Infrastructure Market Trends and Innovations
Anticipatory commerce infrastructure is pivoting from batch-processed forecasts toward continuous streaming architectures. Three interconnected developments are compressing decision latency and expanding addressable use cases.
Digital twin technology is decomposing traditional warehouse design cycles. Retailers are deploying physics-accurate simulations of robotic fulfillment grids before physical construction. German grocery operators now commission entire micro-fulfillment centers virtually, reducing deployment risk and enabling scenario testing for peak-load conditions.
The EU AI Act's algorithmic transparency requirements are mandating interpretable machine learning for demand prediction. Automated inventory systems must now expose decision logic to regulators and consumers. Vendors are responding with attention-mechanism architectures that highlight which data signals triggered specific replenishment orders.
Subscription-based replenishment models are displacing reactive purchasing in household consumables. Direct-to-consumer brands are capturing anticipatory demand through consumption-pattern monitoring. This shift is most visible in North American metropolitan markets where smart-home device penetration enables automated reordering triggers.
Anticipatory Commerce Infrastructure Market Segmentation
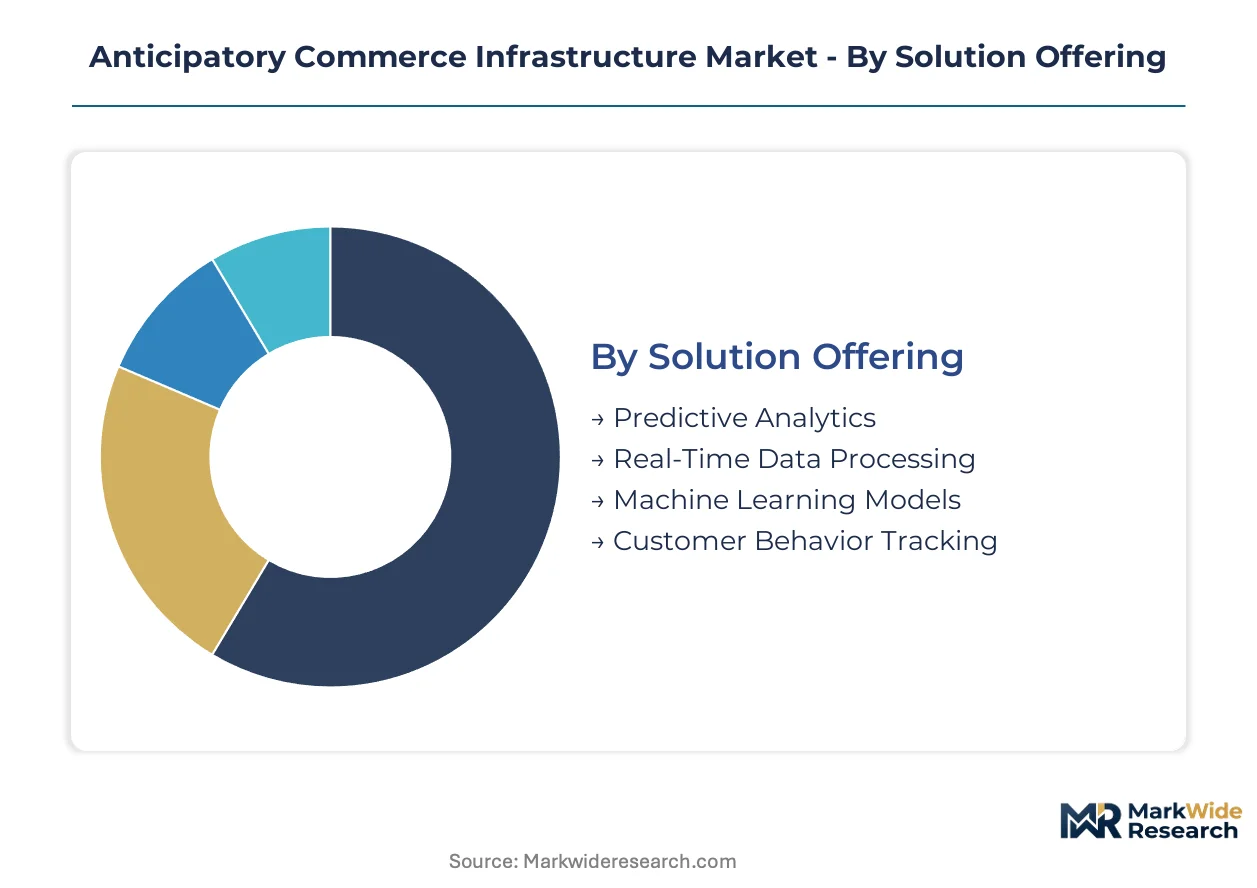
Anticipatory commerce infrastructure vendors must align solution architectures with divergent latency tolerances, data sovereignty constraints, and capital deployment capacities across buyer segments. Segmentation reveals where robotic fulfillment specialists command premium pricing against cloud-native software alternatives.
Solution Offering:
Predictive analytics platforms face intensifying substitution pressure from vertically integrated warehouse robotics vendors that bundle forecasting with physical automation.
- Predictive Analytics:Statistical engines processing terabyte-scale transaction histories to generate demand probability distributions. German grocery chains deploy these systems to preempt stockouts before peak shopping cycles, though accuracy degrades when GDPR constraints limit cross-border data pooling.
- Real-Time Data Processing:Sub-100-millisecond latency pipelines ingesting point-of-sale streams, weather feeds, and social sentiment signals. Edge computing migration is compressing decision loops in urban micro-fulfillment centers where cloud round-trips prove prohibitive.
- Machine Learning Models:Self-improving forecast engines with attention mechanisms for regulatory explainability. The EU AI Act mandates interpretable architectures that expose which data signals triggered specific replenishment orders.
- Customer Behavior Tracking:Federated learning systems predicting individual purchase propensity without centralizing personal data. Privacy-preserving designs sacrifice model precision for GDPR compliance.
Predictive analytics retains volume leadership; real-time data processing holds the steepest expansion curve.
Deployment:
Cost tier stratification separates hyperscale cloud commitments from capital-light edge configurations favored by mid-market retailers.
- Cloud-Based:Centralized compute resources with elastic scaling for seasonal demand spikes. New implementations default here due to minimal upfront infrastructure investment and rapid deployment timelines.
- On-Premise:Dedicated hardware installations in enterprise data centers. Legacy retailers with existing server farms favor this model for data residency control, particularly under national banking regulations when payment data intersects with purchase predictions.
- Hybrid:Split architectures routing sensitive processing locally while bursting non-critical workloads to cloud. This configuration dominates pharmaceutical anticipatory commerce where FDA audit trails require on-premise transaction logging.
- Edge Computing:Localized inference nodes within fulfillment centers eliminating network latency. German supermarket operators retrofitting urban distribution centers specify edge deployments to hit sub-100-millisecond inventory positioning targets.
Cloud-based deployment captures the largest installed base; edge computing is expanding most quickly among grocery micro-fulfillment specialists.
Use Case:
Application maturity varies sharply, with inventory management approaching commoditization while dynamic pricing retains differentiation leverage.
- Inventory Management:Automated replenishment triggering purchase orders before stock depletion. Ocado Group and Symbotic compete here through proprietary grid robotics integration.
- Personalized Marketing:Individual-level promotion timing based on predicted purchase windows. Subscription-based replenishment models in North American metropolitan markets displace reactive purchasing through consumption-pattern monitoring.
- Demand Forecasting:Aggregate volume prediction for procurement and capacity planning. EU AI Act transparency mandates are forcing reengineering of black-box forecast engines.
- Dynamic Pricing:Real-time price elasticity optimization responding to competitive signals and inventory positions. This use case demands the lowest latency infrastructure and commands premium solution pricing.
Inventory management sustains the broadest adoption footprint; dynamic pricing delivers the highest margin expansion potential.
End User:
Customer type determines procurement authority, with retailers controlling capital budgets and logistics providers influencing technical specifications.
- Retailers:Supermarket chains and big-box operators deploying end-to-end anticipatory systems. German grocery chains currently drive the steepest retrofit investment curves.
- E-commerce Platforms:Pure-play digital marketplaces with native data advantages in consumer behavior tracking. These buyers prioritize real-time personalization over physical automation.
- Consumer Goods Brands:Manufacturers seeking direct demand signals to optimize production scheduling. Direct-to-consumer brands leverage smart-home device penetration for automated reordering triggers.
- Logistics Providers:Third-party fulfillment operators offering anticipatory capabilities as a service. These intermediaries aggregate demand across multiple brand clients, creating data pooling advantages.
Retailers dominate current procurement volumes; logistics providers are gaining share fastest as outsourced fulfillment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity for anticipatory robotics, while mid-market retailers in India and Southeast Asia face acute capital constraints that compress procurement budgets by 40-60%.
Germany
Grocery chains Edeka and REWE are retrofitting urban fulfillment centers with sub-100-millisecond edge computing nodes. The EU AI Act mandates algorithmic transparency for automated demand-forecasting systems deployed by 2025. Berlin-Brandenburg hosts the densest concentration of anticipatory robotics pilots, with three major supermarket operators commissioning virtual commissioning through digital twin platforms.
United States
Big-box retailers and direct-to-consumer brands drive demand for cloud-native order management systems. FDA and FTC scrutiny of predictive pharmaceutical replenishment is forcing compliant-first vendor selection criteria. The Seattle metropolitan cluster anchors development of subscription-based replenishment models leveraging smart-home device penetration.
India
Domestic manufacturers exploit 15-20% cost advantages through localized robotic component production under the PLI scheme for warehousing automation. BIS certification requirements for industrial automation equipment are tightening import substitution timelines. Maharashtra and Karnataka host emerging fulfillment automation corridors where third-party logistics providers aggregate demand across multiple e-commerce clients.
China
Dual carbon goals and MIIT smart logistics directives are accelerating electrification of warehouse robotics fleets. GB standards for automated guided vehicles are harmonizing with international safety protocols. The Yangtze River Delta concentration of e-commerce platforms is driving native data advantages in consumer behavior tracking for anticipatory inventory positioning.
United Kingdom
Ocado Group's proprietary grid robotics technology is scaling through licensing partnerships with international supermarket operators. Post-Brexit data residency requirements are fragmenting cross-border customer behavior pooling for demand prediction. The London-Southeast corridor concentrates venture funding for edge computing startups serving grocery micro-fulfillment applications.
Anticipatory Commerce Infrastructure Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence fragmenting competitive boundaries between robotic fulfillment owners and software-only vendors. Three archetypes dominate: vertically integrated grid robotics specialists, AI-driven warehouse orchestration platforms, and cloud-native order management providers. M&A activity concentrates on acquiring millisecond-latency engineering talent, while strategic partnerships proliferate between automation hardware vendors and federated learning software houses.
Within the integrated robotics tier, Ocado Group and AutoStore exemplify capital-heavy proprietary fulfillment grid strategies, while Symbotic occupies a position between physical automation and AI orchestration. Manhattan Associates anchors the asset-light software vector, competing through cloud-native deployment without captive robotics manufacturing. These three representations illustrate the fundamental strategic choice confronting procurement executives: absorb $50-150 million per fulfillment center capital requirements, or outsource physical automation to specialized infrastructure operators.
| Leading Market Players |
|---|
| Ocado Group |
| Symbotic |
| Manhattan Associates |
| Blue Yonder |
| Instacart |
| AutoStore |
| Fluent Commerce |
| Shopify |
| Amazon |
| Others |
Pricing and Supply Chain Analysis
EU AI Act compliance deadlines gate both vendor qualification and price differentiation simultaneously, as retailers demand explainable forecasting engines that command premium positioning against black-box alternatives while disqualifying non-compliant suppliers from procurement shortlists.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions drive lifetime value capture across deployment tiers. Pricing stratifies across premium robotics-integrated bundles, standard cloud-native software tiers, and economy edge-computing configurations. Price differentiation rests on latency performance guarantees and GDPR-compliant architecture certification. Cost compression in the standard tier intensifies as cloud-native vendors compete without physical automation overhead. Mid-market retailers in India and Southeast Asia exhibit the highest price sensitivity, while German grocery chains demonstrate the lowest.
Supply Chain Analysis
Taiwan-based foundry capacity for specialized AI inference chips constitutes a critical chokepoint for warehouse robotics deployment timelines. Hardware assembly concentrates in China, Germany, and the United States. Component sourcing draws from South Korean memory suppliers, Japanese precision motor manufacturers, and domestic sensor producers. Single-source vulnerability in semiconductor fabrication creates procurement risk for latency-sensitive edge computing nodes. Distribution runs through direct OEM relationships for large fulfillment center deployments and systems integrators for mid-market retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a capital expenditure cyclical trough, with retailer technology refresh budgets expanding ahead of peak shopping cycles and regulatory enforcement deadlines.
For Market Incumbents: Secure explainable AI certification ahead of EU AI Act enforcement to defend against cloud-native software vendors encroaching from below. Deepen backward integration into edge computing hardware to capture margin pools currently flowing to semiconductor suppliers. Capacity addition in India under the PLI scheme offsets cost pressure from Taiwan chip dependency. For New Entrants and Emerging Players: Anchor in pharmaceutical predictive replenishment as FDA scrutiny creates compliant-first vendor selection criteria that favor new entrants with purpose-built audit trails. White-space exists in federated learning software for GDPR-constrained European retailers. Go-to-market through systems integrators serving mid-market grocers avoids direct competition with Ocado and Symbotic. For Investors and Strategic Acquirers: EU AI Act transparency mandates reshape the acquisition landscape toward interpretable machine learning assets over black-box forecasting engines. Long-term viability favors vendors with hybrid deployment architectures spanning cloud and edge. Target acquisition archetype: millisecond-latency engineering teams with sub-100-millisecond system design experience. The signal to watch is German supermarket chain procurement decisions as they commission virtual fulfillment centers through digital twin platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Certification Investment | EU AI Act compliance unlocks procurement eligibility with German grocery chains and REWE. |
| Edge Computing Hardware Integration | Sub-100-millisecond latency nodes meet Edeka's urban micro-fulfillment retrofit specifications. |
| Federated Learning Architecture Development | GDPR-compliant demand prediction enables cross-border data pooling without centralization risk. |
| Digital Twin Platform Partnership | Virtual commissioning reduces deployment risk for Berlin-Brandenburg robotics pilots. |
| India PLI Scheme Manufacturing Localization | Domestic robotic component production captures cost advantages in Maharashtra automation corridors. |
Research Methodology
Cross-validation between primary interviews with supply chain directors and secondary validation through customs automation equipment import records anchors the qualitative findings. Primary fieldwork engaged warehouse operations executives, robotics procurement managers, cloud platform engineers, and systems integration specialists across Germany, the United States, India, and China. Secondary sources included SEC filings from publicly traded automation vendors, EU AI Act implementation guidance documents, and BIS certification databases for industrial automation equipment. Bottom-up installation tracking and top-down capex flow analysis triangulate market sizing.
Sensitivity analysis around semiconductor supply disruption scenarios and regulatory enforcement timing variations stress-tests projection stability. The analytical framework models deployment mode, solution layer, end-user category, and latency tolerance tier across the analysis window. CAGRs derive from fitted growth curves against historical automation adoption cycles. Industry-specific inputs include grocery micro-fulfillment center commissioning timelines and pharmaceutical FDA audit trail requirements.
Decision-makers should treat outputs as directional under sustained retailer technology refresh spending and stable Taiwan foundry capacity assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act enforcement interpretation and edge computing hardware availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.