
 Ground Coffee Market | 2026-2036
Ground Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Coffee Market Analysis
Retail bagged coffee revenue is fragmenting across direct-to-consumer subscriptions, café wholesale, and private-label grocery contracts. Nestlé S.A. leverages its Nespresso-compatible ground formats to sustain premium pricing in European households. Starbucks Corporation anchors its North American presence through licensed café channels and grocery store placement. JDE Peet's Coffee competes across mid-market supermarket tiers with multi-brand portfolio breadth.
Ground coffee consists of roasted coffee beans milled to particle sizes between 0.5 and 1.0 millimeters for extraction via drip, pour-over, or espresso brewing methods. The grinding process exposes volatile aromatic oils that degrade within minutes of contact with oxygen, necessitating nitrogen-flushed packaging or immediate consumption. Arabica and Robusta sourcing splits reveal margin concentration at the blend level, where roasters optimize cost-aroma tradeoffs. Specialty stores and online retail represent the fastest-expanding distribution channels as consumers bypass supermarkets for traceable single-origin offerings.
The U.S. FDA oversees labeling standards for coffee products, including caffeine content disclosures and organic certification compliance, while the EU Green Deal and EUDR impose due diligence on deforestation-linked supply chains. Brazil's MAPA and INCRA regulate agricultural land use and exporter registration, shaping how international buyers source from Minas Gerais and São Paulo growing regions. Stakeholders must monitor how evolving carbon border adjustments and regenerative agriculture mandates reshape procurement priorities across origin markets.
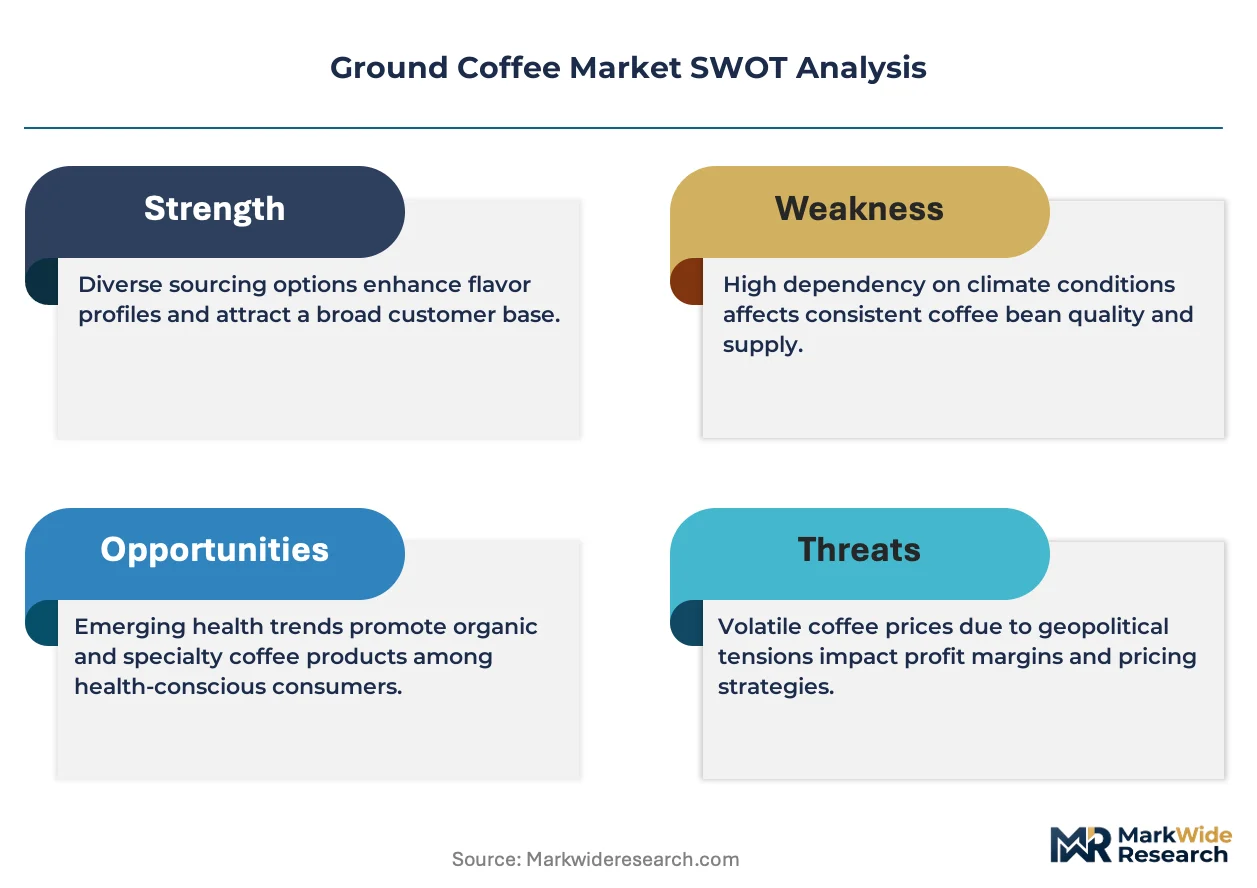
Market Dynamics
The EU Deforestation Regulation is forcing roasters to rebuild traceability systems from farm to port, compressing margins for mid-tier blenders while advantaging vertically integrated suppliers with direct origin relationships.
Growth Catalysts
- Specialty café expansion:Independent coffee shops in Brazil and Vietnam are capturing prepared beverage spending from fast-food chains, driving demand for single-origin Arabica at premium particle specifications.
- EUDR compliance infrastructure:The EU Green Deal's due diligence mandates are creating competitive moats for roasters with certified supply chains, accelerating consolidation among compliant mid-market players.
- Home brewing equipment proliferation:Precision grinders and automated pour-over systems in Japanese and South Korean households are elevating consumer sensitivity to grind consistency and freshness dating.
Market Restraints
- Arabica price volatility:Frost damage in Brazilian highlands and drought cycles in Colombian Andes expose blenders to margin compression when hedging instruments prove inadequate.
- Robusta supply concentration:Vietnamese and Indonesian robusta dominates espresso blend formulations, creating sourcing vulnerability when weather or logistics disrupt Mekong Delta exports.
- Oxidation chemistry limits:Volatile aromatic compound degradation within minutes of grinding constrains pre-ground product shelf life, favoring whole-bean formats in quality-sensitive channels.
Strategic Opportunities
- Regenerative agriculture incentives:Brazil's MAPA credit lines for shade-grown cultivation and carbon sequestration certification open premium positioning for origin-verified micro-lots.
- Direct-to-subscription channels:Roasters bypassing supermarket slotting fees through nitrogen-flushed mail-order formats capture lifetime value from enthusiast segments in Germany and Netherlands.
- Cold brew concentrate applications:Foodservice operators and ready-to-drink manufacturers are sourcing coarse-ground specialty lots for extended extraction processes, creating new volume outlets for lower-density origins.
Industry Challenges
- Q-grader talent scarcity:Certified cupping professionals capable of evaluating green coffee quality at origin remain concentrated in traditional trading houses, constraining roaster direct-sourcing ambitions.
- Multi-jurisdiction compliance layering:Simultaneous adherence to FDA organic labeling, EUDR geolocation requirements, and Brazil's INCRA land registry demands specialized legal and systems investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Coffee Market |
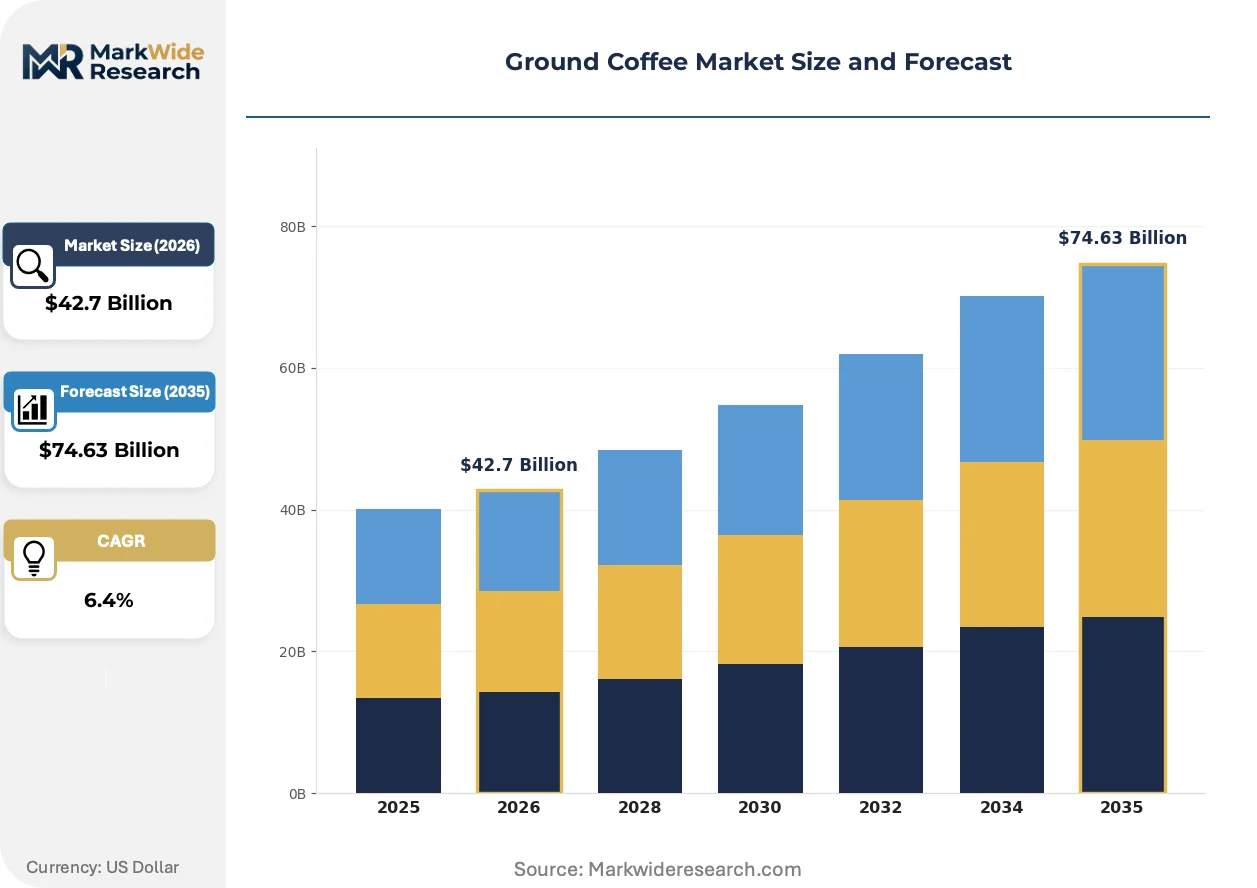
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $74.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Blend, Decaf Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Coffee Shops Packaging Type: Bags, Pods, Canisters, Tins Customer Type: Households, Businesses, Hotels, Restaurants |
| Companies Covered | Nestlé S.A., Starbucks Corporation, The J.M. Smucker Company, JDE Peet's Coffee, Kraft Heinz Company, Lavazza Group, Keurig Dr Pepper, Luigi Lavazza S.p.A., illycaffè S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Coffee Market Emerging Trajectories
Grinding technology and packaging science are converging to extend freshness windows, while regulatory traceability mandates and shifting procurement behaviors are rewiring competitive advantage from scale to transparency.
Precision roller mill systems with particle-size distribution control are replacing industrial blade grinders in medium-capacity roasting facilities. Specialty roasters in Melbourne and Portland are adopting these systems to achieve extraction consistency across batch sizes. The technology is rendering obsolete the tolerance for fines-and-boulders inconsistency that previously characterized commodity ground coffee production.
The EU Deforestation Regulation's geolocation and due diligence requirements took effect for large operators in late 2024, with full phase-in continuing through 2025. Roasters must now document polygon coordinates for all sourcing plots and maintain chain-of-custody records through processing and export. European supermarket private-label programs are most affected, with buyers shifting contract terms toward pre-certified origins from Minas Gerais and Huehuetenango to reduce compliance risk.
Enthusiast consumers are abandoning supermarket center aisles for subscription services and café-direct retail, compressing the traditional wholesale-grocery channel. This channel rotation is most visible in Nordic markets and Pacific Northwest urban centers, where traceability storytelling and roast-date transparency outweigh price positioning in purchase decisions. Roasters responding with micro-lot transparency pages and harvest-specific lot codes are capturing disproportionate loyalty from this migrating demand.
Ground Coffee Market Segmentation
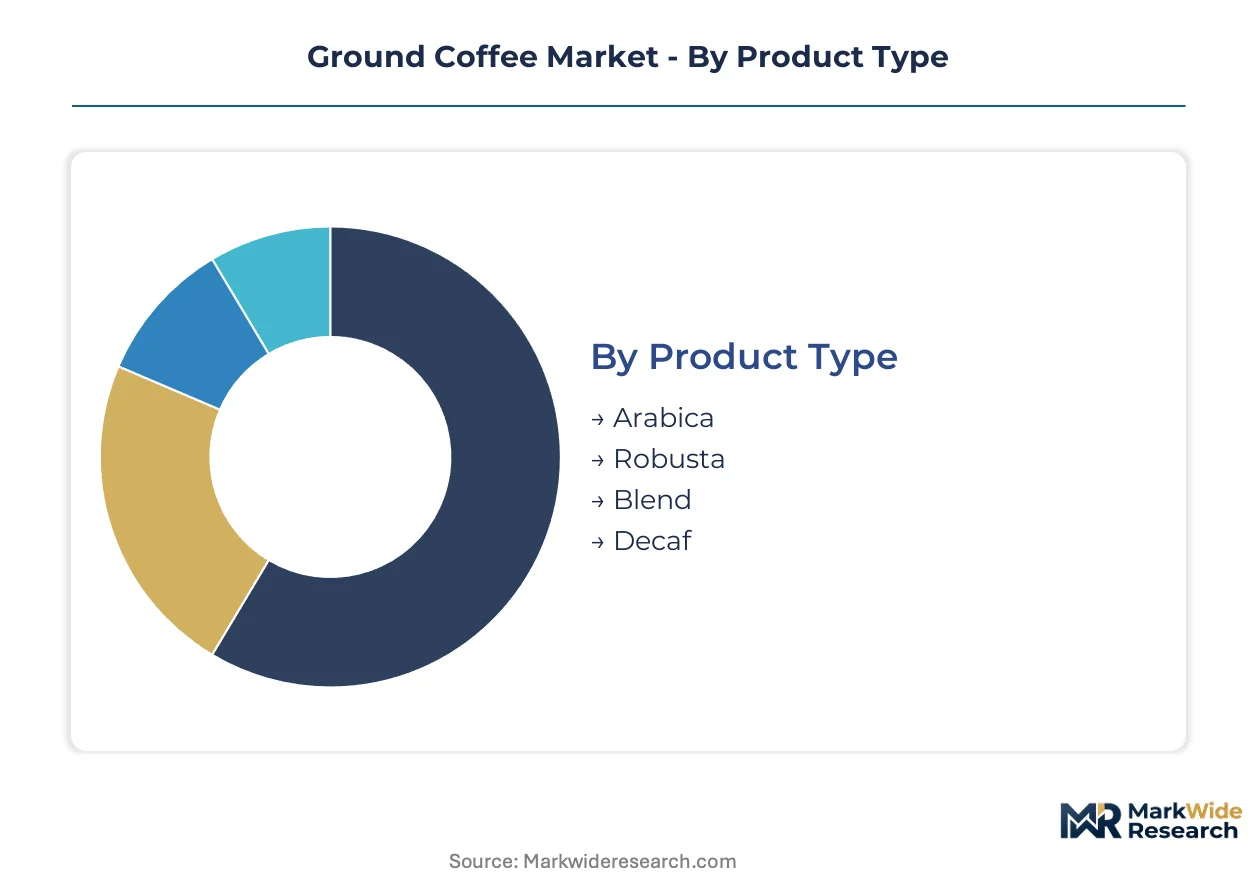
Ground coffee segmentation reveals how sourcing decisions, brewing rituals, and purchasing contexts fragment demand into distinct value pools. Roasters configure grind specifications, packaging formats, and channel strategies around these divides to capture margin.
Product Type:
Mature Arabica and Robusta sourcing patterns now coexist with emerging specialty-grade and decaffeinated segments that command premium positioning.
- Arabica:Higher-altitude cultivation in Ethiopian highlands and Colombian Andes yields lower-caffeine beans with complex acidity profiles. Specialty cafés in Melbourne and Portland favor single-origin Arabica for pour-over service, though frost damage in Brazilian highlands periodically constrains supply.
- Robusta:Dense, higher-caffeine beans from Vietnamese Central Highlands and Indonesian Sumatra dominate espresso blend formulations for crema stability. Italian roasting houses anchor procurement contracts here, though Mekong Delta logistics disruptions create periodic sourcing vulnerability.
- Blend:Cost-aroma optimization at the roaster level combines origins for consistent cup profiles across harvest cycles.
- Decaf:Swiss Water and CO2-processed lots serve caffeine-sensitive households and evening consumption occasions in German and Dutch markets.
Blends handle the majority of throughput; decaf is gaining share fastest among health-conscious urban consumers.
Distribution Channel:
Channel strategy rotates around freshness sensitivity and traceability demands, with cost tier determining supermarket placement versus direct engagement.
- Supermarkets:Center-aisle placement of nitrogen-flushed bags and private-label tins serves price-sensitive household replenishment in US and European mass retail. Slotting fees compress margins for mid-tier roasters competing against captive store brands.
- Specialty Stores:Curated single-origin selections with harvest-specific lot codes attract enthusiast consumers in Nordic urban centers and Pacific Northwest cities. Staff cupping knowledge and roast-date transparency justify 40-60% price premiums over grocery equivalents.
- Online Retail:Subscription services with grind-to-order fulfillment bypass retail markup, capturing lifetime value from German and Netherlands enthusiast segments.
- Coffee Shops:Licensed and independent cafés anchor prepared beverage demand, with Brazilian and Vietnamese independents displacing fast-food chain volume.
Supermarkets move the largest absolute volume; specialty stores are expanding most quickly on margin contribution.
Packaging Type:
Packaging selection trades oxidation protection against convenience and sustainability positioning across customer types.
- Bags:Multi-layer laminate with one-way degassing valves dominates retail ground coffee, balancing cost against 3-6 month shelf stability.
- Pods:Nespresso-compatible aluminum and compostable formats sustain premium pricing in European households, though Nestlé S.A. patent expirations have opened private-label competition.
- Canisters:Reusable steel containers with replaceable inner bags serve hospitality bulk purchasing in hotel and restaurant channels.
- Tins:Heritage metal packaging persists in Italian and Portuguese gift markets, with limited functional advantage over modern laminates.
Bags carry the majority of unit volume; pods are climbing the fastest on revenue per kilogram.
Customer Type:
End-use concentration determines grind specification, with commercial operators demanding consistency at scale and households prioritizing convenience.
- Households:Home brewing equipment proliferation in Japanese and South Korean markets elevates sensitivity to particle-size consistency and freshness dating.
- Businesses:Office coffee services source coarse-ground lots for batch brewers, with cost-per-cup driving blend selection over origin traceability.
- Hotels:In-room pod systems and lobby espresso bars require dual sourcing strategies across convenience and experience tiers.
- Restaurants:Foodservice operators source coarse-ground specialty lots for cold brew concentrate applications, creating new volume outlets for lower-density origins.
Households represent the largest addressable base; restaurants are expanding most quickly on cold brew adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across consuming regions. Brazilian households absorb premium single-origin markups with minimal volume contraction, while German supermarket shoppers trade down aggressively when Arabica futures spike. Japanese consumers occupy the middle ground, responding to freshness cues more than absolute price.
Brazil
Domestic consumption now rivals export volume as specialty cafés proliferate in São Paulo and Belo Horizonte. MAPA credit lines for shade-grown cultivation incentivize regenerative transitions in Minas Gerais. The Cerrado and Mogiana regions concentrate both production and emerging roasting clusters serving the internal market.
Germany
Discounter-driven price sensitivity dominates mass-market ground coffee, yet subscription services in Berlin and Hamburg capture enthusiast segments willing to pay 50% premiums for traceability. The EU Deforestation Regulation forces supermarket private-label buyers to requalify Brazilian and Vietnamese suppliers. The Hamburg port complex remains Europe's largest green coffee entry point.
United States
Licensed café channels and grocery placement sustain volume for major roasters, while direct-to-consumer subscriptions erode supermarket share in Pacific Northwest and Northeast urban centers. FDA labeling requirements for caffeine content and organic certification compliance shape product development cycles. Seattle and Portland roasting clusters anchor specialty-grade innovation.
Japan
Precision home brewing equipment proliferation elevates grind consistency sensitivity beyond price considerations in Tokyo and Osaka households. METI energy efficiency standards affect roasting facility investments. The Kanto region concentrates both consumption demand and import logistics infrastructure.
Vietnam
Domestic café culture expansion in Ho Chi Minh City and Hanoi drives Robusta quality upgrades for local espresso consumption. Central Highlands growing regions face EUDR geolocation documentation requirements that favor larger estate operations over smallholder aggregators. The Mekong Delta logistics corridor remains vulnerable to seasonal flooding disruptions.
Ground Coffee Market Vendor Landscape
Vertically integrated multinationals and specialty-focused independents split the market along freshness-versus-scale lines. The structure concentrates margin capture among three archetypes: origin-integrated roasters with direct farm relationships, equipment-tied pod system operators, and subscription-native micro-roasters. Consolidation pressures mount as EUDR compliance costs favor scaled traceability investment, while cold brew concentrate applications open co-manufacturing partnerships between specialty roasters and ready-to-drink brands.
Within the multinational tier, Nestlé S.A. and Starbucks Corporation exemplify divergent strategic anchors—one leveraging patent-expired pod compatibility for European household penetration, the other binding grocery placement to licensed café network effects. JDE Peet's Coffee occupies the portfolio-breadth position across mid-market supermarket tiers. These three structures illustrate how scale, format control, and channel integration define competitive position without requiring identical resource deployment.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Starbucks Corporation |
| The J.M. Smucker Company |
| JDE Peet's Coffee |
| Kraft Heinz Company |
| Lavazza Group |
| Keurig Dr Pepper |
| Luigi Lavazza S.p.A. |
| illycaffè S.p.A. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Vietnamese Central Highlands wet-milling infrastructure drives both Robusta price premiums and supplier consolidation toward estate-scale operators with captive processing capacity, compressing margins for mid-tier blenders dependent on spot-market sourcing.
Pricing Analysis
Subscription renewal revenue from nitrogen-flushed mail-order formats drives lifetime value capture more than initial bag sales. Three-tier pricing structure across specialty single-origin, certified blend, and private-label economy levels segments buyers by traceability tolerance. Cost compression in supermarket tiers is intensifying because EUDR compliance costs concentrate among private-label buyers. Discounter-driven households in Germany exhibit highest price sensitivity, while Japanese enthusiast segments prioritize freshness dating over absolute cost.
Supply Chain Analysis
EU Deforestation Regulation geolocation documentation acts as export-control-style restrictions limiting flows from uncertified smallholder aggregators in Vietnam and Indonesia. Supply concentrates in Brazil, Vietnam, and Colombia for green coffee procurement, with Italian and German roasting clusters anchoring downstream processing. Input dependencies rest on fertilizer availability, shipping container capacity, and energy costs for roasting operations. Single-source vulnerability around Mekong Delta logistics disruptions creates structural risk. Distribution runs through Hamburg and Santos port complexes toward European and North American consuming markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pod-system interoperability expiration and Nespresso-compatible format proliferation signal platform-economics inflection, with patent cliff effects opening private-label competition across European household channels.
For Market Incumbents: Pre-empt subscription-native micro-roasters by acquiring direct-to-consumer fulfillment capabilities in Germany and Netherlands, while locking EUDR-pre-certified origin contracts in Minas Gerais to defend against compliance-cost-driven margin erosion from emerging vertically integrated competitors. For New Entrants and Emerging Players: Establish a beachhead in cold brew concentrate co-manufacturing partnerships with ready-to-drink brands, targeting restaurant foodservice channels in Pacific Northwest urban centers where traceability storytelling outweighs incumbent brand equity. For Investors and Strategic Acquirers: Capital is best deployed toward origin-integrated roasters with direct farm relationships and certified supply chain infrastructure, as EUDR compliance moats widen competitive advantage over the coming decade; watch for Q-grader talent scarcity constraining direct-sourcing ambitions as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Compliance Infrastructure Investment | Polygon geolocation systems and chain-of-custody documentation satisfy EU Green Deal mandates for supermarket private-label buyers. |
| Direct-to-Subscription Channel Launch | Nitrogen-flushed mail-order formats bypass retail slotting fees and capture lifetime value from German enthusiast segments. |
| Regenerative Agriculture Certification | MAPA credit lines for shade-grown cultivation open premium positioning for carbon-sequestering micro-lots from Minas Gerais. |
| Cold Brew Concentrate Partnership | Co-manufacturing agreements with ready-to-drink brands create volume outlets for lower-density specialty origins. |
| Precision Grinding Technology Adoption | Roller mill systems with particle-size distribution control replace blade grinders in Melbourne and Portland roasting facilities. |
Methodological Framework
Desk research of customs records, trade association filings, and agricultural ministry statistics preceded structured interviews with green coffee traders, roasting facility managers, supermarket category buyers, and café procurement directors. Primary fieldwork with stakeholders across Brazilian, Vietnamese, and German supply chain nodes combined with secondary validation from FDA labeling guidance and EU Deforestation Regulation implementation documents. Bottom-up volume modeling across grind specifications and packaging formats triangulated against top-down trade flow analysis.
Baseline conditions held EUDR phase-in timelines and Arabica futures volatility bands fixed while varying home brewing equipment penetration rates and subscription service adoption curves across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, packaging format, and customer type alongside origin-specific certification tiers. CAGRs were derived from trend extrapolation moderated by regulatory compliance cost absorption capacity. Forecast inputs incorporated wet-milling capacity utilization in Vietnamese Central Highlands and nitrogen flushing technology diffusion rates in mail-order fulfillment.
Stress conditions across frost damage frequency in Brazilian highlands, Mekong Delta flooding severity, and EU carbon border adjustment implementation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with risk factors including Arabica price volatility spikes and Q-grader talent concentration in traditional trading houses potentially revising projections. Cross-checking against Hamburg and Santos port entry data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Australia Coffee Market
Coffee
UK Coffee Roaster Market
Coffee
Freeze Dried Coffee Market
Coffee
Robusta Coffee Beans Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Bags Market
Coffee
Mushroom Coffee Market
Coffee
High Protein Coffee Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Singapore Coffee Roaster Market
Coffee
Global Coffee Machine Market
Coffee
United States Coffee Market
Coffee
Coffee Capsules Market
Coffee
Cold Brew Coffee Market
Coffee
Global Nespresso Capsules Market
Coffee
Saudi Arabia Coffee Roaster Market