
 Stack Emissions Real-Time Speciation and Compliance Test Systems Market | 2026-2036
Stack Emissions Real-Time Speciation and Compliance Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Stack Emissions Real-Time Speciation and Compliance Test Systems Market Insights
Aftermarket service revenue is rewriting profit dynamics across the stack emissions monitoring value chain. Thermo Fisher Scientific leverages its global service infrastructure to capture recurring calibration and maintenance contracts. HORIBA anchors its position through specialized FTIR-based analyzer refurbishment programs. ENVEA competes by extending remote diagnostics capabilities that reduce plant downtime for European industrial operators.
Stack emissions real-time speciation and compliance test systems comprise integrated hardware-software platforms that employ Fourier Transform Infrared Spectroscopy, ultraviolet fluorescence, and electrochemical sensing to quantify pollutants including SOx, NOx, CO2, mercury, and particulate matter at concentrations down to parts-per-billion levels in flue gas streams. Continuous Emission Monitoring Systems dominate installed base value due to regulatory mandates requiring 24/7 operational coverage, while Data Acquisition Systems represent the fastest-expanding margin pool as utilities integrate AI-driven predictive analytics into legacy infrastructure. Gas Analyzers sustain stable replacement demand across coal-to-gas conversion projects in North American power generation.
The US EPA enforces Continuous Emission Monitoring System certification under 40 CFR Part 75, directly shaping product design requirements and testing protocols for vendors serving American utilities. China's MEE implements GB standards for stationary source emissions that force technology localization and drive domestic procurement preferences. Germany's Federal Environment Agency applies EU Industrial Emissions Directive benchmarks that compel cement and metal manufacturers to upgrade analyzer sensitivity. Stakeholders must monitor evolving PFAS stack monitoring requirements and emerging hydrogen combustion emission profiles to anticipate next-generation speciation demands.
Market Dynamics
The US EPA's Mercury and Air Toxics Standards and China's GB emission standards are compressing replacement cycles for Continuous Emission Monitoring Systems while forcing analyzer sensitivity upgrades across coal-to-gas conversion projects.
Growth Catalysts
- EU Green Deal compliance deadlines:Cement and metal manufacturers in Germany face mandated analyzer upgrades under Industrial Emissions Directive benchmarks, accelerating hardware refresh demand.
- FTIR-UV convergence:Fourier Transform Infrared Spectroscopy paired with ultraviolet fluorescence is enabling parts-per-billion mercury detection that satisfies tightening stationary source mandates.
- Power generation restructuring:Coal-to-gas conversion projects across North American utilities sustain replacement demand for electrochemical sensing arrays in modified flue gas streams.
Market Restraints
- Certified reference gas supply concentration:Specialty calibration gas production clusters in Germany and Japan create procurement bottlenecks for remote monitoring deployments.
- Technical limitation in hydrogen combustion profiles:Existing FTIR libraries lack validated spectral signatures for emerging hydrogen-blended fuel emission matrices.
- Regulatory friction from PFAS monitoring uncertainty:The US EPA has not finalized stack testing protocols for per- and polyfluoroalkyl substances, freezing capital allocation for preemptive analyzer configurations.
Strategic Opportunities
- Remote diagnostics channel expansion:European industrial operators are unbundling maintenance contracts from hardware procurement, creating recurring revenue pools for predictive service platforms.
- AI-driven Data Acquisition System integration:Utilities are retrofitting legacy Continuous Emission Monitoring infrastructure with machine learning analytics without full hardware replacement.
- China's dual carbon localization mandate:Domestic procurement preferences under MEE standards create captive demand for technology transfer partnerships with foreign analyzer vendors.
Industry Challenges
- Spectroscopy technician scarcity:FTIR analyzer calibration and fault diagnosis require specialized optical engineering skills that outpace vocational training pipeline output in industrial regions.
- 40 CFR Part 75 certification timeline compression:The US EPA's recertification windows for modified monitoring systems force simultaneous hardware validation and software requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stack Emissions Real-Time Speciation and Compliance Test Systems Market |
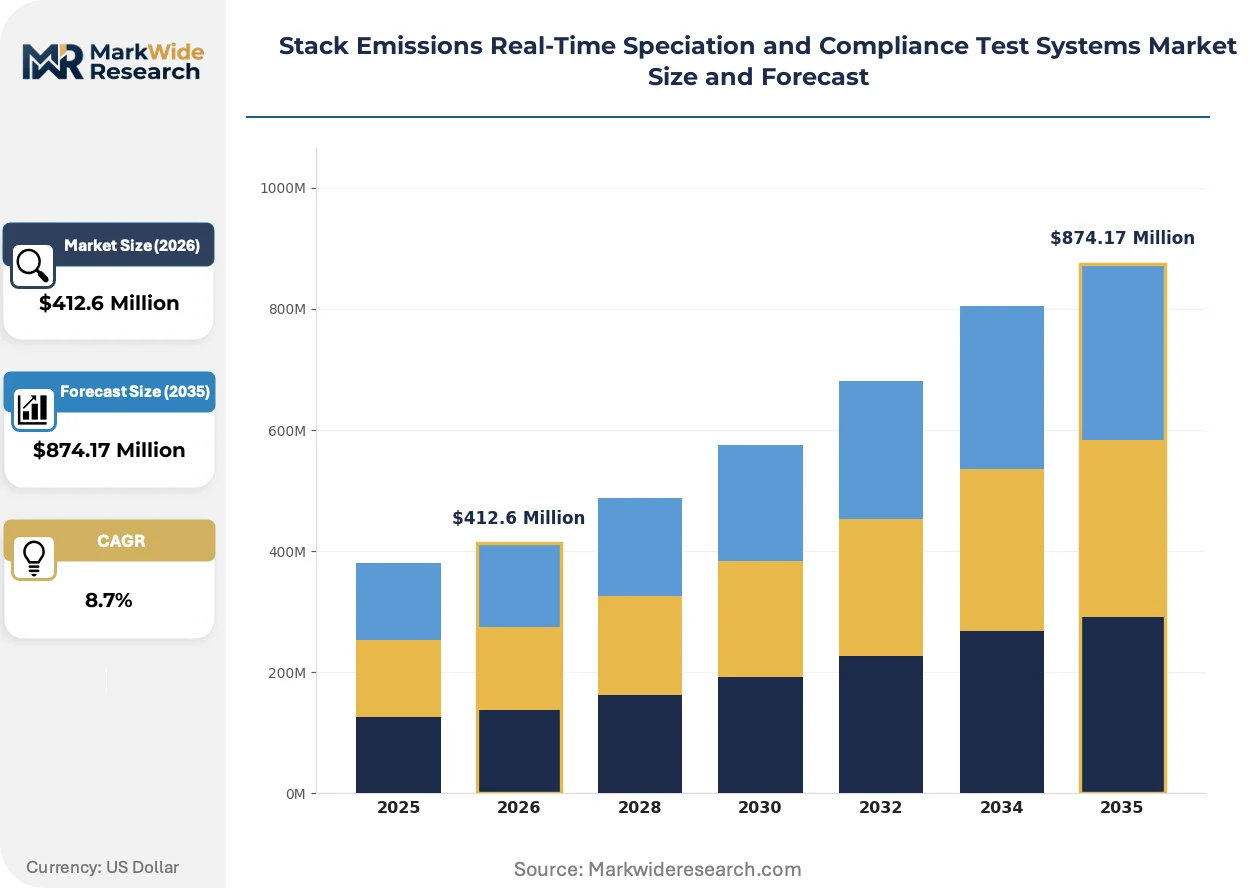
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Particulate Monitors, Continuous Emission Monitoring Systems, Sample Conditioning Units, Data Acquisition Systems Technology: Fourier Transform Infrared Spectroscopy, Non-Dispersive Infrared, Chemiluminescence, Ultraviolet Fluorescence, Electrochemical Sensors Application: Power Generation, Chemical Processing, Metal Manufacturing, Cement Production, Waste Management End User: Energy Producers, Industrial Manufacturers, Municipal Waste Facilities, Environmental Laboratories, Regulatory Agencies |
| Companies Covered | Thermo Fisher Scientific, HORIBA, ENVEA, SICK, MKS Instruments, Siemens, Fuji Electric, ABB, Emerson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stack Emissions Real-Time Speciation and Compliance Test Systems Market Trends and Innovations
Digital twin architectures are virtualizing stack emissions monitoring infrastructure, compressing physical calibration cycles while expanding predictive maintenance coverage across distributed power generation assets.
Cloud-native Data Acquisition Systems are virtualizing the traditional hardware-software boundary in Continuous Emission Monitoring platforms. Power generation utilities in Germany are deploying these architectures to centralize multi-site compliance reporting. The shift is virtualizing capital expenditure patterns from upfront analyzer purchases toward subscription-based analytics licensing.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in industrial cooling systems that support stack sampling conditioning. Analyzer manufacturers serving European cement and metal producers must redesign thermal management subsystems. The regulation is compressing product development timelines for vendors with installed bases in EU industrial clusters.
Service unbundling is fragmenting traditional bundled procurement contracts in the utility sector. Predictive maintenance subscriptions and remote calibration support are displacing comprehensive hardware-service packages. This pattern is most visible among German municipal power operators facing skilled technician shortages and compressed maintenance windows.
Stack Emissions Real-Time Speciation and Compliance Test Systems Market Segmentation
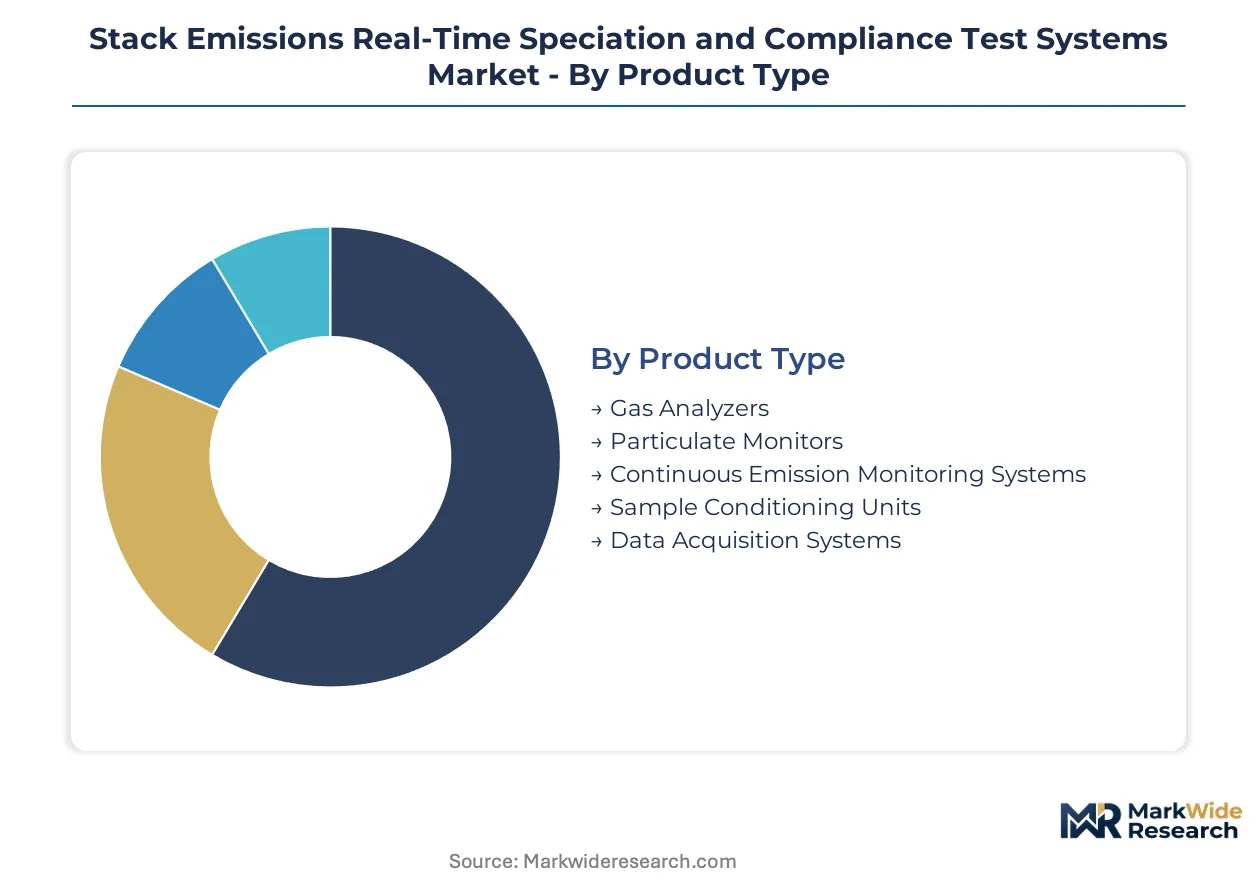
Stack emissions monitoring vendors configure product portfolios around replacement cycle velocity. Continuous emission monitoring systems operate on decade-long recertification timelines, while data acquisition software refreshes annually as utilities layer predictive analytics onto legacy hardware.
Product Type:
Replacement cycles stretch from 18 months for consumable conditioning modules to 15 years for certified monitoring platforms. Hardware with embedded regulatory approval commands extended depreciation schedules.
- Continuous Emission Monitoring Systems:Integrated hardware-software platforms certified under 40 CFR Part 75 and EU Industrial Emissions Directive. Power generation utilities in Germany anchor demand as coal-to-gas conversions force sensitivity upgrades for modified flue gas matrices.
- Data Acquisition Systems:Cloud-native compliance reporting infrastructure virtualizing multi-site data aggregation. German municipal power operators unbundle these from hardware procurement, shifting capital expenditure toward subscription licensing models.
- Gas Analyzers:Modular SOx, NOx, and CO2 detection units requiring 3-5 year replacement cycles.
- Particulate Monitors:Optical scattering and gravimetric instruments for PM2.5 and PM10 quantification.
- Sample Conditioning Units:Thermal management and filtration subsystems facing EU F-Gas Regulation redesign pressures.
Continuous Emission Monitoring Systems dominate installed base. Data Acquisition Systems represent where expansion concentrates.
Technology:
Cost tiers separate laboratory-grade precision from field-deployable durability. FTIR platforms command premium positioning against electrochemical alternatives suited for distributed, low-maintenance installations.
- Fourier Transform Infrared Spectroscopy:Multi-species analyzers detecting mercury and organic compounds at parts-per-billion thresholds. Cement manufacturers in Germany deploy these for EU Green Deal compliance as sensitivity mandates tighten.
- Electrochemical Sensors:Compact, low-power arrays for CO and NOx detection in remote monitoring configurations. North American coal-to-gas conversion projects sustain replacement demand for modified flue stream compatibility.
- Ultraviolet Fluorescence:SO2-specific detection with minimal cross-interference from CO2 or water vapor.
- Chemiluminescence:NO and NOx quantification standard for regulatory reference methods.
- Non-Dispersive Infrared:Cost-effective CO2 and hydrocarbon monitoring for baseline compliance screening.
FTIR platforms command premium positioning. Electrochemical sensors are climbing the fastest on volume.
Application:
Customer concentration varies by enforcement intensity. Cement and metal producers face binding EU directive deadlines, while waste facilities navigate emerging PFAS monitoring uncertainty.
- Power Generation:Centralized utility fleets with 24/7 operational coverage mandates. China's MEE GB standards and US EPA Part 75 drive parallel certification requirements for multinational operators.
- Cement Production:Rotary kiln emissions with high particulate loading and variable sulfur profiles. German industrial clusters upgrade analyzer sensitivity ahead of EU Industrial Emissions Directive benchmarks.
- Chemical Processing:Petrochemical and specialty chemical stack monitoring for VOC and hazardous air pollutant control.
- Metal Manufacturing:Smelter and foundry emissions with heavy metal and particulate compliance requirements.
- Waste Management:Incinerator and landfill gas monitoring awaiting finalized PFAS stack testing protocols.
Power Generation anchors revenue concentration. Cement Production is where near-term upgrade cycles concentrate.
End User:
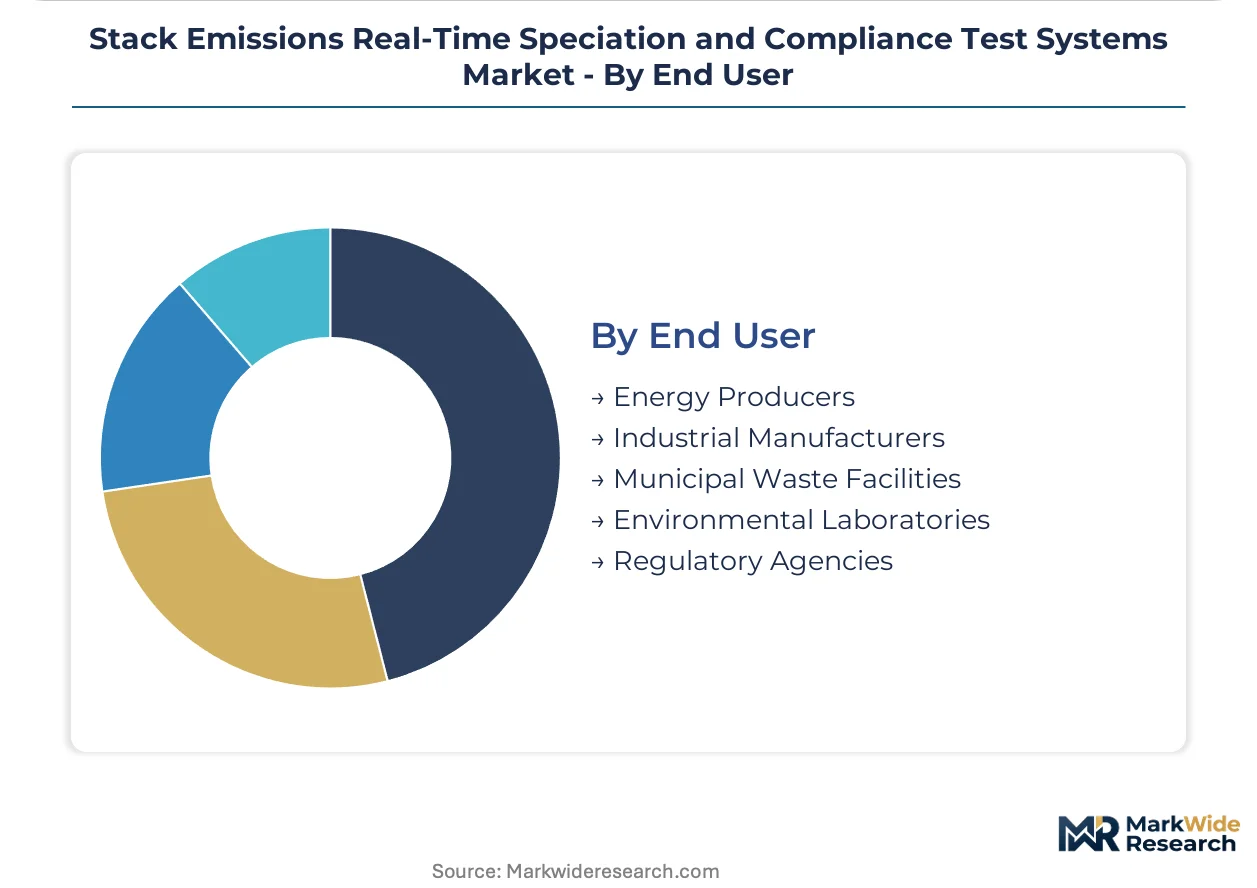
Procurement authority fragments between operational technology teams and centralized sustainability offices. Energy producers retain longest-standing vendor relationships; environmental laboratories drive method development demand.
- Energy Producers:Vertically integrated utilities with captive maintenance capabilities. German municipal operators face technician scarcity that accelerates remote diagnostics adoption.
- Industrial Manufacturers:Cement, metal, and chemical producers with process-integrated monitoring requirements. China's dual carbon goals force domestic procurement preferences under MEE localization mandates.
- Municipal Waste Facilities:Public-sector incinerators with constrained capital budgets and extended procurement cycles.
- Environmental Laboratories:Third-party validation and reference method development services.
- Regulatory Agencies:Certification body procurement for compliance auditing and enforcement infrastructure.
Energy Producers dominate installed base. Industrial Manufacturers represent where technology transfer partnerships concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German cement manufacturers deploy FTIR platforms for EU Green Deal compliance, while Chinese utilities prioritize domestic-certified systems under MEE localization mandates. North American coal-to-gas conversions sustain electrochemical sensor replacement cycles.
United States
Power generation utilities anchor demand through coal-to-gas conversion projects requiring modified flue gas analyzer configurations. The EPA enforces 40 CFR Part 75 recertification timelines that compress hardware validation windows. Industrial clusters in Texas and the Ohio River Valley upgrade sensitivity specifications for mercury detection at parts-per-billion thresholds.
Germany
Cement and metal manufacturers face binding EU Industrial Emissions Directive deadlines accelerating analyzer refresh cycles. The Federal Environment Agency applies stringent sensitivity benchmarks that force FTIR platform upgrades. The Ruhr industrial cluster and Bavarian cement works dominate installed base concentration as compliance deadlines approach.
China
Domestic procurement preferences under MEE GB standards create captive demand for technology localization partnerships. The dual carbon goals force state-owned utilities toward continuous monitoring infrastructure with indigenous certification. Yangtze River Delta power generators and Shandong industrial clusters lead deployment velocity for localized analyzer platforms.
Japan
Specialty calibration gas production concentrates in industrial corridors serving regional export markets. METI standards shape reference method requirements for stationary source monitoring. Osaka-Kobe manufacturing zones and Nagoya industrial areas sustain demand for high-precision FTIR refurbishment programs.
Stack Emissions Real-Time Speciation and Compliance Test Systems Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player archetypes: diversified instrumentation conglomerates with global service infrastructure, specialized analyzer manufacturers with deep spectroscopy expertise, and regional system integrators with localized certification capabilities. Consolidation pressure operates through strategic technology licensing partnerships rather than outright acquisition, while portfolio diversification into predictive analytics software represents the dominant competitive vector.
Among diversified instrumentation groups, Thermo Fisher Scientific and Siemens occupy positions exemplifying scale-driven service unbundling. Specialized analyzer manufacturers including HORIBA and ENVEA represent the capability-intensive tier focused on FTIR platform sensitivity advancement. ABB and Emerson anchor the industrial automation-integrated segment where emissions monitoring converges with broader process control infrastructure. These named entities illustrate competitive positioning without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| HORIBA |
| ENVEA |
| SICK |
| MKS Instruments |
| Siemens |
| Fuji Electric |
| ABB |
| Emerson |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's container rate volatility feeds directly into analyzer landed costs from German and Japanese production hubs, compressing margins for remote monitoring deployments while amplifying price spreads between premium FTIR platforms and standard electrochemical arrays.
Pricing Analysis
Long-term offtake contracts dominate procurement for Continuous Emission Monitoring Systems, with German cement manufacturers locking in decade-long hardware-service bundles. Price differentiation rests on EPA 40 CFR Part 75 certification tier and embedded AI analytics capability. Cost compression in standard electrochemical tiers is intensifying because Chinese domestic vendors are undercutting legacy import pricing. Municipal waste facilities exhibit highest price sensitivity; integrated utilities with captive maintenance capabilities are least sensitive.
Supply Chain Analysis
Extended payment terms from German calibration gas suppliers are tightening working capital requirements for FTIR platform assemblers. Component sourcing concentrates in Germany, Japan, and China, drawing from specialty optical elements, electrochemical sensor membranes, and certified reference gas mixtures. Single-source vulnerability sits with hydrogen fluoride purification for sample conditioning subsystems facing EU F-Gas redesign mandates. Distribution runs through authorized service integrators with localized EPA and MEE certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as hydrogen combustion emission profiles and PFAS stack monitoring mandates create fresh speciation demand ahead of finalized regulatory protocols.
For Market Incumbents: Entrench service infrastructure advantage by extending remote diagnostics coverage to offset technician scarcity in German industrial clusters. Deepen backward integration into specialty calibration gas production to neutralize procurement bottlenecks from Japanese supply concentration. Prioritize FTIR spectral library development for hydrogen-blended fuel matrices before protocol standardization locks in competitor solutions. For New Entrants and Emerging Players: Establish a beachhead in China's Yangtze River Delta utility market through technology localization partnerships that satisfy MEE domestic procurement preferences. Target municipal waste facilities awaiting finalized EPA PFAS testing protocols with preemptive analyzer configurations. Pursue software-only Data Acquisition System licensing to bypass hardware certification barriers. For Investors and Strategic Acquirers: Specialized FTIR refurbishment service providers with captive European industrial relationships represent the most defensible acquisition archetype. Long-term viability hinges on recurring revenue share from predictive maintenance platforms displacing bundled hardware contracts. Monitor EPA PFAS protocol finalization as the signal for capital allocation timing into preemptive analyzer configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Localization Partnership | MEE GB standards compliance unlocks Chinese state utility procurement channels. |
| Remote Diagnostics Platform Expansion | German technician scarcity accelerates subscription-based service unbundling. |
| FTIR Spectral Library Investment | Hydrogen combustion validation gaps create first-mover certification advantage. |
| Calibration Gas Backward Integration | German and Japanese supply concentration creates captive margin opportunity. |
| AI-Driven Data Acquisition Licensing | Cloud-native retrofit avoids hardware replacement cycles in legacy utility infrastructure. |
Research Methodology
A spread of perspectives from utility environmental compliance officers, EPA certification auditors, MEE standards engineers, FTIR platform R&D directors, and European aftermarket service managers converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from EPA 40 CFR Part 75 docket records, MEE GB standard publications, EU Industrial Emissions Directive implementation reports, and customs trade data for analyzer component flows. Bottom-up unit economics triangulated against top-down regulatory mandate sizing.
Demand-supply balance modeling across the projection horizon captured replacement cycle velocity for Continuous Emission Monitoring Systems against new installation demand from coal-to-gas conversions. Segmentation dimensions spanned product type, detection technology, application vertical, and end-user procurement authority. CAGRs derived from regulatory deadline clustering and technology refresh elasticity. Industry-specific inputs included EPA recertification timeline compression and EU F-Gas Regulation phase-down schedules.
Stress conditions across hydrogen fuel blend adoption rates, PFAS protocol finalization timing, and calibration gas supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology transfer partnership success rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Global Residue Testing Market
Testing Equipment
Adhesive Tester Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Cyclic Corrosion Test Chamber Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Laboratory Centrifuge and Accessories Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Chemical Testing Services Market