

High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market Insights
FDA 21 CFR Part 11 is rebalancing the cost-of-entry calculus for vendors serving regulated pharmaceutical and forensic laboratories. Thermo Fisher Scientific leverages its installed base of chromatography software to sustain recurring revenue from compliance upgrades. Waters Corporation anchors its competitive position through proprietary ion source architectures that differentiate workflow throughput. SCIEX specializes in tandem quadrupole platforms for regulated bioanalysis, occupying a defensible niche in clinical research and toxicology testing.
High Performance Liquid Chromatography-Tandem Mass Spectrometry Systems combine liquid chromatography separation with tandem mass spectrometric detection, typically achieving mass resolution below 0.1 Da and detection limits in the picogram-per-milliliter range for complex biological matrices. These systems quantify trace analytes in pharmaceutical metabolites, environmental contaminants, and food adulterants with molecular specificity that single-stage detectors cannot match. Triple Quadrupole LC-MS leads the product landscape due to its dominant role in regulated quantitative bioanalysis, while QTOF LC-MS represents the fastest-expanding category as proteomics and metabolomics research demands high-resolution accurate mass capabilities. Pharmaceutical Testing commands the largest application share, though Environmental Analysis is gaining traction as per- and polyfluoroalkyl substance regulations tighten across jurisdictions.
The FDA enforces Current Good Manufacturing Practice standards that mandate validated analytical methods for drug approval submissions, directly shaping instrument procurement specifications in biopharmaceutical companies. The EPA and EMA maintain parallel requirements for environmental and pharmaceutical residue monitoring, creating a multi-jurisdictional compliance burden that favors vendors with global service networks and harmonized software platforms. Stakeholders must monitor evolving PFAS testing mandates and biosimilar approval pathways, as these regulatory currents will determine which instrument configurations and application workflows command priority investment across laboratory end users.
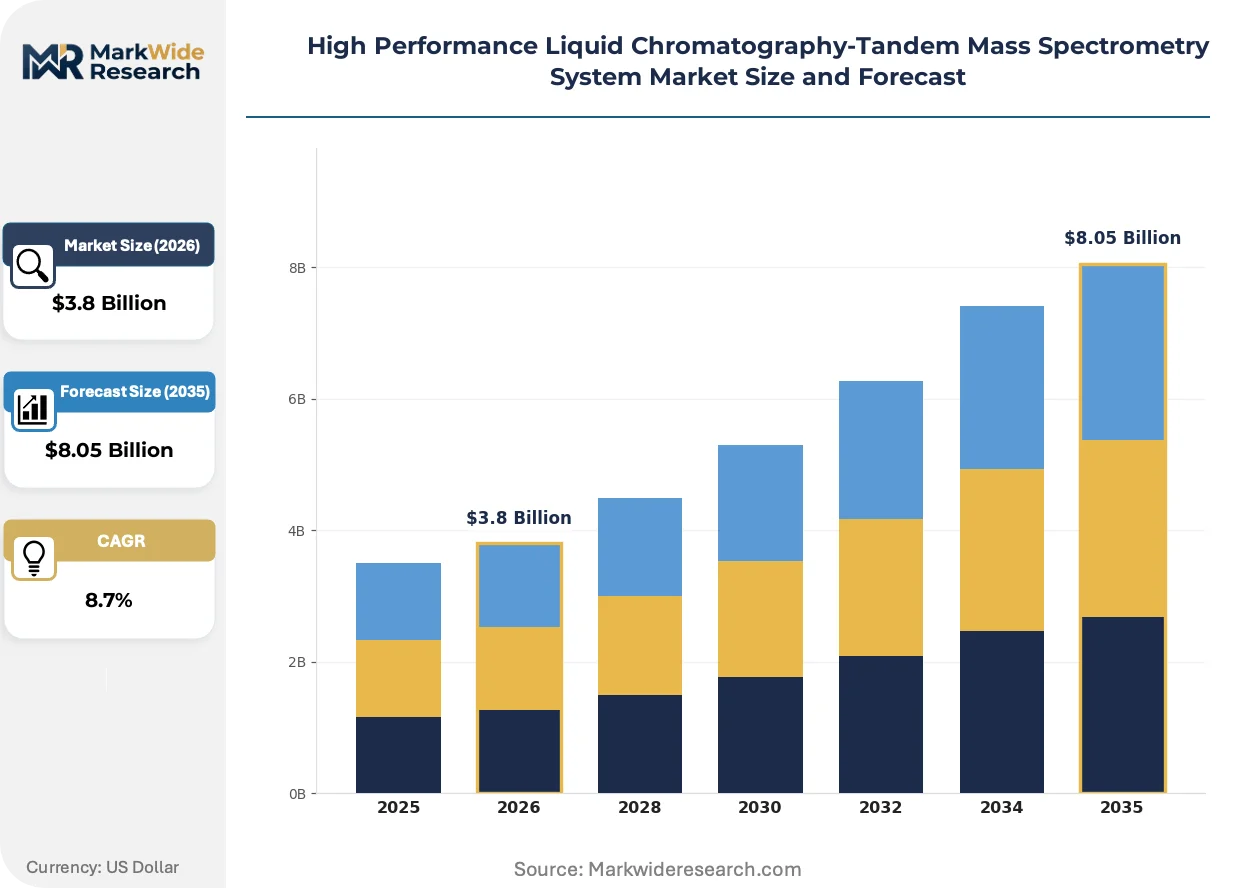
Market Dynamics
Triple quadrupole platform standardization is compressing method transfer timelines across contract research organizations, forcing vendors to differentiate through software ecosystems rather than hardware specifications alone.
Growth Catalysts
- PFAS monitoring mandates:The EPA's expanded testing requirements for per- and polyfluoroalkyl substances in drinking water are compelling environmental laboratories to upgrade from single-stage detection to tandem mass spectrometry configurations.
- Biosimilar approval pathways:FDA's rigorous bioequivalence standards for generic biologics are sustaining demand for validated LC-MS/MS workflows in contract manufacturing organizations.
- China's centralized reference laboratory buildout:Provincial health commissions in Jiangsu and Guangdong are consolidating testing capacity into high-throughput facilities equipped with tandem quadrupole systems.
Market Restraints
- Helium supply volatility:Chromatographic carrier gas costs have destabilized operating budgets for laboratories running high-throughput separations, prompting migration to hydrogen alternatives with method revalidation burdens.
- Detector component concentration:Electron multiplier manufacturing is concentrated among a limited set of specialized suppliers, creating single-source vulnerability for instrument refurbishment cycles.
- Cross-platform method incompatibility:Proprietary ion source geometries prevent direct method transfer between vendor ecosystems, locking users into existing installed bases.
Strategic Opportunities
- India's pharmaceutical quality infrastructure:CDSCO's tightening bioanalytical standards for export-oriented manufacturers are creating first-time adoption opportunities in Ahmedabad and Hyderabad clusters.
- Clinical toxicology expansion:Hospital-based laboratories are integrating LC-MS/MS into emergency toxicology workflows, displacing immunoassay platforms for therapeutic drug monitoring.
- AI-assisted spectral interpretation:Machine learning deconvolution algorithms are reducing analyst training requirements for complex metabolite identification tasks.
Industry Challenges
- Mass spectrometrist talent scarcity:Universities are producing insufficient graduates with hands-on experience in tandem quadrupole optimization and troubleshooting.
- 21 CFR Part 11 validation timelines:Electronic records compliance for software upgrades extends instrument deployment cycles by four to six months in regulated environments.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market Trends and Innovations
Workflow automation and cloud-native data architectures are redrawing competitive boundaries, separating vendors with integrated platform strategies from point-solution specialists.
Microflow chromatography is electrifying sample throughput economics by reducing solvent consumption eighty percent while maintaining sensitivity for pharmacokinetic studies. Biopharmaceutical contract laboratories in Massachusetts and Basel are adopting these configurations for high-volume bioanalytical programs. The technology is electrifying competitive positioning for vendors offering seamless method transfer from conventional to microflow formats.
REACH's expanded authorization requirements for analytical reference standards are forcing reagent suppliers to document supply chain provenance through certified mass spectrometry characterization. European environmental laboratories must now demonstrate metrological traceability for PFAS quantification methods. German and Dutch testing facilities are responding by consolidating procurement with vendors offering bundled instrument-reagent-service packages.
Service contract unbundling is fragmenting the traditional captive maintenance model, with third-party field service organizations now qualifying for warranty-preserving interventions on triple quadrupole platforms. Academic core facilities in the United States are piloting pay-per-use arrangements with remote diagnostic support. This shift is most pronounced in California and Texas, where capital constraints favor operational expenditure structures over instrument ownership.
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market Segmentation
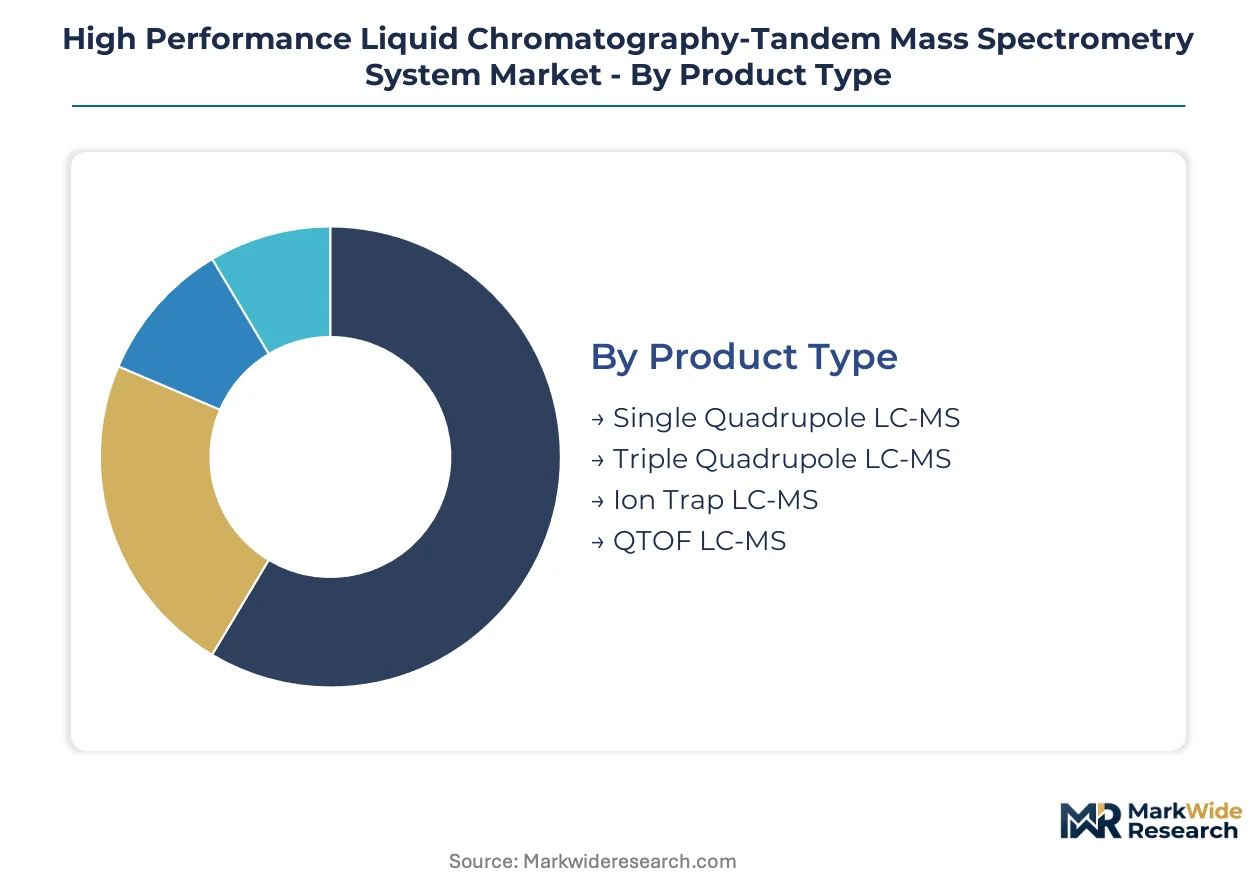
LC-MS/MS procurement decisions cluster around four intersecting dimensions: platform physics, analytical workflow, capital ownership structure, and physical operating environment. Each segmentation axis carries distinct margin profiles and vendor competitive dynamics.
Product Type:
Capital intensity varies dramatically across mass analyzer architectures, with high-resolution platforms demanding substantially greater upfront investment than unit-resolution workhorses.
- Triple Quadrupole LC-MS:Unit-resolution tandem platforms dominate regulated quantitative bioanalysis through multiple reaction monitoring selectivity. Pharmaceutical testing laboratories in the United States and Germany anchor procurement volume, driven by FDA and EMA bioequivalence mandates for generic drug approvals.
- QTOF LC-MS:Quadrupole time-of-flight configurations deliver high-resolution accurate mass capabilities essential for untargeted metabolomics and proteomics discovery. Academic core facilities in Basel and Boston are expanding installations as research funding shifts toward systems biology approaches.
- Single Quadrupole LC-MS:Entry-level platforms serve routine screening applications with limited fragmentation capability.
- Ion Trap LC-MS:Compact architectures target teaching laboratories and method development workflows requiring MSn sequencing.
Most installed capacity flows through Triple Quadrupole LC-MS. Expansion is steepest in QTOF LC-MS.
Application:
Regulatory enforcement intensity directly shapes application-level demand, with compliance deadlines forcing synchronized upgrade cycles across laboratory networks.
- Pharmaceutical Testing:Bioanalytical method development for pharmacokinetics and immunogenicity assessments consumes the largest instrument allocation. Contract research organizations in India and China are building captive capacity as CDSCO and NMPA tighten bioequivalence standards for export markets.
- Environmental Analysis:PFAS quantification in drinking water and soil matrices is accelerating tandem MS adoption. EPA Method 1633 implementation is compelling environmental laboratories to displace single-stage detection across the United States.
- Food Safety:Pesticide residue and veterinary drug monitoring programs drive multi-residue screening workflows.
- Forensic Toxicology:Post-mortem and impaired driving investigations require broad-spectrum drug screening with definitive quantification.
- Petrochemical Analysis:Hydrocarbon fingerprinting and additive identification support refinery quality control operations.
Pharmaceutical Testing commands the largest installed base. Environmental Analysis is gaining share fastest as PFAS mandates proliferate.
End User:
Procurement authority and funding mechanisms diverge sharply between externally regulated commercial entities and publicly funded research infrastructure.
- Biopharmaceutical Companies:In-house bioanalytical groups at large molecule developers prioritize triple quadrupole platforms with validated software ecosystems. Massachusetts and North Carolina clusters are expanding headcount for biosimilar development programs.
- Contract Research Organizations:Method transfer standardization across client portfolios favors vendor-agnostic platform selection with harmonized service contracts.
- Government Laboratories:Centralized reference facilities in Jiangsu and Guangdong provinces are consolidating testing capacity with high-throughput tandem quadrupole configurations.
- Academic Research:Core facilities balance capital constraints against publication demands for cutting-edge resolution capabilities.
Biopharmaceutical Companies deploy the most units per organization. Contract Research Organizations are expanding fleet size most aggressively.
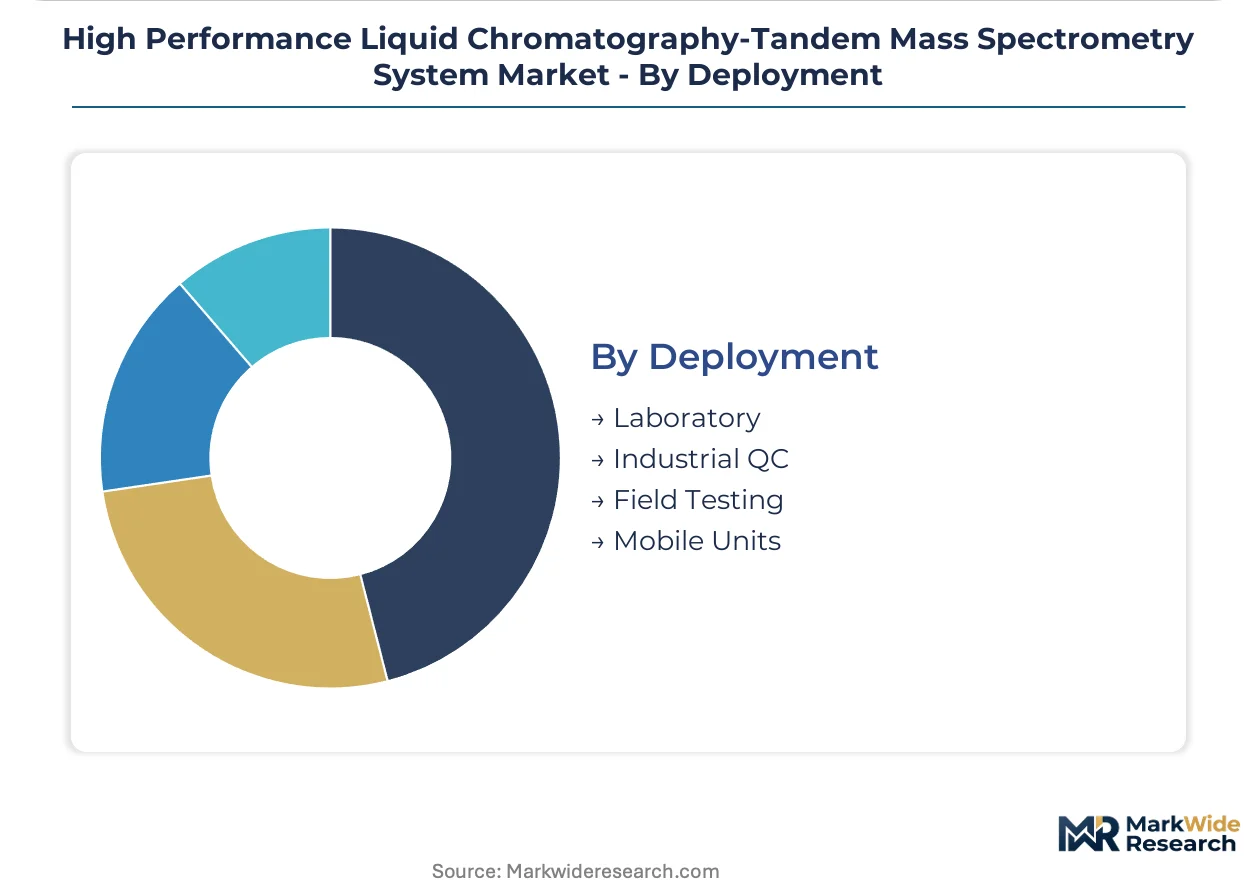
Deployment:
Operating environment constraints determine instrument ruggedization requirements and service model design.
- Laboratory:Climate-controlled facilities with stable power and consumables supply chains support the full performance envelope of high-resolution platforms.
- Industrial QC:At-line installations in pharmaceutical manufacturing suites demand rapid cycle times and validated cleaning protocols.
- Field Testing:Mobile environmental monitoring units require compact ion source designs and simplified maintenance procedures.
- Mobile Units:Emergency response and border inspection applications prioritize battery-operated portability over analytical performance.
Laboratory deployments host the most sophisticated configurations. Industrial QC is shifting fastest toward integrated at-line detection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass spectrometrist talent pools concentrate in metropolitan research corridors where pharmaceutical and environmental testing clusters overlap with academic training programs. FDA, EMA, and NMPA compliance timelines synchronize procurement cycles across these geographies.
United States
Biosimilar development programs and PFAS monitoring mandates drive tandem quadrupole demand. EPA Method 1633 implementation compels environmental laboratories to upgrade detection capabilities. Massachusetts and North Carolina biopharmaceutical clusters expand captive bioanalytical capacity.
Germany
REACH authorization requirements for analytical reference standards tighten documentation burdens. EMA bioequivalence standards sustain validated LC-MS/MS procurement. Basel-proximate contract laboratories in Baden-Württemberg consolidate high-throughput configurations.
China
Provincial health commissions in Jiangsu and Guangdong build centralized reference laboratories. NMPA tightens bioequivalence standards for export-oriented manufacturers. Yangtze River Delta testing facilities adopt triple quadrupole platforms for pharmaceutical quality control.
India
CDSCO bioanalytical standards for export markets create first-time adoption opportunities. Ahmedabad and Hyderabad pharmaceutical manufacturing clusters invest in validated workflows. Government laboratory consolidation in Maharashtra and Gujarat accelerates tandem MS procurement.
Japan
PMDA pharmacokinetic guidelines sustain demand for high-sensitivity quantification platforms. METI environmental monitoring programs expand PFAS testing capacity. Kanto region academic core facilities upgrade to high-resolution accurate mass configurations for proteomics research.
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across platform architectures and service models. The vendor base stratifies into three tiers: integrated life science conglomerates with chromatography software ecosystems, mass spectrometry specialists with proprietary ion source technologies, and regional instrumentation houses with price-competitive entry-level platforms. Dominant competitive moves include portfolio diversification into microflow chromatography configurations and strategic partnerships with third-party field service organizations for contract unbundling.
Among diversified life science conglomerates, Thermo Fisher Scientific and Agilent Technologies occupy positions spanning chromatography software through detector hardware. SCIEX exemplifies the tandem quadrupole specialist archetype with concentrated focus on regulated bioanalysis workflows. Waters Corporation anchors the premium-tier segment through proprietary ion source architectures that differentiate workflow throughput for pharmaceutical testing laboratories.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| SCIEX |
| Waters Corporation |
| Shimadzu Corporation |
| Bruker |
| PerkinElmer |
| Hitachi High-Tech |
| JEOL |
| Others |
Pricing and Supply Chain Analysis
Triple quadrupole platform standardization against high-resolution QTOF premium positioning bifurcates the market into commodity unit-resolution workhorses and precision analytical instruments, with the former driving volume procurement in China's government laboratories and the latter commanding margin premiums in Basel and Boston academic cores. This tier divergence manifests in supply chain configurations where electron multiplier detector manufacturing concentrates among Japanese and German specialized suppliers for premium platforms, while Chinese contract manufacturers scale assembly capacity for entry-level single quadrupole systems.
Pricing Analysis
Bundled service contracts versus unbundled third-party maintenance arrangements split buyer economics sharply, with pharmaceutical testing laboratories in the United States and Germany absorbing premium pricing for validated software ecosystems and FDA 21 CFR Part 11 compliance modules. Price differentiation hinges on ion source architecture proprietary protection and multi-year service bundling, with helium supply volatility intensifying cost compression in high-throughput environmental laboratories. Contract research organizations in India exhibit acute price sensitivity, while biopharmaceutical captive facilities in Massachusetts prioritize throughput validation over capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing qualification mandates from FDA-regulated pharmaceutical laboratories force instrument vendors to maintain qualified secondary suppliers for critical ion source and detector subassemblies. Manufacturing concentration spans Germany for precision mass analyzer components, Japan for electron multiplier detectors, and China for chassis and fluidic assemblies. Supply chain vulnerability centers on single-source electron multiplier refurbishment cycles. Distribution runs through direct field service organizations for premium platforms and third-party distributors for price-competitive configurations in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO bioanalytical tightening in India creates first-time adoption demand at price points forty percent below equivalent procurement in FDA-regulated United States facilities.
For Market Incumbents: Extend software ecosystem lock-in through seamless microflow chromatography method transfer capabilities, defending against third-party field service unbundling that fragments traditional captive maintenance revenue. Deepen backward integration into ion source manufacturing to reduce detector component concentration exposure. Prioritize certification investment for EPA Method 1633 compliance modules as PFAS mandates synchronize upgrade cycles across environmental laboratory networks. For New Entrants and Emerging Players: AI-assisted spectral interpretation algorithms offer a technology-first wedge into clinical toxicology emergency workflows where analyst talent scarcity constrains incumbent expansion. Target hospital-based laboratories in Texas and California where capital constraints favor pay-per-use operational expenditure structures over instrument ownership. Pursue white-label OEM partnerships with established chromatography hardware suppliers to bypass proprietary ion source geometry barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where service contract unbundling fragments vendor-customer relationships and creates distressed asset opportunities among regional instrumentation houses. Long-term viability favors platforms with harmonized software architectures spanning triple quadrupole and QTOF configurations. Watch NMPA bioequivalence standard harmonization with FDA as the signal indicating accelerated procurement synchronization across Chinese provincial reference laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Microflow Chromatography Configuration Launch | Eighty percent solvent reduction captures Massachusetts and Basel biopharmaceutical contract laboratory demand. |
| Third-Party Field Service Partnership | Unbundled maintenance arrangements penetrate California and Texas academic core facilities facing capital constraints. |
| AI-Assisted Spectral Interpretation Integration | Machine learning deconvolution reduces analyst training requirements for complex metabolite identification workflows. |
| Helium-to-Hydrogen Carrier Gas Transition | Alternative carrier validation addresses supply volatility destabilizing high-throughput environmental laboratory operating budgets. |
| Bundled Instrument-Reagent-Service Package Consolidation | REACH authorization documentation burdens force European environmental laboratories toward single-vendor procurement. |
Research Methodology
Bottom-up pharmaceutical testing laboratory procurement tracking reconciled against top-down mass spectrometry vendor shipment monitoring forms the analytical core. Primary interviews with bioanalytical method development directors, regulatory affairs validation specialists, environmental laboratory operations managers, and academic core facility directors combine with secondary validation against FDA 483 inspection observations, EPA method implementation timelines, EMA bioequivalence submission databases, and NMPA export certification records. Triangulation across installed base estimates and replacement cycle analysis yields market sizing.
Historical trendline analysis of triple quadrupole and QTOF platform replacement cycles informs projection modeling across the analysis window. Segmentation dimensions span mass analyzer architecture, application workflow, end-user procurement authority, and deployment environment constraints. CAGRs derive from instrument unit shipment trajectories weighted by average selling price evolution and service contract attachment rate assumptions. Forecast inputs incorporate PFAS regulatory mandate implementation schedules and biosimilar approval pathway throughput requirements.
The model holds under stable helium supply conditions and continued FDA-EMA-NMPA regulatory harmonization; deviation in carrier gas substitution economics or abrupt trade restriction imposition would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.