
 Digital Pulse Mixer Market | 2026-2036
Digital Pulse Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Pulse Mixer Market Insights
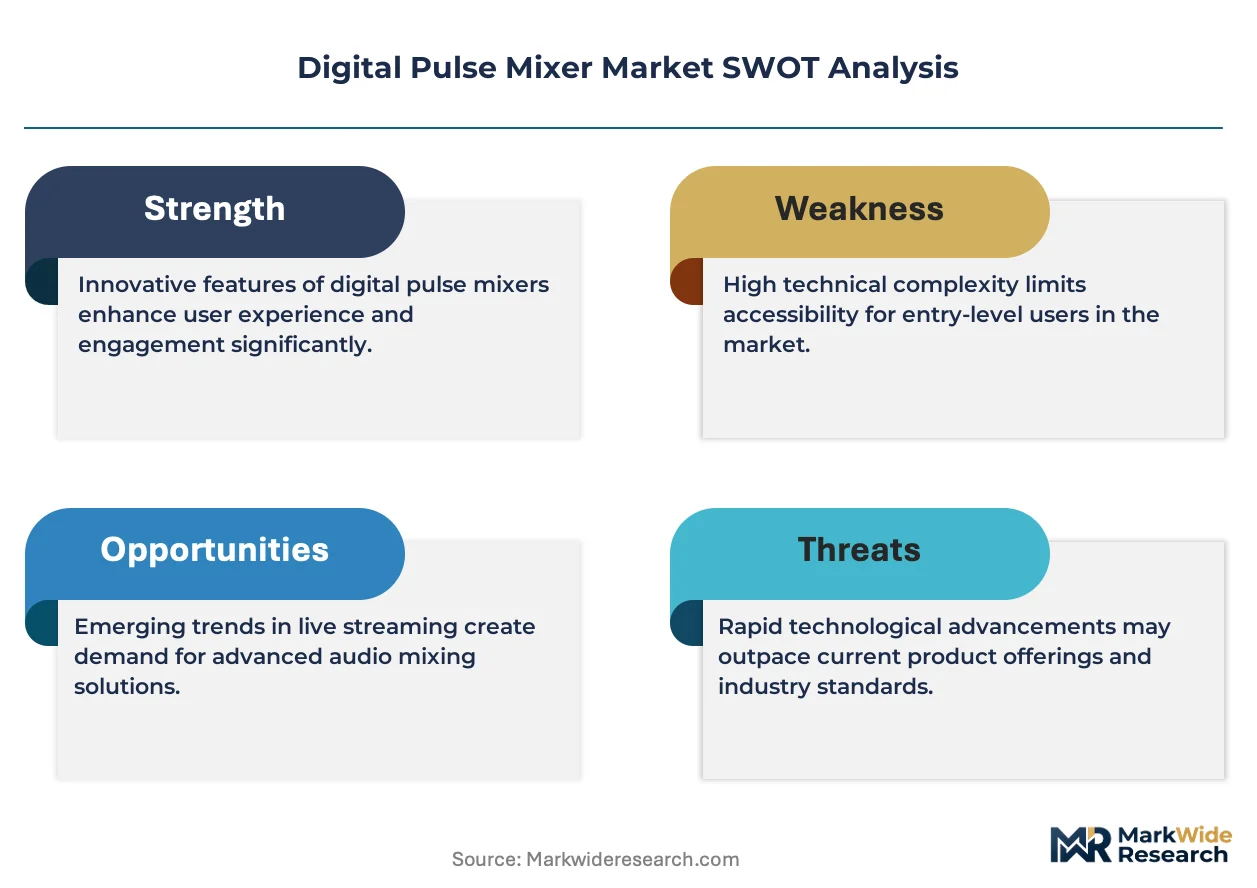
Japanese semiconductor foundry capacity for audio DSP chips is hardening as consumer electronics and pro-audio sectors compete for wafer starts. Yamaha Corporation leverages captive semiconductor relationships to sustain mixer production continuity. Roland Corporation anchors its competitive stance through deep specialization in live performance interfaces. Allen & Heath competes aggressively on channel density per rack unit in touring applications.
A digital pulse mixer is an audio signal processing device that employs digital signal processing to combine, route, and modify multiple audio inputs through time-domain pulse-width modulation techniques, typically operating at sampling rates of 48 kHz or higher with 24-bit resolution. Its primary commercial purpose is to deliver precise, recallable, and networkable audio mixing for professional sound reinforcement and studio recording environments. Digital mixers occupy the dominant value position within the product type taxonomy due to software-expandable channel counts and Dante/AES67 integration. Live sound venues represent the fastest-growing end user segment as houses of worship and regional theaters replace aging analog infrastructure. App control technology is reshaping operator workflows by enabling tablet-based mixing from audience positions.
FCC equipment authorization requirements govern wireless connectivity modules embedded in US-sold digital pulse mixers, while CE marking under the EU Electromagnetic Compatibility Directive shapes transatlantic product design convergence. Japan's METI enforces energy efficiency standards that influence power supply architecture decisions for mixers sold in East Asian markets. Stakeholders must monitor evolving RF spectrum allocation rulings that could obsolete existing wireless mixer ecosystems.
Market Dynamics
Japanese foundry capacity constraints for audio DSP wafers are forcing pro-audio manufacturers to renegotiate long-term supply agreements and accelerate alternative sourcing strategies across Taiwan and South Korea.
Growth Catalysts
- Dante/AES67 network protocols:Houses of worship and regional theaters are retiring analog snake systems for ethernet-based audio distribution, expanding addressable market for network-native consoles.
- EU Ecodesign Directive standby power limits:Manufacturers redesigning power supply architectures to meet sub-0.5W standby requirements, creating competitive differentiation for compliant product lines.
- Berlin-Hamburg manufacturing corridor:German pro-audio cluster concentration enables rapid prototyping cycles and shared component sourcing for touring-grade mixer chassis.
Market Restraints
- Silicon wafer allocation rigidity:Consumer electronics fabs in Japan prioritize smartphone and automotive orders over specialty audio DSP volumes during capacity crunches.
- Substitution by software mixing:Low-latency native processing on ARM-based tablets threatens entry-level digital mixer categories in small venue applications.
- FCC equipment authorization timelines:Embedded wireless module certification delays average 14-18 weeks, compressing product launch windows for US-bound SKUs.
Strategic Opportunities
- India's live event infrastructure expansion:Metro theater construction in Mumbai and Bangalore creates first-mover advantage for Dante-equipped console vendors.
- App-control workflow convergence:Tablet-based mixing from audience positions enables new service revenue streams and reduces front-of-house footprint requirements.
- METI energy efficiency tiering:Japan's top-runner standards reward premium efficiency designs with preferential procurement status in public venue tenders.
Industry Challenges
- DSP firmware talent scarcity:Real-time audio algorithm development requires specialized embedded systems expertise concentrated in limited geographic pools.
- Legacy analog integration complexity:Hybrid venues demand seamless patching between digital cores and vintage outboard gear without signal degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Pulse Mixer Market |
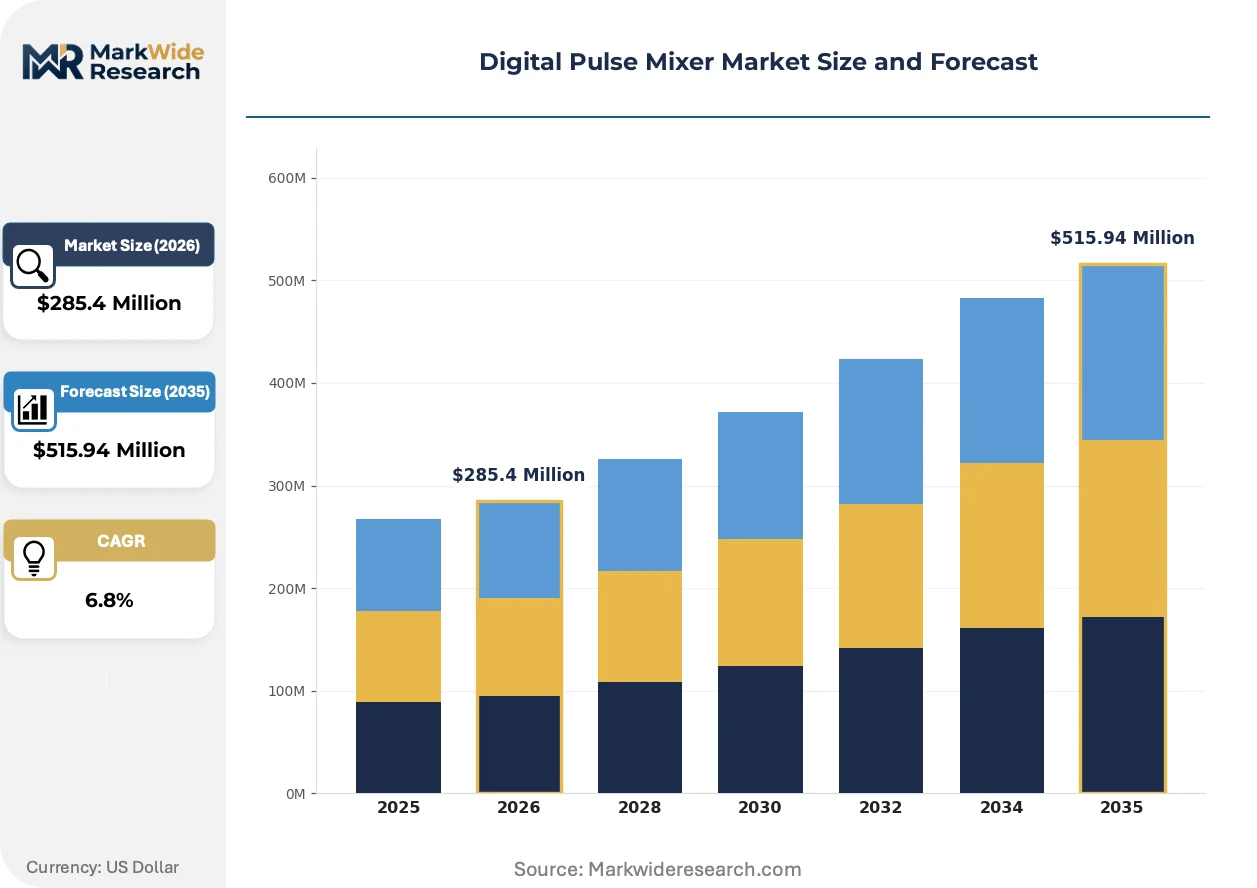
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Mixers, Digital Mixers, Powered Mixers, Standalone Mixers End User: Recording Studios, Live Sound Venues, Broadcast Stations, Audiovisual Production Technology: Wireless Connectivity, USB Output, App Control, MIDI Support Application: Music Production, Film Sound Design, Broadcasting, Events Management |
| Companies Covered | Yamaha Corporation, Behringer, PreSonus Audio Electronics, Allen & Heath, Soundcraft, Roland Corporation, Mackie, Harman International, LOUD Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Pulse Mixer Market Trends and Innovations
Time-domain pulse-width modulation architectures are displacing traditional delta-sigma approaches in high-channel-count touring consoles, enabling denser rack units and reduced thermal footprints.
FPGA-based processing cores is rewriting the economics of channel expansion. Mid-tier manufacturers now field 96-input configurations previously reserved for flagship lines. Rental houses in Nashville and London are standardizing on these platforms for festival deployments. The technology is rewriting how channel density maps to price tiers across the product stack.
EU Electromagnetic Compatibility Directive recasts are tightening emission limits for networked audio devices. Manufacturers must redesign shielding and grounding topologies to maintain CE marking validity. Touring rental fleets operating across Schengen borders face retrofit obligations for pre-2023 inventory.
Sound engineers now expect manufacturer-agnostic control surface compatibility. Open-source control protocols are displacing proprietary tablet apps in house-of-worship and corporate AV installations. This behavioral pivot is most pronounced in US megachurch networks where volunteer operators rotate across multiple venue sites weekly.
Digital Pulse Mixer Market Segmentation
Digital pulse mixer procurement hinges on channel count scalability, network protocol compatibility, and operator workflow preferences. Buyers evaluate total cost of ownership across hardware, Dante licensing, and tablet ecosystem investments. Segmentation reveals where premium configurations command pricing power versus commoditized entry tiers.
Product Type:
Purchase decisions orbit around channel density requirements and recall granularity for touring versus installed applications.
- Digital Mixers:FPGA-based processing cores enable 96-input configurations with scene automation and Dante/AES67 native integration. Houses of worship in the US Southeast and regional theaters across Germany's Berlin-Hamburg corridor are retiring analog infrastructure for these network-native consoles, driven by volunteer operator rotation demands and reduced snake cabling costs.
- Analog Mixers:Transformer-coupled circuitry persists in recording environments seeking harmonic saturation characteristics. Boutique studios in Nashville and London maintain procurement of compact 16-channel configurations for tracking rooms where signal path transparency outweighs recall necessity.
- Powered Mixers:Integrated amplification suits mobile DJ and small venue deployments with severe rack space constraints.
- Standalone Mixers:Self-contained units without expansion ports serve educational institutions and community centers with fixed channel needs and minimal IT infrastructure.
Volume sits with Digital Mixers; growth tilts toward configurations with embedded Dante networking.
End User:
Operational intensity and duty cycle durability separate procurement specifications across buyer categories.
- Live Sound Venues:Touring-grade chassis withstand daily load-in cycles and environmental variance across festival circuits. Rental houses in Nashville and London standardize on FPGA-based platforms for 96-input festival deployments, prioritizing channel-per-rack-unit density and thermal efficiency under sustained full-load operation.
- Recording Studios:Critical listening environments demand ultra-low noise floors and boutique preamplification stages. Facilities in Berlin's pro-audio manufacturing corridor specify custom configurations leveraging local component sourcing for rapid prototyping of hybrid analog-digital signal paths.
- Broadcast Stations:Redundant power supplies and compliance-grade metering satisfy 24/7 on-air reliability requirements.
- Audiovisual Production:Corporate event deployers prioritize rapid setup protocols and tablet-based operator mobility.
Installed base concentrates in Recording Studios; expansion is steepest in Live Sound Venues replacing aging analog infrastructure.
Technology:
Integration depth with existing IT infrastructure determines technology stack adoption sequencing.
- App Control:Tablet-based mixing from audience positions enables front-of-house footprint reduction and volunteer operator accessibility. US megachurch networks with multi-site rotation requirements drive standardization on manufacturer-agnostic open-source control protocols rather than proprietary ecosystems.
- Wireless Connectivity:Embedded RF modules for stage monitoring and talkback systems face FCC equipment authorization timelines averaging 14-18 weeks, compressing product launch windows for US-bound SKUs and favoring vendors with pre-certified module partnerships.
- USB Output:Direct computer interfacing serves podcast production and bedroom studio segments with minimal latency tolerance.
- MIDI Support:Automation synchronization with DAW environments remains essential for post-production workflows in film sound design.
Deployment scale favors Wireless Connectivity; capability investment is climbing fastest in App Control as open protocols displace proprietary tablet ecosystems.
Application:
Content delivery format and distribution channel dictate processing latency and metadata handling requirements.
- Music Production:Multitrack recording and mixdown workflows demand expandable I/O configurations with low-latency monitoring paths. Germany's pro-audio cluster supplies rapid prototyping for hybrid venues requiring seamless patching between digital cores and vintage outboard gear.
- Film Sound Design:Immersive format mixing for theatrical release requires object-based panning and extensive automation snapshot capabilities. Post houses in London and Los Angeles specify consoles with dedicated Dolby Atmos integration and precise sample-accurate synchronization.
- Broadcasting:Live-to-air redundancy and loudness compliance metering dominate specification sheets for network affiliates.
- Events Management:Rapid deployment and strike efficiency prioritize rack density and preset recall speed over sonic refinement.
Revenue concentration rests in Music Production; capability expansion is gaining share fastest in Film Sound Design as immersive format adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese foundry capacity for audio DSP wafers anchors supply-side geography, while German pro-audio manufacturing and US live venue infrastructure anchor demand-side concentration across three continents.
United States
FCC equipment authorization requirements govern wireless connectivity modules in US-sold digital pulse mixers, with certification timelines averaging 14-18 weeks. Nashville rental houses standardize on FPGA-based touring platforms for festival deployments, prioritizing channel density and thermal efficiency under sustained operation.
Germany
The EU's Ecodesign for Energy-Related Products Directive pressures manufacturers to reduce standby power consumption below 0.5W in DSP architectures. Berlin and Hamburg anchor a pro-audio manufacturing corridor enabling rapid prototyping cycles and shared component sourcing for touring-grade mixer chassis.
Japan
METI enforces energy efficiency standards that influence power supply architecture decisions for mixers sold in East Asian markets. Yamaha Corporation leverages captive semiconductor relationships to sustain production continuity as consumer electronics fabs prioritize smartphone and automotive wafer starts.
United Kingdom
Post houses in London specify consoles with dedicated immersive format integration and precise sample-accurate synchronization for theatrical release workflows. The UK market concentrates procurement in broadcast-grade redundant configurations satisfying 24/7 on-air reliability requirements.
India
Metro theater construction in Mumbai and Bangalore creates first-mover advantage for Dante-equipped console vendors. India's live event infrastructure expansion concentrates demand in houses of worship and regional performance venues replacing aging analog snake systems with ethernet-based audio distribution.
Digital Pulse Mixer Market Competitive Landscape
Global majors compete with regional champions across semiconductor access and channel density specifications. The vendor base stratifies into three tiers: integrated conglomerates with captive foundry relationships, specialized pro-audio houses with touring-grade chassis expertise, and value-oriented manufacturers competing on price-per-channel metrics. Dominant competitive moves include strategic partnerships for pre-certified wireless module sourcing and portfolio diversification into tablet-based control ecosystems.
Among Japanese-based conglomerates, Yamaha Corporation and Roland Corporation occupy positions reflecting divergent strategic archetypes: the former exemplifies vertical integration into semiconductor supply chains, while the latter anchors competitive stance through deep specialization in live performance interfaces. Allen & Heath, a UK-based specialist, represents the touring-focused tier competing aggressively on channel density per rack unit. These three entities collectively illustrate how geographic clustering around foundry access, manufacturing corridors, and end-user proximity shapes sustainable differentiation.
| Leading Market Players |
|---|
| Yamaha Corporation |
| Behringer |
| PreSonus Audio Electronics |
| Allen & Heath |
| Soundcraft |
| Roland Corporation |
| Mackie |
| Harman International |
| LOUD Technologies |
| Others |
Pricing and Supply Chain Analysis
DSP firmware engineering talent concentrated in Berlin, Hamburg, and Tokyo commands wage premiums that widen spreads between touring-grade consoles and entry-level configurations. Labor scarcity in real-time audio algorithm development forces manufacturers to absorb higher R&D costs in flagship tiers while compressing margins in price-sensitive segments.
Pricing Analysis
Extended warranty and field service bundling separates touring-grade procurement from stripped-down educational SKUs. Three-tier pricing structure across premium, standard, and economy levels tracks channel density, Dante licensing tiers, and thermal chassis specifications. Price differentiation hinges on FPGA processing capacity and CE marking under EU Electromagnetic Compatibility Directive recasts. Cost compression in entry-level configurations intensifies as ARM-based tablet mixing substitutes rack-mounted hardware in small venues. Houses of worship and community centers exhibit highest price sensitivity; festival rental houses prioritize total cost of ownership over unit price.
Supply Chain Analysis
Regional distribution centers in Nashville, London, and Berlin operate hub-and-spoke patterns to serve touring rental fleets with rapid chassis replacement. Manufacturing concentrates in Japan, Germany, and Taiwan for DSP wafer fabrication, mixer chassis assembly, and FPGA sourcing respectively. Component dependencies include audio-grade capacitors, precision ADC/DAC chipsets, and touring-hardened power supply modules. Single-source vulnerability in Japanese foundry capacity for specialty audio DSP wafers threatens production continuity during consumer electronics allocation crunches. Distribution runs through pro-audio dealer networks and direct rental house contracts with manufacturer technical support integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japanese foundry capacity constraints for audio DSP wafers prop pricing power for manufacturers with captive semiconductor relationships or pre-negotiated long-term supply agreements.
For Market Incumbents: Deepen backward integration into semiconductor supply chains or lock multi-year wafer allocation agreements with Taiwanese and South Korean foundries to insulate against Japanese capacity crunches. Fortify touring-grade chassis IP against FPGA-based mid-tier entrants fielding 96-input configurations. Prioritize certification investment for FCC equipment authorization pre-clearance to compress US product launch windows. For New Entrants and Emerging Players: App-control protocol standardization offers entry into US megachurch networks where volunteer operator rotation demands manufacturer-agnostic tablet compatibility. India's metro theater construction in Mumbai and Bangalore presents the most penetrable geography for Dante-equipped console vendors displacing aging analog infrastructure. Pursue white-label partnerships with established German chassis manufacturers to bypass Berlin-Hamburg prototyping cycle advantages. For Investors and Strategic Acquirers: The window for entry favors specialized pro-audio houses with touring-grade expertise and embedded RF module pre-certification. Long-term viability rests on FPGA-based processing core roadmaps and open-source control protocol adoption curves. Monitor METI energy efficiency tiering announcements as inflection signals for premium efficiency design procurement advantages in Japanese public venue tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Supply Agreement | Japanese foundry allocation rigidity rewards upstream control over audio DSP wafer access. |
| FCC Pre-Certification Partnership | Embedded wireless module pre-clearance compresses 14-18 week authorization timelines for US-bound SKUs. |
| Open-Source Control Protocol Adoption | Manufacturer-agnostic tablet ecosystems displace proprietary apps in US megachurch network procurement. |
| Dante/AES67 Native Integration | Ethernet-based audio distribution replaces analog snake systems in houses of worship and regional theaters. |
| METI Top-Runner Efficiency Design | Premium energy efficiency ratings unlock preferential procurement status in Japanese public venue tenders. |
Research Methodology
Trade association filings, customs records, and FCC equipment authorization databases formed the secondary backbone for supply chain mapping and regulatory timeline analysis. Primary interviews with DSP firmware engineers, touring rental house procurement directors, and pro-audio dealer network managers validated capacity constraint severity and pricing tier elasticity. Bottom-up channel count and Dante licensing revenue estimates triangulated against top-down regional infrastructure spending assessments across Germany, Japan, and the United States.
Historical trendline analysis of FPGA processing core adoption and analog-to-digital console replacement cycles anchored the projection framework. Segmentation modeling spanned product type, end user operational intensity, technology integration depth, and application content format requirements. CAGRs derived from installed base turnover rates and metro theater construction pipelines across Mumbai, Bangalore, and US Southeast megachurch networks. Supply-side assumptions incorporated foundry capacity allocation patterns and EU Ecodesign Directive standby power compliance trajectories.
Several conditions sit outside the modeled scope, including unannounced RF spectrum reallocation rulings that could obsolete wireless mixer ecosystems and geopolitical disruptions to Taiwan-South Korea foundry operations. Forecasts reflect documented assumptions around Japanese semiconductor capacity prioritization and EU Electromagnetic Compatibility Directive recast implementation timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Safety Relay Market
Electronic Components
Serial Device Servers Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
USB Charger Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
Display Port Adapters Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Amplifier Market
Electronic Components
Motherboard Battery Market
Electronic Components
Chip Shield Market
Electronic Components
Microspeaker Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Encoder Market