
 China E-Bike Market | 2026-2036
China E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
China E-Bike Market Intelligence
Zhejiang province's battery pack assembly base is repositioning toward higher energy density lithium-ion configurations. Yadea Group leverages captive cell sourcing to sustain margin control across mid-tier commuter lines. Aima Technology anchors its position through dense distributor networks in tier-two and tier-three cities. Sunra Electric Vehicle competes on cost-optimized lead-acid replacement cycles in rural county markets.
An electric bicycle combines a pedal-driven frame with an integrated electric motor and rechargeable battery, typically rated between 250W and 400W under Chinese national standards, providing motorized assistance for urban mobility and last-mile logistics. Commuter E-Bikes occupy the volume core as daily transport for salary workers across dense metropolitan zones. Lithium-Ion battery configurations command the technology frontier as GB standards phase out heavier lead-acid alternatives in major city registrations. Delivery Services represent the fastest-growing end-user pool as platform economy riders prioritize range and swap-station compatibility.
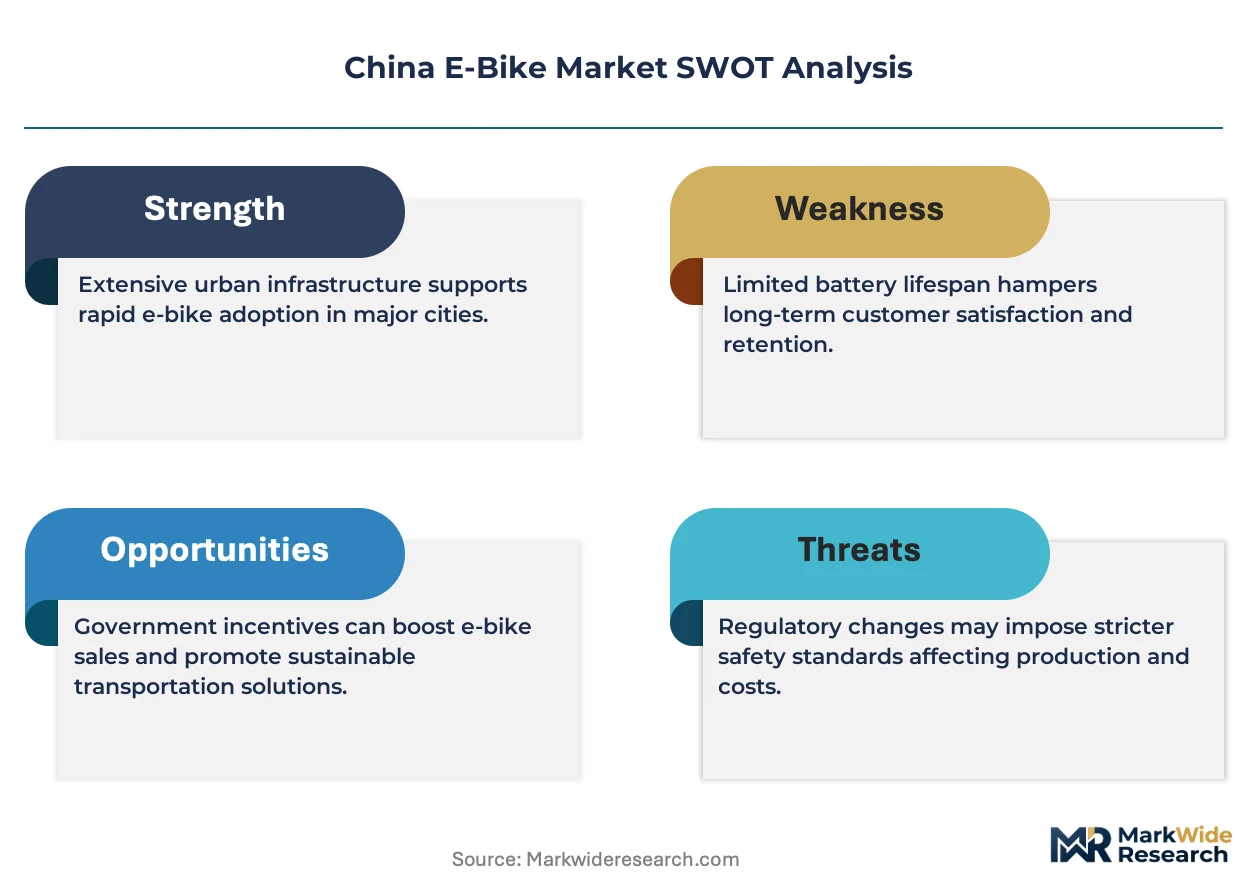
MIIT enforces compulsory product certification under GB 17761 technical specifications, while SAMR monitors market surveillance for non-compliant imports and refurbished units. Local traffic bureaus in Hangzhou and Shenzhen restrict non-certified models from license plate issuance, channeling demand toward standardized OEM supply. Stakeholders must track evolving municipal subsidy taper schedules and battery recycling mandates to calibrate production mix and aftermarket service investments.
Market Dynamics
GB standards for electric two-wheelers are compressing lead-acid replacement cycles while MIIT battery safety certification redirects procurement toward lithium-ion configurations. Municipal license plate restrictions in Hangzhou and Shenzhen are channeling demand toward standardized OEM supply.
Growth Catalysts
- Platform economy expansion:Food delivery and courier services in Shanghai and Beijing are scaling fleet procurement of swap-station-compatible models.
- MIIT certification mandates:Compulsory product certification under GB 17761 technical specifications is eliminating non-compliant refurbished imports from aftermarket circulation.
- Dual carbon policy alignment:National decarbonization targets are accelerating electrification incentives across urban mobility infrastructure.
Market Restraints
- Lithium raw material volatility:Cathode material costs fluctuate with global lithium carbonate spot markets, squeezing pack assembler margins.
- Zhejiang-Jiangsu supply concentration:Battery pack assembly clusters in eastern coastal provinces create geographic vulnerability to regional logistics disruptions.
- GB standard compliance friction:Stricter technical specifications extend product development timelines and raise certification costs for smaller assemblers.
Strategic Opportunities
- Tier-three and county market penetration:Rural markets in central and western provinces remain underpenetrated by lithium-ion configurations.
- Battery-as-a-service models:Subscription and swap-station networks are emerging as alternative ownership structures for delivery fleet operators.
- Recycling mandate preparation:Pending producer responsibility regulations for battery end-of-life management create aftermarket service revenue pools.
Industry Challenges
- Cell chemistry engineering talent scarcity:Qualified battery management system designers and thermal engineers command premium compensation in Zhejiang manufacturing hubs.
- Certification timeline compression:Accelerated GB standard revision cycles strain testing laboratory capacity and delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China E-Bike Market |
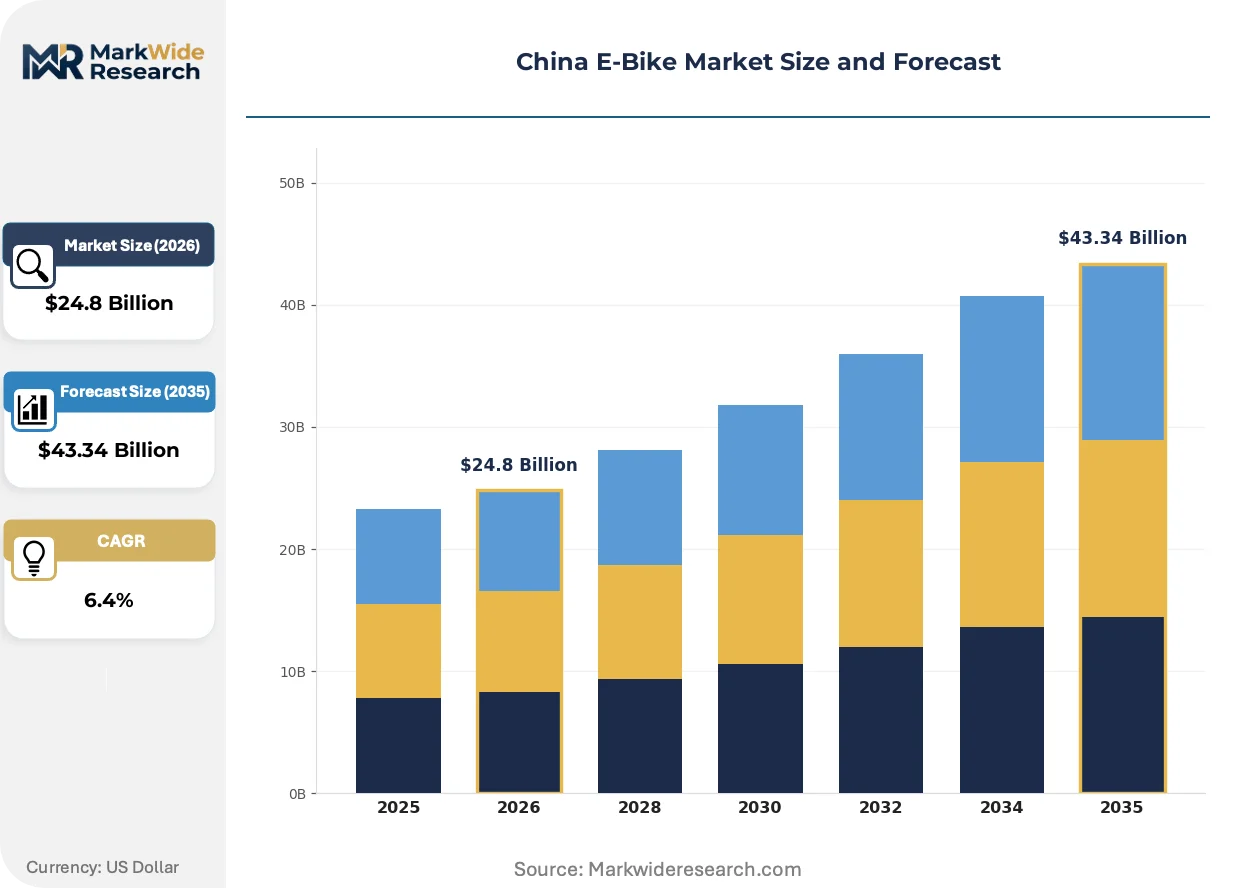
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain E-Bikes, Foldable E-Bikes, Cruiser E-Bikes, Commuter E-Bikes End User: Urban Riders, Off-Road Enthusiasts, Delivery Services, Recreational Users Battery Type: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Lithium Polymer Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Luyuan, XDS Cycle, Yadea Group, FTN Electric Bike, Lima Vehicle, Aima Technology, Sunra Electric Vehicle, Ninebot, Zhejiang JSL Vehicle Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China E-Bike Market Strategic Shifts & Innovations
Intelligent battery management systems and connected vehicle platforms are reshaping how fleet operators monitor asset utilization. Manufacturers are repositioning R&D investments toward software-defined performance optimization.
Solid-state and semi-solid electrolyte research is integrating into next-generation pack designs for delivery service applications. Platform economy riders in Beijing and Shanghai are piloting these configurations for extended range requirements. The technology is integrating thermal stability improvements that reduce swap frequency and enable higher energy density without GB standard compliance trade-offs.
MIIT enforcement protocols for GB 17761 certification are tightening market surveillance procedures for non-compliant imports. SAMR monitoring mechanisms now coordinate with local traffic bureaus to block license plate issuance for uncertified models. Delivery fleet procurement departments are responding by mandating OEM documentation audits before volume orders.
Subscription-based battery access is displacing outright ownership among high-utilization delivery riders. Dense swap-station networks in Shenzhen and Hangzhou are replacing overnight charging for platform economy workers. This pattern concentrates most visibly in metropolitan zones where municipal infrastructure subsidies support station deployment density.
China E-Bike Market Segmentation
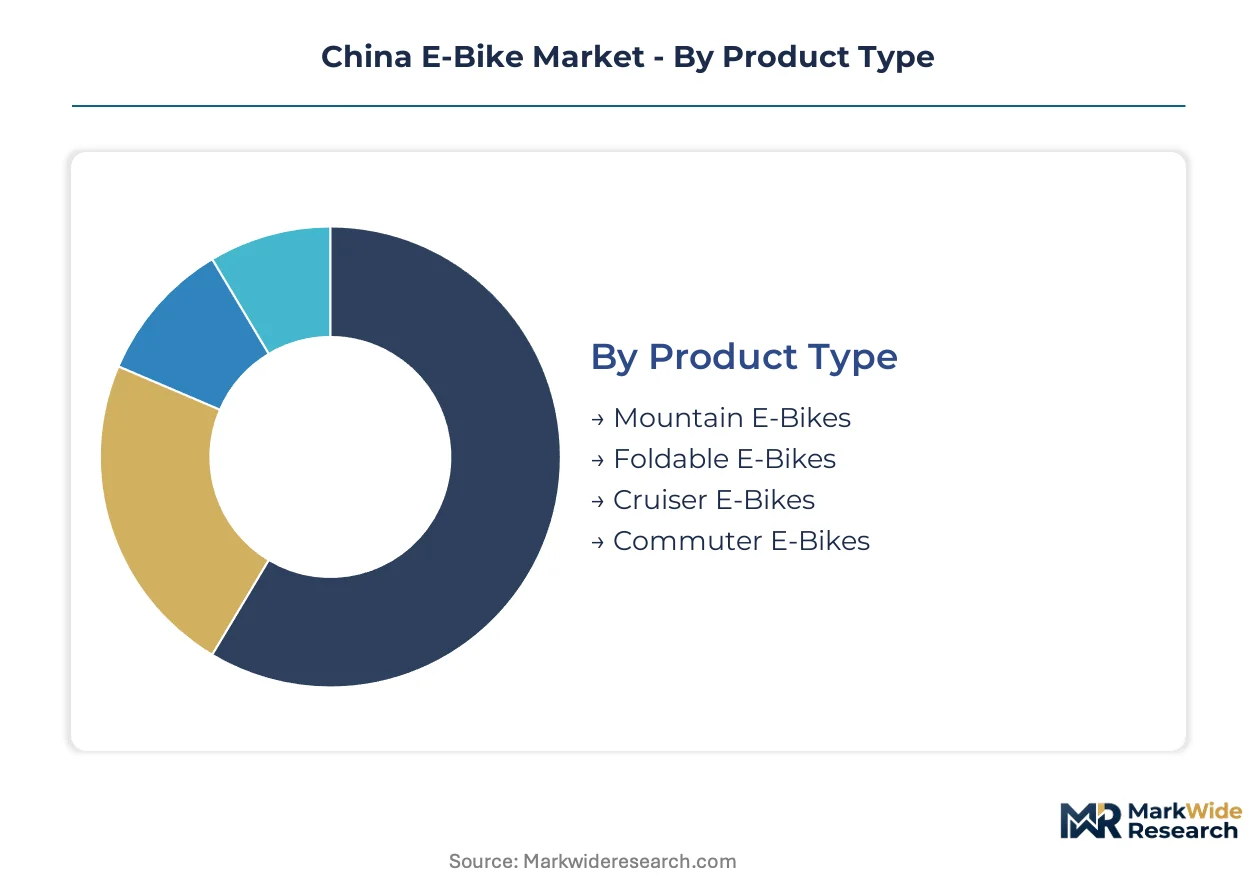
Segmentation in the China E-Bike Market reveals how procurement priorities diverge between fleet operators and individual consumers. MIIT certification requirements and municipal registration rules create distinct compliance thresholds that reshape demand patterns across product configurations and battery technologies.
Product Type:
Urban density and trip distance separate buyers into performance tiers ranging from compact storage solutions to high-torque cargo haulers.
- Commuter E-Bikes:Standard 250W-400W pedal-assist frames dominate daily transport for salary workers across Shanghai and Beijing metropolitan corridors. Municipal license plate restrictions in Hangzhou and Shenzhen channel procurement toward GB 17761-certified OEM supply, consolidating volume around standardized mid-tier configurations.
- Foldable E-Bikes:Collapsible frame designs with quick-release mechanisms address multi-modal transit integration for subway commuters in tier-one cities. Zhejiang manufacturing clusters specialize in hinge engineering and compact battery integration, though higher unit costs limit penetration outside premium urban districts.
- Mountain E-Bikes:Reinforced suspension systems and elevated torque ratings serve off-road enthusiasts in western provincial recreation zones.
- Cruiser E-Bikes:Step-through frames with relaxed geometry target leisure riders in coastal retirement communities.
Volume sits with Commuter E-Bikes; growth tilts toward Foldable E-Bikes.
End User:
Utilization intensity and range requirements fragment the customer base across platform economy infrastructure and discretionary purchase cycles.
- Delivery Services:High-rotation fleet operators in Shanghai and Beijing prioritize swap-station compatibility and extended range lithium-ion configurations. Platform economy expansion accelerates procurement of standardized models with modular battery architecture, while municipal subsidy programs for charging infrastructure reduce total cost of ownership.
- Urban Riders:Daily commuters in tier-two and tier-three cities select cost-optimized lead-acid replacements or entry-level lithium-ion variants. Aima Technology's distributor density in these markets captures recurring replacement demand as GB standards phase out non-compliant legacy units.
- Off-Road Enthusiasts:Specialized suspension and torque specifications attract recreational buyers in Yunnan and Sichuan mountain regions.
- Recreational Users:Weekend leisure riders in eastern coastal provinces drive seasonal demand for cruiser and comfort-oriented frame designs.
Delivery Services command the steepest expansion trajectory; Urban Riders anchor absolute volume.
Battery Type:
Chemistry selection determines compliance eligibility, weight trade-offs, and lifecycle economics under tightening GB technical specifications.
- Lithium-Ion:Higher energy density configurations dominate new registrations in Hangzhou, Shenzhen, and Beijing where municipal authorities restrict lead-acid license plate issuance. MIIT safety certification mandates redirect procurement from refurbished imports toward standardized OEM supply, compressing price premiums against legacy alternatives.
- Lead-Acid:Heavier, lower-cost chemistry persists in rural county markets and replacement cycles where registration enforcement remains uneven. Central and western provinces maintain residual demand as price-sensitive buyers delay lithium-ion conversion.
- Lithium Polymer:Flexible form factors enable frame-integrated pack designs for premium foldable and compact urban models.
- Nickel-Cadmium:Legacy chemistry with limited new production, primarily serving aftermarket replacement for aging fleet units in peripheral municipalities.
Lithium-Ion captures regulatory tailwinds; Lead-Acid retains residual rural volume.
Distribution Channel:
Touchpoint selection reflects buyer sophistication, service requirements, and fleet procurement scale.
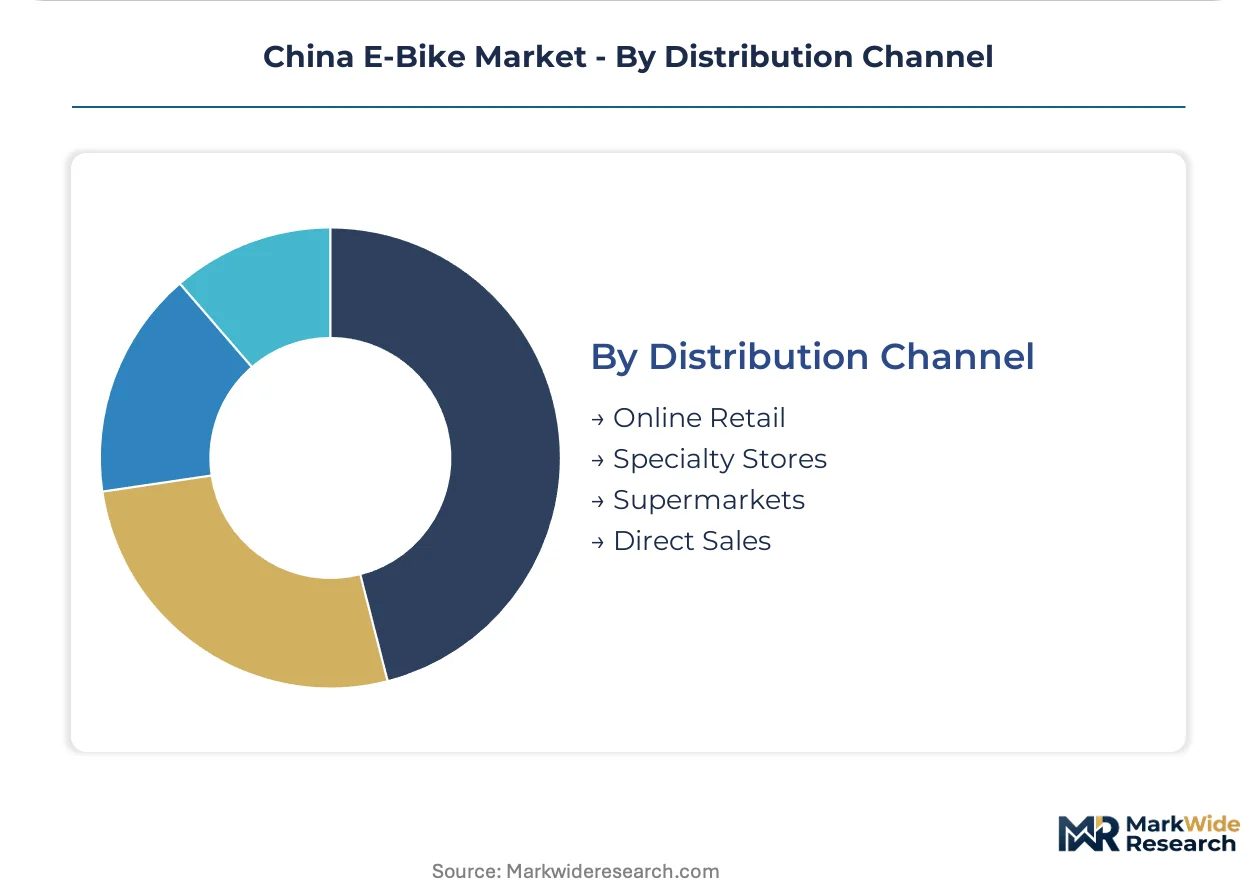
- Specialty Stores:Authorized dealer networks provide GB certification documentation essential for municipal license plate issuance in Hangzhou and Shenzhen. Yadea Group and Aima Technology anchor market position through dense distributor coverage in tier-two and tier-three cities, capturing replacement demand and warranty service attachment.
- Direct Sales:OEM-owned channels and platform economy fleet procurement departments negotiate volume contracts with documentation audit requirements. Delivery service operators in Beijing and Shanghai mandate MIIT certification verification before standardized fleet orders.
- Online Retail:E-commerce platforms serve price-sensitive individual buyers in regions with established logistics infrastructure.
- Supermarkets:Mass retail penetration remains limited to entry-level lead-acid models in rural county markets.
Specialty Stores hold volume concentration; Direct Sales expand fastest among fleet accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate processing capacity in Qinghai and Sichuan provinces anchors the upstream battery material supply chain for electric two-wheeler manufacturing clusters.
Shanghai
Platform economy fleet operators command procurement volumes exceeding 200,000 units annually. MIIT certification audits now precede all municipal license plate issuances. Pudong and Minhang districts concentrate swap-station infrastructure deployment density.
Beijing
Delivery service riders generate replacement demand cycles compressed to 18-24 months. SAMR market surveillance blocks non-compliant imports from aftermarket circulation. Daxing and Tongzhou logistics corridors host centralized fleet maintenance facilities.
Zhejiang Province
Hangzhou municipal authorities restrict lead-acid battery registrations from central district license plate pools. GB 17761 technical specifications govern all new vehicle certifications. Jinhua and Yongkang manufacturing clusters specialize in compact foldable frame engineering.
Jiangsu Province
Wuxi and Changzhou industrial zones assemble battery packs for export-oriented OEM supply chains. Local traffic bureaus coordinate with SAMR to enforce documentation verification. Suzhou and Nantong port facilities handle lithium-ion cell import logistics.
Guangdong Province
Shenzhen's municipal subsidy programs support charging infrastructure density targets. Dual carbon policy alignment accelerates electrification incentives across urban mobility networks. Dongguan and Foshan component suppliers feed Pearl River Delta assembly operations.
China E-Bike Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue connected-vehicle software specialization. The vendor base distributes across three performance tiers: premium lithium-ion specialists, mid-volume commuter assemblers, and cost-optimized rural market suppliers. Strategic archetypes include captive cell sourcers, dense distributor network operators, and swap-station-compatible platform providers. Dominant competitive moves center on backward integration into battery pack assembly and municipal fleet procurement contract capture.
Among Zhejiang-based fabricators, Luyuan and Zhejiang JSL Vehicle Co., Ltd. exemplify the manufacturing cluster archetype. Yadea Group, Aima Technology, and Sunra Electric Vehicle represent contrasting strategic positions across the tier spectrum. These entities anchor competitive dynamics through divergent channel strategies and geographic coverage patterns.
| Leading Market Players |
|---|
| Luyuan |
| XDS Cycle |
| Yadea Group |
| FTN Electric Bike |
| Lima Vehicle |
| Aima Technology |
| Sunra Electric Vehicle |
| Ninebot |
| Zhejiang JSL Vehicle Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Delivery fleet procurement departments in Beijing and Shanghai are mandating swap-station-compatible lithium-ion configurations with full GB 17761 documentation, forcing pack assemblers to absorb certification costs and compress lead-acid replacement margins across rural distributor networks.
Pricing Analysis
Warranty bundling separates premium OEM supply from unbundled aftermarket alternatives in municipal procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects GB certification grade and swap-station compatibility rather than raw battery chemistry alone. Pricing pressure stems from lithium carbonate spot volatility squeezing pack assembler margins. Delivery fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations; rural county buyers in central provinces remain most price-responsive.
Supply Chain Analysis
Regional distribution centers in Hangzhou and Shenzhen operate hub-and-spoke patterns feeding specialty store networks across eastern coastal provinces. Battery cell production concentrates in China, South Korea, and Japan with cathode material processing anchored in Qinghai and Sichuan. Lithium carbonate, nickel sulfate, and electrolyte formulations constitute critical input dependencies. Single-source vulnerability to Zhejiang-Jiangsu logistics corridors creates geographic concentration risk. Distribution runs through authorized dealer networks requiring MIIT certification documentation for license plate issuance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB 17761 certification mandates are eliminating non-compliant refurbished imports, compressing the vendor base and rewarding standardized OEM supply with documented compliance trails.
For Market Incumbents: Deploy captive cell sourcing to secure margin control as lithium raw material volatility intensifies. Deepen distributor network density in tier-three cities to capture replacement cycles as lead-acid phase-out accelerates. Yadea Group's vertical integration model demonstrates how backward integration into battery pack assembly defends against emerging connected-vehicle software specialists. For New Entrants and Emerging Players: MIIT battery safety certification in China opens a window for swap-station-compatible platform providers to capture delivery fleet procurement contracts. Target rural county markets in central and western provinces where lithium-ion penetration remains underdeveloped. Pursue battery-as-a-service subscription models to bypass upfront ownership barriers among high-utilization platform economy riders. For Investors and Strategic Acquirers: The window for entry favors mid-volume commuter assemblers with established GB 17761 certification pipelines and dense distributor footprints in tier-two cities. Long-term viability hinges on producer responsibility readiness for pending battery recycling mandates. Monitor municipal subsidy taper schedules as the inflection signal for production mix calibration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Yadea Group's captive cell sourcing sustains margin control against raw material volatility. |
| Swap-Station Infrastructure Partnership | Platform economy fleet operators in Shanghai prioritize compatibility with dense charging networks. |
| GB 17761 Certification Investment | MIIT mandates eliminate non-compliant refurbished imports from aftermarket circulation channels. |
| Rural County Market Penetration | Central and western provinces retain residual lead-acid demand awaiting lithium-ion conversion. |
| Battery-as-a-Service Platform Launch | Subscription models displace outright ownership among high-utilization delivery riders in Shenzhen. |
Research Approach
MIIT regulatory filings, SAMR market surveillance reports, and municipal traffic bureau registration databases formed the secondary backbone. Primary interviews with battery pack assembly plant managers, OEM procurement leads at Yadea Group and Aima Technology, specialty store distributors in Zhejiang province, and platform economy fleet operators in Shanghai validated demand assumptions. Bottom-up and top-down triangulation reconciled production volume estimates with end-user procurement patterns.
Bottom-up modeling aggregated segment-level volume and value trajectories across the projection horizon. Segmentation dimensions included product type, battery chemistry, end-user utilization intensity, and distribution channel structure. CAGRs derived from historical growth pattern analysis adjusted for regulatory inflection points. Forecast inputs incorporated lithium carbonate price elasticity and municipal subsidy taper schedules.
The model assumes a particular technology adoption path; alternative pathways for solid-state electrolyte commercialization would alter the outlook for swap-station deployment density. Forecasts reflect documented assumptions about GB standard revision timelines and MIIT enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Motorcycle Fairings Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Kids Bicycle Market
Bikes and Motorcycles
Global Hybrid Bicycles Market
Bikes and Motorcycles
Bike Fenders Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Bike Taxi Market