
 Aboveground Fuel Storage Market | 2026-2036
Aboveground Fuel Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Aboveground Fuel Storage Market Analysis
Modular fabrication and field-erected construction methods is fragmenting traditional aboveground tank manufacturing into distributed supply chains. Highland Tanks leverages its Pennsylvania-based fabrication network to anchor regional delivery timelines for UL-certified steel tanks. Toyo Kanetsu competes through advanced seismic design capabilities that dominate Japan's earthquake-prone industrial zones. Polymaster specializes in rotationally molded polyethylene containment systems that extend corrosion resistance into marine and coastal applications.
Aboveground fuel storage denotes stationary vessels designed for atmospheric or low-pressure containment of petroleum products, chemicals, or alternative fuels, typically constructed from welded carbon steel plate meeting API 650 or UL 142 thickness standards with secondary containment integration. These systems serve critical functions in bulk fuel terminals, emergency power generation, fleet refueling, and industrial process heat supply where leak detection and spill prevention override burial cost savings. Steel tanks retain the largest installed base across commercial and government end users due to structural familiarity and established API certification pathways, while fiberglass-reinforced polymer segments represent the fastest-growing material category where sulfur-laden biofuels and saline environments accelerate metal degradation. UL-certified product lines command premium positioning in North American municipal procurement, whereas NFPA 30 compliance shapes fire-code-driven replacement cycles in densely populated industrial districts.
EPA's 40 CFR 112 Spill Prevention, Control, and Countermeasure rules mandate secondary containment and periodic integrity testing for non-transportation bulk oil storage, directly expanding demand for double-wall and diked configurations across commercial and industrial installations. API 653 inspection standards and NFPA 30 flammable liquids codes create recurring compliance-driven replacement revenue as aging single-wall tanks reach mandatory retirement thresholds. Stakeholders must monitor evolving state-level PFAS contamination liability frameworks and biofuel blend compatibility specifications that will determine next-generation material selection and retrofit investment priorities.
Market Dynamics
EPA's 40 CFR 112 secondary containment mandates are forcing wholesale replacement of aging single-wall infrastructure, while double-wall steel and fiberglass-reinforced polymer systems capture procurement preference in coastal corrosion zones and biofuel handling facilities.
Growth Catalysts
- 40 CFR 112 SPCC enforcement:EPA inspection protocols and penalty structures accelerate retirement timelines for non-compliant bulk storage, expanding replacement demand across commercial terminals and industrial campuses.
- Biofuel blend penetration:Sulfur-laden ethanol and biodiesel storage requirements degrade conventional carbon steel, driving specification shifts toward corrosion-resistant fiberglass and coated double-wall configurations.
- Gulf Coast petrochemical expansion:Capacity additions along the Texas-Louisiana corridor generate concentrated demand for UL-certified atmospheric tanks with integrated leak detection systems.
Market Restraints
- Steel plate input volatility:Welded carbon steel fabrication depends on hot-rolled coil pricing subject to tariff and energy cost fluctuations, compressing fabricator margins on fixed-price municipal contracts.
- Skilled welder scarcity:API 650 and ASME Section IX-certified welding labor pools concentrate in legacy manufacturing regions, constraining field-erected tank construction timelines.
- Concrete secondary containment cost:Diked concrete impoundment construction adds 35-50% to installed system costs versus standalone double-wall vessels, limiting adoption in cost-sensitive agricultural and fleet applications.
Strategic Opportunities
- Modular fabrication networks:Distributed regional manufacturing cells reduce freight costs and delivery windows for standardized UL 142 shop-built tanks, penetrating municipal and commercial markets beyond traditional fabricator territories.
- Seismic zone specification:Japan's METI building codes and California's seismic design requirements create premium positioning for flexible-base anchoring systems and sloshing suppression technology in earthquake-prone industrial corridors.
- Marine coastal corrosion resistance:Rotationally molded polyethylene containment systems address salt-air degradation in port fueling and offshore backup power applications where steel requires continuous recoating.
Industry Challenges
- API 653 inspector certification backlog:Mandatory integrity assessment schedules outpace qualified inspector availability, delaying tank recertification and forcing operational downtime at bulk terminals.
- Legacy single-wall retrofit complexity:Existing concrete diked installations require extensive civil modification to accommodate modern double-wall vessels, extending project timelines and site disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aboveground Fuel Storage Market |
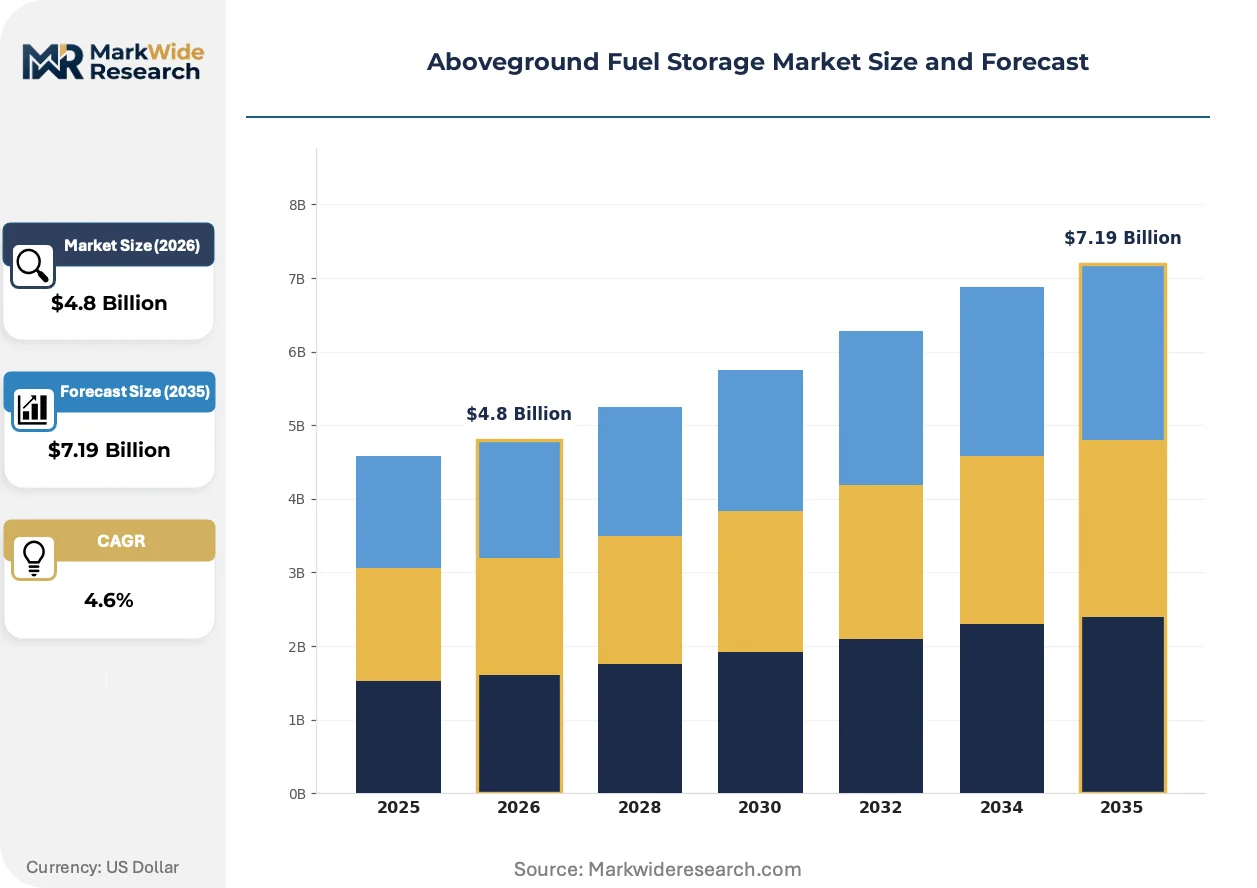
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Tank, Sump, Vault, Container Material: Steel, Plastic, Fiberglass, Aluminum End User: Commercial, Industrial, Residential, Government Certification: UL, API, NFPA, ISO |
| Companies Covered | Shijiazhuang Enric Gas Equipment Co Ltd, Motherwell Bridge, ISHI Iron Works, Polymaster, Fox Tank, MEKRO, PermianLide, Highland Tanks, Toyo Kanetsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aboveground Fuel Storage Market Emerging Trajectories
Material science advances and digital monitoring integration are redefining containment system specifications, with corrosion-resistant polymers and real-time leak detection reshaping procurement criteria across regulated industrial sectors.
Hybrid composite tank construction is hybridizing fiberglass-reinforced polymer inner shells with steel outer containment, delivering chemical resistance against aggressive biofuels while maintaining structural familiarity for inspectors and fire marshals. Power generation facilities and marine terminals are specifying these configurations for sulfur-laden ethanol storage where pure steel suffers accelerated pitting. The technology is hybridizing traditional material categories, forcing fabricators to develop dual-certification capabilities across API 650 and RTP-1 standards.
EPA's 40 CFR 112 integrity testing mandates now require periodic containment assessments using hydrostatic or alternative methods, compelling tank owners to budget for inspection access infrastructure and documentation systems. The regulation compresses operational planning horizons and elevates total cost-of-ownership calculations in procurement decisions. Bulk terminals along the US Gulf Coast are responding by pre-positioning portable containment and vacuum recovery equipment to minimize inspection-related downtime.
Specification authority is migrating from facilities engineering departments to environmental compliance officers, with secondary containment performance and leak detection sensitivity outweighing capital cost in vendor selection. Engineering-procurement-construction firms and industrial end-users are unbundling tank supply from installation and commissioning services, creating discrete contracting opportunities for specialized containment contractors. This shift concentrates most visibly in California and Northeastern states where state-level PFAS liability frameworks amplify spill prevention investment priorities.
Aboveground Fuel Storage Market Segmentation
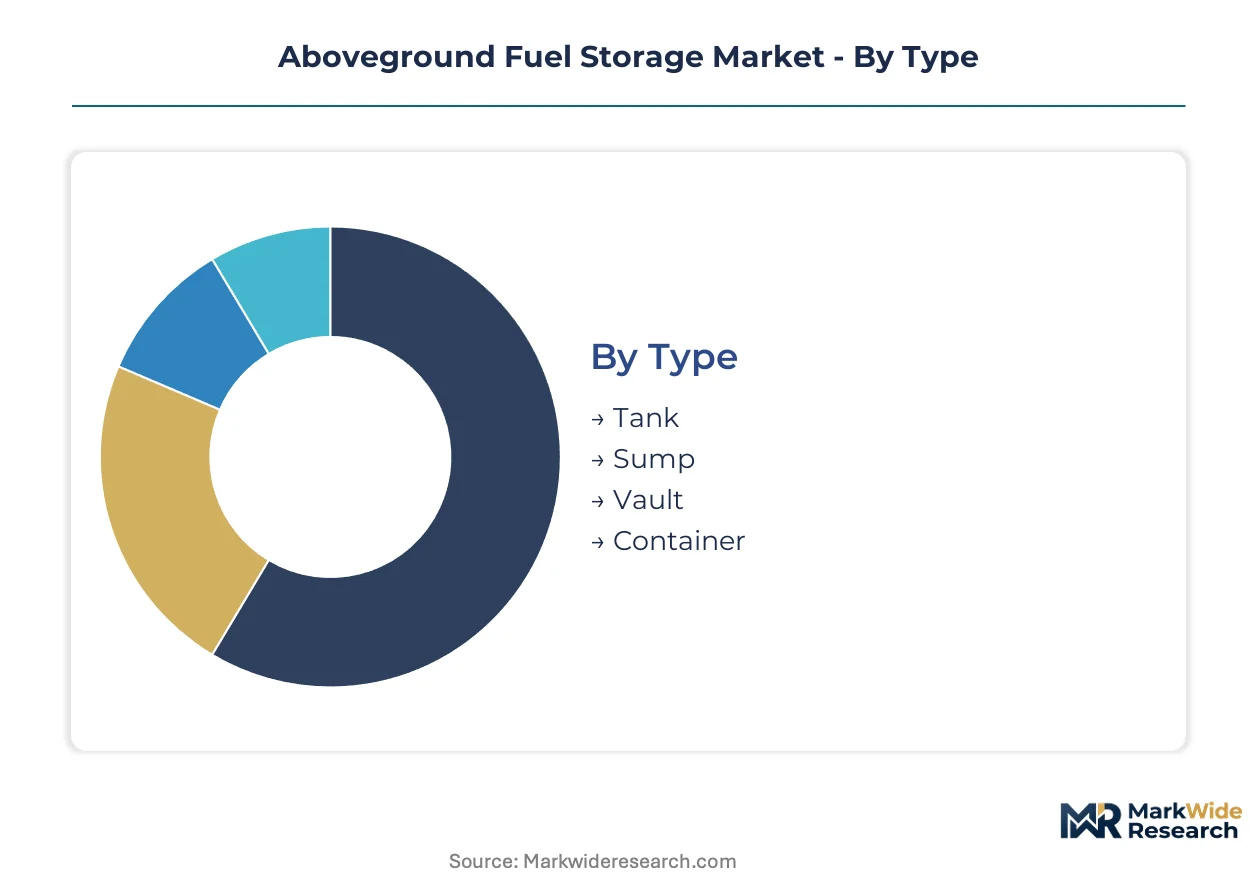
Aboveground fuel storage procurement varies sharply by replacement cycle and compliance pressure. Tank configurations face mandatory retirement under EPA inspection schedules, while certification tiers determine which segments command premium pricing versus commodity substitution.
Type:
Tank systems turn over slowest due to capital intensity and civil infrastructure lock-in. Containers and vaults cycle faster as modular units respond to fleet mobility and temporary power needs.
- Tank:Stationary welded vessels meeting API 650 or UL 142 plate thickness standards with integrated secondary containment. Demand concentrates along the US Gulf Coast petrochemical corridor where bulk terminals require atmospheric storage with leak detection systems for SPCC compliance.
- Sump:Subsurface collection reservoirs designed for spill containment and groundwater protection at fueling points. California and Northeastern states drive specification shifts as state-level PFAS liability frameworks amplify investment in below-grade containment.
- Vault:Buried or semi-buried concrete enclosures housing tanks in space-constrained urban environments. Municipal transit depots in dense industrial districts specify these for fire-code compliance under NFPA 30 restrictions.
- Container:Portable rectangular vessels for temporary fuel supply at construction sites and emergency power operations. Modular fabrication networks are penetrating commercial markets with standardized UL 142 shop-built units.
Tank dominates installed base. Container is where expansion concentrates.
Material:
Cost tiers separate structural steel from corrosion-resistant alternatives. Premium polymers and fiberglass command 40-60% price premiums over carbon steel but deliver lower lifecycle costs in aggressive chemical environments.
- Steel:Welded carbon steel plate construction retains the largest commercial and government installed base due to structural familiarity and established API certification pathways. Hot-rolled coil price volatility compresses fabricator margins on fixed-price municipal contracts.
- Plastic:Rotationally molded polyethylene systems deliver salt-air degradation resistance in port fueling and offshore backup power applications. Polymaster anchors this segment through marine coastal specialization.
- Fiberglass:Fiberglass-reinforced polymer segments expand most quickly where sulfur-laden biofuels and saline environments accelerate metal degradation. Hybrid composite construction is hybridizing fiberglass inner shells with steel outer containment for dual-certification capabilities.
- Aluminum:Lightweight alloy construction for aviation fueling and weight-sensitive transport applications. Premium positioning reflects material cost and specialized welding requirements.
Steel dominates installed base. Fiberglass is where expansion concentrates.
End User:
Customer type determines specification authority and procurement complexity. Government and industrial buyers centralize environmental compliance oversight, while commercial and residential segments prioritize capital cost minimization.
- Commercial:Fleet refueling operations and retail fueling stations balancing SPCC compliance against throughput economics. Diked concrete impoundment construction adds 35-50% to installed costs versus standalone double-wall vessels.
- Industrial:Bulk fuel terminals, process heat supply, and manufacturing facilities where leak detection overrides burial cost savings. Specification authority is migrating from facilities engineering to environmental compliance officers.
- Residential:Home heating oil storage in rural and suburban markets with limited regulatory oversight. Price sensitivity limits adoption of premium double-wall configurations.
- Government:Military installations, municipal emergency power, and federal facilities with mandated UL certification and documented integrity testing. Procurement concentrates in Pennsylvania-based fabrication networks for regional delivery timelines.
Industrial dominates installed base. Government is where expansion concentrates.
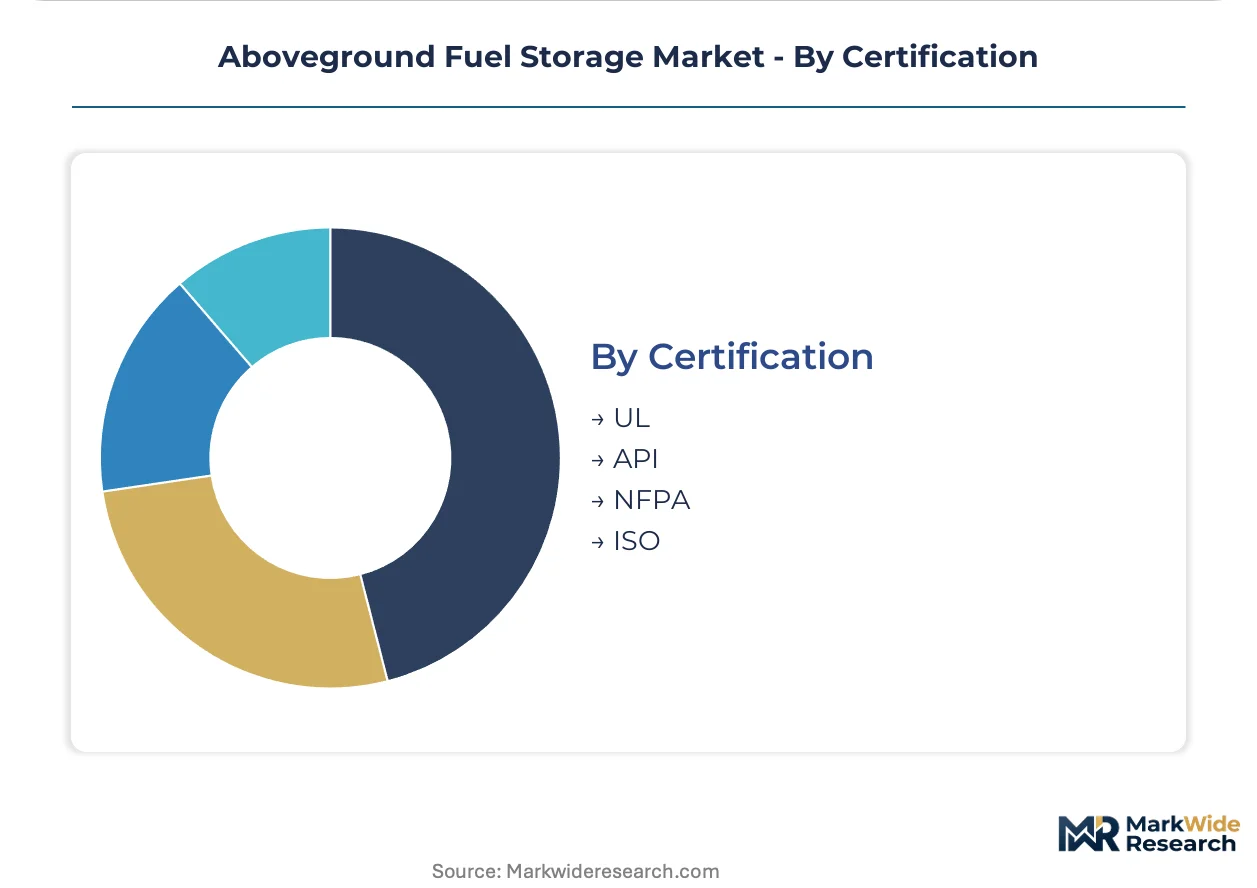
Certification:
Maturity levels separate legacy API pathways from emerging international standards. NFPA and UL certifications carry enforcement weight in North American procurement, while ISO gains traction in multinational industrial accounts.
- UL:Underwriters Laboratories certification commands premium positioning in North American municipal procurement with standardized shop-built tank specifications. Highland Tanks leverages UL-certified steel tank lines to anchor regional delivery.
- API:American Petroleum Institute standards govern field-erected atmospheric tank construction with mandatory inspector certification under API 653. Inspector availability backlog delays recertification and forces operational downtime.
- NFPA:National Fire Protection Association codes shape flammable liquids storage requirements in densely populated industrial districts. California and Northeastern states amplify NFPA 30-driven replacement cycles.
- ISO:International Organization for Standardization frameworks address multinational industrial accounts with harmonized quality management. Adoption remains limited in domestic procurement dominated by US-specific regulatory compliance.
API dominates installed base. UL is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Gulf Coast fabricators export double-wall containment systems to Caribbean petrochemical terminals and Latin American bulk fuel operations, with EPA-certified steel tanks commanding premium positioning in cross-border procurement.
United States
Texas and Louisiana petrochemical corridors drive concentrated demand for UL-certified atmospheric tanks with integrated leak detection. EPA's 40 CFR 112 SPCC enforcement accelerates retirement of aging single-wall infrastructure across commercial terminals. Houston-area fabricators anchor regional delivery networks for municipal and industrial buyers throughout the Gulf South.
Japan
Earthquake-prone industrial zones in Kanto and Chubu regions specify flexible-base anchoring systems for seismic resilience. METI building codes mandate sloshing suppression technology in bulk fuel installations. Osaka-based engineering groups dominate specification authority for coastal power generation and marine terminal applications.
Germany
Rhine-Ruhr industrial clusters and Bavarian chemical parks prioritize corrosion-resistant fiberglass systems for biofuel blend storage. REACH compliance frameworks shape material selection for sulfur-laden ethanol handling. Stuttgart-area fabricators supply double-wall configurations to automotive manufacturing campuses and emergency power facilities.
China
Yangtze River Delta petrochemical complexes and Pearl River Delta port operations expand atmospheric tank capacity for refined product storage. GB standards and MIIT industrial safety codes tighten secondary containment requirements. Shanghai-based fabricators serve coastal refinery clusters with field-erected steel vessels.
Australia
Queensland mining corridors and Western Australian offshore operations specify rotationally molded polyethylene containment for salt-air degradation resistance. National environmental protection frameworks extend spill prevention liability to fuel storage operators. Perth-based specialists anchor marine coastal applications for port fueling and remote backup power.
Aboveground Fuel Storage Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented fabrication networks. Consolidated procurement by Gulf Coast petrochemical operators and Japanese power utilities concentrates volume with established API-certified fabricators, while municipal and commercial segments fragment across regional shop-built tank suppliers. Three archetypes dominate: seismic-design specialists serving earthquake-prone zones, corrosion-resistant polymer fabricators targeting marine environments, and modular steel tank producers leveraging distributed manufacturing cells. Competitive moves center on backward integration into steel plate supply and technology licensing for hybrid composite construction.
Among Asia-Pacific fabricators, Toyo Kanetsu and ISHI Iron Works exemplify seismic-design specialization for earthquake-prone industrial corridors. Highland Tanks anchors North American positioning through Pennsylvania-based fabrication networks serving UL-certified municipal procurement. Polymaster occupies the corrosion-resistant tier with rotationally molded polyethylene systems for marine and coastal applications.
| Leading Market Players |
|---|
| Shijiazhuang Enric Gas Equipment Co Ltd |
| Motherwell Bridge |
| ISHI Iron Works |
| Polymaster |
| Fox Tank |
| MEKRO |
| PermianLide |
| Highland Tanks |
| Toyo Kanetsu |
| Others |
Supply Flow & Price Mechanics
US Gulf Coast barge and rail corridors carry hot-rolled steel coil from Pittsburgh-area mills to Houston and Beaumont fabrication yards, with freight cost volatility compressing margins on fixed-price municipal contracts while enabling price premiums for regional delivery guarantees. This logistics architecture concentrates supply-side pricing power among Pennsylvania-based UL-certified fabricators serving emergency power and government procurement, while coastal corrosion zones absorb 40-60% material premiums for fiberglass-reinforced polymer alternatives.
Pricing Analysis
Single-wall carbon steel tanks, double-wall steel configurations, and hybrid fiberglass-steel composite systems stratify across three performance tiers with pricing spreads driven by certification grade and corrosion resistance specifications. UL 142 shop-built tanks command 15-25% premiums over non-certified equivalents in North American municipal procurement, while API 650 field-erected vessels price on project scale and seismic design complexity. Price erosion runs through standard carbon steel segments as Chinese mill capacity and tariff uncertainty destabilize hot-rolled coil input costs. Commercial fleet operators exhibit highest price sensitivity, prioritizing capital cost minimization over lifecycle containment performance, whereas Gulf Coast petrochemical terminals accept premium positioning for integrated leak detection and documented integrity testing.
Supply Chain Analysis
API-certified tank fabrication concentrates in the United States, Japan, and Germany, with regional specialists anchoring seismic design, corrosion-resistant polymer, and modular steel production respectively. Welded carbon steel construction draws from domestic hot-rolled coil supply chains, fiberglass-reinforced polymer systems rest on resin and glass fiber feedstocks, and rotationally molded polyethylene sources specialized resin grades for marine salt-air resistance. Single-source vulnerability clusters around API 653 inspector certification pools, where qualified assessor scarcity delays recertification schedules and forces operational downtime. Distribution runs through engineering-procurement-construction firms unbundling tank supply from installation services, with specialized containment contractors capturing commissioning and leak detection integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aboveground fuel storage sits in early-cycle expansion as EPA 40 CFR 112 enforcement accelerates replacement demand for non-compliant single-wall infrastructure across commercial and industrial installations. Double-wall containment adoption penetrates bulk terminals and power generation facilities where spill prevention liability overrides capital cost minimization.
For Market Incumbents: Build inspector certification capacity as a defensive moat against API 653 assessor scarcity that delays competitor recertification timelines. Backward integration into steel plate supply hedges hot-rolled coil price volatility compressing margins on fixed-price municipal contracts. Expand distributed modular fabrication networks to compress delivery windows for standardized UL 142 shop-built tanks penetrating commercial markets beyond traditional territories. For New Entrants and Emerging Players: Pursue corrosion-resistant polymer specialization targeting marine coastal applications where salt-air degradation accelerates steel recoating cycles and rotationally molded polyethylene commands lifecycle cost advantages. Target Australian mining corridors and Caribbean petrochemical terminals as underpenetrated geographies with concentrated demand for salt-air resistant containment. Anchor go-to-market strategy through engineering-procurement-construction firm partnerships unbundling tank supply from installation services. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core tank fabrication divisions lacking UL certification pathways or seismic design capabilities. Five-to-ten year viability hinges on compliance-driven replacement cycles and biofuel blend compatibility specifications reshaping material selection. Watch state-level PFAS contamination liability frameworks as inflection indicators amplifying secondary containment investment priorities in California and Northeastern states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Plate Supply | Captive hot-rolled coil sourcing stabilizes input costs against tariff volatility for municipal contract margins. |
| Hybrid Composite Certification Investment | Dual API 650 and RTP-1 capabilities capture sulfur-laden biofuel storage specifications displacing pure steel. |
| Modular Fabrication Network Expansion | Distributed regional cells compress freight costs and delivery windows for standardized UL 142 shop-built tanks. |
| API 653 Inspector Training Programs | Certified assessor pipelines address mandatory integrity testing backlogs forcing operational downtime. |
| Marine Coastal Polymer Specialization | Rotationally molded polyethylene systems target port fueling applications where steel requires continuous recoating. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with tank fabricator executives, environmental compliance officers at bulk terminals, API 653 certified inspectors, and EPC procurement leads; and secondary validation through EPA 40 CFR 112 enforcement records, API certification registries, customs steel trade data, and NFPA 30 code adoption tracking. Bottom-up triangulation across fabrication capacity surveys and top-down reconciliation against petrochemical capacity expansion databases anchored volume estimates.
Forecast inputs incorporated tank replacement cycle modeling, regulatory compliance deadline schedules, and biofuel blend penetration scenarios across the projection horizon. Segmentation dimensions included tank configuration type, material category, end-user vertical, and certification tier. CAGRs derived from installed base turnover rates and mandatory retirement thresholds under EPA inspection protocols, with steel plate price elasticity and skilled welder availability as industry-specific sensitivity parameters.
Sensitivities concentrate around tariff policy shifts affecting hot-rolled coil input costs, state-level PFAS liability framework expansion, and biofuel sulfur content specifications accelerating material substitution. Quarterly review of EPA enforcement penalty structures, API 653 inspector certification pipeline output, and Gulf Coast petrochemical project development announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Compressed Natural Gas Market
Fuels
High Octane Racing Fuel Market
Fuels
No.2 Diesel Fuel Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Australia Coal Market
Fuels
China Coal Market
Fuels
Coal to Liquid Fuel (CTL) Market
Fuels
Coal Briquette Box Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
LPG Gas Cylinder Market
Fuels
India Petrol Station Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
Fuel Quality Testing Market
Fuels
Global Fuel Ethanol Market