
 Asia-Pacific Frozen Yogurt Market | 2026-2036
Asia-Pacific Frozen Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Frozen Yogurt Market Outlook
Fragmentation among cafe and food truck operators is realigning procurement patterns across the Asia-Pacific frozen yogurt landscape. Unilever leverages its cold-chain logistics network to sustain shelf presence in convenience channels. Yili Group anchors supply security through captive dairy sourcing in Inner Mongolia. Pinkberry differentiates via tart-flavor formulations that dominate premium mall locations in Seoul and Singapore.
Frozen yogurt is a fermented dairy dessert containing live bacterial cultures, typically manufactured through controlled fermentation of milk solids followed by freezing to achieve overrun levels between 20% and 40%. The product serves as a lower-fat alternative to ice cream in commercial foodservice and retail environments. Softserve formulations occupy the largest volume share due to lower capital equipment requirements for foodservice operators. Hard frozen yogurt leads margin pools in supermarkets, where extended shelf life reduces spoilage costs. Mango flavor variants are accelerating fastest in tropical markets, reflecting local palate preferences that outpace traditional vanilla and chocolate adoption.
FSSAI in India mandates live culture count disclosures on frozen yogurt packaging, shaping reformulation investments by domestic and imported brands. China's SAMR enforces GB standards for dairy dessert composition that restrict non-dairy fat substitution ratios. Japan's Food Sanitation Act, administered by the Ministry of Health, requires pathogen testing protocols that elevate compliance costs for new market entrants. Stakeholders must monitor evolving probiotic health claims regulations, as Australia and South Korea tighten substantiation requirements that could redirect marketing spend toward clinical validation or away from functional positioning entirely.
Market Dynamics
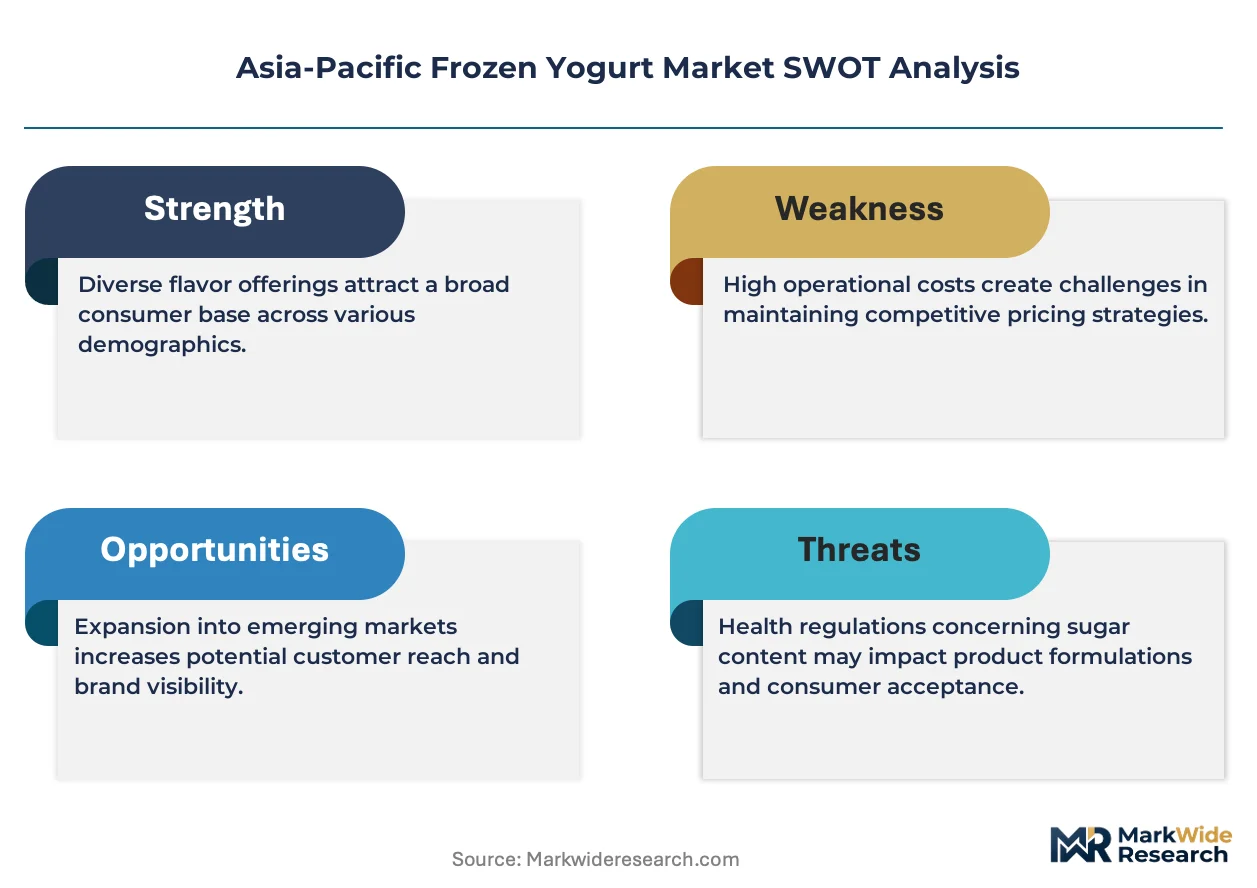
China's SAMR enforcement of GB standards for dairy dessert composition is compressing formulation flexibility for imported frozen yogurt brands, forcing supply chain reconfiguration toward domestic dairy sourcing partnerships.
Growth Catalysts
- Cloud Kitchen Proliferation:Mall-based kiosk operators in metropolitan India are expanding into delivery-only cloud kitchens, extending frozen yogurt reach beyond physical retail footprints into residential catchments.
- FSSAI Live Culture Mandates:India's packaging disclosure requirements for probiotic counts are accelerating domestic fermentation capacity investments and differentiating compliant imports from non-compliant alternatives.
- Softserve Equipment:Lower capital equipment thresholds for softserve machines are enabling food truck and small-format cafe entry across Southeast Asian urban centers.
Market Restraints
- Inner Mongolia Dairy Concentration:Yili Group's captive sourcing dominance creates supply security asymmetries for brands lacking backward integration into raw milk production.
- SAMR Substitution Limits:China's GB standards restricting non-dairy fat ratios prevent cost-engineering through plant-based fat alternatives in premium positioning segments.
- Cold-Chain Infrastructure Gaps:Temperature-controlled last-mile capabilities remain underdeveloped in tier-2 Indian cities and Indonesian archipelago markets, elevating spoilage risk for hard frozen yogurt distribution.
Strategic Opportunities
- Vietnam's Urban Middle Class:Ho Chi Minh City and Hanoi present underpenetrated demand pockets where quick-service restaurant chains have yet to saturate frozen yogurt menu placements.
- Probiotic Health Claims:Australia's tightening substantiation requirements for functional positioning create first-mover advantage for brands investing in clinical validation ahead of South Korean regulatory convergence.
- Mango Flavor Localization:Tropical palate preferences in Thailand and the Philippines favor accelerated R&D in regional fruit variants over vanilla and chocolate legacy formulations.
Industry Challenges
- Fermentation Specialist Scarcity:Food science talent capable of optimizing live culture viability through freezing cycles remains concentrated in Japan and South Korea, constraining operational scaling in emerging Southeast Asian production facilities.
- GB Standard Compliance Timelines:Imported brands face extended product registration cycles with SAMR, delaying market entry against domestically formulated competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Frozen Yogurt Market |
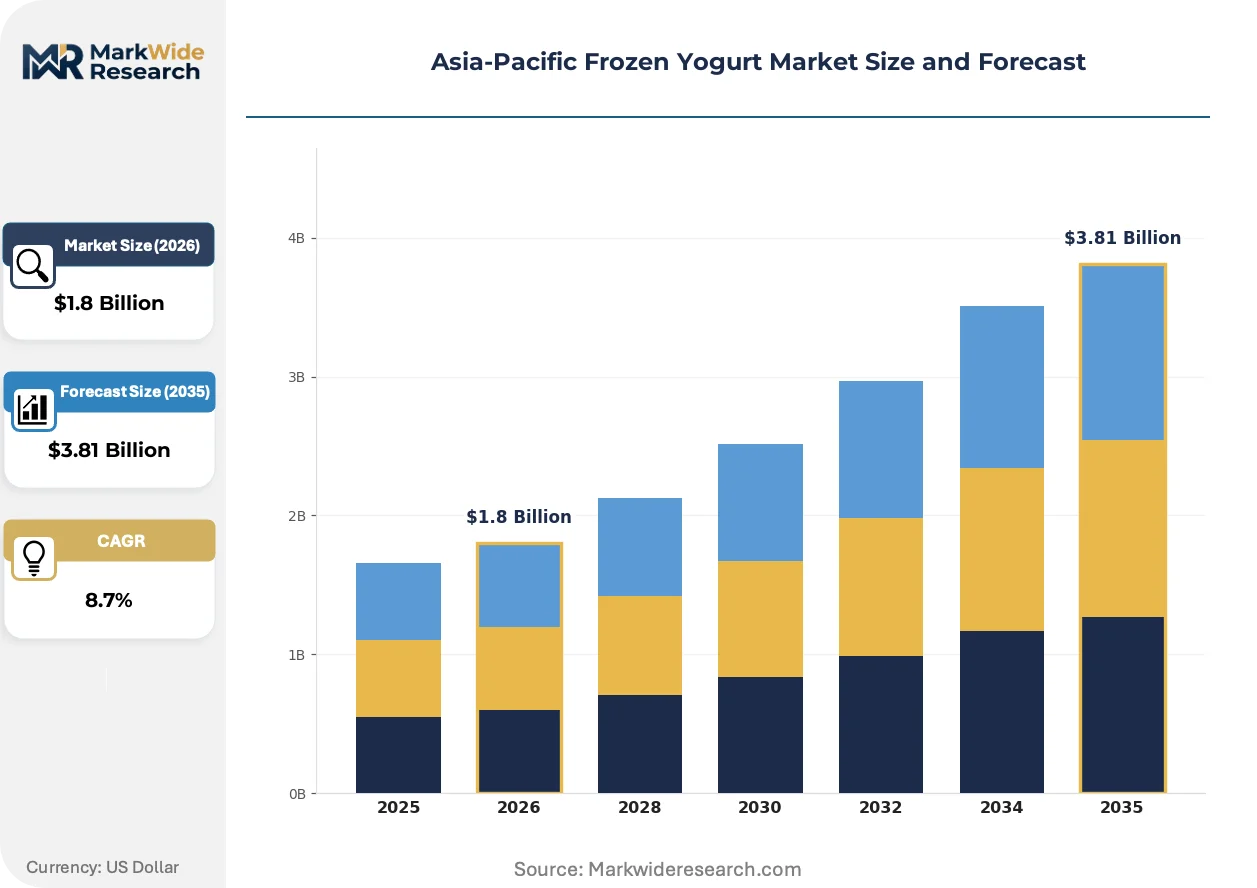
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softserve, Hard, Gelato, Sorbet End User: Restaurants, Cafes, Retail Stores, Food Trucks Flavor: Vanilla, Chocolate, Strawberry, Mango Distribution Channel: Supermarkets, Online, Convenience Stores, Specialty Shops |
| Companies Covered | Danone, Menchie's Frozen Yogurt, Unilever, Red Mango, Pinkberry, Nestlé, Yili Group, Frosty Boy, General Mills, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Frozen Yogurt Market Strategic Shifts
Active fermentation control systems and probiotic strain engineering are compressing product development cycles while regulatory divergence across Asia-Pacific jurisdictions is fragmenting formulation standardization.
Precision fermentation technology is modularizing frozen yogurt production by enabling distributed, small-batch manufacturing with consistent culture viability. Food truck operators and mall kiosk chains in Bangkok and Jakarta are adopting these systems to reduce dependence on centralized dairy processing facilities. The technology is modularizing supply chain geography, allowing brands to establish micro-factories closer to consumption clusters rather than consolidating production in single-source regions.
Japan's Food Sanitation Act pathogen testing protocols are elevating compliance costs for new market entrants without established laboratory partnerships. The regulation forces brands to either absorb extended testing timelines or pre-qualify production facilities through METI-registered third-party auditors. Premium positioning segments targeting health-conscious consumers in Tokyo and Osaka bear the highest compliance burden, redirecting marketing investment toward clinical substantiation.
Cloud kitchen aggregation platforms are compressing traditional foodservice procurement cycles for frozen yogurt operators. Quick-service brands in Bangalore and Mumbai now source base mixes through digital B2B marketplaces rather than direct distributor relationships, shifting margin capture toward platform intermediaries. This channel migration is most visible in India's National Capital Region, where delivery volume concentration justifies dedicated dark kitchen infrastructure for frozen dessert fulfillment.
Asia-Pacific Frozen Yogurt Market Segmentation
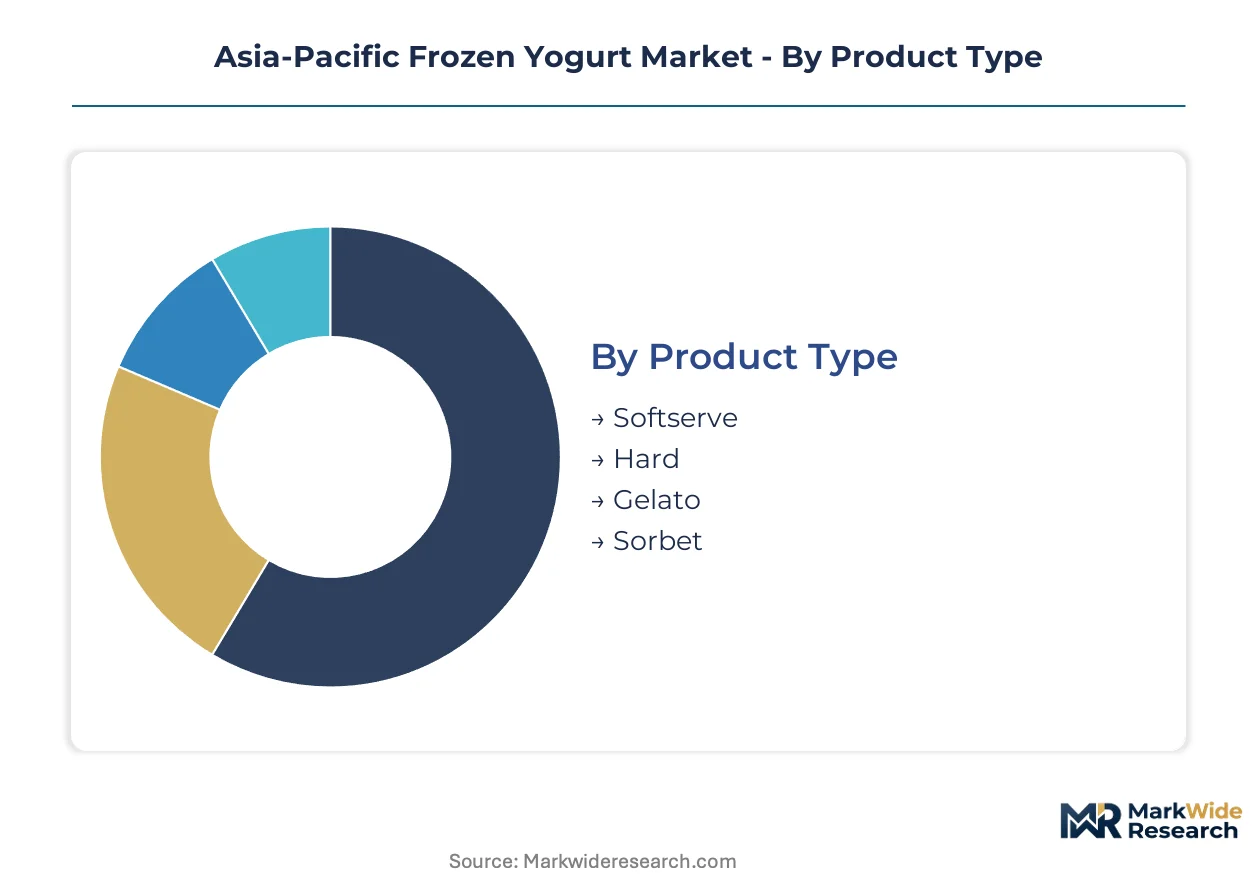
Segmentation in the Asia-Pacific frozen yogurt market reveals how formulation flexibility, channel access, and flavor localization determine competitive positioning across divergent regulatory and taste environments. Understanding these divisions exposes where capital equipment requirements, cold-chain investments, and procurement patterns concentrate margin capture.
Product Type:
Capital equipment thresholds and shelf-life requirements drive operator selection between frozen yogurt formats.
- Softserve:Manufactured through continuous freezing to achieve 20-40% overrun with immediate service temperature requirements. Demand concentrates in Bangkok and Jakarta food truck clusters where compact Taylor or Carpigiani machines enable sub-$15,000 entry costs for independent operators.
- Hard:Blast-frozen to -18°C with stabilized culture viability extending retail shelf life to 90-180 days. Supermarket distribution in Australia's Woolworths and Coles chains anchors volume, though SAMR registration delays for imported formulations constrain Chinese retail penetration.
- Gelato:Lower overrun (10-20%) and higher milk fat content distinguish Italian-style positioning in premium mall locations.
- Sorbet:Dairy-free formulations targeting lactose-intolerant segments in Japan's aging demographic profile.
Softserve leads on scale; hard frozen yogurt leads on momentum through supermarket channel expansion.
End User:
Real estate cost structures and labor intensity separate viable operating models across metropolitan catchments.
- Restaurants:Full-service integration of frozen yogurt into dessert menus, common in South Korean family dining chains where post-meal sweet consumption rates exceed regional averages. Procurement runs through centralized dairy distributors with weekly delivery schedules.
- Cafes:Self-serve formats with weight-based pricing dominate Seoul and Singapore premium mall placements, requiring higher upfront fit-out investment but generating superior per-ounce margins.
- Retail Stores:Dedicated frozen yogurt kiosks in India's Phoenix Marketcity and DLF Mall networks.
- Food Trucks:Mobile softserve units exploiting event licensing and university campus rotations in Vietnam's emerging urban centers.
Cafes lead on scale; food trucks lead on momentum through regulatory arbitrage in underpenetrated Southeast Asian cities.
Flavor:
Palate localization intensity determines R&D allocation and ingredient sourcing geography.
- Vanilla:Standard base formulation with Madagascar and Indonesian Bourbon vanilla extract supply chains. Serves as the default option in training-wheels markets where consumer education on tart profiles remains incomplete.
- Chocolate:Cocoa butter and alkalized powder formulations competing against established ice cream preferences in Australia's mature dessert market.
- Strawberry:Seasonal fresh fruit integration in Japanese convenience store formats.
- Mango:Alphonso and Kent puree sourcing from India and Thailand drives tropical market penetration. Bangkok and Manila operators report mango SKUs outselling vanilla by 3:1 ratios in summer months, redirecting procurement toward regional fruit processors.
Vanilla leads on scale; mango leads on momentum through tropical palate preference divergence.
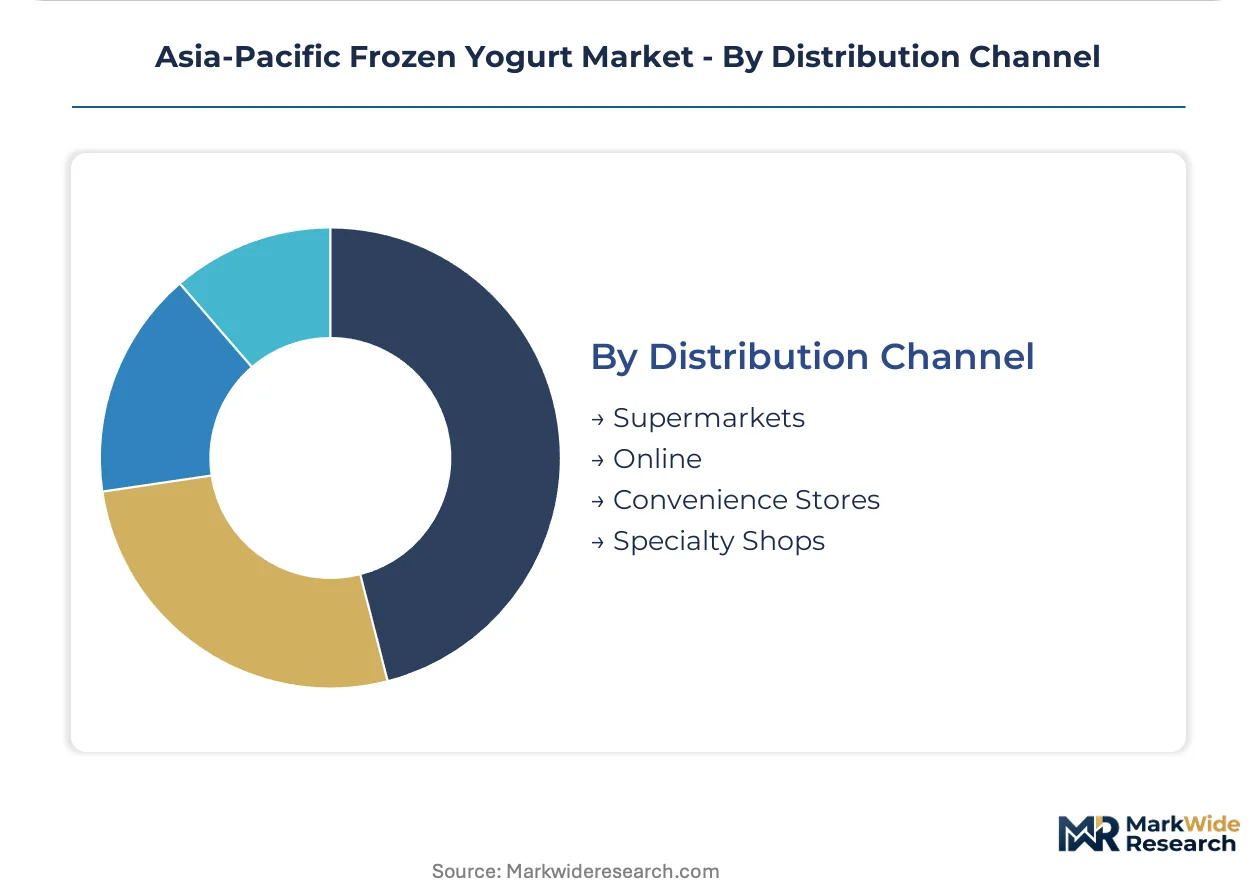
Distribution Channel:
Cold-chain reliability and last-mile temperature control separate viable from constrained pathways.
- Supermarkets:Hard frozen yogurt placement in frozen dessert aisles with 24-hour temperature logging requirements. Australia's Coles and Woolworths demand HACCP certification at distribution center level, filtering out smaller regional brands.
- Online:Dark kitchen aggregation and direct-to-consumer subscription models in India's Swiggy and Zomato ecosystems. Delivery packaging with dry ice supplementation adds 15-20% cost premium, compressing margins unless offset by volume concentration in Bangalore and Mumbai residential zones.
- Convenience Stores:7-Eleven and Lawson placements in Japan and Thailand with limited freezer door space driving SKU rationalization.
- Specialty Shops:Dedicated frozen yogurt boutiques in Seoul's Gangnam district emphasizing customization and Instagram-optimized presentation.
Supermarkets lead on scale; online leads on momentum through cloud kitchen infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's frozen yogurt market operates under stricter formulation constraints than Australia's mature retail environment, creating divergent entry pathways for international brands. SAMR enforcement of GB standards forces supply chain localization while TGA requirements in Australia emphasize HACCP certification at distribution centers.
China
Domestic dairy sourcing partnerships dominate as SAMR's GB standards restrict non-dairy fat substitution ratios in imported formulations. Registration delays with the national market regulator compress first-mover advantage for foreign brands against domestically formulated competitors. Production gravity concentrates in Inner Mongolia where Yili Group anchors captive milk supply.
India
FSSAI mandates for live culture count disclosures are accelerating domestic fermentation capacity investments across Maharashtra and Karnataka. The national food safety authority's packaging requirements differentiate compliant imports from non-compliant alternatives. Bangalore and Mumbai cloud kitchen operators now source base mixes through digital B2B marketplaces rather than direct distributor relationships.
Australia
TGA and state-level health departments enforce pathogen testing protocols that elevate compliance costs for new market entrants. Tightening substantiation requirements for probiotic health claims are redirecting marketing investment toward clinical validation. Coles and Woolworths supermarket chains anchor hard frozen yogurt volume through frozen dessert aisle placements with 24-hour temperature logging mandates.
Japan
METI-registered third-party auditors pre-qualify production facilities under Food Sanitation Act requirements administered by the Ministry of Health. Pathogen testing protocols force brands to absorb extended timelines or establish laboratory partnerships. Tokyo and Osaka premium positioning segments bear the highest compliance burden among Asia-Pacific metropolitan markets.
Vietnam
Ho Chi Minh City and Hanoi present underpenetrated demand pockets where quick-service restaurant chains have yet to saturate frozen yogurt menu placements. Regulatory arbitrage in emerging urban centers enables food truck and mobile softserve unit expansion. Event licensing and university campus rotations drive operator entry with sub-$15,000 capital equipment thresholds.
Asia-Pacific Frozen Yogurt Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base concentrates around three strategic archetypes: multinational CPG conglomerates with cold-chain logistics networks, regional dairy majors with captive sourcing advantages, and premium format specialists emphasizing tart-flavor differentiation. Dominant competitive moves include backward integration into raw milk production and geographic expansion through cloud kitchen partnerships.
Within the diversified conglomerate tier, Unilever and Nestlé exemplify scale-driven positioning through established convenience channel presence and frozen dessert portfolio breadth. Yili Group anchors the regional dairy major archetype with upstream control over Inner Mongolia milk supply. Among format specialists, Pinkberry occupies a position in premium mall placements across Seoul and Singapore through tart-flavor formulation differentiation.
| Leading Market Players |
|---|
| Danone |
| Menchie's Frozen Yogurt |
| Unilever |
| Red Mango |
| Pinkberry |
| Nestlé |
| Yili Group |
| Frosty Boy |
| General Mills |
| Others |
Value Chain & Pricing Dynamics
FSSAI live culture count mandates in India are forcing domestic fermentation capacity investments that compress margins for imported brands unable to source compliant base mixes locally. This procurement specification shift elevates cost structures for non-integrated operators while rewarding Yili Group's captive Inner Mongolia dairy supply.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for softserve equipment packages, enabling sub-$15,000 entry thresholds that intensify competition among food truck operators. Three-tier pricing structure across premium tart-flavor positioning, standard vanilla-chocolate formulations, and economy private-label tiers separates Pinkberry's mall placements from cloud kitchen commodity plays. Cost compression in economy tiers stems from digital B2B marketplace procurement bypassing traditional distributor margins. Quick-service restaurant chains exhibit lowest price sensitivity due to menu integration value, while independent food truck operators face acute margin pressure from equipment financing burdens.
Supply Chain Analysis
Single-source vulnerability sits with Inner Mongolia's concentrated dairy production where Yili Group controls captive raw milk supply. Manufacturing draws from China, Australia, and Thailand for base mix production, with flavor concentrate sourcing anchored in India for Alphonso mango puree and Madagascar for vanilla extract. Tariff exposure on imported dairy fat formulations entering China elevates landed costs against domestically compliant competitors. Distribution runs through cold-chain logistics networks with Unilever leveraging established convenience channel infrastructure to sustain shelf presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific frozen yogurt market reads as a late-cycle quality story where tart-flavor premium positioning and live culture compliance separate viable operators from commodity pressure. Palate localization toward mango variants and probiotic health claims substantiation are redirecting R&D investment toward clinically validated functional positioning.
For Market Incumbents: Anchor backward integration into regional dairy sourcing to preempt SAMR registration delays and GB standard compliance costs. Defend channel position by locking cloud kitchen aggregation partnerships in Bangalore and Mumbai before platform intermediaries capture margin. Prioritize fermentation specialist recruitment from Japan and South Korea to overcome operational scaling constraints in Southeast Asian production facilities. For New Entrants and Emerging Players: Digital B2B marketplace routes through India's Swiggy and Zomato ecosystems offer lowest-friction entry for base mix procurement without legacy distributor relationships. Vietnam's Ho Chi Minh City and Hanoi present underpenetrated demand pockets where regulatory arbitrage enables food truck expansion ahead of quick-service restaurant saturation. Target university campus rotations and event licensing in emerging urban centers with mobile softserve units exploiting sub-$15,000 equipment thresholds. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation technology providers enabling distributed micro-factory deployment closer to consumption clusters. Long-term viability over a multi-year horizon favors operators with clinical validation capabilities for probiotic health claims ahead of Australian and South Korean regulatory convergence. Monitor GB standard compliance timelines as inflection indicator for imported brand market entry velocity against domestic formulation competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Sourcing | Yili Group's Inner Mongolia captive supply secures raw milk access against SAMR substitution limits. |
| Precision Fermentation Technology Deployment | Modular micro-factories in Bangkok and Jakarta reduce dependence on centralized processing facilities. |
| Cloud Kitchen Partnership Expansion | Dark kitchen infrastructure in India's National Capital Region concentrates delivery volume for frozen dessert fulfillment. |
| Probiotic Health Claims Clinical Validation | Australia's TGA tightening substantiation requirements redirects marketing investment toward scientific evidence. |
| Mango Flavor Localization R&D | Bangkok and Manila operators report mango SKUs outselling vanilla by 3:1 ratios in summer months. |
Study Parameters
Multiple input streams — regulatory filing analysis, channel partner interviews, and production facility assessments — were reconciled to construct this Asia-Pacific frozen yogurt market analysis. Primary interviews with fermentation technology specialists, cloud kitchen operators, and dairy procurement managers at quick-service chains were cross-validated against secondary sources including FSSAI compliance databases, SAMR registration records, and cold-chain logistics provider disclosures. Bottom-up volume modeling from individual country markets was triangulated against top-down category spend estimates.
Historical consumption patterns were cross-referenced against expert panel inputs from food science professionals and retail channel buyers. Segmentation modeling across product type, end user, flavor profile, and distribution channel dimensions informed volume and value projections across the analysis window. CAGRs were derived from trend extrapolation moderated by regulatory compliance timeline adjustments and equipment penetration saturation curves specific to softserve machine deployment in Southeast Asian urban centers.
The model assumes a particular technology adoption path for precision fermentation systems; alternative pathways for active fermentation control would alter the outlook for distributed manufacturing economics. Forecasts reflect assumptions regarding SAMR enforcement consistency, FSSAI live culture mandate implementation timelines, and cold-chain infrastructure development in tier-2 Indian cities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
North America Dehydrated Food Market