
 Scandinavia Frozen Food Market | 2026-2036
Scandinavia Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
Scandinavia Frozen Food Market Intelligence
Premium clean-label tier upgrades is redrawing competitive boundaries across Scandinavia. Findus Group leverages its vertically integrated Nordic sourcing network to sustain margin advantages in frozen fish. Orkla ASA anchors its position through R&D intensity in sodium-reduced frozen prepared meals. Arla Foods competes via brand strength in dairy-integrated frozen dessert segments.
Scandinavia frozen food encompasses vegetables, meat, fish, and prepared meals preserved through blast freezing or individual quick freezing at temperatures below minus eighteen degrees Celsius, primarily serving retail and foodservice channels requiring extended shelf stability without chemical preservatives. Frozen prepared meals command the widest margin pools as health-conscious consumers accept premium positioning for allergen-controlled, portion-calibrated offerings. Frozen fish maintains volume leadership through Lerøy Seafood Group ASA's integrated aquaculture-to-retail chain, while online retail channels gain structural share as cold-chain last-mile capabilities mature in Oslo and Stockholm metropolitan zones.
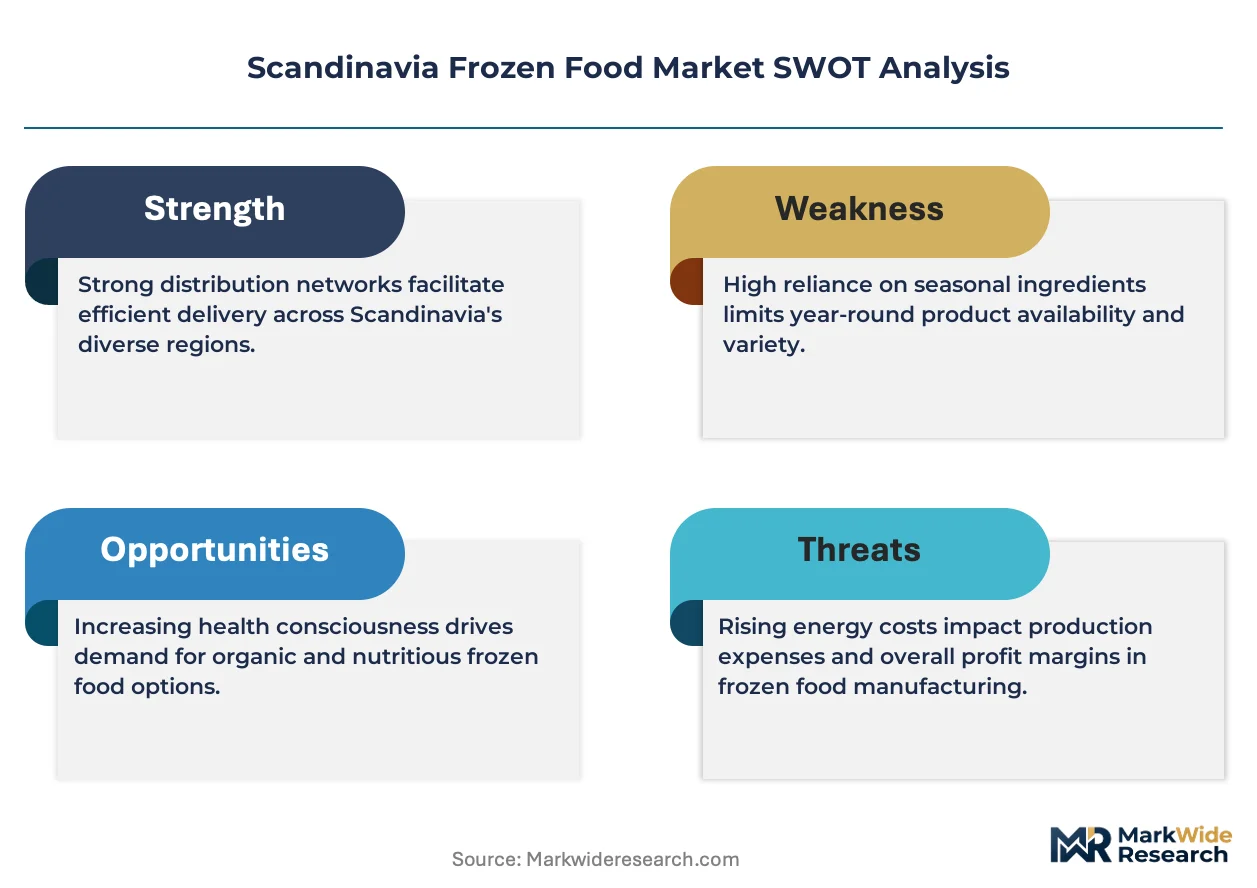
ECHA REACH compliance and the EU Green Deal packaging mandates shape product standards, forcing substitution of multilayer flexible pouches with mono-material alternatives across Danish and Swedish manufacturing facilities. Norway's national food safety authority enforces stricter cold-chain documentation than baseline EU requirements, creating asymmetric compliance costs for imported frozen meat. Stakeholders must monitor whether proposed EU-wide front-of-pack nutritional labeling expands to capture frozen prepared meals, potentially redrawing formulation priorities before the forecast horizon closes.
Market Dynamics
EU Green Deal packaging directives are forcing mono-material substitution across Danish and Swedish manufacturing, while Norway's stricter cold-chain documentation creates asymmetric compliance burdens that reshape competitive positioning in frozen prepared meals and seafood distribution.
Growth Catalysts
- Clean-label reformulation:Health-conscious consumers in Sweden and Norway accelerate demand for allergen-controlled frozen prepared meals with simplified ingredient declarations.
- ECHA REACH compliance:Chemical safety standards drive investment in preservative-free preservation technologies across regional manufacturing facilities.
- Cold-chain logistics density:Copenhagen-Aarhus corridor infrastructure supports premium frozen seafood distribution with reduced spoilage rates.
Market Restraints
- Multilayer packaging phase-out:EU Green Deal mandates force costly retooling of flexible pouch production lines before mono-material alternatives achieve cost parity.
- Imported meat documentation:Norway's national food safety authority imposes cold-chain verification requirements exceeding baseline EU standards.
- Energy-intensive blast freezing:Electricity cost volatility in Denmark and Sweden compresses margins for frozen vegetable processors.
Strategic Opportunities
- Last-mile cold-chain maturation:Oslo and Stockholm metropolitan zones enable direct-to-consumer frozen meal delivery through temperature-controlled fulfillment networks.
- Front-of-pack labeling expansion:Proposed EU-wide nutritional scoring systems create first-mover advantages for sodium-reduced formulation specialists.
- Aquaculture-to-retail integration:Norwegian coastal processing clusters support traceable frozen fish premiumization through blockchain-enabled provenance tracking.
Industry Challenges
- Refrigeration technician scarcity:Specialized cold-chain maintenance skills shortage constrains expansion of automated frozen storage facilities in Norway.
- Legacy ERP integration:Batch-level traceability requirements for EU regulations force costly upgrades to decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scandinavia Frozen Food Market |
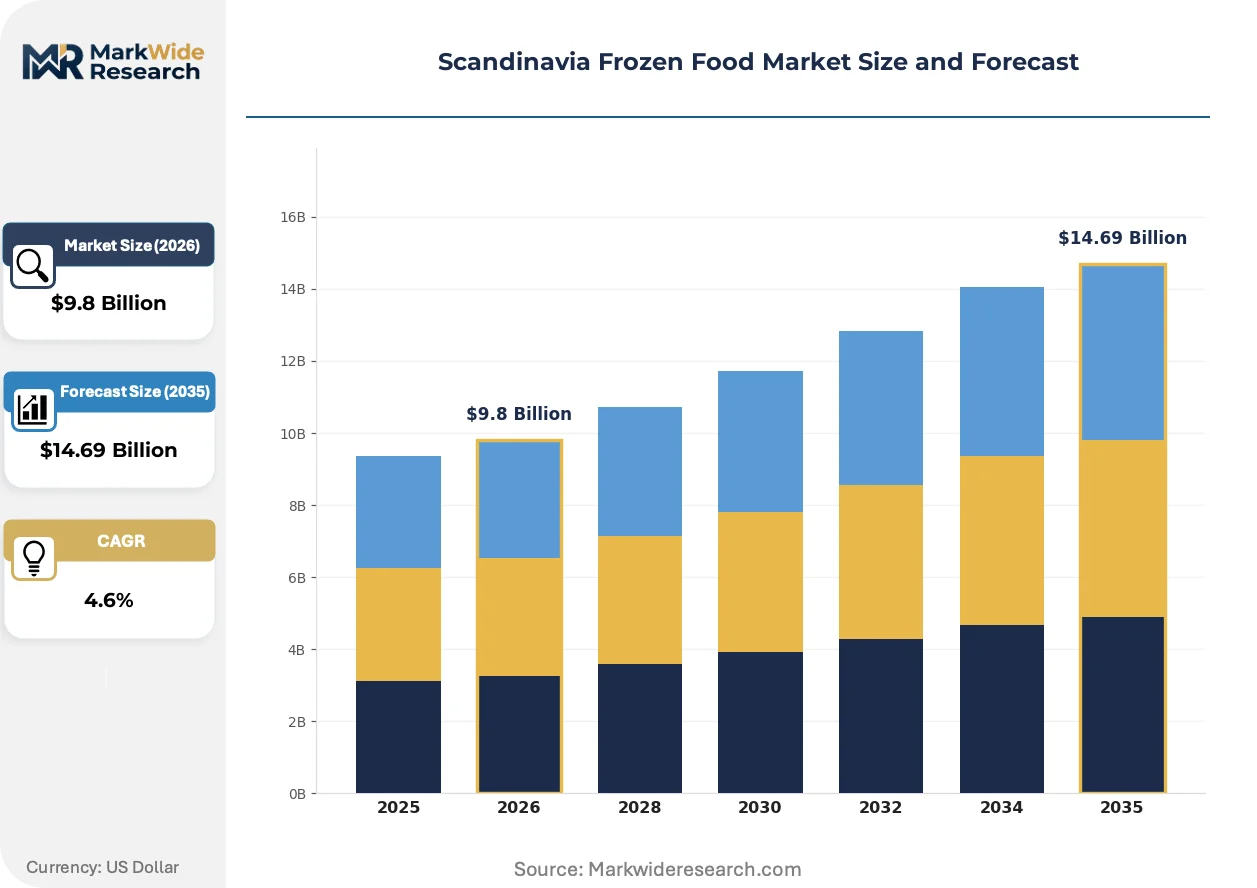
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Vegetables, Frozen Meat, Frozen Fish, Frozen Prepared Meals Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale Consumer Segment: Families, Singles, College Students, Health-Conscious Consumers Packaging Type: Rigid Containers, Flexible Pouches, Bags, Cartons |
| Companies Covered | Findus Group, Arla Foods, Orkla ASA, Nestlé, Ardo NV, McCain Foods, Nomad Foods Limited, Lantmännen Unibake Denmark A/S, Lerøy Seafood Group ASA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scandinavia Frozen Food Market Strategic Shifts & Innovations
Mono-material flexible packaging is fragmenting established supply relationships, while digital traceability platforms and direct-to-retailer procurement models compress traditional wholesale intermediation in Scandinavian frozen food distribution.
Blast freezing technology is fragmenting conventional equipment vendor relationships as modular IQF tunnel systems enable mid-size processors to achieve previously capital-prohibitive throughput rates. Danish frozen vegetable cooperatives adopt these systems to bypass centralized freezing facility dependence. Equipment financing partnerships with Nordic banks accelerate adoption, compressing the traditional five-year replacement cycle to eighteen-month upgrade windows.
EU Green Deal packaging waste directives mandate substitution of multilayer laminates with recyclable mono-material structures by 2030. Swedish converters retrofit extrusion lines to produce high-barrier polyethylene alternatives, though oxygen transmission rates remain 40% above legacy specifications. Frozen fish processors in Bergen and Gothenburg absorb margin compression while awaiting improved barrier coatings.
Direct procurement from aquaculture cooperatives is displacing traditional auction-based fish sourcing for Copenhagen's foodservice distributors. Restaurant groups in the Danish capital now contract directly with Faroese salmon farmers, eliminating two intermediary handling stages. This pattern concentrates most rapidly in premium sushi-grade frozen segments where provenance documentation commands price premiums.
Scandinavia Frozen Food Market Segmentation
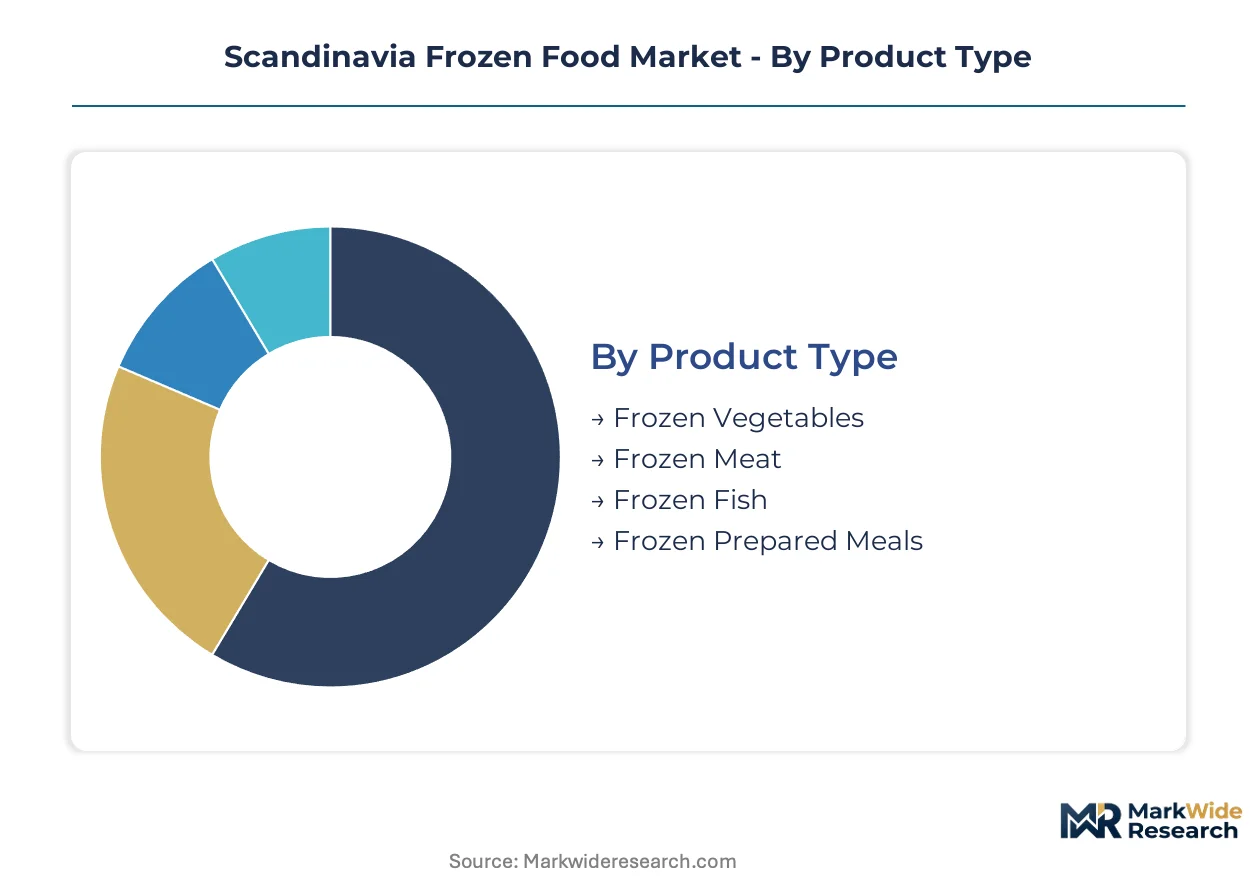
Segmentation in Scandinavian frozen food tracks how cold-chain capabilities and regulatory pressures reshape channel economics. Product and packaging configurations diverge sharply between retail and foodservice flows, while consumer micro-segments command distinct margin structures.
Product Type:
Channel-mix varies dramatically across product categories, with foodservice dominating fish flows and retail capturing prepared meal volumes.
- Frozen Prepared Meals:Allergen-controlled formulations with calibrated portions serve health-conscious urban consumers through supermarket and online channels. Copenhagen and Stockholm metropolitan demand concentrates here, driven by time-scarcity among dual-income households accepting premium positioning.
- Frozen Fish:Blast-frozen at sea or aquaculture-integrated processing preserves texture integrity for sushi-grade and retail segments. Norwegian coastal clusters supply this category, with direct procurement displacing traditional wholesale intermediation in Danish foodservice.
- Frozen Vegetables:Danish cooperative processing supplies retail private-label programs with standardized cut specifications.
- Frozen Meat:Norwegian import documentation requirements create asymmetric compliance costs, channeling volumes through established cold-chain operators.
Frozen fish dominates installed base. Frozen prepared meals is where expansion concentrates.
Distribution Channel:
Cost-tier stratification separates premium temperature-controlled fulfillment from conventional ambient-adjacent retail.
- Supermarkets:Multi-temperature zone displays accommodate full product range with highest footfall conversion rates. Swedish and Norwegian chains invest in automated frozen sections, compressing labor costs while maintaining product accessibility.
- Online Retail:Last-mile cold-chain maturation in Oslo and Stockholm enables direct-to-consumer frozen meal delivery with temperature-verified handoff. Metro zone density supports unit economics that remain unviable in rural postcodes.
- Wholesale:Foodservice distributors in Copenhagen-Aarhus corridor maintain dedicated frozen storage for restaurant and institutional procurement.
- Convenience Stores:Limited frozen SKUs focus on impulse categories with extended shelf-life packaging.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Consumer Segment:
Application context—meal occasion and preparation time—determines product format and channel selection.
- Health-Conscious Consumers:Clean-label scrutiny drives sodium-reduced and allergen-controlled formulation premiums. Swedish consumers in this segment accept price positioning 15-30% above standard tier for simplified ingredient declarations.
- Families:Bulk formats and value multi-packs concentrate in suburban supermarket locations with freezer capacity for stock-up purchasing.
- Singles:Single-serve prepared meals and portion-calibrated fish fillets align with smaller household economics.
- College Students:Price-sensitive demand concentrates on private-label frozen vegetables and basic meat formats through discount channels.
Families dominate installed base. Health-conscious consumers is where expansion concentrates.
Packaging Type:
Supply concentration in Swedish and Danish converting capacity shapes material availability and compliance timelines.
- Flexible Pouches:EU Green Deal mandates force mono-material substitution of multilayer laminates by 2030. Swedish extrusion retrofits produce high-barrier polyethylene alternatives, though oxygen transmission rates lag legacy specifications.
- Rigid Containers:Polypropylene and PET structures maintain dimensional stability for stacked retail display. Danish manufacturers absorb retooling costs for recyclable mono-material compliance ahead of regulatory deadlines.
- Bags:Standard polyethylene formats serve bulk frozen vegetable and commodity meat segments with lowest unit cost.
- Cartons:Paperboard-based structures with polyethylene barriers support premium positioned prepared meals requiring print quality for brand differentiation.
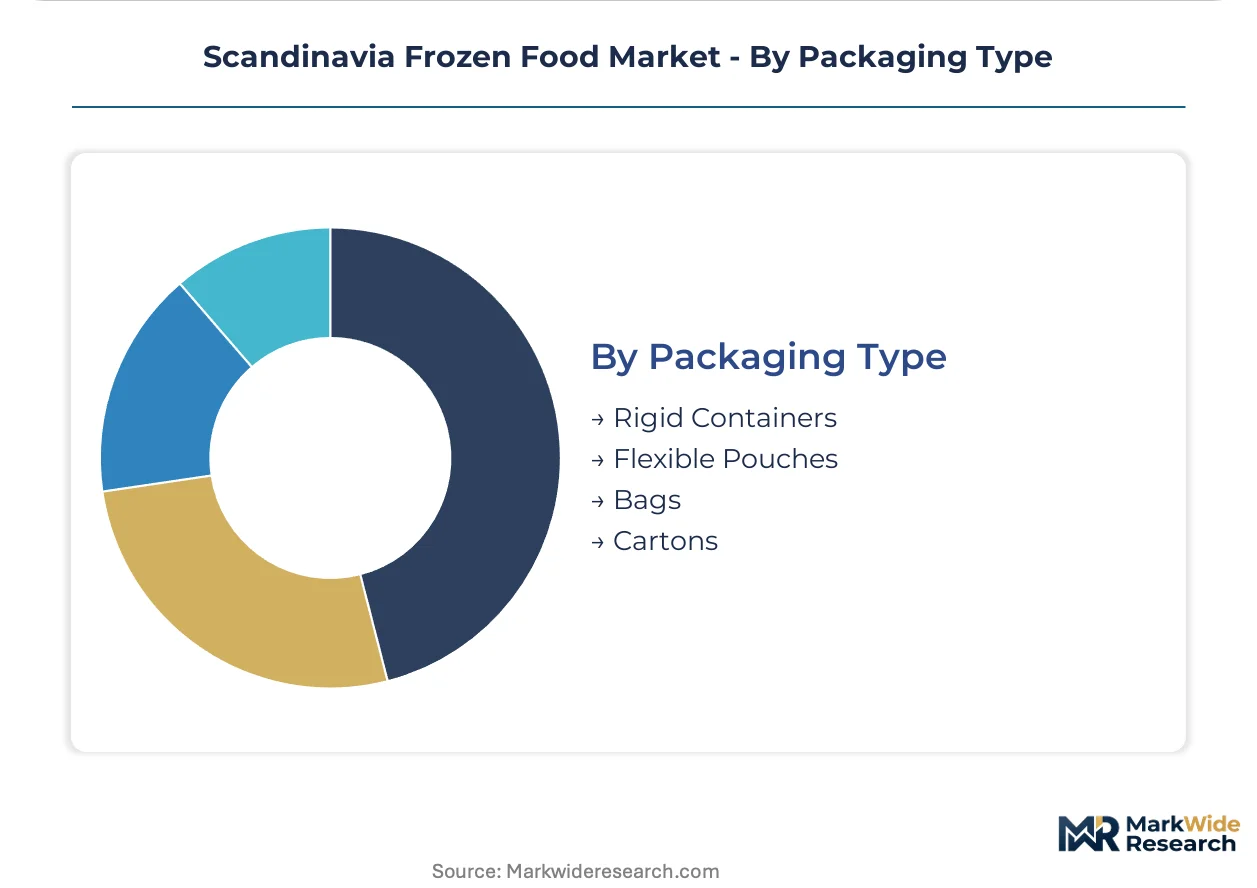
Rigid containers dominate installed base. Flexible pouches is where reformulation investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumers in Norway and Sweden accept premium positioning for clean-label frozen prepared meals, while Danish buyers concentrate demand through Copenhagen-Aarhus corridor logistics infrastructure that reduces spoilage costs.
Norway
Direct procurement from aquaculture cooperatives displaces traditional auction-based fish sourcing for Bergen and Stavanger processors. The Norwegian Food Safety Authority enforces cold-chain documentation requirements exceeding baseline EU standards, creating asymmetric compliance costs for imported frozen meat. Coastal processing clusters in Møre og Romsdal support blockchain-enabled provenance tracking for premium frozen fish exports.
Sweden
Stockholm metropolitan zone density enables last-mile cold-chain maturation for direct-to-consumer frozen meal delivery. ECHA REACH compliance drives investment in preservative-free preservation technologies across Uppsala and Malmö manufacturing facilities. Swedish converters in Gothenburg retrofit extrusion lines to produce high-barrier mono-material polyethylene alternatives for flexible pouch packaging.
Denmark
Copenhagen-Aarhus corridor infrastructure supports premium frozen seafood distribution with reduced spoilage rates for foodservice channels. The EU Green Deal packaging waste directives mandate substitution of multilayer laminates with recyclable structures by 2030, forcing Danish manufacturers to absorb retooling costs ahead of regulatory deadlines. Danish frozen vegetable cooperatives adopt modular IQF tunnel systems to bypass centralized freezing facility dependence.
Finland
Helsinki metropolitan demand concentrates for allergen-controlled frozen prepared meals serving time-scarce dual-income households. Finland's national food safety regulator aligns with EU baseline standards while maintaining stricter veterinary border controls for frozen meat imports from non-EU sources. Tampere-based cold-chain operators expand automated frozen storage capacity to serve cross-border Nordic distribution.
Scandinavia Frozen Food Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across Scandinavia's frozen food sector. Vertically integrated aquaculture-to-retail chains command premium positioning in frozen fish, while cooperative processing structures dominate commodity vegetable segments. Strategic archetypes include Nordic sourcing network operators, sodium-reduction R&D specialists, and dairy-integrated dessert platform owners. Competitive moves concentrate on direct procurement partnerships with aquaculture cooperatives and mono-material packaging line retooling ahead of EU regulatory deadlines.
Among Nordic-anchored operators, Findus Group exemplifies the vertically integrated sourcing network archetype through its captive supply relationships. Orkla ASA occupies a position within the reformulation-focused tier, representing investment intensity in clean-label frozen prepared meals. Arla Foods sits within the dairy-integrated platform category, anchoring brand strength in frozen dessert segments where co-manufacturing relationships extend distribution reach.
| Leading Market Players |
|---|
| Findus Group |
| Arla Foods |
| Orkla ASA |
| Nestlé |
| Ardo NV |
| McCain Foods |
| Nomad Foods Limited |
| Lantmännen Unibake Denmark A/S |
| Lerøy Seafood Group ASA |
| Others |
Cost & Logistics Intelligence
Seventy-two-hour cold-chain integrity windows concentrate pricing power with operators maintaining blast-freezing-to-retail continuity across the Copenhagen-Aarhus corridor. Inventory velocity at Norwegian coastal processing clusters compresses working-capital cycles for aquaculture-integrated players while forcing margin discipline on import-dependent meat distributors facing documentation-heavy customs clearance.
Pricing Analysis
After-sales revenue through temperature-controlled logistics contracts and extended shelf-life service agreements drives lifetime value for frozen prepared meal specialists. Three-tier pricing structure across premium clean-label, standard formulation, and economy private-label tiers stratifies margin pools. Cost compression in the standard tier intensifies because mono-material packaging retooling absorbs capital before barrier-performance parity arrives. College students and single-person households exhibit highest price sensitivity, while health-conscious dual-income households in Stockholm and Oslo accept premium positioning with minimal elasticity.
Supply Chain Analysis
Port congestion at Gothenburg and Bergen container terminals elevates inbound logistics costs for imported frozen meat and specialty packaging films. Supply concentration rests on Norway for aquaculture-integrated fish, Denmark for cooperative vegetable processing, and Sweden for mono-material flexible film converting. Raw material dependencies include polyethylene resins, blast-freezing equipment components, and temperature-monitoring IoT sensors. Single-source vulnerability concentrates in Swedish extrusion capacity for high-barrier mono-material alternatives. Distribution runs through Copenhagen-Aarhus corridor cold-chain hubs serving foodservice wholesale and supermarket retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scandinavia frozen food is approaching a platform-economics inflection where blockchain-enabled provenance tracking and direct-to-retailer procurement platforms disintermediate traditional wholesale intermediation.
For Market Incumbents: Consolidate backward integration into aquaculture cooperatives and captive cold-chain infrastructure to defend margin position against direct-procurement platforms. Prioritize mono-material packaging line certification ahead of EU Green Deal deadlines to lock in converter capacity. Reinforce R&D intensity in sodium-reduced formulation to capture front-of-pack labeling advantages.
For New Entrants and Emerging Players: Differentiate on allergen-controlled single-serve prepared meals targeting time-scarce singles in Stockholm and Helsinki metropolitan zones. Exploit underdeveloped last-mile cold-chain density in secondary Norwegian cities as a white-space entry point. Pursue direct-to-consumer subscription models with temperature-verified handoff as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because aquaculture-to-retail vertical integration and mono-material packaging compliance create asymmetric scale advantages. Target mid-cap processors with coastal cold-chain assets and established EU regulatory documentation systems. Watch for EU front-of-pack nutritional labeling implementation as the signal indicating formulation-premium inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Transition | EU Green Deal compliance forces Swedish converter retooling ahead of 2030 mandates. |
| Blockchain Provenance Integration | Norwegian coastal clusters enable premium frozen fish traceability for Copenhagen foodservice. |
| Direct-to-Consumer Cold-Chain Buildout | Oslo and Stockholm metro density supports temperature-controlled fulfillment network expansion. |
| Sodium-Reduced Formulation R&D | Orkla ASA's clean-label investment anchors positioning for EU nutritional labeling expansion. |
| Aquaculture Cooperative Procurement | Faroese salmon direct contracts eliminate intermediary handling stages for Danish distributors. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, cold-chain operator customs records, and seafood trade databases. Interviews with frozen food brand managers, supermarket category buyers, aquaculture cooperative procurement leads, and cold-chain logistics operators inform demand-side and supply-side assessments. Secondary validation draws from ECHA REACH compliance documentation, EU Green Deal directive texts, and Nordic customs trade statistics. Bottom-up volume modeling and top-down value triangulation cross-check segment-level estimates.
Segmentation dimensions modeled include product type, distribution channel, consumer application context, and packaging material configuration across the projection horizon. CAGRs derive from trend extrapolation calibrated against historical cold-chain infrastructure investment cycles and regulatory compliance cost absorption patterns. Forecast inputs incorporate electricity cost volatility assumptions for blast-freezing operations and mono-material packaging adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement, stable cold-chain energy costs, or intact Nordic trade flows would require recalibration. Forecasts reflect documented assumptions about packaging substitution timelines and front-of-pack labeling implementation scope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
North America Frozen Pizza Market