
 North America Freeze Dried Products Market | 2026-2036
North America Freeze Dried Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Freeze Dried Products Market Analytics
Backpacking and emergency preparedness is recalibrating the end-use mix for freeze dried offerings. Nestlé S.A. leverages its retail distribution depth to anchor supermarket placement across the United States. Van Drunen Farms dominates ingredient supply to food manufacturers with its integrated Illinois and California growing operations. OFD Foods LLC specializes in custom freeze drying for military and institutional accounts.
Freeze dried products undergo sublimation dehydration at pressures below 6.1 millibars and shelf temperatures typically ranging from -50°C to -80°C, yielding moisture content below 3% and shelf stability exceeding 25 years for sealed packaging. The technology serves commercial applications requiring lightweight, nutrient-retentive food preservation for remote consumption and long-duration storage. Fruits retain the largest value share within product type segmentation due to premium pricing for berry and tropical varieties in retail channels. Military application demand generates the fastest volume expansion as defense agencies expand cold-chain-independent ration programs. Online retail distribution captures margin pools through direct-to-consumer subscription models targeting camping enthusiasts and household preppers.
The FDA enforces low-acid canned food regulations extending to freeze dried products with pH controls and water activity testing for pathogen prevention. USDA organic certification and FSMA preventive controls reshape ingredient sourcing and facility validation requirements across North American production sites. The EPA regulates solvent recovery and energy intensity in vacuum pump operations for environmental compliance. Stakeholders must monitor evolving defense procurement specifications and organic label integrity standards as dual demand vectors from military and clean-label retail channels converge.
Market Dynamics
Military procurement expansion and FSMA preventive controls are reshaping competitive positioning across North American freeze dried production, forcing processors to dual-certify for defense contracts and organic retail channels simultaneously.
Growth Catalysts
- Defense Ration Modernization:The U.S. Department of Defense is expanding shelf-stable meal contracts requiring cold-chain-independent logistics. Military application demand generates the fastest volume expansion in the sector.
- FSMA Preventive Controls:FDA-mandated hazard analysis and risk-based preventive controls are accelerating facility validation investments. This regulatory pressure is consolidating compliant supplier networks.
- California Central Valley Processing Cluster:Demand concentrates in this geography due to integrated fruit supply chains and vacuum pump infrastructure density. Proximity to Pacific Northwest fruit belt reduces raw material transit time.
Market Restraints
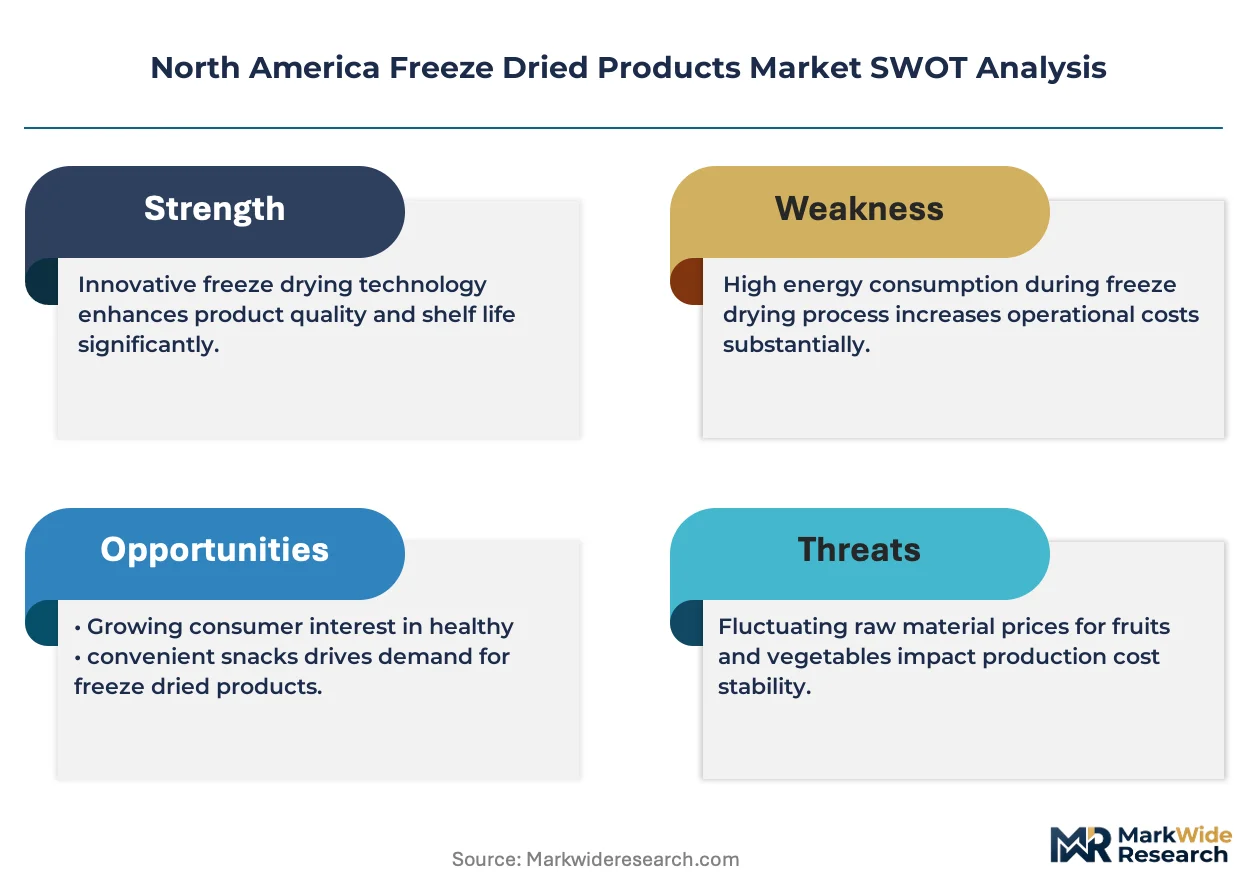
- Energy Input Volatility:Vacuum pump operations consume substantial electricity for sublimation dehydration at pressures below 6.1 millibars. EPA-regulated solvent recovery adds secondary energy intensity compliance costs.
- Equipment Supply Concentration:Specialized freeze drying chamber fabrication concentrates among limited industrial refrigeration equipment suppliers. Lead times for -50°C to -80°C shelf temperature systems extend procurement cycles.
- Moisture Barrier Substitution Limits:Alternative dehydration technologies including drum drying and air drying retain lower nutrient profiles. These substitutes fail military specification requirements for 25-year shelf stability.
Strategic Opportunities
- Pacific Northwest Berry Belt Expansion:Washington and Oregon blueberry and raspberry cultivation offers underpenetrated raw material sourcing. Organic certification density in this region supports clean-label product line development.
- Direct-to-Consumer Subscription Channels:Online retail distribution captures margin pools through recurring revenue models. Camping enthusiasts and household preppers represent addressable micro-segments.
- USDA Organic Certification Tailwind:Federal organic label integrity standards create pricing differentiation for certified ingredient supply. Van Drunen Farms and similar integrated growers leverage this for food manufacturer contracts.
Industry Challenges
- Vacuum Technology Specialist Scarcity:Operation of sublimation systems requires technicians trained in cryogenic engineering and pressure vessel management. Educational pipeline gaps constrain facility expansion timelines.
- Dual Certification Complexity:Simultaneous FDA low-acid canned food compliance and USDA organic validation extends facility qualification periods. Traceability requirements for low-moisture foods demand integrated ERP systems.
- Cold Chain Infrastructure Integration:Pre-freeze processing requires blast freezing capacity that legacy food manufacturing plants lack. Retrofit capex for -80°C staging areas strains mid-capitalization processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Freeze Dried Products Market |
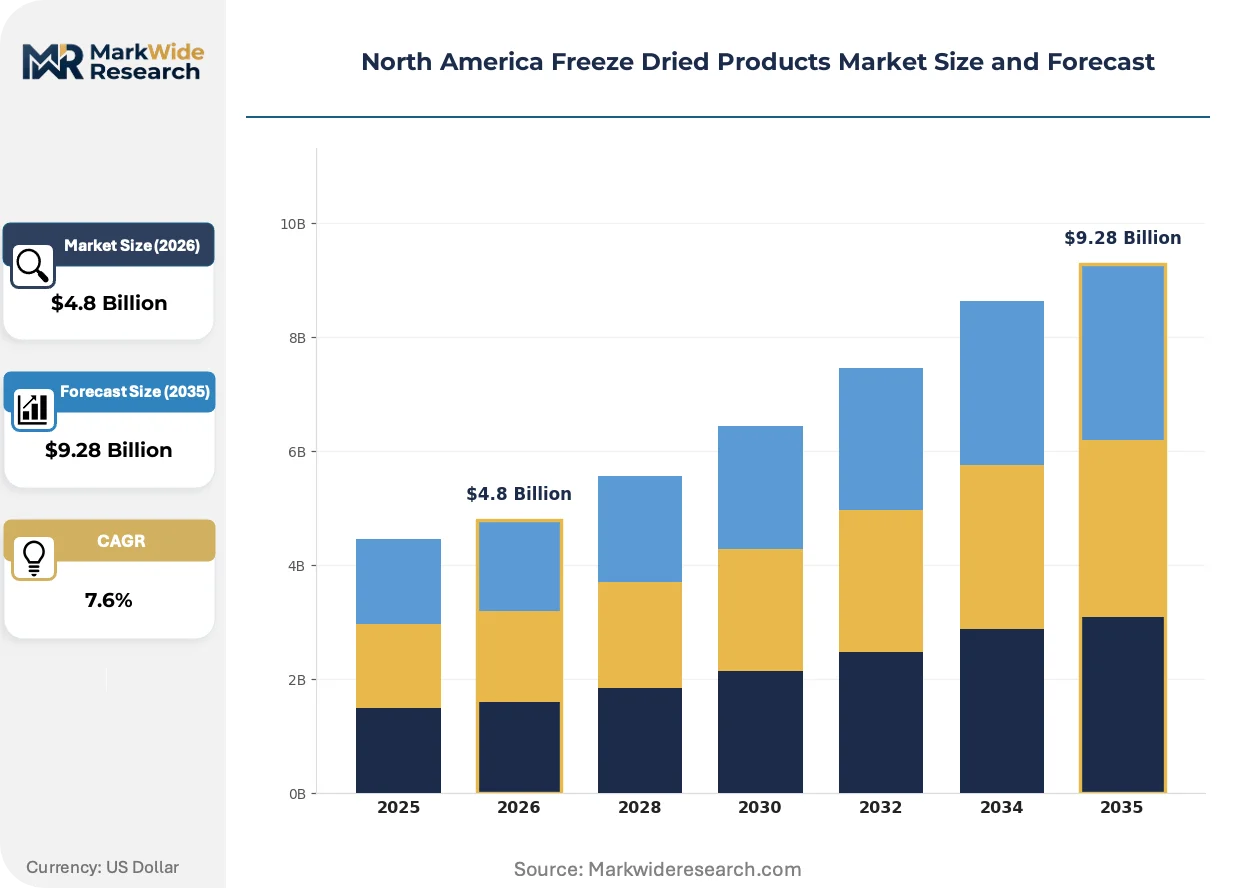
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Meals, Snacks Application: Food Service, Retail, Emergency Preparedness, Military End User: Hospitality, Camping Enthusiasts, Food Manufacturers, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Conagra Brands, Inc., Kerry Group plc, Nestlé S.A., OFD Foods LLC, Van Drunen Farms, Mercer Foods LLC, Thrive Life, LLC, Harmony House Foods, Inc., Freeze Dry Foods, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Freeze Dried Products Market Evolving Landscape
Automation of sublimation monitoring and predictive maintenance is compressing operational labor requirements while regulatory digitization and channel fragmentation reshape how freeze dried products reach end users.
Radio-frequency moisture sensing technology is automating real-time sublimation endpoint detection in commercial freeze drying chambers. Military contractors and high-volume fruit processors are adopting these systems at accelerated replacement cycles. This automation is compressing batch-to-batch variability and reducing technician oversight hours per production run.
The FDA and USDA co-administered Food Safety Modernization Act enforcement is tightening water activity testing mandates for pathogen prevention in low-moisture foods. Facility validation documentation must now integrate preventive control records with organic certification audits. Berry and tropical fruit segments face the steepest compliance cost escalation as premium retail channels demand dual verification.
Subscription-based preparedness kit assembly is displacing traditional outdoor retail distribution for camping and emergency food categories. Direct-to-consumer platforms now capture household prepper demand that REI and Bass Pro Shops previously dominated. This channel rotation is most visible in California and Texas metropolitan markets where urban density supports efficient last-mile fulfillment.
North America Freeze Dried Products Market Segmentation
Freeze dried product specifications diverge sharply across end-use contexts, with military contracts demanding 25-year shelf stability while retail channels prioritize flavor intensity and rehydration speed. Understanding these segment boundaries clarifies where capital deployment yields margin protection versus volume expansion.
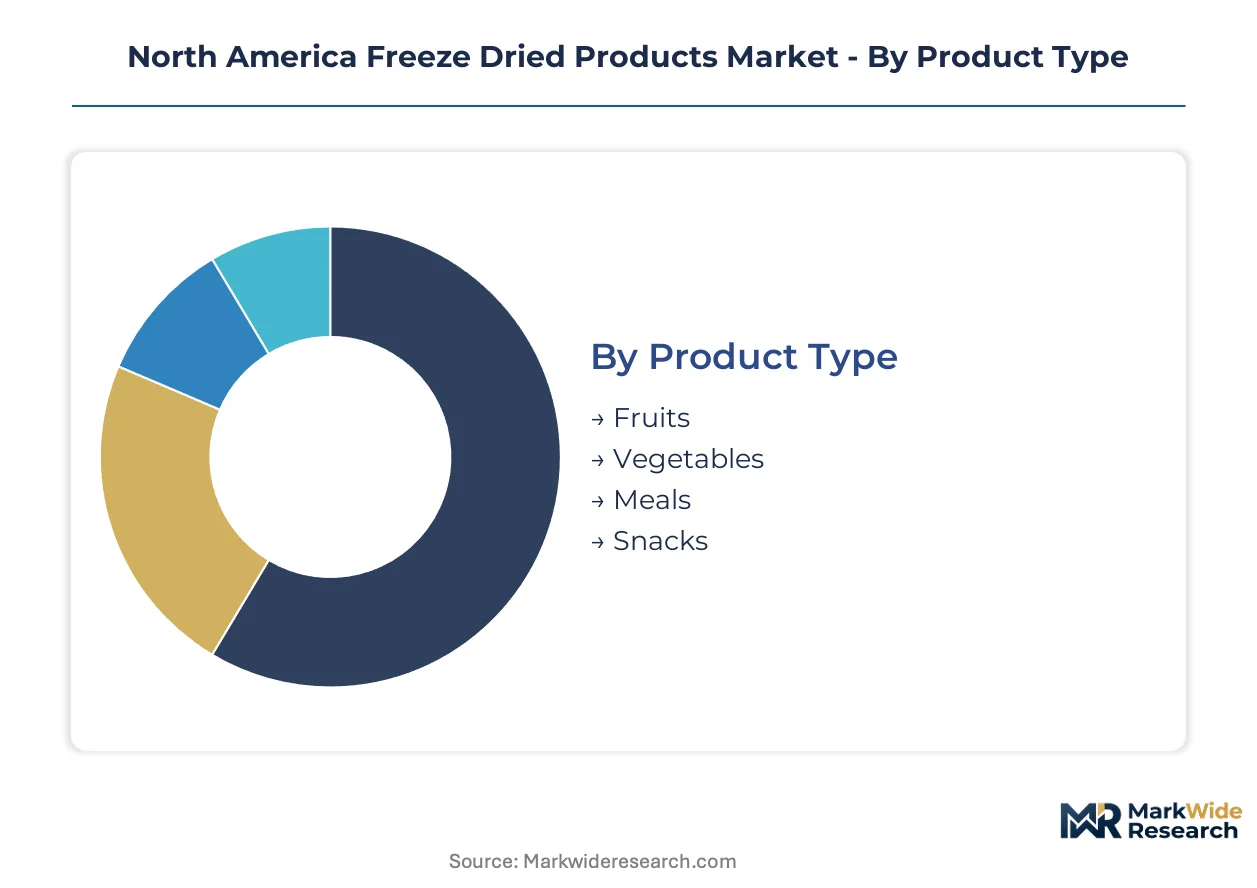
Product Type:
Upgrade cycles favor premium berry and tropical varieties as retailers refresh private-label lines to capture clean-label premiums.
- Fruits:Berry and tropical varieties undergo sublimation at -50°C to -80°C shelf temperatures, preserving volatile aromatic compounds lost in conventional drying. California Central Valley processors and Pacific Northwest fruit belt suppliers concentrate supply for this premium retail tier, with organic certification commanding pricing separation.
- Meals:Complete shelf-stable entrees integrate protein, carbohydrate, and vegetable components in single-package formats. Military procurement expansion in Texas and California defense corridors drives fastest volume growth for this segment, with cold-chain-independent logistics specifications disqualifying competing preservation methods.
- Vegetables:Diced and sliced formats serve food manufacturer ingredient demand across soup and ready-meal applications. Van Drunen Farms dominates contracted supply through integrated Illinois growing operations.
- Snacks:Crisp-textured fruit pieces and yogurt bites target direct-to-consumer subscription channels. Online retail distribution captures margin pools through recurring revenue models targeting camping enthusiasts.
Volume placements concentrate in Fruits; the faster expansion belongs to Meals.
Application:
Cost tier stratification separates specification-grade military contracts from price-sensitive retail channels, with emergency preparedness occupying a hybrid middle position.
- Military:Defense agencies mandate water activity below 0.6 and oxygen barrier packaging validated for 25-year stability. U.S. Department of Defense shelf-stable meal contract expansion drives fastest volume growth, with OFD Foods LLC and similar specialists qualifying for procurement specifications.
- Retail:Supermarket and online channels prioritize rehydration speed and flavor intensity over maximum shelf life. Nestlé S.A. leverages distribution depth to anchor placement across United States mass-market retailers.
- Emergency Preparedness:Household prepper demand concentrates in California and Texas metropolitan markets where urban density supports efficient last-mile fulfillment. Subscription-based kit assembly displaces traditional outdoor retail distribution.
- Food Service:Restaurants and institutional kitchens value lightweight storage and portion control for remote or seasonal operations. Backpacking and camping outfitters represent secondary demand nodes.
Revenue concentrates in Retail; Military application shows the steepest expansion trajectory.
End User:
Customer type determines packaging format, with bulk ingredient supply to manufacturers contrasting sharply with single-serve retail configurations.
- Food Manufacturers:Industrial buyers source diced fruits and vegetables as ingredients for cereal, bakery, and ready-meal production. Van Drunen Farms dominates this channel through backward integration into Illinois and California growing operations.
- Households:Direct purchasers prioritize convenience and long-duration storage for emergency contingencies. Online subscription models capture this demand most efficiently in dense metropolitan markets.
- Hospitality:Hotels and cruise lines deploy freeze dried components for remote location service where fresh supply chains fail. Portion-controlled formats reduce waste in variable-demand environments.
- Camping Enthusiasts:Lightweight, nutrient-dense meal packages address backcountry calorie requirements with minimal pack weight. REI and Bass Pro Shops retain partial channel share though direct-to-consumer platforms gain ground.
Procurement volume clusters with Food Manufacturers; Households represent the fastest-climbing demand category.
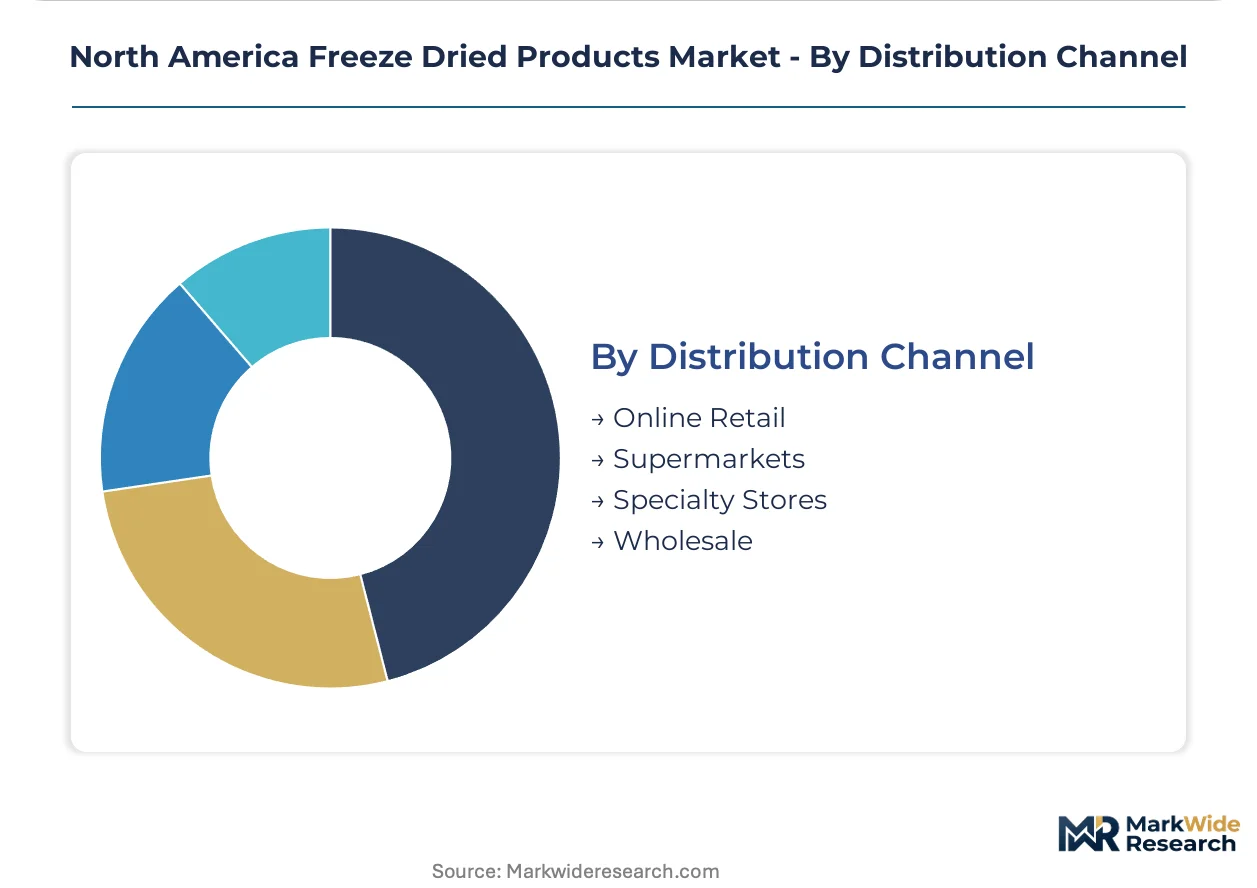
Distribution Channel:
Margin structure varies dramatically across channel tiers, with wholesale and specialty stores capturing value through technical consultation while online retail extracts efficiency through automation.
- Online Retail:Direct-to-consumer platforms eliminate intermediary markups and enable subscription-based recurring revenue. Camping enthusiasts and household preppers in California and Texas metropolitan markets drive addressable micro-segment concentration.
- Wholesale:Bulk supply to food manufacturers and institutional buyers prioritizes consistent specification and contracted volume. Van Drunen Farms leverages this channel for ingredient supply relationships.
- Supermarkets:Mass-market placement requires slotting fee investment and retail distribution depth. Nestlé S.A. anchors shelf presence through existing frozen and packaged food infrastructure.
- Specialty Stores:Outdoor retailers and preparedness suppliers offer technical guidance and curated assortment. Bass Pro Shops and REI maintain geographic concentration in mountain and coastal recreation corridors.
Transaction volume concentrates in Wholesale; Online Retail demonstrates the most rapid share gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Enterprise Zone tax credits and Illinois' EDGE program anchor freeze dried production concentration. Processing clusters co-locate near fruit cultivation belts to minimize raw material transit. Defense procurement corridors in Texas and Virginia drive military specification demand.
United States
Military ration modernization and emergency preparedness subscription channels concentrate demand in California, Texas, and Virginia corridors. The FDA enforces FSMA preventive controls requiring hazard analysis documentation for low-moisture food facilities. California's Central Valley processing cluster integrates vacuum pump infrastructure with Pacific Northwest fruit belt supply chains.
Canada
Backpacking tourism in British Columbia and Alberta generates lightweight meal demand from outdoor enthusiasts. Health Canada regulates food safety through the Safe Food for Canadians Regulations with preventive control requirements mirroring FDA frameworks. Ontario's food processing corridor near Toronto anchors ingredient supply to U.S. manufacturers.
Mexico
Tropical fruit export growth in Michoacán and Veracruz creates raw material sourcing opportunities for cross-border processors. COFEPRIS administers food safety standards with increasing alignment to FDA preventive control protocols. Baja California's maquiladora zones host contract freeze drying operations serving California-based brands.
Pacific Northwest
Organic blueberry and raspberry cultivation in Washington and Oregon supports clean-label product line development. USDA organic certification density in this region enables pricing differentiation for berry processors. Seattle-Tacoma logistics hubs facilitate direct-to-consumer fulfillment for subscription-based preparedness kit assemblers.
Southwest
Defense contractor concentration in Texas generates shelf-stable meal procurement for cold-chain-independent military logistics. The Department of Defense expands multi-year ration contracts requiring 25-year stability validation. Dallas-Fort Worth distribution infrastructure supports emergency preparedness retailer fulfillment to metropolitan household prepper segments.
North America Freeze Dried Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail channels favoring packaged brands and food service tilting toward ingredient suppliers. The vendor base concentrates among integrated growers with captive raw material supply and specialized military contractors with defense qualification credentials. Three archetypes dominate: vertically integrated agricultural processors, defense-focused specification houses, and direct-to-consumer subscription operators. Capacity expansion and dual certification for organic retail and military compliance represent the dominant competitive moves.
Among publicly traded packaged food conglomerates, Nestlé S.A. and Conagra Brands, Inc. anchor mass-market retail placement through existing frozen and shelf-stable distribution infrastructure. Van Drunen Farms exemplifies the integrated grower-processor archetype with backward control over Illinois and California cultivation operations. OFD Foods LLC occupies the defense contractor tier, specializing in custom freeze drying for military and institutional accounts requiring extended stability validation.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| Kerry Group plc |
| Nestlé S.A. |
| OFD Foods LLC |
| Van Drunen Farms |
| Mercer Foods LLC |
| Thrive Life, LLC |
| Harmony House Foods, Inc. |
| Freeze Dry Foods, Ltd. |
| Others |
Value Network & Pricing Analysis
Military procurement concentration in Texas and California defense corridors anchors contract-based long-term offtake pricing for specification-grade freeze dried meals. Subscription direct-to-consumer channels in metropolitan markets operate on per-unit transactional models with recurring revenue premiums for household preppers.
Pricing Analysis
Lead-time-driven pricing separates rush military contracts commanding premiums from standard procurement cycles with contracted discounts. Three-tier pricing structure across premium organic, standard commercial, and economy bulk ingredient levels reflects USDA certification density and volume scale. Pricing pressure stems from energy input volatility in vacuum pump operations as EPA compliance costs escalate. Food manufacturers exhibit highest price sensitivity due to ingredient cost pass-through limits, while defense agencies accept premium pricing for 25-year stability validation.
Supply Chain Analysis
Fresh fruit supply rests on California Central Valley cultivation and Pacific Northwest berry belt operations in Washington and Oregon. Vacuum pump fabrication draws from specialized industrial refrigeration equipment suppliers concentrated in the United States and Germany. Single-source vulnerability concentrates in -80°C shelf temperature system fabrication with extended procurement cycles. Distribution runs through integrated processor networks co-located with raw material cultivation to minimize transit degradation of volatile aromatic compounds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSMA preventive control compliance costs are forcing consolidation among mid-capitalization processors lacking integrated ERP traceability systems. Dual certification requirements for military and organic retail channels favor scaled incumbents with capital deployment capacity.
For Market Incumbents: Deepen backward integration into Pacific Northwest organic berry cultivation to secure raw material cost control against spot market volatility. Expand -80°C blast freezing retrofit capacity in California Central Valley facilities to capture defense contract volume expansion. Invest in radio-frequency moisture sensing automation to compress batch variability and reduce technician oversight costs per production run.
For New Entrants and Emerging Players: FDA preventive control digitization requirements in the United States open a window for software-enabled compliance service providers targeting mid-tier processors. Target Pacific Northwest organic certification gaps in Washington and Oregon raspberry supply as the most penetrable white space. Pursue direct-to-consumer subscription assembly partnerships with existing freeze drying capacity rather than greenfield facility investment.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated agricultural processors with captive Illinois or California growing operations and existing USDA organic validation. Long-term viability hinges on defense contract qualification credentials and clean-label retail channel access. Watch military shelf-stable meal contract award announcements as the primary inflection signal for volume allocation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous FDA low-acid food compliance and USDA organic validation unlocks military and retail channel access simultaneously. |
| Pacific Northwest Sourcing Expansion | Washington and Oregon organic berry cultivation integration secures premium raw material supply for clean-label product lines. |
| Vacuum Pump Infrastructure Retrofit | California Central Valley -80°C blast freezing capacity addition qualifies facilities for defense ration procurement specifications. |
| Direct-to-Consumer Channel Launch | Subscription-based preparedness kit assembly in Texas and California metropolitan markets captures recurring revenue from household preppers. |
| Automation Technology Deployment | Radio-frequency moisture sensing systems reduce batch-to-batch variability and technician oversight hours for military contractors. |
Research Methodology
Independent corroboration across plant managers at California and Illinois processing facilities, procurement leads at downstream food manufacturers, and defense contract officers at U.S. Department of Defense agencies underwrites the qualitative findings. Primary interviews with vacuum pump equipment specialists and organic certification auditors combined with secondary validation from FDA FSMA guidance documents, USDA organic integrity database records, and customs trade data for freeze dried fruit imports. Bottom-up facility capacity assessments and top-down military procurement budget analysis triangulate volume estimates.
Rate-of-change decomposition across product type, application, and distribution channel dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth trajectory blending rather than aggregate extrapolation. Modeled inputs include Pacific Northwest organic berry yield forecasts, EPA energy intensity compliance cost trajectories, and defense shelf-stable meal contract award patterns.
The model assumes a particular technology adoption path; alternative pathways for radio-frequency moisture sensing automation would alter the outlook if deployment lags among military contractors. Forecasts reflect documented assumptions about FSMA enforcement intensity and organic certification integrity standard evolution. Defense procurement priority shifts, energy input cost spikes, and vacuum equipment supply bottlenecks warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Chilled Meal Kits Market