
 Taiyaki Ice Cream Market | 2026-2036
Taiyaki Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Taiyaki Ice Cream Market Analytics
Young adults is collapsing the historical family-dominant buyer archetype in the Taiyaki Ice Cream Market as TikTok and Instagram virality reorders purchase occasions toward solo indulgence and social content creation. Kurikoan leverages its century-old Tokyo heritage to anchor premium positioning among domestic tourists seeking authentic wagashi experiences. SomiSomi competes through rapid format innovation, rotating limited-edition flavors that sustain repeat visitation across its West Coast dessert shop network. Imuraya dominates Japanese retail freezer cases with manufacturing scale that controls nationwide distribution into convenience stores and supermarkets.
Taiyaki ice cream fuses a fish-shaped waffle shell, traditionally cast in specialized molded griddles from wheat flour and egg batter, with a soft-serve or filled ice cream core to create a portable, visually distinctive frozen dessert. The shell achieves structural integrity through precise batter viscosity and griddle temperature control, enabling one-handed consumption while maintaining crisp-temperature contrast against the cold filling. Traditional product type segments command established margin pools in Japanese domestic markets, while fusion formats capture fastest-growing demand as Korean-American chains like SomiSomi popularize taiyaki-croissant hybrids and cereal-crusted variants. Dessert shop sales channels concentrate highest per-unit margins, whereas food truck distribution extends geographic reach into festival and event contexts with lower fixed-cost structures.
Japan's Ministry of Health, Labour and Welfare sets frozen confection standards that govern ice cream milkfat minimums and additive permissions, directly shaping formulation choices for cross-border exporters. The US FDA and state-level dairy regulations create fragmented compliance requirements for Japanese manufacturers entering American retail channels, particularly around soft-serve equipment sanitation and dairy sourcing documentation. China's SAMR enforces GB standards for frozen drinks that affect taiyaki equipment and ingredient imports through labeling and safety testing protocols. Stakeholders must monitor evolving dairy-alternative regulations as vegan product type segments expand, since oat and soy-based fillings trigger distinct allergen labeling and protein content standards across Japan, the United States, and China.
Market Dynamics
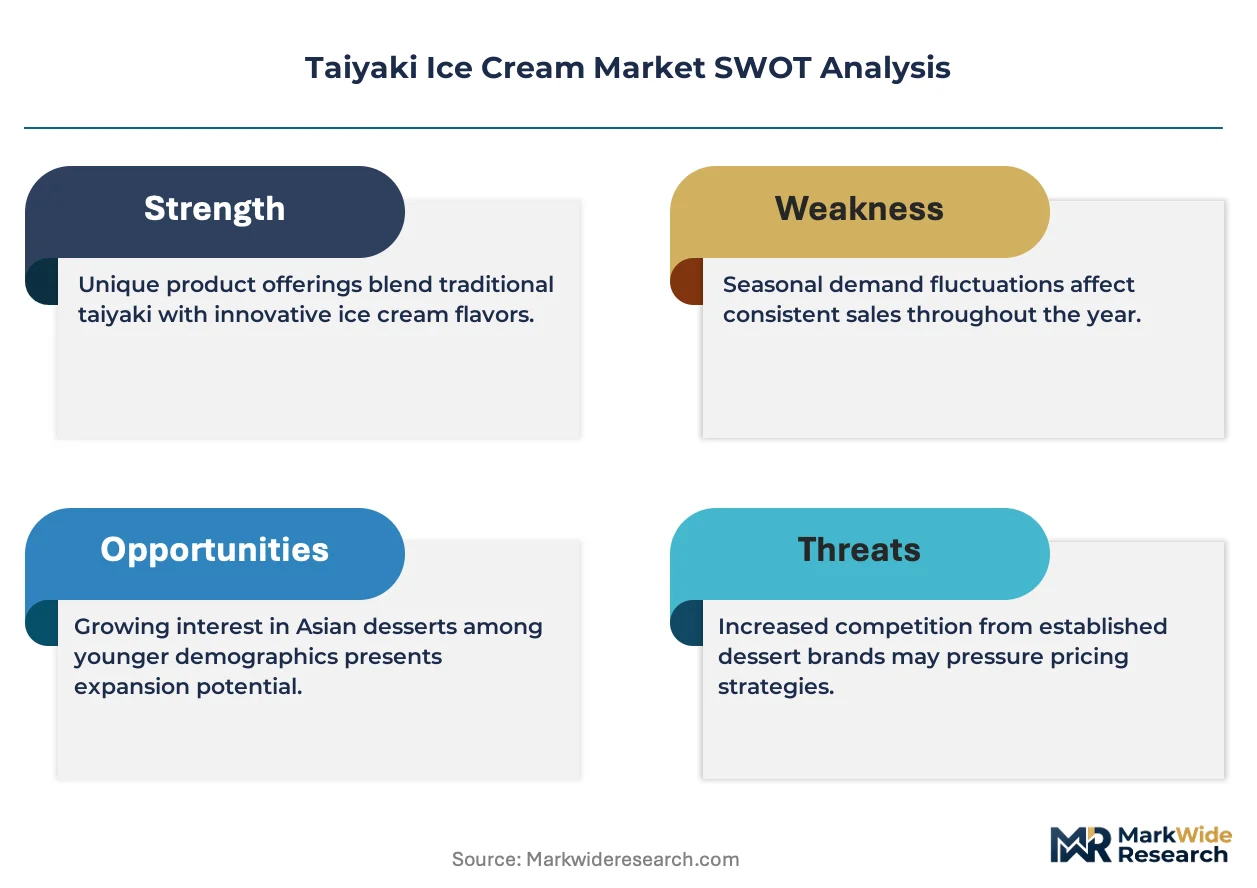
Social media-driven dessert culture is compressing purchase cycles and reordering buyer priorities toward visual distinctiveness and shareability, forcing manufacturers to prioritize Instagram-ready aesthetics over traditional flavor profiles.
Growth Catalysts
- TikTok and Instagram virality:Solo indulgence occasions now outpace family sharing, with young adults seeking content-worthy formats that drive repeat visits to dessert shops and food trucks.
- Japan's frozen confection standards:Clear Ministry of Health, Labour and Welfare guidelines on milkfat minimums and additive permissions provide regulatory certainty that accelerates new product development cycles.
- Urban tourism clustering:Tokyo and Osaka's dense foot traffic around traditional wagashi districts creates built-in distribution density for premium taiyaki ice cream formats.
Market Restraints
- Dairy input volatility:Soft-serve core formulations depend on fluid milk and cream supplies exposed to commodity price swings and seasonal production cycles.
- Equipment supply concentration:Specialized molded griddle manufacturing clusters in Osaka and Nagoya, creating lead time vulnerability for new market entrants.
- Substitution threat from mochi ice cream:Established freezer-aisle presence and lower equipment barriers enable faster retail scaling for competing Japanese dessert formats.
Strategic Opportunities
- Vegan formulation white space:Oat and soy-based soft-serve cores can capture allergen-conscious and sustainability-motivated segments as Japan's dairy-alternative regulations mature.
- Festival and event channel expansion:Food truck distribution models with lower fixed-cost structures can penetrate secondary Japanese cities lacking dedicated dessert shop infrastructure.
- Cross-border equipment export:Korean-American chains demonstrate demand for taiyaki griddle systems in North American mall and entertainment district installations.
Industry Challenges
- Griddle operator skill gaps:Precise batter viscosity and temperature control requirements demand trained labor that dessert shop franchises struggle to retain at scale.
- Multi-jurisdiction compliance timelines:Exporters face divergent FDA dairy documentation, state-level soft-serve sanitation rules, and China's SAMR frozen drink labeling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiyaki Ice Cream Market |
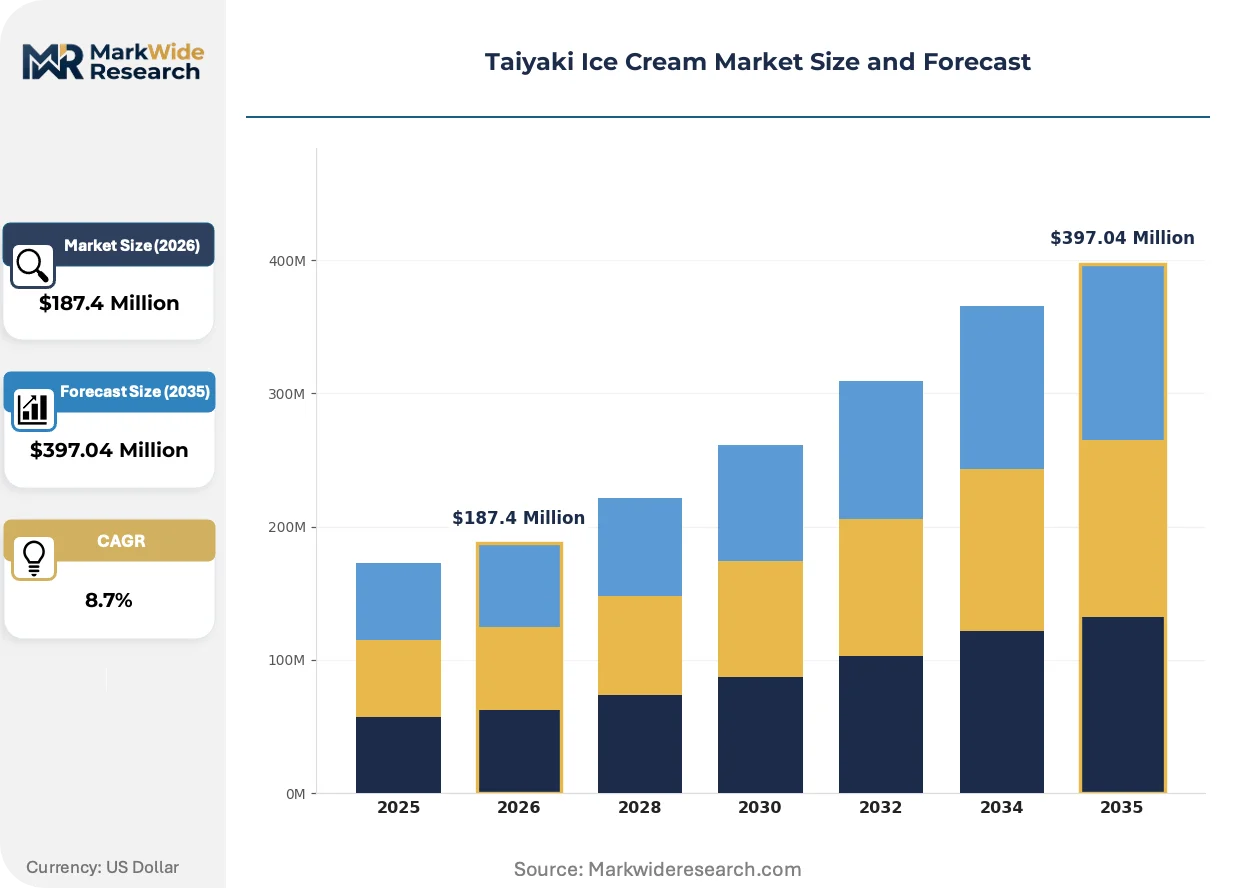
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Fusion, Vegan, Seasonal Flavour Category: Matcha, Chocolate, Red Bean, Strawberry Sales Channel: Online, Retail, Food Truck, Dessert Shop Customer Type: Families, Young Adults, Tourists, Students |
| Companies Covered | Kurikoan, Gelato Manufacturing, Harajuku, Tokyo Café, Guangzhou City Pengda Machineries, Taiyaki NYC, Taiyaki Hiiragi, Imuraya, SomiSomi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiyaki Ice Cream Market Evolving Landscape
Format hybridization and digital-native consumption patterns are redefining what constitutes authentic taiyaki, with traditionalists and fusion innovators competing for legitimacy across distinct buyer cohorts.
Specialized batter formulations with modified starch blends and egg protein adjustments are fragmenting the crisp-shell texture standard that once unified the category. Korean-American dessert chains now deploy taiyaki-croissant hybrids and cereal-crusted variants that sacrifice structural purity for viral shareability. Young adult buyers reward this experimentation, compressing the innovation cycle from seasonal to monthly limited-edition rotations.
Japan's Ministry of Health, Labour and Welfare frozen confection standards are tightening additive disclosure requirements for cross-border exporters. Manufacturers must now document milkfat sourcing and soft-serve equipment sanitation protocols that exceed domestic compliance thresholds. This regulatory friction most affects mid-sized producers targeting American retail channels, where FDA dairy regulations and state-level health codes create fragmented approval pathways.
Buyer concentration in solo indulgence occasions is displacing the historical family-dominant purchase archetype. Dessert shop channels now optimize for single-portion speed and photo-ready presentation over group seating and shared formats. This behavioral pivot appears most sharply in Tokyo's Harajuku and Shibuya districts, where queue management and Instagram wall installations drive location selection decisions ahead of traditional foot-traffic metrics.
Taiyaki Ice Cream Market Segmentation
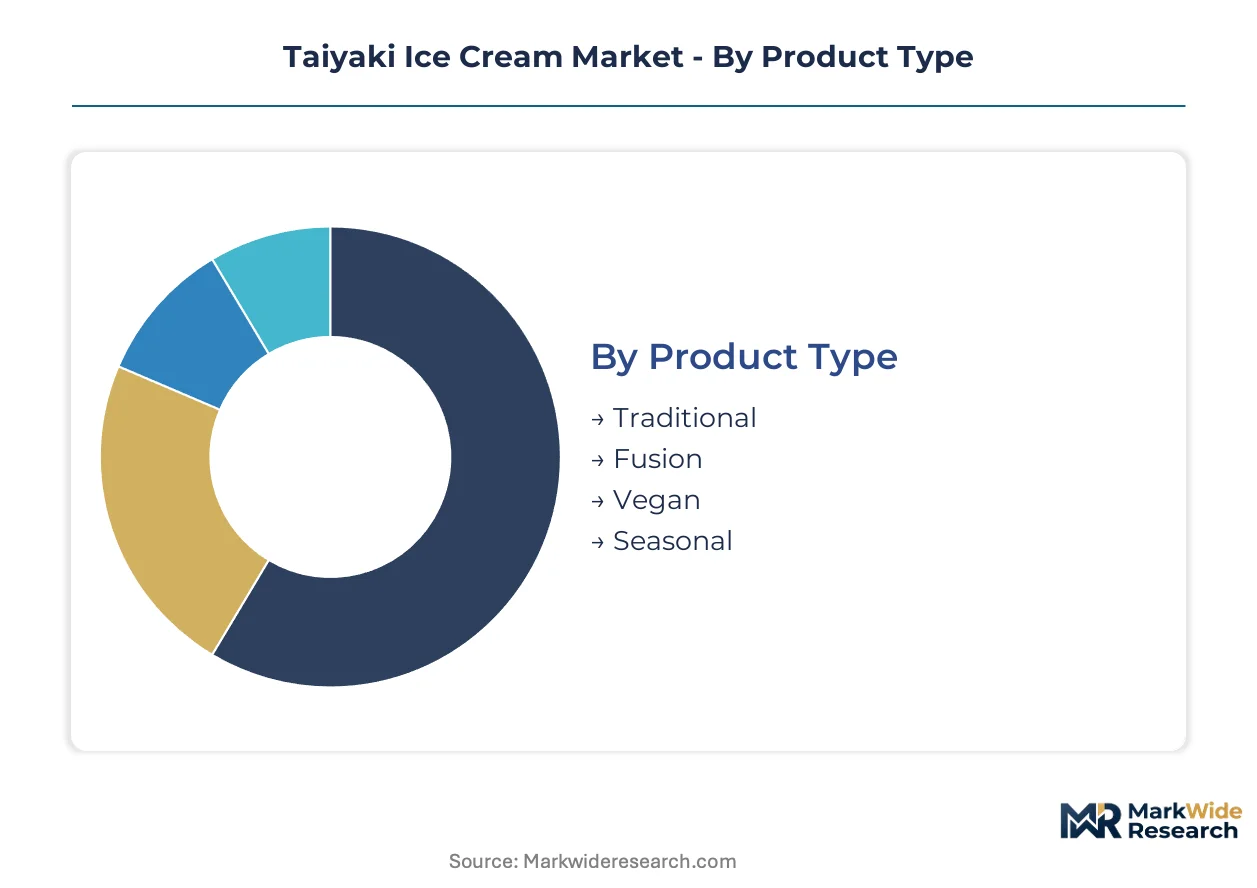
Segmentation in the Taiyaki Ice Cream Market reveals how format innovation and channel fragmentation create divergent margin pools. Each dimension exposes distinct vulnerability to substitution from mochi ice cream, frozen yogurt, and viral dessert formats.
Product Type:
Fusion formats face the most acute substitution pressure from Korean bungeoppang and croissant hybrids, while traditional formats defend share through heritage positioning.
- Traditional:Wheat flour and egg batter shells cast in specialized molded griddles deliver the crisp-temperature contrast that defines authentic wagashi experiences. Tokyo's Asakusa and Osaka's Dotonbori districts concentrate demand from domestic tourists seeking unaltered heritage formats. Traditional formats anchor the volume base while fusion formats gain share at the steepest rate.
- Fusion:Taiyaki-croissant hybrids and cereal-crusted variants sacrifice structural purity for Instagram shareability. Korean-American chains like SomiSomi rotate monthly limited editions that compress innovation cycles and sustain repeat visitation.
- Vegan:Oat and soy-based soft-serve cores target allergen-conscious segments as Japan's dairy-alternative regulations mature. Formulation complexity rises with protein content standards and labeling requirements.
- Seasonal:Sakura, chestnut, and yuzu rotations drive urgency purchases through scarcity marketing. Limited availability windows protect margin premiums.
Traditional formats anchor volume in heritage corridors while fusion formats capture the steepest share gains through viral velocity.
Flavour Category:
Cost tier stratification separates premium single-origin matcha from commodity chocolate, with red bean occupying the contested middle ground.
- Matcha:Single-origin Uji and Nishio powder grades command tiered pricing based on ceremonial versus culinary classification. Tokyo dessert shops source directly from Kyoto prefecture cooperatives to authenticate provenance claims.
- Chocolate:Cocoa butter content and sourcing documentation determine retail freezer placement. Commodity formulations dominate convenience store channels.
- Red Bean:Tsubuan and koshian texture variations segment traditionalist preferences. Sweetness modulation affects cross-border acceptance in North American markets.
- Strawberry:Fresh fruit versus compote filling choices alter shelf-life calculations and cold chain requirements. Seasonal domestic harvest windows constrain year-round supply.
Matcha anchors premium positioning while strawberry climbs fastest through color-driven social media performance.
Sales Channel:
Application context determines equipment investment intensity, with fixed-cost structures ranging from mobile griddles to full-service dessert shop buildouts.
- Dessert Shop:Harajuku and Shibuya installations optimize for queue throughput and Instagram wall placement. Per-unit margins peak here through speed and presentation premiums.
- Food Truck:Festival and event penetration extends geographic reach without lease commitments. Lower fixed-cost structures suit secondary cities lacking dedicated dessert infrastructure.
- Retail:Imuraya's nationwide convenience store and supermarket distribution leverages manufacturing scale. Frozen supply chains require -18°C integrity through last-mile delivery.
- Online:Direct-to-consumer frozen shipping faces last-mile cold chain fragility. Dry ice packaging costs erode margin at low order values.
Dessert shops anchor margin extraction while food trucks expand most quickly into underserved geography.
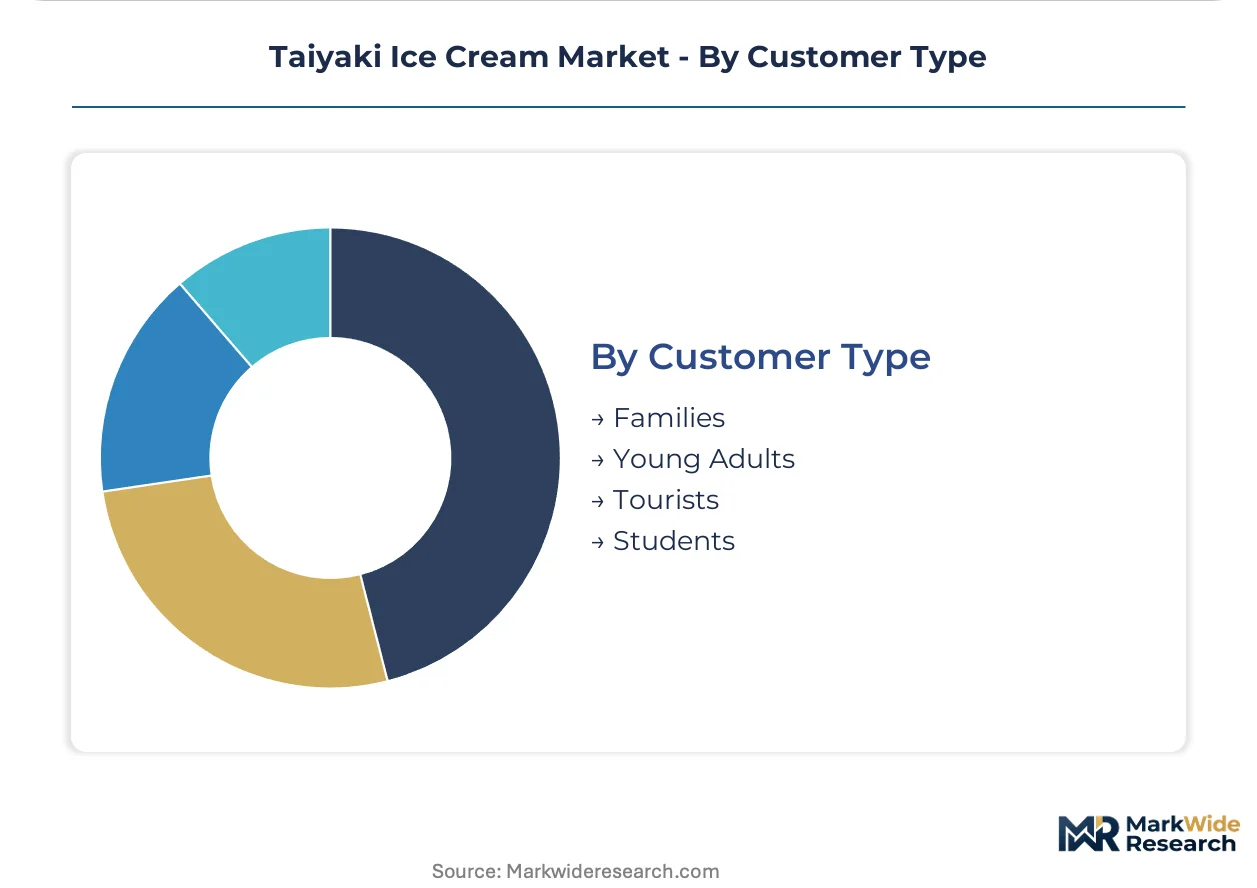
Customer Type:
Volume concentration now tilts toward solo indulgence occasions, displacing historical family-dominant purchase patterns.
- Young Adults:TikTok and Instagram virality reorder priorities toward visual distinctiveness over flavor tradition. Solo consumption occasions now outpace group sharing in Tokyo's dense urban districts.
- Tourists:Wagashi-seeking domestic visitors drive premium pricing in heritage corridors. Kurikoan's century-old Tokyo heritage anchors authenticity claims.
- Families:Multi-portion sharing formats face compression as dessert shops optimize for single-serve speed. Group seating configurations decline in new location designs.
- Students:Price-sensitive trial behavior concentrates near university districts. Limited-edition chasing sustains repeat visitation at accessible price points.
Young adults anchor demand transformation while tourists defend premium yield in heritage locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized taiyaki griddle manufacturing clusters in Osaka and Nagoya create lead time vulnerability for new market entrants seeking equipment supply. Demand concentrates in urban Japan while Korean-American chains demonstrate cross-border format viability. Regulatory fragmentation across export destinations complicates expansion timelines for domestic producers.
Japan
Tokyo's Harajuku and Shibuya districts drive premium dessert shop density through queue-optimized formats and Instagram wall installations. The Ministry of Health, Labour and Welfare governs frozen confection standards including milkfat minimums and additive permissions. Osaka's Dotonbori heritage corridor anchors traditional wagashi tourism demand alongside Nagoya's equipment manufacturing concentration.
United States
Korean-American dessert chains popularize taiyaki-croissant hybrids across West Coast mall installations and entertainment districts. The FDA and state-level dairy regulations create fragmented compliance requirements for soft-serve equipment sanitation and sourcing documentation. Los Angeles and New York metropolitan areas concentrate highest food truck and dessert shop penetration.
South Korea
Domestic bungeoppang heritage creates format familiarity that accelerates taiyaki ice cream trial among young adult consumers. The MFDS enforces frozen dessert labeling and dairy safety standards affecting cross-border ingredient imports. Seoul's Hongdae and Gangnam districts cluster dessert shop innovation with monthly limited-edition rotation cycles.
China
Tier-one city dessert tourism supports premium pricing for visual-forward formats in Shanghai and Beijing commercial corridors. SAMR administers GB standards for frozen drinks that govern equipment imports and ingredient safety testing protocols. The Yangtze River Delta manufacturing base supplies molded griddle components to regional equipment assemblers.
Australia
Sydney and Melbourne dessert shop openings test format viability in English-speaking markets with established Asian dessert familiarity. Food Standards Australia New Zealand regulates dairy content claims and allergen labeling for soft-serve formulations. Inner-urban precincts concentrate initial footprint before secondary city expansion.
Taiyaki Ice Cream Market Competitive Landscape
Concentration sits with heritage Japanese wagashi houses and Korean-American format innovators competing across distinct legitimacy claims. The market structure fragments between century-old domestic producers controlling retail freezer distribution and venture-backed dessert shop chains driving viral format experimentation. Two strategic archetypes dominate: heritage-authenticity defenders leveraging Tokyo and Osaka tourism corridors, and fusion-acceleration specialists rotating limited editions to sustain social media velocity. Competitive moves center on griddle equipment export partnerships and rapid flavor pipeline expansion.
Among heritage-positioned specialists, Kurikoan anchors century-old Tokyo provenance claims for domestic tourist segments seeking unaltered wagashi experiences. Imuraya represents manufacturing-scale archetypes with nationwide convenience store and supermarket freezer penetration. SomiSomi exemplifies Korean-American fusion acceleration, deploying monthly format rotations that compress innovation cycles and sustain repeat visitation across West Coast dessert shop networks.
| Leading Market Players |
|---|
| Kurikoan |
| Gelato Manufacturing |
| Harajuku |
| Tokyo Café |
| Guangzhou City Pengda Machineries |
| Taiyaki NYC |
| Taiyaki Hiiragi |
| Imuraya |
| SomiSomi |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Osaka-based griddle manufacturers and heritage wagashi houses lock in equipment supply access while anchoring price visibility for traditional format producers. These contracts insulate domestic incumbents from spot-market volatility in specialized molded griddle procurement, though fusion-format entrants face exposure to cereal-crust and croissant-hybrid ingredient spot markets.
Pricing Analysis
Volume-discount tiering structures separate heritage wagashi houses placing annual griddle orders from dessert shop chains purchasing single units. Three-tier pricing structure across premium, standard, and economy levels reflects Uji matcha certification grade and equipment customization depth. Pricing pressure stems from Korean-American chains compressing innovation cycles to monthly rotations. Students near university districts exhibit highest price sensitivity, while tourists in Asakusa accept heritage premiums.
Supply Chain Analysis
Osaka-Nagoya griddle manufacturing clusters concentrate specialized molded griddle production, creating single-source vulnerability for North American dessert shop expansions. Batter formulation draws from Hokkaido wheat flour, Kyoto matcha powder, and domestic egg supply cooperatives. Tariff exposure on equipment exports to the United States threatens margin structures for cross-border format licensing. Distribution runs through Imuraya's refrigerated logistics network into convenience store freezer cases nationwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiyaki ice cream sits in early-cycle expansion as social media virality accelerates format trial among young adults previously unexposed to wagashi heritage. Penetration depth remains shallow outside Tokyo-Osaka corridors and West Coast Korean-American enclaves.
For Market Incumbents: Consolidate griddle manufacturing relationships through captive capacity reservations in Osaka and Nagoya to defend against lead time erosion. Deepen backward integration into matcha powder sourcing from Kyoto prefecture cooperatives, insulating provenance claims from commodity substitution threats. Lock in dessert shop real estate along Harajuku-Dotonbori heritage corridors before fusion chains capture Instagram-wall-optimized locations. For New Entrants and Emerging Players: Anchor in festival and event food truck channels across secondary Japanese cities lacking dedicated dessert infrastructure, exploiting lower fixed-cost structures against lease-committed incumbents. Target vegan formulation white space as Japan's dairy-alternative regulations mature, capturing allergen-conscious segments underserved by heritage houses. Pursue equipment export partnerships with Korean-American mall operators seeking authentic griddle systems. For Investors and Strategic Acquirers: Heritage-authenticity defenders with century-old Tokyo provenance and controlled retail freezer distribution represent the most defensible acquisition archetype. Long-term viability hinges on whether social media velocity sustains format relevance or collapses into substitution by mochi ice cream and frozen yogurt alternatives. Watch monthly limited-edition rotation frequency as the inflection signal—compression below three-week cycles indicates unsustainable innovation burn.| Strategic Initiative | Industry Significance |
|---|---|
| Griddle Equipment Export Partnership | Captures North American mall demand demonstrated by SomiSomi's West Coast expansion. |
| Vegan Soft-Serve Core Development | Aligns with Japan's evolving dairy-alternative regulations and allergen-conscious segments. |
| Festival Food Truck Network Buildout | Penetrates secondary cities lacking dedicated dessert shop infrastructure at lower fixed cost. |
| Monthly Limited-Edition Rotation System | Sustains repeat visitation through scarcity marketing and Instagram shareability. |
| Kyoto Matcha Direct Sourcing Agreement | Authenticates provenance claims for premium positioning in heritage tourism corridors. |
Research Methodology
Cross-validation between regulatory filings and equipment manufacturer order books anchors the qualitative findings on griddle supply concentration. Primary interviews with dessert shop operators, wagashi house production managers, and frozen confection distribution specialists combined with secondary validation from Japan's Ministry of Health, Labour and Welfare additive standards, FDA dairy documentation requirements, and customs trade data on griddle exports. Bottom-up channel capacity estimates and top-down retail freezer placement audits triangulate market sizing.
Sensitivity analysis across matcha grade tier, format type, and sales channel dimensionality tests forecast robustness over the projection horizon. CAGRs derive from segment-level adoption curves weighted by social media engagement velocity and tourism foot traffic indices. Industry-specific inputs include monthly limited-edition rotation frequency and equipment lead time variability from Osaka-Nagoya manufacturing clusters.
Decision-makers should treat outputs as directional under sustained TikTok-Instagram virality and stable dairy input costs; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as substitution threats from mochi ice cream and frozen yogurt evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Frozen Food Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Cold Cuts Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
US Frozen Dessert Market