
 Mexico Laundry Appliances Market | 2026-2036
Mexico Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Laundry Appliances Market Foresight
Multi-family residential operators is expanding their share of commercial laundry procurement as Mexico's rental housing stock professionalizes. Mabe leverages its domestic manufacturing footprint to anchor supply contracts with large property managers across Mexico City and Guadalajara. Whirlpool Corporation sustains brand recognition through retail channel control in suburban markets. LG Electronics competes on inverter motor technology leadership in the premium front-load segment.
Mexico laundry appliances encompass electrically powered machines designed for fabric cleaning and drying, typically featuring stainless steel drums, variable-speed direct-drive motors, and water consumption ratings below 45 liters per cycle for efficient residential use. These units serve households, commercial laundromats, and institutional facilities requiring hygienic textile processing at scale. Washing machines dominate unit volume as replacement cycles shorten in coastal humidity zones, while smart appliances capture margin pools through Wi-Fi-enabled diagnostics and utility-integrated load scheduling. Front-load configurations are gaining share in urban households where water tariffs from CONAGUA-regulated utilities incentivize conservation.
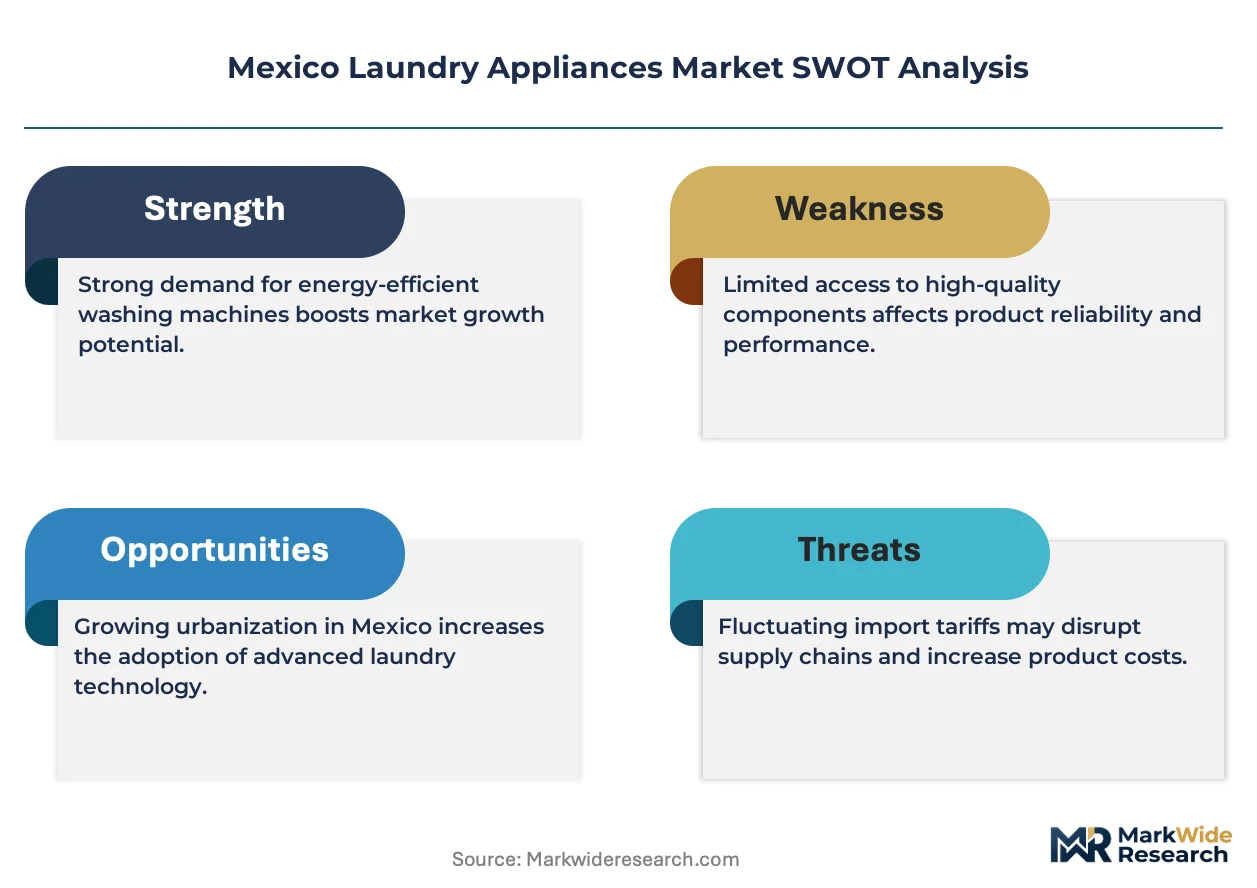
CONAGUA water-use regulations and NOM energy-efficiency standards shape product certification requirements, forcing design changes to drum geometry and heating element efficiency. PROFECO consumer protection rules mandate repair parts availability, influencing warranty structures and aftermarket service networks. Stakeholders must monitor whether forthcoming efficiency tier adjustments will disqualify current top-load mechanical-control models from government subsidy programs.
Market Dynamics
NOM energy-efficiency standards are compressing mechanical-control top-load models while accelerating inverter motor adoption across Mexico's manufacturing corridor. Rental housing professionalization in Guadalajara and Monterrey is restructuring procurement toward commercial-grade fleet contracts.
Growth Catalysts
- CONAGUA water tariffs:Utilities in Mexico City and Guadalajara impose tiered consumption penalties. Front-load washers with sub-45 liter cycles capture preference in these regulated zones.
- Apartment construction acceleration:Multi-family developments in Tijuana and Querétaro generate fleet procurement from professional property managers seeking standardized equipment.
- Inverter motor technology:Variable-speed direct-drive systems reduce energy draw during spin cycles. This hardware shift aligns with forthcoming NOM efficiency tier upgrades.
Market Restraints
- Copper and steel input volatility:Drum and chassis manufacturing faces raw material price swings from concentrated Latin American mining supply.
- PROFECO parts-availability mandates:Warranty structures must guarantee 10-year component access. This inflates inventory carrying costs for distributors.
- Mechanical control obsolescence:Legacy top-load platforms risk disqualification from government subsidy programs under pending NOM revisions.
Strategic Opportunities
- Smart appliance integration:Wi-Fi-enabled diagnostics and CONAGUA-integrated load scheduling open premium margin pools in Mexico City high-rises.
- Coastal humidity zones:Shortened replacement cycles in Veracruz and Cancún create recurring demand for corrosion-resistant drum systems.
- Export channel expansion:Assembly plants near San Luis Potosí serve US and Central American retail with NAFTA-advantaged logistics positioning.
Industry Challenges
- Inverter motor technician scarcity:Service networks lack certified repair capacity for variable-speed drive systems outside major metros.
- NOM certification timeline compression:Manufacturers face 18-month approval windows for efficiency tier upgrades while maintaining legacy production.
- Commercial fleet integration complexity:Property managers demand centralized monitoring platforms that interface with existing building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Laundry Appliances Market |
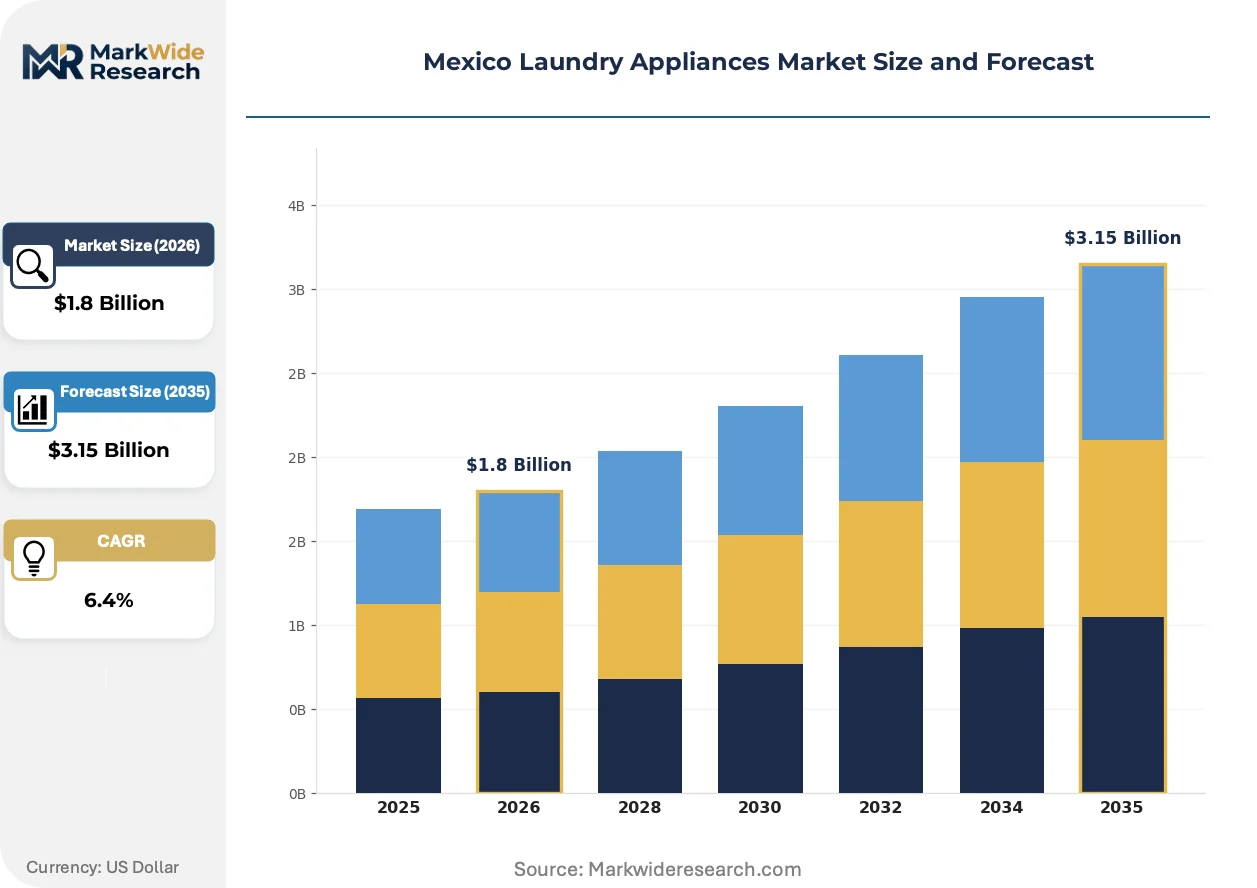
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Combo Units, Washers Technology: Smart Appliances, Eco-Friendly, Top Load, Front Load End User: Residential, Commercial, Institutional, Hospitality Distribution Channel: Online Sales, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Mabe, Whirlpool Corporation, LG Electronics, Samsung Electronics, Electrolux AB, BSH Hausgeräte, Panasonic Corporation, Maytag, Koblenz Eléctrica, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Laundry Appliances Market Shifts & Advancements
Technology convergence between sensor arrays and utility-integrated load management is redefining equipment value propositions. Regulatory pressure on water consumption is accelerating hardware redesign cycles.
Inverter-driven drum systems are integrating variable-speed motors with real-time load sensors to optimize water and energy draw per cycle. Multi-family operators in Monterrey and Guadalajara are specifying these configurations in new-build procurement. This hardware shift is compressing margins for mechanical-control suppliers while opening service revenue streams through predictive maintenance algorithms.
NOM energy-efficiency standards are tightening motor performance thresholds and water-consumption caps for residential certification. Manufacturers must redesign drum geometry and heating element specifications to maintain subsidy eligibility. Front-load configurations in urban households face the steepest compliance burden as CONAGUA-regulated utilities enforce conservation tariffs.
Rental housing operators are consolidating procurement through centralized fleet contracts rather than unit-by-unit retail purchases. Large property managers in Mexico City now negotiate direct supply agreements with manufacturers for standardized equipment rolls. This channel compression is most visible in the Bajío region where professionalized multi-family stock is expanding fastest.
Mexico Laundry Appliances Market Segmentation
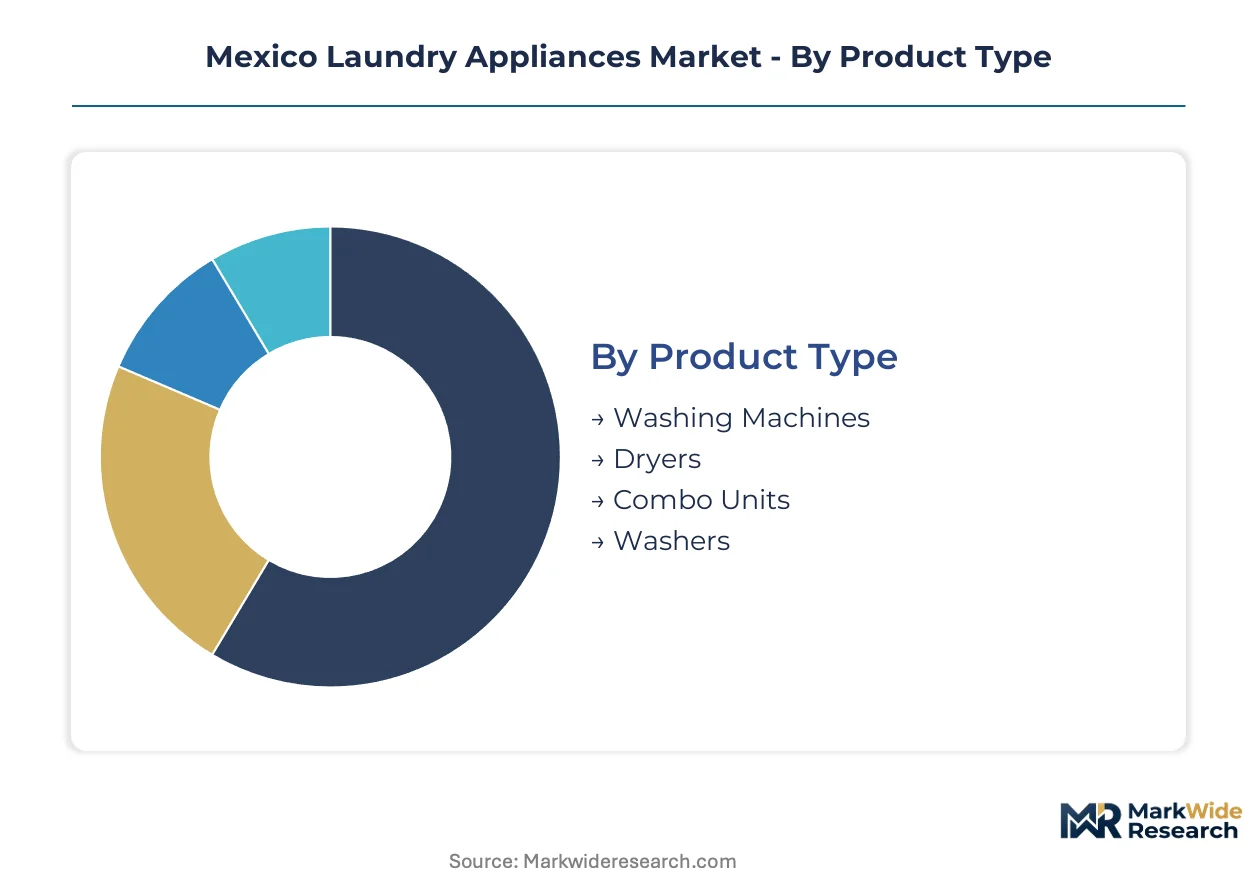
Segmentation in Mexico's laundry appliances market reveals how NOM energy-efficiency standards and CONAGUA water tariffs are reshaping procurement patterns across product configurations and buyer types. Manufacturers must align their portfolios with these regulatory divides to maintain subsidy eligibility and distribution access.
Product Type:
Supply concentration in Mexico's manufacturing corridor clusters assembly capacity around Querétaro and San Luis Potosí, with component sourcing dictating which product lines achieve cost-competitive scale.
- Washing Machines:Electrically powered units featuring stainless steel drums and variable-speed direct-drive motors dominate unit volume. Demand concentrates in central Mexico's manufacturing corridor where apartment construction accelerates and replacement cycles shorten in coastal humidity zones.
- Dryers:Ventless heat-pump and conventional gas-heated configurations serve households with space constraints. Procurement from multi-family operators in Guadalajara and Monterrey favors commercial-grade fleet contracts with standardized venting specifications.
- Combo Units:All-in-one washer-dryer systems address urban space limitations.
- Washers:Semi-automatic and manual alternatives serve price-sensitive rural segments.
Today's leader: Washing Machines. Tomorrow's challenger: Combo Units.
Technology:
Cost tier stratification separates premium inverter-driven systems from legacy mechanical platforms facing NOM certification pressure.
- Smart Appliances:Wi-Fi-enabled units with CONAGUA-integrated load scheduling and predictive diagnostics capture premium margins. Mexico City high-rises drive adoption as property managers seek centralized monitoring platforms.
- Eco-Friendly:Water consumption ratings below 45 liters per cycle and energy-efficient heating elements align with forthcoming NOM efficiency tier upgrades. Front-load configurations in regulated utility zones face the steepest compliance burden.
- Top Load:Mechanical-control platforms risk disqualification from government subsidy programs.
- Front Load:Inverter motor adoption accelerates as drum geometry redesigns meet tightening standards.
Smart Appliances command the premium tier. Eco-Friendly configurations are climbing the fastest as regulatory deadlines approach.
End User:
Volume concentration tilts toward residential replacement demand, though commercial procurement is professionalizing fastest.
- Residential:Individual household purchases dominate absolute unit sales, with coastal humidity zones in Veracruz and Cancún generating recurring demand for corrosion-resistant drum systems.
- Commercial:Laundromat operators and multi-family property managers consolidate procurement through fleet contracts. Tijuana and Querétaro developments generate standardized equipment rolls from professional managers.
- Institutional:Healthcare and educational facilities require hygienic textile processing at scale.
- Hospitality:Hotel chains in tourist corridors specify commercial-grade durability.
Residential holds the volume base. Commercial is expanding most quickly as rental housing stock professionalizes.
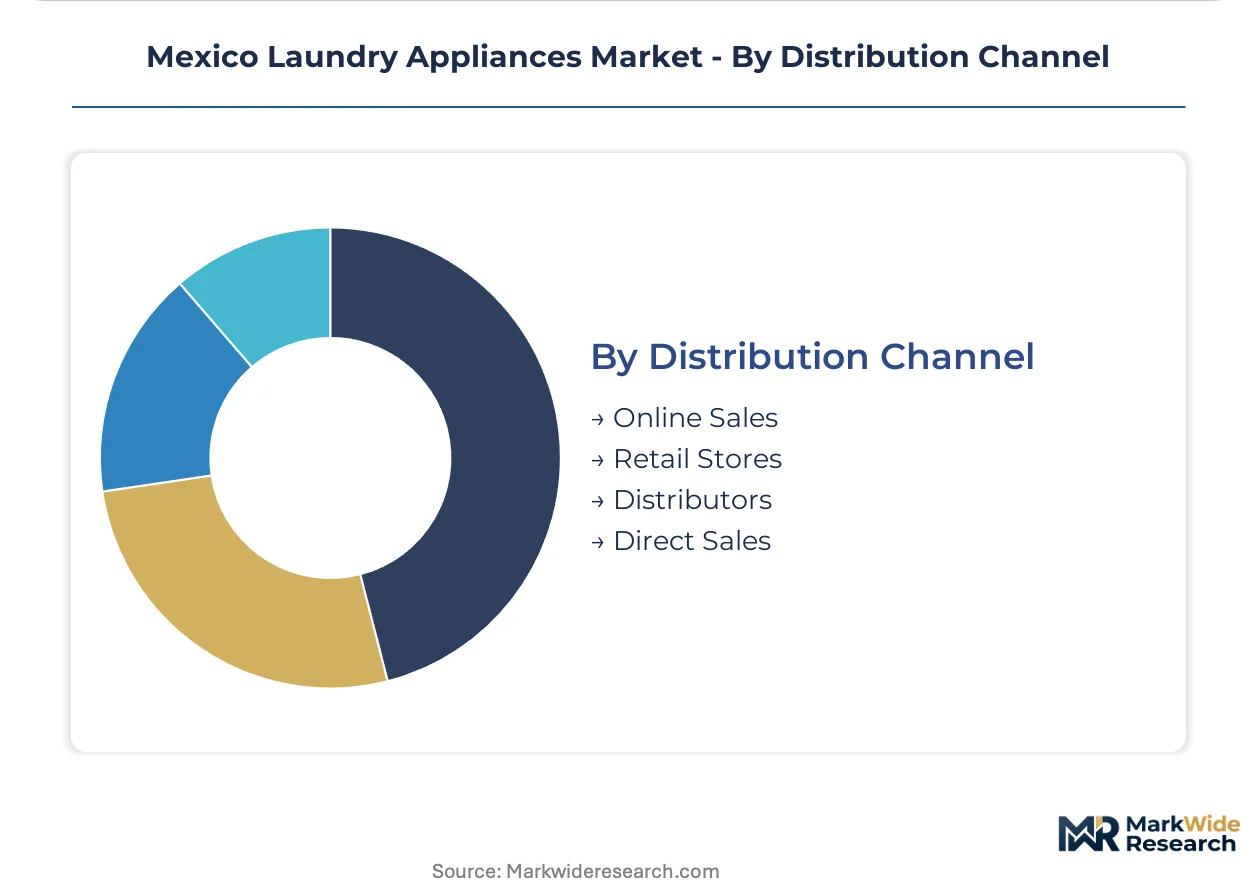
Distribution Channel:
Customer type fragmentation separates retail-dependent households from fleet-contracting institutional buyers.
- Online Sales:E-commerce platforms capture growing share of replacement purchases in Mexico City and Guadalajara metro areas, with Wi-Fi-enabled smart appliances particularly suited to digital-native research behavior.
- Retail Stores:Suburban markets sustain brand recognition through controlled channel presence, with suburban households relying on in-person comparison for mechanical-control models.
- Distributors:PROFECO parts-availability mandates inflate inventory carrying costs for warranty service networks.
- Direct Sales:Manufacturers negotiate supply agreements with large property managers bypassing traditional retail.
Retail Stores anchor current volume. Direct Sales is gaining share fastest as commercial procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are concentrating assembly capacity in central Mexico's manufacturing corridor, where NOM compliance costs and CONAGUA water tariffs create compliance-cost gaps against coastal zones. Production migrates toward Querétaro and San Luis Potosí to exploit proximity to both domestic retail channels and NAFTA-advantaged export logistics.
Mexico City Metro
CONAGUA-regulated utilities impose tiered water consumption penalties that favor front-load washers with sub-45 liter cycles. PROFECO parts-availability mandates inflate inventory carrying costs for distributors serving warranty networks. The metropolitan area anchors demand for smart appliances with Wi-Fi-enabled diagnostics as property managers seek centralized monitoring platforms.
Nuevo León
Monterrey's accelerating apartment construction generates fleet procurement from professionalized multi-family operators consolidating toward standardized equipment rolls. NOM energy-efficiency standards compress margins for mechanical-control suppliers while accelerating inverter motor adoption. The state's manufacturing base supports component sourcing for drum and chassis assembly.
Jalisco
Guadalajara's rental housing stock professionalization restructures procurement toward commercial-grade fleet contracts rather than unit-by-unit retail purchases. CONAGUA water tariffs incentivize conservation-rated appliances in regulated utility zones. The city's logistics positioning connects Bajío region production to Pacific coast distribution channels.
Bajío Region
Querétaro and San Luis Potosí cluster appliance assembly plants serving both domestic retail and export channels to the United States and Central America. NOM certification timelines compress manufacturer approval windows to 18 months while legacy production must continue. The corridor's NAFTA-advantaged positioning attracts capacity expansion from multinational fabricators.
Northern Border States
Tijuana's multi-family developments generate standardized equipment procurement from professional property managers seeking durability in high-turnover rental units. Copper and steel input volatility from concentrated Latin American mining supply affects drum manufacturing costs. The region's maquiladora infrastructure supports component integration for cross-border assembly operations.
Mexico Laundry Appliances Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers reposition assembly lines to exploit NOM compliance-cost differentials across Mexico's manufacturing corridor. The vendor base stratifies between multinational OEMs with captive distribution and domestic fabricators serving price-sensitive segments. Three archetypes occupy distinct positions: integrated manufacturers with in-house component production, brand licensors relying on contract assembly, and regional specialists targeting commercial fleet contracts. M&A activity concentrates among distributors seeking backward integration into service networks, while technology licensing agreements proliferate around inverter motor platforms.
Among multinational OEMs, Mabe, Whirlpool Corporation, and LG Electronics occupy anchor positions representing distinct strategic archetypes. Mabe exemplifies the domestically-rooted integrated manufacturer leveraging proximity to central Mexico's assembly corridor. Whirlpool Corporation sits within the brand-licensor tier with established retail channel control in suburban markets. LG Electronics represents the technology-driven premium specialist competing on inverter motor leadership in front-load configurations. These three entities illustrate how competitive positioning fragments across manufacturing integration depth, distribution architecture, and technology tier rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Mabe |
| Whirlpool Corporation |
| LG Electronics |
| Samsung Electronics |
| Electrolux AB |
| BSH Hausgeräte |
| Panasonic Corporation |
| Maytag |
| Koblenz Eléctrica |
| Others |
Supply & Pricing Matrix
Multi-family property managers consolidating fleet procurement in Guadalajara and Monterrey negotiate volume-based contract pricing that compresses distributor margins while securing standardized equipment rolls. This buyer concentration shifts pricing power toward manufacturers with captive assembly capacity in central Mexico's manufacturing corridor.
Pricing Analysis
Retailer markups on mechanical-control top-load models face compression as NOM efficiency tier upgrades threaten subsidy eligibility. Three-tier pricing structure across premium inverter-driven, standard front-load, and economy semi-automatic levels separates Wi-Fi-enabled smart appliances from basic configurations. Pricing pressure stems from copper and steel input volatility affecting drum manufacturing costs. Price-sensitive rural households in southern states resist premium tier migration while Mexico City high-rise operators absorb smart appliance premiums for centralized monitoring capabilities.
Supply Chain Analysis
Technician scarcity for inverter motor repair constrains capacity expansion in Querétaro and San Luis Potosí assembly zones. Component sourcing draws from China for control boards, Brazil for steel chassis, and domestic suppliers for drum stampings. Single-source vulnerability in variable-speed drive controller chips creates procurement risk for manufacturers retooling product lines. Distribution runs through manufacturer-direct fleet contracts for commercial buyers and retail storefront networks for replacement demand in suburban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's laundry appliance market represents a late-cycle quality pivot as CONAGUA water tariffs and NOM efficiency standards force specification upgrades toward inverter-driven front-load configurations. Demand is concentrating among professionalized rental housing operators willing to pay premium pricing for fleet-standardized, connected equipment.
For Market Incumbents: Deploy backward integration into inverter motor component production to defend margin position against raw material volatility and service network constraints. Mabe and Whirlpool Corporation should lock multi-year fleet supply agreements with expanding property managers in Tijuana and Querétaro before certification timelines compress further. Capture aftermarket service revenue through predictive maintenance platforms that address technician scarcity. For New Entrants and Emerging Players: Smart appliance integration capabilities offer the most penetrable wedge for challengers lacking legacy manufacturing scale. Target coastal humidity zones in Veracruz and Cancún where shortened replacement cycles create recurring demand for corrosion-resistant drum systems. Pursue white-label partnerships with regional distributors seeking differentiated inventory beyond mechanical-control legacy stock. For Investors and Strategic Acquirers: Distributors seeking backward integration into service networks are the most active acquirer in this space, motivated by PROFECO parts-availability mandates inflating warranty inventory requirements. Acquisition targets should display captive technician training programs and established relationships with CONAGUA-regulated utility zones. Watch NOM certification timeline announcements as inflection indicators for mechanical-control obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Motor Platform Investment | Aligns product portfolios with forthcoming NOM efficiency tier upgrades and subsidy eligibility requirements. |
| Fleet Contract Standardization | Captures volume commitments from professionalized multi-family operators in Guadalajara and Monterrey growth corridors. |
| Smart Appliance Integration | Opens premium margin pools through Wi-Fi-enabled diagnostics and CONAGUA-integrated load scheduling capabilities. |
| Service Network Expansion | Addresses certified technician scarcity for variable-speed drive systems outside Mexico City and Monterrey metros. |
| Export Channel Development | Leverages NAFTA-advantaged logistics positioning from San Luis Potosí assembly plants toward US and Central American retail. |
Research Methodology
Multiple input streams — manufacturer production disclosures, distributor inventory records, and utility tariff filings — were reconciled to construct market estimates. Primary interviews with appliance plant managers, multi-family property procurement directors, and aftermarket service heads were validated against secondary sources including CONAGUA water-use databases, NOM certification registries, and PROFECO consumer complaint filings. Bottom-up unit shipment tracking and top-down retail audit data were triangulated to anchor volume projections.
Data-stream reconciliation across product configuration, technology tier, end-user category, and distribution channel dimensions supported analytical framework development over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating NOM regulatory phase-in schedules, apartment construction permits in target metros, and replacement cycle compression in coastal zones. Forecast inputs included inverter motor adoption curves and fleet procurement consolidation rates among professionalized rental operators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NOM certification timeline delays, copper price volatility, and CONAGUA tariff enforcement consistency. Forecasts reflect documented assumptions regarding regulatory implementation pace and manufacturing capacity migration patterns. Material deviation in NOM efficiency tier announcement timing or abrupt CONAGUA tariff restructuring warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
US Portable Washing Machines Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
North America Personal Care Appliances Market
Appliances
Saudi Arabia Microwave Ovens Market
Appliances
Body Dryer Market
Appliances
Bathroom Heaters Market
Appliances
Laundry Dryer Market
Appliances
Bhutan and Nepal White Goods Market
Appliances
GCC Microwave Oven Market
Appliances
Europe Induction Hobs Market
Appliances
Portable Mini Fridge Market
Appliances
GCC Dishwashers Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
Electric Ranges Market
Appliances
China Washing Machine Market
Appliances
Large Cooking Appliance Market