
 United States Washing Machine Market | 2026-2036
United States Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
United States Washing Machine Market Analytics
Direct-to-consumer platforms and builder-direct procurement is rewriting how washing machines reach end users in the United States. Whirlpool Corporation leverages its captive distribution network to sustain pricing power across the replacement cycle. Speed Queen anchors the commercial laundry segment with specialized durability engineering for laundromat operators.
The United States washing machine comprises an electrically powered appliance engineered to clean textiles through automated agitation, spin cycles, and programmable water-temperature control, typically operating at 120V/60Hz with drum capacities ranging from compact units below 2.5 cubic feet to extra-large residential models exceeding 5.0 cubic feet. Its primary commercial purpose spans household garment sanitation, commercial linen processing, and industrial textile maintenance across institutional and hospitality settings. Front-loading configurations command premium positioning due to superior water efficiency and stackability in dense housing, while smart appliances represent the fastest-expanding technology segment as Wi-Fi connectivity and load-sensing algorithms reshape consumer expectations. The residential end-user category remains the mature volume base, though commercial applications generate disproportionate margin pools through service contracts and fleet replacement cycles.
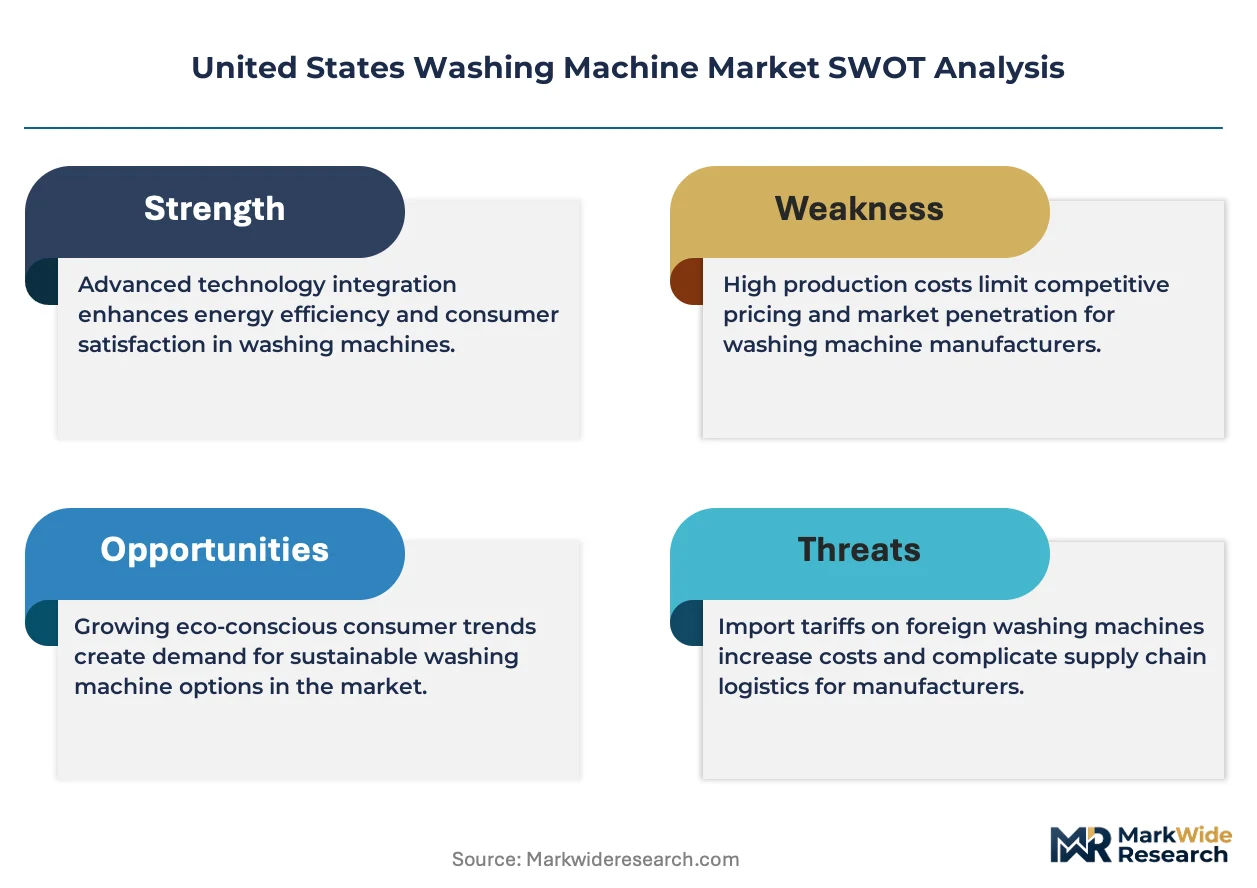
DOE appliance efficiency mandates, EPA WaterSense guidelines, and ENERGY STAR certification thresholds collectively shape product design requirements and market access conditions for manufacturers selling into the United States. These frameworks elevate minimum efficiency standards, compress allowable water consumption per cycle, and restrict entry for non-compliant imports. Stakeholders must monitor pending rulemakings on connected appliance cybersecurity standards and refrigerant transitions in adjacent equipment categories that could signal broader regulatory expansion.
Market Dynamics
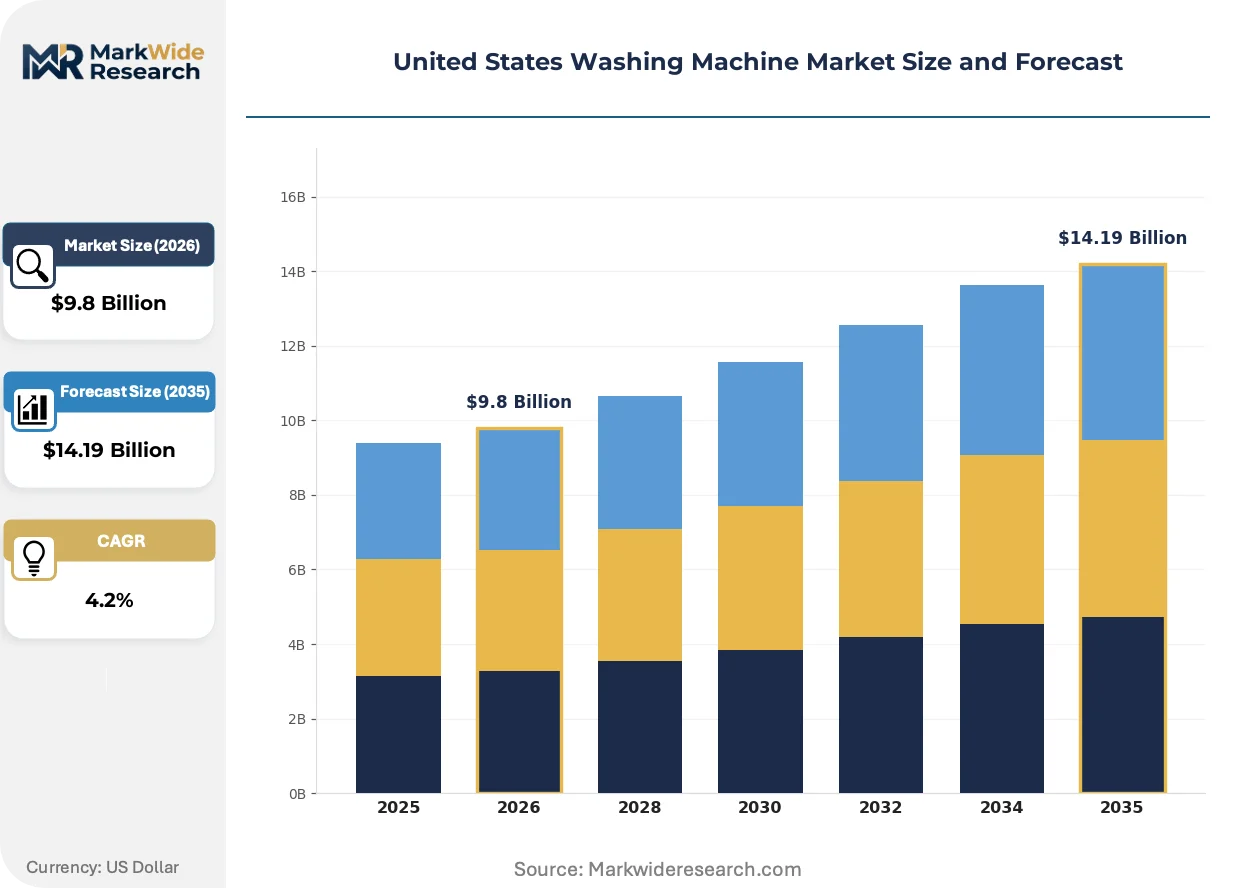
DOE energy conservation standards and ENERGY STAR certification thresholds are compressing allowable water consumption and energy use per cycle, forcing manufacturers to redesign drum systems and motor architectures while multi-family housing developers accelerate procurement timelines to meet rental modernization deadlines.
Growth Catalysts
- Multi-family housing modernization:Rental stock upgrades across Sun Belt states are accelerating replacement cycles for compact, stackable front-loading units in apartment and condominium developments.
- ENERGY STAR certification thresholds:Tightening federal efficiency benchmarks are pulling forward consumer upgrade decisions as older machines lose rebate eligibility and face higher operating cost penalties.
- Smart connectivity integration:Wi-Fi-enabled load-sensing algorithms and remote cycle management are creating replacement pull among tech-adopting households seeking utility integration.
Market Restraints
- Steel and copper input volatility:Drum assemblies and motor windings face cost pressure from commodity price swings that compress margin predictability for domestic assembly operations.
- Import compliance friction:Non-compliant overseas manufacturers face exclusion from federal procurement channels and state-level rebate programs under DOE enforcement expansion.
- Technical limitation in water heating:Heat pump wash systems remain capacity-constrained for extra-large residential loads above 5.0 cubic feet, limiting premium positioning in the high-end segment.
Strategic Opportunities
- Underpenetrated commercial service contracts:Laundromat and hospitality fleet operators present recurring revenue pools through predictive maintenance and usage-based replacement scheduling.
- Regulatory tailwind from EPA WaterSense:Voluntary certification programs are creating brand differentiation channels for manufacturers achieving sub-10 gallon per cycle performance.
- Distribution channel innovation:Builder-direct procurement platforms are collapsing traditional retail markups for new construction volume, enabling margin recapture through specification lock-in.
Industry Challenges
- Connected appliance cybersecurity compliance:Pending FCC rulemakings on IoT device security standards are forcing firmware architecture redesigns and certification timeline extensions.
- Legacy electrical infrastructure integration:Smart grid synchronization and demand-response compatibility require utility partnership negotiations that fragment rollout timelines across regional power authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Washing Machine Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front-Loading, Top-Loading, Washer-Dryer Combo, Portable Technology: Smart Appliances, Energy-Efficient, High-Efficiency, Standard End User: Residential, Commercial, Industrial, Multi-Family Units Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Whirlpool Corporation, Speed Queen, LG Electronics, Hotpoint, Haier, Samsung Electronics, Maytag, Insignia, GE Appliances, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Washing Machine Market Evolving Landscape
Load-sensing algorithms and connected appliance architectures are collapsing traditional water and energy consumption baselines while reshaping how manufacturers capture value through software-enabled service relationships rather than hardware margins alone.
Heat pump wash technology is collapsing thermal energy requirements for water heating by extracting ambient heat rather than resistive element consumption. Multi-family housing developers and premium residential buyers are specifying these systems for LEED certification compliance and utility incentive capture. The technology is collapsing operating cost differentials between front-load and legacy top-load configurations, accelerating segment convergence.
DOE appliance efficiency mandates and pending ENERGY STAR 8.0 thresholds are mandating 20% water reduction from current baselines by tightening test procedure standards. Manufacturers are responding with recirculating spray systems and low-profile drum geometries that maintain cleaning performance at reduced fill volumes. The front-loading segment faces the steepest redesign requirements as it carries the highest efficiency expectations and regulatory scrutiny.
Builder-direct procurement and property management platform integration are compressing retail channel relevance for new construction volume. National multifamily developers are consolidating specification authority through centralized procurement offices, bypassing traditional appliance dealer networks. Texas and Florida submarkets exhibit the most pronounced channel shift as rental unit delivery volumes concentrate in institutional ownership structures.
United States Washing Machine Market Segmentation
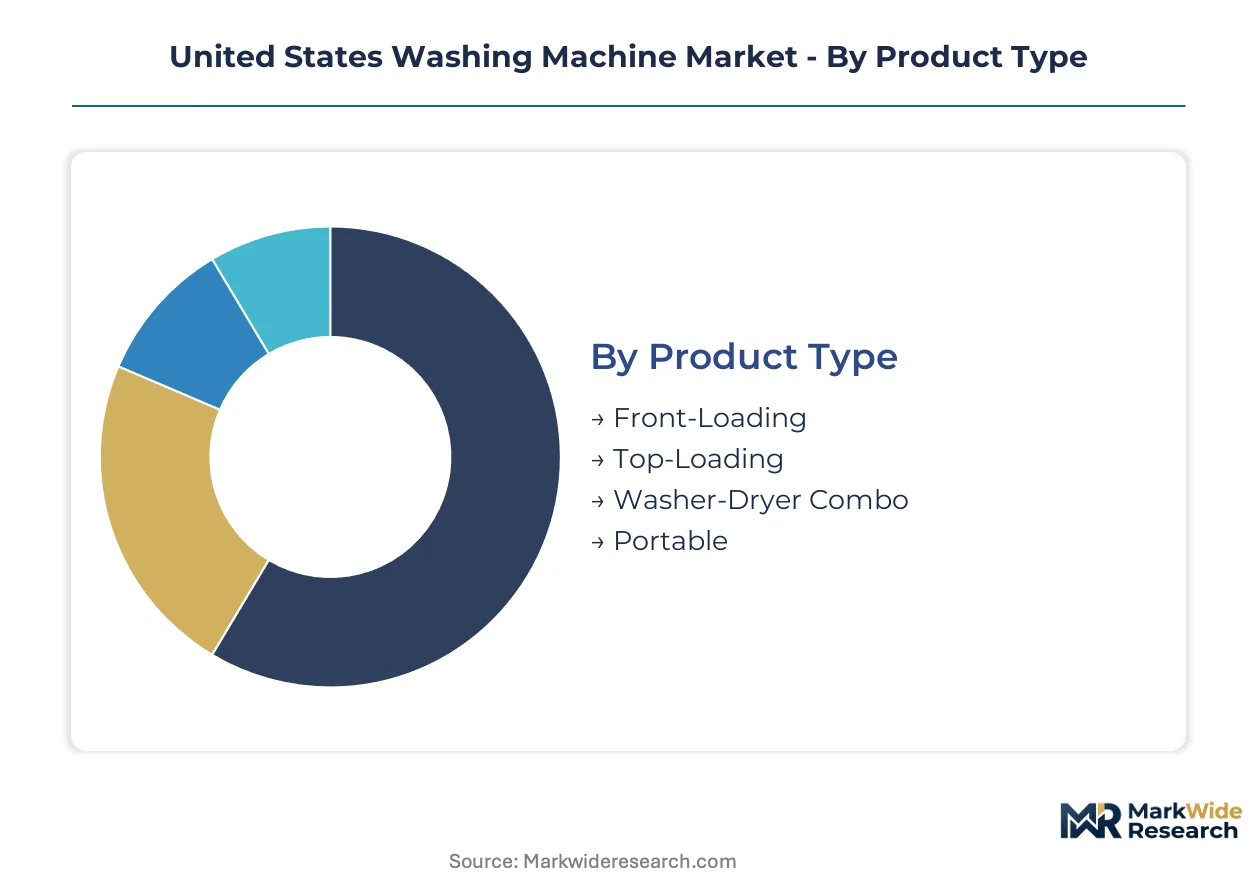
Segmentation in the United States washing machine market reveals how regulatory pressure, housing stock evolution, and channel restructuring fragment demand across distinct technical and commercial configurations. Manufacturers must align product architectures with specific end-use requirements rather than pursuing uniform platform strategies.
Product Type:
Maturity varies sharply across this category, with legacy configurations facing displacement from efficiency-mandated redesigns while emerging formats capture specification authority in new construction.
- Front-Loading:Horizontal-axis drum systems with tumble-action cleaning deliver superior water extraction and stackability for dense housing. Multi-family developers across Texas and Florida submarkets specify these units for LEED compliance and space optimization in institutional rental portfolios.
- Top-Loading:Vertical-axis agitator systems retain consumer familiarity and lower price positioning for replacement cycles in suburban single-family housing. DOE test procedure changes are compressing allowable water consumption for these units, forcing impeller-based redesigns that sacrifice load capacity for efficiency compliance.
- Washer-Dryer Combo:Condensing all-in-one units serve RV, marine, and micro-apartment applications where venting infrastructure is unavailable. Ventless heat pump drying extends cycle duration but enables installation flexibility in legacy electrical infrastructure.
- Portable:Compact units below 2.5 cubic feet with caster mobility and sink-attachment hoses target urban renters without in-unit laundry connections. Sun Belt apartment conversions and accessory dwelling unit construction sustain demand for temporary-installation solutions.
Front-loading retains volume leadership; washer-dryer combo holds the steepest expansion curve.
Technology:
Cost tier stratification dominates this dimension, with premium positioning commanding hardware-software integration while baseline segments absorb regulatory compliance costs without pricing power.
- Smart Appliances:Wi-Fi-enabled platforms with load-sensing algorithms, remote cycle management, and utility demand-response integration reshape consumer expectations for connected home ecosystems. ENERGY STAR 8.0 preparation and FCC cybersecurity rulemakings are accelerating firmware architecture investments among manufacturers targeting tech-adopting households.
- Energy-Efficient:Units meeting current ENERGY STAR thresholds without full smart connectivity capture rebate-dependent consumers in states with utility incentive programs. California and New York regulatory environments sustain demand for these mid-tier efficiency configurations.
- High-Efficiency:Reduced water-fill designs with recirculating spray systems achieve performance parity at lower consumption baselines through mechanical innovation rather than electronic integration. Front-loading architectures dominate this segment.
- Standard:Baseline efficiency units without certification premiums serve price-sensitive replacement demand and secondary residence installations. Import compliance friction under DOE enforcement expansion is narrowing available supply channels.
Energy-efficient configurations retain volume leadership; smart appliances hold the steepest expansion curve.
End User:
Application-driven divergence separates household sanitation requirements from commercial throughput demands, with multi-family housing emerging as a distinct procurement category between these poles.
- Residential:Single-family household installations dominate replacement cycle volume, with purchase decisions driven by failure events rather than upgrade timing. Front-loading preference concentrates in new construction and kitchen renovation contexts.
- Commercial:Laundromat and hospitality fleet operators generate recurring revenue pools through service contracts and predictive maintenance agreements. Speed Queen anchors this segment with specialized durability engineering for high-cycle environments.
- Industrial:Continuous-batch and tunnel washer systems process institutional linen at healthcare and correctional facilities. These applications sit outside standard residential product definitions and procurement channels.
- Multi-Family Units:Centralized laundry rooms and in-unit installations for apartment and condominium developments constitute a distinct specification category with unique space, ventilation, and durability requirements. Builder-direct procurement platforms are collapsing traditional retail relevance for this volume.
Residential retains volume leadership; multi-family units hold the steepest expansion curve.
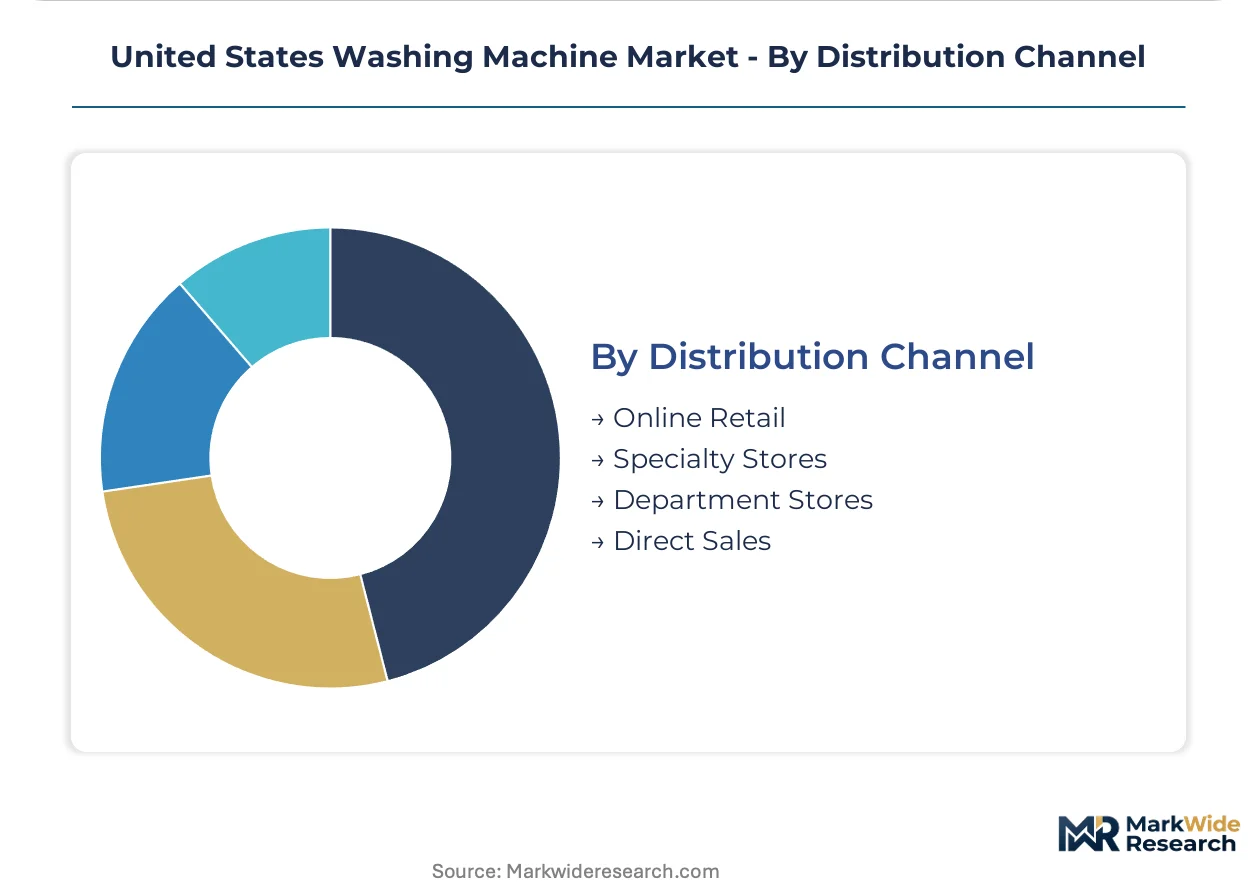
Distribution Channel:
Customer type and purchase context reshape channel relevance, with institutional buyers bypassing retail entirely while household consumers fragment across physical and digital touchpoints.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable specification comparison and delivery scheduling for replacement cycle purchases. Whirlpool Corporation leverages captive distribution networks to sustain pricing power across this channel.
- Specialty Stores:Independent appliance dealers retain influence in kitchen renovation and premium replacement contexts where tactile evaluation and installation coordination matter. These channels face compression from builder-direct procurement growth.
- Department Stores:Big-box retail maintains presence for mid-market segments and promotional event purchasing, though floor space allocation is shifting toward connected appliance displays.
- Direct Sales:Manufacturer-direct and builder-direct procurement platforms collapse retail markups for new construction volume, enabling margin recapture through specification lock-in with national multifamily developers.
Specialty stores retain volume leadership; direct sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida command pricing premiums through builder-direct procurement consolidation, while Midwest replacement markets absorb margin compression from retail channel competition. DOE regional enforcement variance and state-level utility incentive fragmentation create arbitrage opportunities for specification-savvy developers.
Texas
Multi-family housing deliveries in Dallas-Fort Worth and Houston metro areas drive institutional procurement volume for stackable front-loading units. ERCOT grid stability concerns accelerate smart appliance demand-response integration specifications. San Antonio's military housing privatization programs sustain fleet replacement schedules through centralized contracting.
Florida
Miami-Dade and Tampa-St. Petersburg rental modernization absorbs compact washer-dryer combos for aging condominium stock without venting infrastructure. Florida Public Service Commission utility rebate programs favor ENERGY STAR-certified replacements. Orlando's vacation rental management companies drive commercial laundry service contract growth.
California
Title 24 building efficiency mandates and CPUC electrification timelines pull heat pump wash technology into new construction specifications. Los Angeles County rent stabilization ordinances accelerate in-unit appliance upgrades between tenant turnovers. Bay Area ADU construction sustains portable washing machine demand for accessory dwelling plumbing limitations.
New York Metro
Co-op board renovation approvals and Local Law 97 carbon caps reshape replacement timing for aging laundry infrastructure in pre-war housing stock. Consolidated Edison demand-response incentive programs favor Wi-Fi-enabled smart appliance specifications. Brooklyn and Queens multi-family conversions drive centralized laundry room equipment procurement.
Southeast
Atlanta and Charlotte suburban sprawl sustains big-box retail replacement volume for top-loading units in single-family housing. Georgia Power and Duke Energy rebate programs concentrate demand for mid-tier efficiency configurations. South Carolina manufacturing clusters support regional distribution hub positioning for builder-direct fulfillment.
United States Washing Machine Market Competitive Landscape
Full-line appliance conglomerates and specialized commercial laundry engineers split the market into distinct capability zones. Consolidation pressure concentrates around captive distribution networks and specification lock-in with national developers. Strategic archetypes include vertically integrated manufacturers with builder-direct platforms, commercial durability specialists with service contract ecosystems, and electronics conglomerates with smart home ecosystem integration. Dominant competitive moves include backward integration into component supply and strategic partnerships with property management software platforms.
Within the full-line manufacturer tier, Whirlpool Corporation and GE Appliances occupy positions anchored by captive distribution infrastructure and multi-brand portfolio coverage. Speed Queen exemplifies the commercial durability archetype through specialized engineering for high-cycle environments. LG Electronics and Samsung Electronics represent the electronics conglomerate vector with smart home ecosystem integration capabilities. Haier's acquisition-derived portfolio sits within the global appliance platform category with regional manufacturing footprint advantages.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Speed Queen |
| LG Electronics |
| Hotpoint |
| Haier |
| Samsung Electronics |
| Maytag |
| Insignia |
| GE Appliances |
| Others |
Value Network & Pricing Analysis
Ohio manufacturing clusters anchor domestic drum assembly capacity, concentrating motor winding and steel fabrication operations that feed downstream pricing power toward institutional buyers consolidating procurement through builder-direct platforms.
Pricing Analysis
Configured-to-order pricing for ENERGY STAR 8.0-compliant units commands substantial premiums over standard efficiency baselines. Three-tier pricing structure across premium smart-connected, mid-tier certified, and economy non-certified levels stratifies the market. Price differentiation hinges on ENERGY STAR certification tier and after-sales service bundling. Cost compression in economy tiers intensifies due to import compliance friction narrowing supply channels. Single-family replacement buyers exhibit highest price sensitivity; multi-family developers show lowest sensitivity due to specification lock-in incentives.
Supply Chain Analysis
Export-control scrutiny on advanced motor control algorithms and connected appliance firmware limits technology transfer from certain Asian manufacturing jurisdictions. Domestic assembly draws from Chinese steel coil, Mexican copper winding, and South Korean electronic component inputs. Single-source vulnerability concentrates in semiconductor motor controllers sourced from Taiwan and South Korea. Distribution runs through captive manufacturer networks, builder-direct procurement platforms, and consolidated retail channels serving replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through national multi-family developer procurement consolidation, with institutional purchasers bypassing traditional retail channels entirely to capture specification authority and margin recapture.
For Market Incumbents: Entrench builder-direct platform relationships through predictive maintenance service contracts and firmware update ecosystems that lock in multi-family developer specifications. Backward integration into motor controller supply mitigates semiconductor sourcing risk from Taiwan and South Korea. Certification investment in ENERGY STAR 8.0 pre-compliance defends against regulatory displacement of legacy product lines. For New Entrants and Emerging Players: Pursue commercial service contract white space in laundromat fleet management where Speed Queen's dominance leaves predictive maintenance and usage-based replacement scheduling underpenetrated. Target Sun Belt multi-family submarkets through property management software platform integrations that collapse traditional dealer channel relevance. Go-to-market leverage rests on utility demand-response compatibility certifications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors connected appliance firmware specialists with FCC cybersecurity pre-certification and utility integration partnerships. Long-term viability centers on software-enabled service revenue streams decoupled from hardware replacement cycles. Acquisition archetype: smart home ecosystem integrators with existing ENERGY STAR certification pipelines. Signal to monitor: FCC IoT security rulemaking finalization timelines as inflection trigger for compliance-ready asset premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Controllers | Captive supply of semiconductor-dependent components reduces Taiwan and South Korea sourcing vulnerability. |
| Property Management Software Partnership | Platform integration with Yardi and RealPage collapses retail channel relevance for multi-family procurement. |
| ENERGY STAR 8.0 Pre-Certification Investment | Early compliance with DOE water reduction mandates secures rebate eligibility across utility territories. |
| Commercial Service Contract Expansion | Predictive maintenance agreements with laundromat operators generate recurring revenue beyond hardware margins. |
| Utility Demand-Response Integration | ERCOT and California ISO compatibility specifications capture grid-stability incentive programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of DOE appliance efficiency filings, ENERGY STAR certification databases, and utility rebate program disclosures. Interviews with multi-family development procurement directors, appliance dealer network managers, and motor controller sourcing specialists informed demand and supply assumptions. Bottom-up unit shipment estimates triangulated against top-down housing construction and replacement cycle modeling.
Forecast inputs incorporate housing starts by structure type, ENERGY STAR version adoption curves, and utility incentive program budget allocations. Segmentation dimensions span product architecture, technology tier, end-user category, and distribution channel. CAGRs derived from regression analysis against historical efficiency standard implementation patterns and demographic migration flows. Industry-specific inputs include DOE rulemaking comment filings and FCC IoT security proceeding dockets.
Sensitivities concentrate around DOE test procedure finalization timelines, steel and copper commodity volatility, and FCC cybersecurity rulemaking implementation schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Household Beauty Appliances Market
Appliances
Smart Connected Washing Machine Market
Appliances
Residential Space Heater Market
Appliances
Europe Garment Steamers Market
Appliances
Refrigerator Repair Service Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Portable Fridges Market
Appliances
UAE Gas Hobs Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Qatar Dishwashers Market
Appliances
US Washing Machine Parts Market
Appliances
Asia-Pacific Electric Rice Cooker Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Electric Ranges Market
Appliances
Electric Hand Dryer Market
Appliances
Saudi Arabia Gas Hobs Market